
 France Mobile Payment Market | 2026-2036
France Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
France Mobile Payment Market Foresight
Tokenization of card credentials is fragmenting the traditional payment stack into modular, API-first components. BNP Paribas SA leverages its universal banking license to anchor issuer-processing relationships across retail networks. Worldline SA competes on terminal hardware and merchant-acquiring scale, while Lydia Solutions differentiates through instant peer-to-peer transfers aimed at younger account holders.
France mobile payment denotes digital fund transfers initiated through smartphones or wearables using encrypted credential proxies, typically operating over NFC radio frequencies at 13.56 MHz or QR-encoded data packets, with primary purpose of displacing physical card-present and cash transactions at point-of-sale terminals. Near Field Communication occupies the dominant share of in-store volume due to embedded terminal infrastructure across French retail, while QR Code adoption accelerates among small merchants seeking zero-hardware onboarding. Mobile Wallet provision concentrates margin pools with banking institutions and technology vendors that control device-level secure elements and token vaults.
France's mobile payment ecosystem operates under the EU Payment Services Directive, GDPR data governance, and CE marking for terminal hardware, with the Autorité de Contrôle Prudentiel et de Résolution supervising licensing and the Commission Nationale de l'Informatique et des Libertés enforcing consent protocols for biometric authentication. These frameworks elevate compliance costs for fintech entrants but simultaneously reinforce incumbent trust advantages among risk-averse merchant categories. Stakeholders must weigh whether to build proprietary token vaults or rely on bank-issued credential proxies as the regulatory perimeter around open banking data tightens.
Market Dynamics
Tokenization architectures are fragmenting France's payment stack into modular API-first components, forcing incumbents and fintechs to renegotiate control over credential vaults and secure element access.
Growth Catalysts
- EU Payment Services Directive:Open banking mandates force incumbent institutions to expose account data via standardized APIs, lowering barriers for wallet providers to embed payment initiation services.
- Paris-Île-de-France merchant density:Concentrated retail networks in the capital corridor accelerate NFC terminal rollout and create network effects for contactless adoption.
- Biometric authentication:Fingerprint and facial recognition integration into Android and iOS secure elements reduces friction for high-value transactions without compromising PSD2 strong customer authentication requirements.
Market Restraints
- GDPR compliance architecture:Consent management for biometric data collection adds fixed engineering costs that disproportionately burden sub-scale fintech entrants.
- Terminal hardware concentration:CE-marked NFC reader supply chains cluster with Asian contract manufacturers, exposing acquirers to component lead time volatility.
- Interchange fee compression:EU caps on card-present transaction economics squeeze merchant acquirer margins and limit reinvestment in value-added services.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur tourism corridors:Seasonal merchant populations in coastal hospitality markets remain underpenetrated by integrated POS-wallet solutions.
- Transportation open-loop convergence:Navigo card credential migration to smartphone wallets creates unified transit-retail payment experiences across Île-de-France Mobilités networks.
- CNIL biometric consent frameworks:Early compliance with France's data protection authority on facial recognition protocols positions providers for EU-wide scalability.
Industry Challenges
- Legacy core banking integration:Real-time ledger synchronization between neobank front-ends and mainframe-based clearing systems demands specialized middleware talent scarce in the French labor market.
- Certification timeline compression:EMVCo token service provider accreditation and ACPR licensing run sequentially rather than in parallel, extending time-to-market for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Mobile Payment Market |
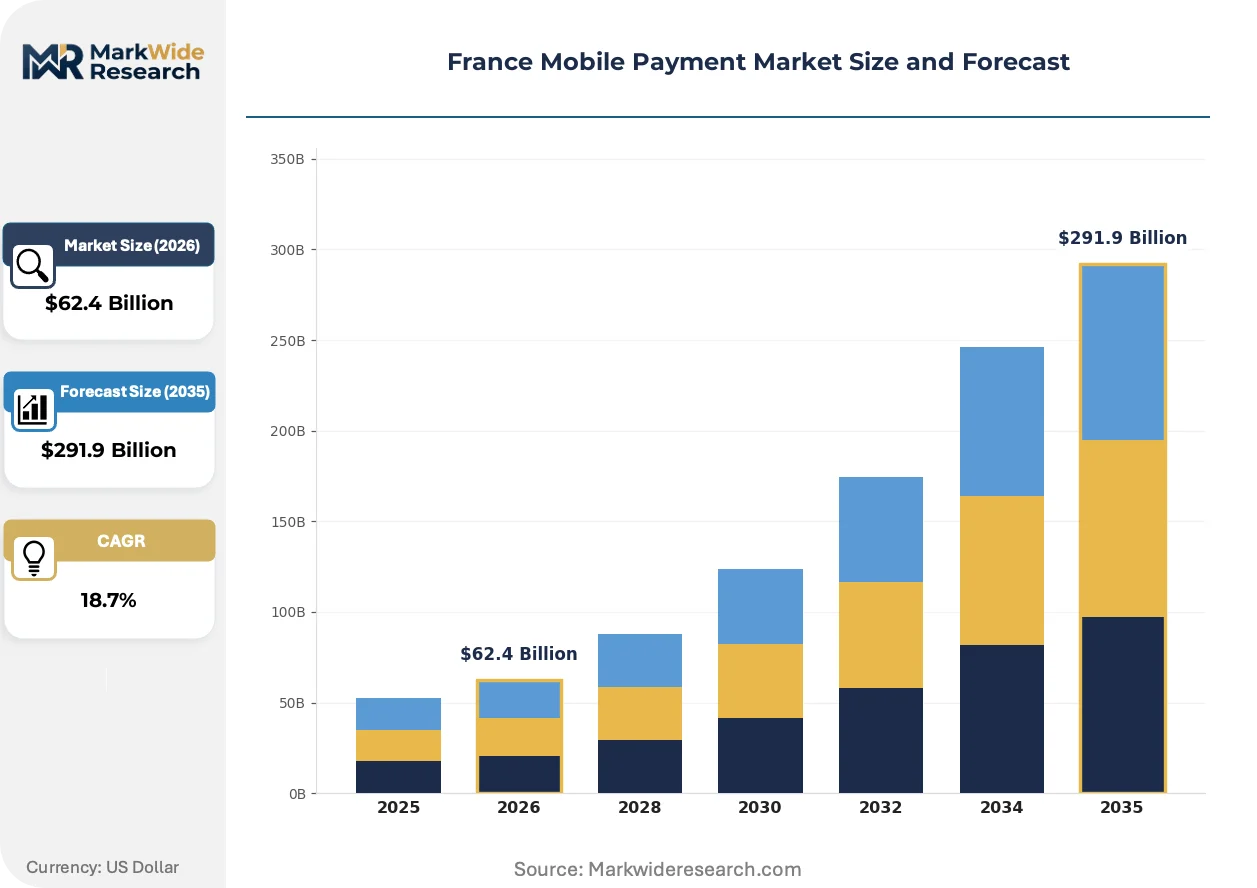
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $291.9 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Near Field Communication, QR Code, Mobile Wallet, Direct Carrier Billing, Tokenization End User: Retail Consumers, Hospitality Customers, Transportation Passengers, Government Service Users, Educational Institutions Service Provider: Banking Institutions, Telecom Operators, Fintech Companies, Payment Gateways, Technology Vendors Deployment Model: Cloud-Based Platforms, On-Premises Systems, Hybrid Infrastructure, API Integrations |
| Companies Covered | BNP Paribas SA, Groupe BPCE, Worldline SA, Paylib Services, Crédit Agricole SA, Ingenico SA, Société Générale SA, Lydia Solutions, Orange SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Mobile Payment Market Shifts & Advancements
Credential storage architectures are migrating from hardware-bound models toward cloud-native vaults, reshaping liability distribution and vendor contracting patterns across the French ecosystem.
Host card emulation is migrating from device-secure-element dependence to cloud-based credential provisioning. Mid-market hospitality operators in Lyon and Bordeaux are adopting this architecture to bypass dedicated terminal hardware investments. The shift is compressing merchant onboarding cycles from weeks to hours while redistributing fraud liability toward token service providers.
GDPR Article 35 data protection impact assessments now govern biometric authentication rollouts at French retail banks. The CNIL mandates explicit consent workflows for facial recognition at point-of-sale, forcing architecture teams to build granular permission layers. Large-format grocery chains are responding by piloting palm-vein alternatives that fall outside biometric classification thresholds.
Merchant acquisition is fragmenting from bundled terminal-plus-processing contracts toward unbundled software-first onboarding. Small independent retailers in Lille and Nantes now select payment apps through marketplace distribution rather than bank relationship managers. This channel rotation favors API-native acquirers with self-service integration kits over branch-network-dependent institutions.
France Mobile Payment Market Segmentation
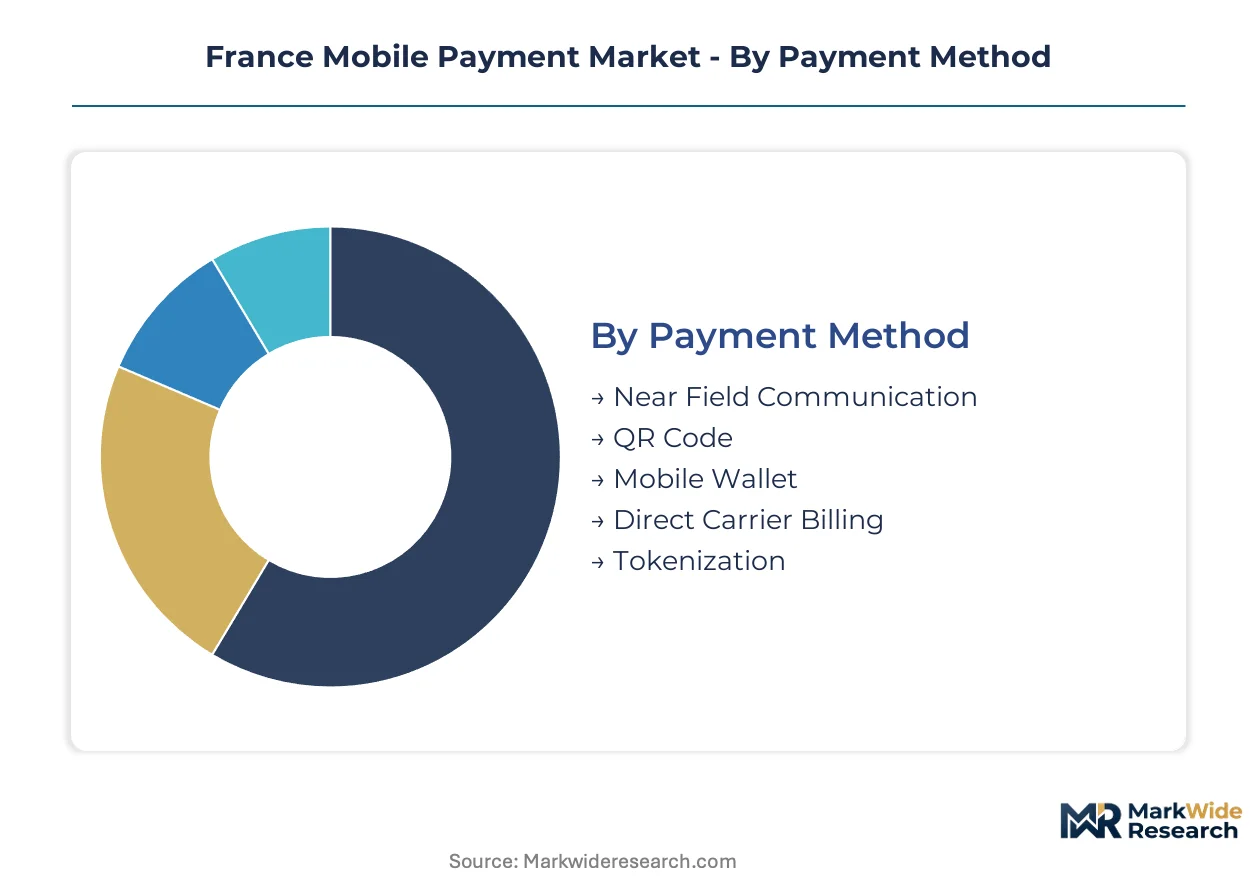
Segmentation reveals where capital allocation and engineering resources concentrate across France's mobile payment infrastructure. Each dimension exposes distinct margin structures, compliance burdens, and partnership requirements that shape vendor strategy.
Payment Method:
Cycle times vary sharply across credential technologies, with terminal-dependent methods requiring longer certification pipelines than software-native alternatives.
- Near Field Communication:Operates at 13.56 MHz radio frequency through embedded secure elements or host card emulation. Paris-Île-de-France retail chains drive volume concentration, though CE-marked terminal supply constraints from Asian manufacturers extend deployment timelines.
- QR Code:Encodes payment credentials as scannable image data for camera-based initiation. Small merchants in Lille and Nantes adopt this for zero-hardware onboarding, bypassing NFC terminal investments entirely.
- Mobile Wallet:Aggregates multiple credential sources within smartphone secure elements.
- Direct Carrier Billing:Charges transactions to mobile subscriber accounts.
- Tokenization:Replaces primary account numbers with cryptographically generated proxies.
NFC anchors the volume base while QR Code gains share at the steepest rate.
End User:
Customer acquisition costs stratify sharply across these segments, with institutional buyers demanding custom integration work that consumer-facing channels avoid.
- Retail Consumers:Individual shoppers using smartphones for everyday purchases.
- Hospitality Customers:Diners and hotel guests initiating tableside or contactless payments. Lyon and Bordeaux hospitality chains pilot cloud-native credential provisioning to reduce terminal hardware footprints.
- Transportation Passengers:Navigo credential holders migrating to smartphone wallets. Île-de-France Mobilités networks create unified transit-retail experiences as open-loop convergence accelerates.
- Government Service Users:Citizens accessing public benefits through mobile channels.
- Educational Institutions:Universities and schools managing campus payment ecosystems.
Retail Consumers generate the transaction volume base while Transportation Passengers show the steepest adoption climb as transit-wallet integration matures.
Service Provider:
Margin capture depends on regulatory license depth, with prudentially supervised entities commanding trust premiums over unregulated intermediaries.
- Banking Institutions:Universal banks leveraging ACPR licenses to anchor issuer-processing relationships. BNP Paribas SA and peers control token vaults and secure element access, extracting rents from fintech partners.
- Telecom Operators:Mobile network providers with subscriber billing relationships.
- Fintech Companies:API-native challengers unbundling merchant acquisition from branch networks. Lydia Solutions targets younger account holders with instant peer-to-peer transfers.
- Payment Gateways:Technical intermediaries routing authorization messages.
- Technology Vendors:Terminal hardware and software platform providers. Worldline SA competes on merchant-acquiring scale and CE-marked device distribution.
Banking Institutions anchor the revenue base while Fintech Companies expand most quickly through unbundled software-first onboarding.
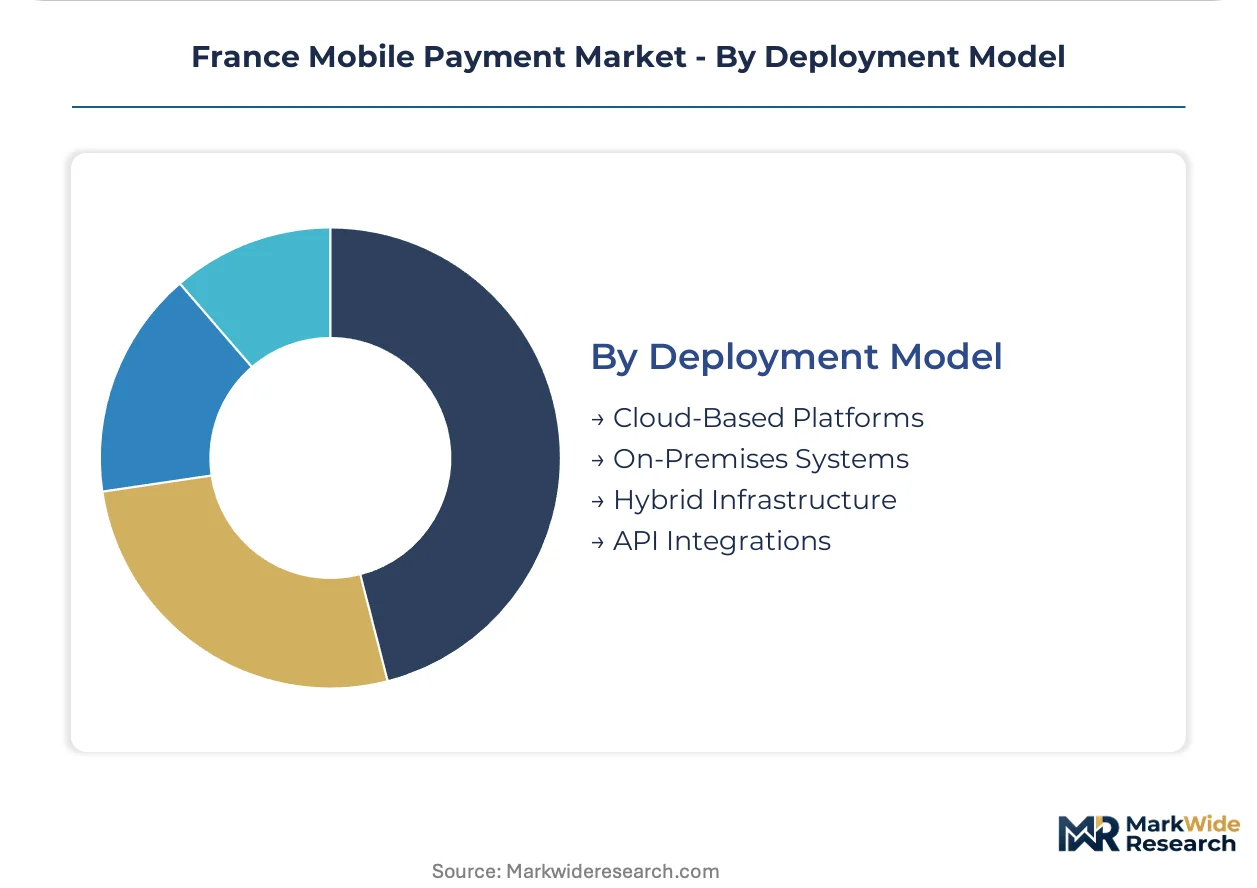
Deployment Model:
Infrastructure ownership models determine compliance liability distribution and capital intensity for market participants.
- Cloud-Based Platforms:Hosted credential vaults and processing engines managed by third-party providers. GDPR Article 35 data protection impact assessments govern biometric authentication rollouts, elevating engineering costs for consent-layer architecture.
- On-Premises Systems:Bank-owned data centers maintaining direct control over ledger synchronization.
- Hybrid Infrastructure:Split architectures with sensitive operations on-premises and scalable layers in cloud.
- API Integrations:Modular connections between wallet front-ends and legacy core banking systems. Real-time ledger synchronization demands middleware talent scarce in the French labor market.
On-Premises Systems anchor the transaction base while Cloud-Based Platforms climb the fastest as host card emulation migrates from hardware-bound models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports mobile payment infrastructure expertise to neighboring EU markets, particularly Belgium and Spain, while importing terminal hardware components from Asian contract manufacturers. The Paris-Île-de-France corridor anchors domestic transaction volume concentration.
Île-de-France
Paris merchant density drives NFC terminal penetration rates above national averages. Autorité de Contrôle Prudentiel et de Résolution licensing requirements concentrate fintech headquarters in La Défense and Station F. The capital corridor generates network effects for contactless adoption across retail and hospitality verticals.
Auvergne-Rhône-Alpes
Lyon hospitality chains pilot cloud-native credential provisioning to reduce hardware footprints. GDPR Article 35 assessments govern biometric authentication rollouts at regional retail banks. Mid-market restaurant operators adopt host card emulation for tableside payment flexibility.
Provence-Alpes-Côte d'Azur
Seasonal tourism merchant populations in Nice and Cannes remain underpenetrated by integrated POS-wallet solutions. CNIL consent protocols for facial recognition delay biometric rollout at coastal retail locations. Hospitality operators seek zero-hardware onboarding for temporary summer staffing.
Hauts-de-France
Lille retail independents select payment apps through marketplace distribution rather than bank relationship managers. CE-marked terminal supply constraints from Asian manufacturers extend deployment timelines in this logistics hub. API-native acquirers capture share through self-service integration kits.
Nouvelle-Aquitaine
Bordeaux wine tourism merchants adopt QR-code solutions for zero-hardware onboarding. Commission Nationale de l'Informatique et des Libertés enforcement elevates compliance engineering costs for biometric consent layers. Regional agricultural cooperatives explore direct carrier billing for B2B procurement.
France Mobile Payment Market Competitive Landscape
On the supply side, the industry is consolidating around universal banking licenses and merchant-acquiring scale, with token vault control emerging as the primary rent-extraction point. Three archetypes dominate: licensed deposit-taking institutions anchoring issuer-processing relationships, terminal hardware specialists competing on CE-marked distribution, and API-native fintechs unbundling merchant acquisition. Competitive moves center on M&A for token service provider accreditation and strategic partnerships for cloud-native credential provisioning.
Among Paris-based banking groups, BNP Paribas SA and Société Générale SA occupy positions within the licensed-institution tier, leveraging ACPR supervision to control secure element access. Worldline SA exemplifies the hardware-scale archetype through terminal distribution and merchant-acquiring infrastructure. Lydia Solutions represents the API-native challenger model targeting younger account holders with instant peer-to-peer functionality.
| Leading Market Players |
|---|
| BNP Paribas SA |
| Groupe BPCE |
| Worldline SA |
| Paylib Services |
| Crédit Agricole SA |
| Ingenico SA |
| Société Générale SA |
| Lydia Solutions |
| Orange SA |
| Others |
Supply & Pricing Matrix
Asian contract manufacturers for CE-marked NFC terminals concentrate upstream supply, anchoring margin pools with French banking institutions that control token vaults and secure element access rather than hardware distributors.
Pricing Analysis
Cloud-native credential provisioning widens pricing gaps against hardware-secure-element architectures. Three-tier pricing structure across premium, standard, and economy levels separates large-format grocery chains from mid-market hospitality operators and small independent retailers. Price differentiation rests on GDPR compliance architecture costs and ACPR licensing depth. Pricing pressure stems from interchange fee compression under EU caps, squeezing merchant acquirer margins. Small retailers in Lille and Nantes exhibit highest price sensitivity, while universal banks command lowest sensitivity through trust premiums.
Supply Chain Analysis
Semiconductor fabrication for secure elements draws from Taiwan, South Korea, and Japan. Terminal assembly hinges on Chinese and Vietnamese contract manufacturers for CE-marked NFC readers. Raw material dependencies span silicon wafers, radio frequency modules, and cryptographic processors. Single-source vulnerability concentrates in Asian component suppliers, exposing acquirers to lead time volatility. Distribution runs through Worldline SA and Ingenico SA hardware networks alongside API-native fintech direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
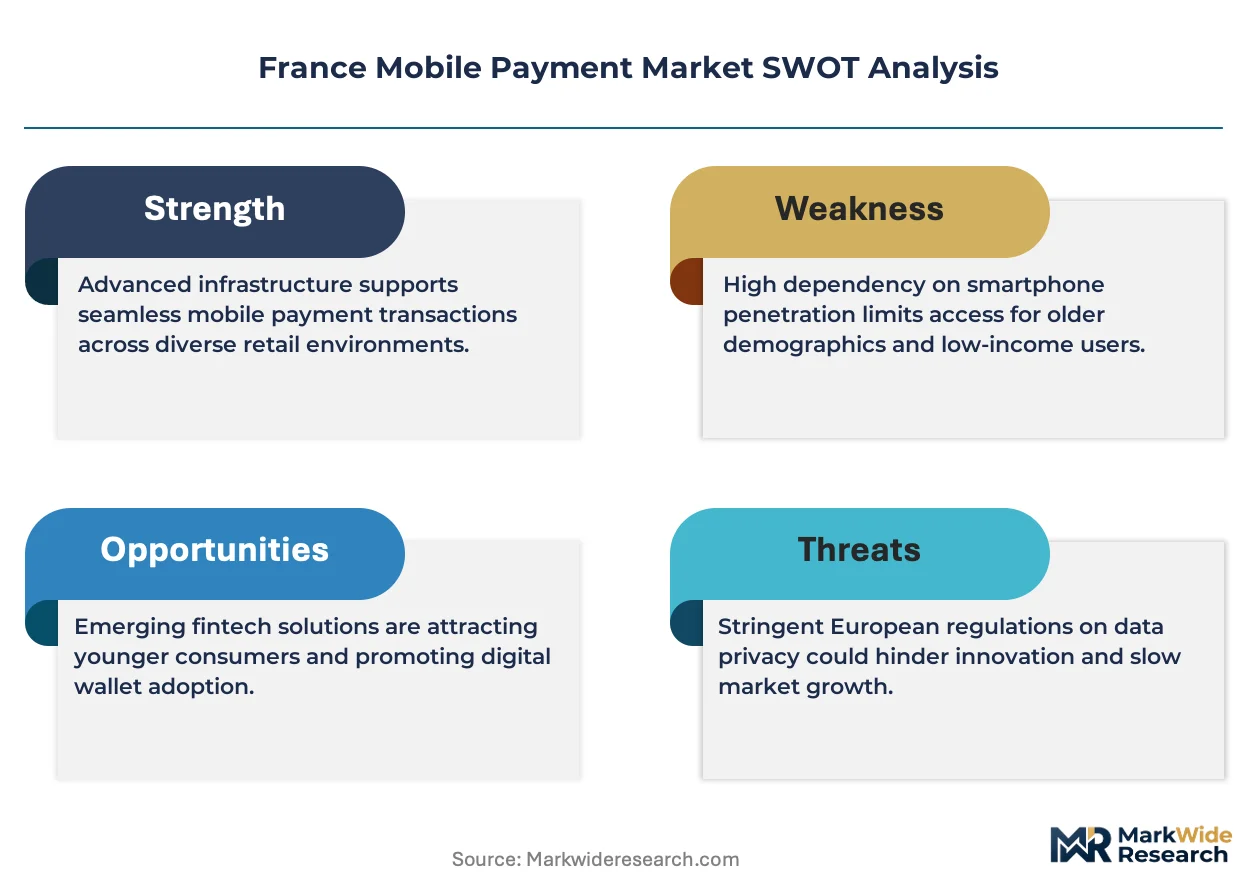
France's mobile payment market fragments around merchant acquisition models, with unbundled software-first onboarding creating niches for challengers as branch-network-dependent institutions cede share.
For Market Incumbents: Insulate token vault control against API-native challengers by deepening ACPR-supervised issuer-processing relationships. Defend merchant-acquiring scale through proprietary secure element access rather than terminal hardware bundling. Acquire cloud-native credential provisioning capabilities to counter host card emulation migration compressing hardware margins.
For New Entrants and Emerging Players: Build out zero-hardware onboarding solutions for seasonal tourism merchants in Provence-Alpes-Côte d'Azur corridors. Target underpenetrated hospitality operators in Nice and Cannes seeking rapid deployment without terminal investments. Pursue marketplace distribution channels over bank relationship manager networks.
For Investors and Strategic Acquirers: Capital is best deployed toward API-native acquirers with self-service integration kits and EMVCo token service provider accreditation. Long-term viability favors vendors controlling credential vaults over terminal hardware distributors. Watch Navigo open-loop convergence adoption rates as inflection indicator for transit-wallet integration scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Token Service Provider Accreditation | EMVCo certification enables vault control, extracting rents from fintech partners seeking credential proxies. |
| Cloud-Native Credential Provisioning | Host card emulation migration compresses merchant onboarding from weeks to hours in Lyon hospitality chains. |
| Biometric Consent Layer Investment | CNIL-compliant facial recognition workflows position providers for EU-wide scalability under GDPR Article 35. |
| Transit-Wallet Integration Partnership | Île-de-France Mobilités open-loop convergence creates unified payment experiences across retail and transportation. |
| API-First Merchant Acquisition Platform | Self-service integration kits capture Lille and Nantes independents abandoning branch-network onboarding. |
Research Methodology
Initial hypotheses were tested against primary input from payment platform engineers, merchant acquiring executives, regulatory compliance officers, and hospitality operations directors and refined through secondary validation across ACPR licensing databases, CNIL enforcement records, EMVCo certification registries, and SEC filings from listed payment processors. Bottom-up transaction volume modeling triangulated against top-down banking sector revenue allocations.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions spanned payment method technology, end user archetype, service provider license tier, and deployment model infrastructure ownership. CAGRs derived from terminal penetration curves, wallet adoption rates, and regulatory implementation timelines. Industry-specific inputs included NFC terminal shipment data and open banking API call volumes.
Sensitivities concentrate around GDPR enforcement intensity, CE-marked terminal supply disruptions, and interchange fee regulatory revisions. Forecasts reflect assumptions on biometric authentication adoption and cloud migration velocity. Cross-checking against European Central Bank payment statistics and Banque de France transaction data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Money Transfer Agencies Market
Payments
Direct Carrier Billing Market
Payments
Master Recharge API Market
Payments
NFC Payments Market
Payments
Europe Fuel Cards Market
Payments
QR Codes Payment Market
Payments
United States Clearing Houses and Settlements Market
Payments
E-Wallet Market
Payments
United Arab Emirates Real Time Payments Market
Payments
UK Prepaid Cards Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Biometric Payment Market
Payments
United States Mobile Payment Market
Payments
Japan Virtual Cards Market
Payments
Sweden POS Terminals Market
Payments
Saudi Arabia Buy Now Pay Later Services Market