
 France Student Loan Market | 2026-2036
France Student Loan Market Size, Share, and Industry Trends Forecast 2026-2036
France Student Loan Market Insights
The gap between government-backed student credit and private refinancing options is shifting as borrowers with stronger credit profiles seek lower rates outside state channels. SoFi leverages its technology platform to compete for French graduates with international earning potential. Prodigy Finance specializes in cross-border lending to international students enrolled at French business schools. MPOWER Financing anchors its model on future-income scoring rather than co-signer requirements, differentiating its risk approach from traditional French banks.
France student loans constitute debt instruments issued to finance tuition, living expenses, and ancillary academic costs, typically structured with repayment terms spanning two to twenty years and interest rates indexed to European reference benchmarks or fixed contractual terms. These products primarily enable access to higher education for individuals lacking immediate liquidity or family capital. Government-funded loans retain the largest volume share due to state guarantees and subsidized rate floors, while income-driven repayment models are gaining traction fastest among private issuers seeking to align obligations with graduate earnings trajectories. Short-term and medium-term durations dominate the current portfolio, though extended terms are emerging as a margin pool for refinancing specialists targeting alumni with established credit histories.
The French Prudential Supervision and Resolution Authority (ACPR) oversees lending conduct and consumer protection standards for student credit products, while EU-wide consumer credit directives harmonize disclosure and cooling-off requirements across member states. France's national student support system under the Caisse des Dépôts et Consignations shapes demand by setting baseline terms that private competitors must exceed to win borrowers. Stakeholders should monitor how upcoming revisions to income-contingent repayment thresholds affect the relative attractiveness of private refinancing versus public consolidation pathways.
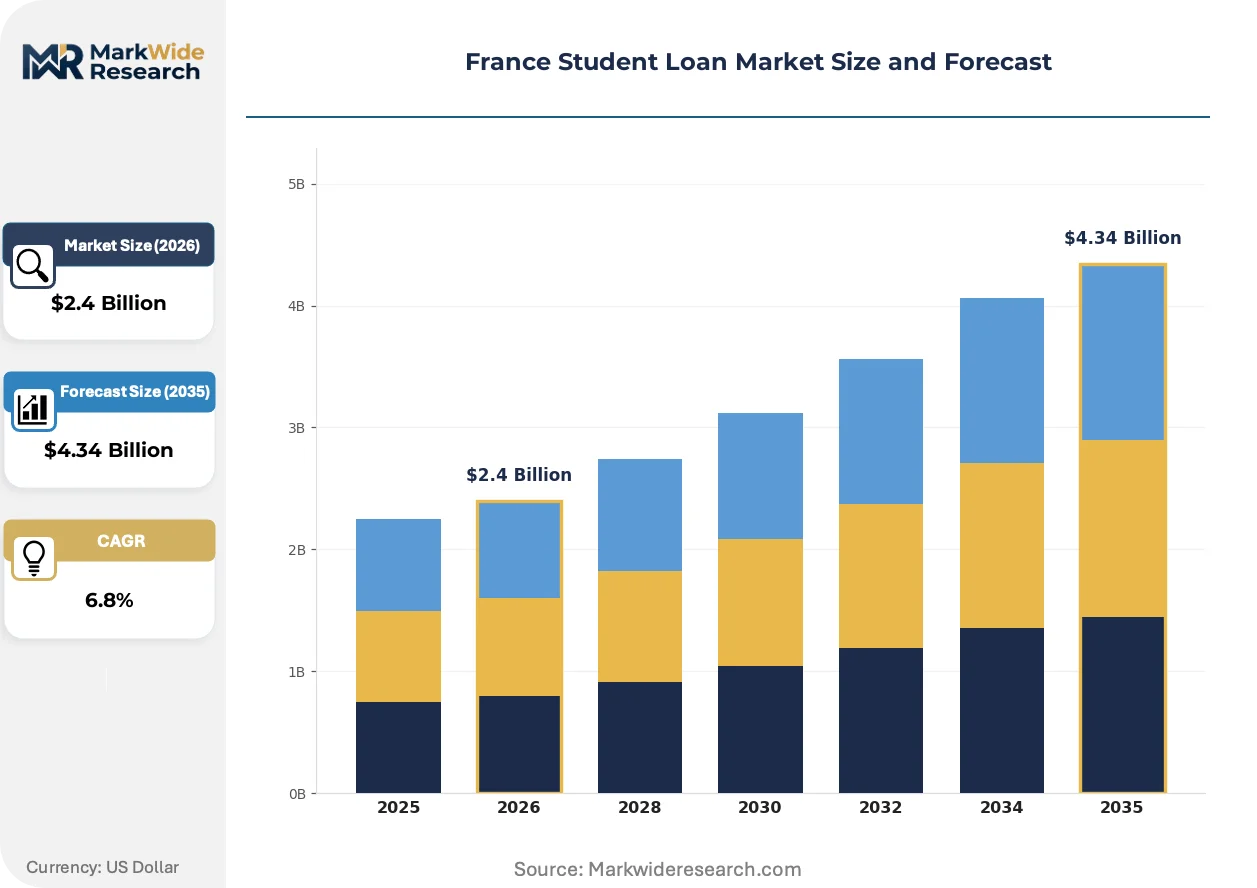
Market Dynamics
The income-contingent repayment framework administered by Caisse des Dépôts et Consignations is compressing margins for private lenders while forcing product innovation around future-earnings underwriting models.
Growth Catalysts
- Professional degree cost inflation:Graduate programs at French business schools and engineering institutions are driving borrowing volumes upward as tuition outpaces family savings capacity.
- EU Consumer Credit Directive harmonization:Standardized disclosure requirements across member states are lowering cross-border refinancing friction for mobile French graduates.
- Paris-Ile-de-France housing cost concentration:Living expense differentials between the capital region and provincial university clusters are expanding loan size averages in the primary demand center.
Market Restraints
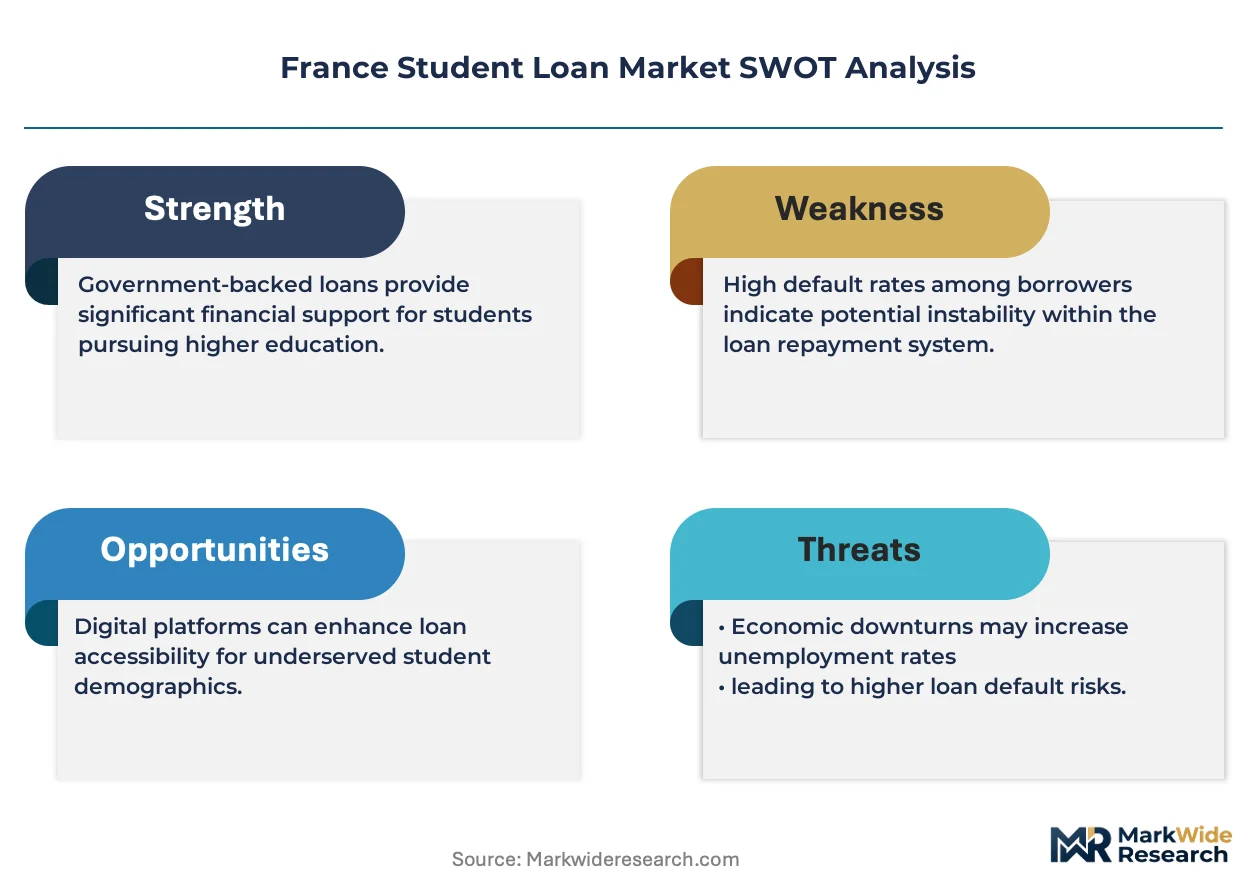
- State guarantee crowding-out:Government-backed loan floors with subsidized rates limit private issuer pricing power across the core undergraduate segment.
- EURIBOR volatility transmission:Interest rate benchmarks indexed to European money markets expose floating-rate portfolios to refinancing risk during monetary tightening cycles.
- Co-signer dependency in traditional banking:French retail banks maintain collateral requirements that exclude borrowers from non-asset-owning families, capping addressable market penetration.
Strategic Opportunities
- Alumni refinancing white space:Established graduates with credit histories represent an underserved segment for rate reduction products outside state consolidation pathways.
- Future-income scoring technology:Machine learning models analyzing degree-specific earnings trajectories enable unsecured lending to international students without local co-signers.
- Grand Est and Occitanie expansion:University cluster development outside Paris is creating provincial volume pools with lower competitive intensity.
Industry Challenges
- ACPR compliance timeline compression:The French Prudential Supervision and Resolution Authority's evolving conduct standards require continuous product restructuring.
- Legacy core banking integration:Fintech originators face technical friction connecting automated underwriting engines to established payment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Student Loan Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Government-Funded, Private, Subsidized, Unsubsidized Borrower Type: Undergraduate Students, Graduate Students, International Students, Alumni Repayment Model: Pay-As-You-Earn, Fixed Rate, Income-Driven, Interest-Only Loan Duration: Short-Term, Medium-Term, Long-Term, Extended |
| Companies Covered | Earnest, College Ave, Prodigy Finance, SoFi, Ascent, MPOWER Financing, Sallie Mae, GlobCred, Avanse, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Student Loan Market Trends and Innovations
Digital underwriting platforms are displacing branch-based origination while income-contingent structures migrate from public programs into private product design.
Automated future-income scoring is modularizing risk assessment across the lending stack. These algorithms ingest degree program, institution, and field-of-study data to project repayment capacity without traditional credit history. Fintech originators targeting international enrollees at HEC Paris and INSEAD have deployed these models at scale. The technology is modularizing how originators separate pricing tiers by earnings trajectory rather than collateral backing.
ACPR's evolving consumer protection guidelines are tightening cooling-off period enforcement and pre-contractual disclosure requirements. Lenders must now deliver standardized European Consumer Credit Information forms with enhanced total-cost-of-credit calculations. Private issuers are responding by extending grace periods and building regulatory buffers into pricing spreads.
Borrower channel preference is fragmenting away from branch networks toward mobile-first origination platforms. French graduates with international mobility are demanding multi-currency repayment options and cross-border servicing capabilities. This shift concentrates among business school alumni with earnings denominated in USD or GBP.
France Student Loan Market Segmentation
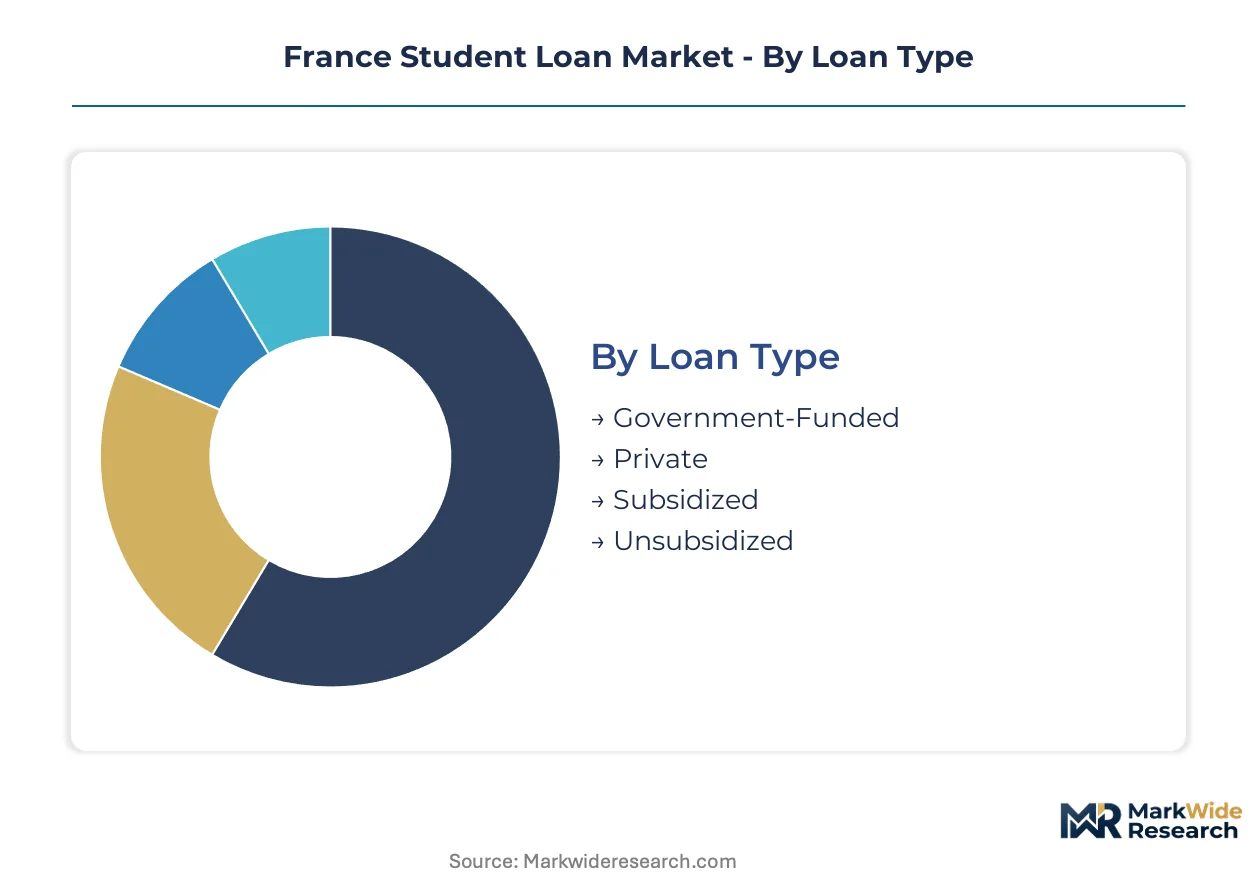
Segmentation in the France student loan market reveals how borrower circumstances and regulatory frameworks shape product architecture. Lenders structure offerings around funding source, academic progression stage, repayment capacity, and time horizon to match risk profiles with appropriate capital deployment.
Loan Type:
Funding source determines rate floors, guarantee backing, and borrower eligibility thresholds across the French market.
- Government-Funded:State-backed instruments administered through Caisse des Dépôts et Consignations carry subsidized interest rate floors and income-contingent repayment guarantees. These products dominate undergraduate volumes in Paris-Ile-de-France and provincial university clusters where family liquidity constraints are most acute.
- Private:Bank-originated and fintech-distributed credit operates outside state guarantee frameworks, competing on rate reduction for borrowers with established credit histories or international earning potential. Demand concentrates among business school alumni seeking refinancing outside public consolidation pathways.
- Subsidized:Interest accrual pauses during enrollment periods, with state actors absorbing carrying costs. Engineering and medical programs in Grand Est and Occitanie show elevated uptake where extended study durations amplify subsidy value.
- Unsubsidized:Interest capitalizes throughout academic tenure, requiring borrowers to service or defer payments without public support. International enrollees at HEC Paris and INSEAD frequently access these structures when government programs exclude non-citizens.
Volume sits with Government-Funded; growth tilts toward Private refinancing instruments.
Borrower Type:
Academic progression stage shapes loan size, co-signer requirements, and future-income underwriting model applicability.
- Undergraduate Students:First-cycle enrollees access smaller principal amounts tied to state-determined living expense benchmarks. Paris housing cost premiums drive borrowing volumes above Lyon or Marseille equivalents.
- Graduate Students:Second-cycle and professional degree candidates command larger facilities as tuition at French business schools and engineering institutions outpaces family savings capacity. Future-income scoring models gain traction here.
- International Students:Cross-border enrollees without local credit history or co-signer access rely on degree-specific earnings projections and multi-currency repayment options. INSEAD and HEC Paris attract concentrated fintech originator activity.
- Alumni:Degree completers with established employment and credit histories represent an underserved refinancing segment. ACPR disclosure requirements and cooling-off period enforcement shape product design for this cohort.
Undergraduate Students carry the largest outstanding balances; International Students are expanding most quickly as fintech underwriting models scale.
Repayment Model:
Repayment structure alignment with earnings volatility determines default probability and lender margin sustainability.
- Pay-As-You-Earn:Monthly obligations scale with documented income, administered through Caisse des Dépôts infrastructure. This model dominates public sector employment trajectories.
- Fixed Rate:Contractual obligations remain constant regardless of income fluctuation, exposing borrowers to stress during unemployment but offering lender margin predictability. EURIBOR-indexed variants transmit monetary policy tightening directly to obligors.
- Income-Driven:Private issuers are migrating public program structures into proprietary products, capping payments at earnings percentages and extending forgiveness horizons. Machine learning models enable this without traditional credit history requirements.
- Interest-Only:Principal amortization pauses during early career phases, common among medical and legal trainees in extended residency or pupillage periods. Grand Est university hospitals generate concentrated demand.
Fixed Rate structures dominate current portfolios; Income-Driven configurations are gaining share fastest among private originators.
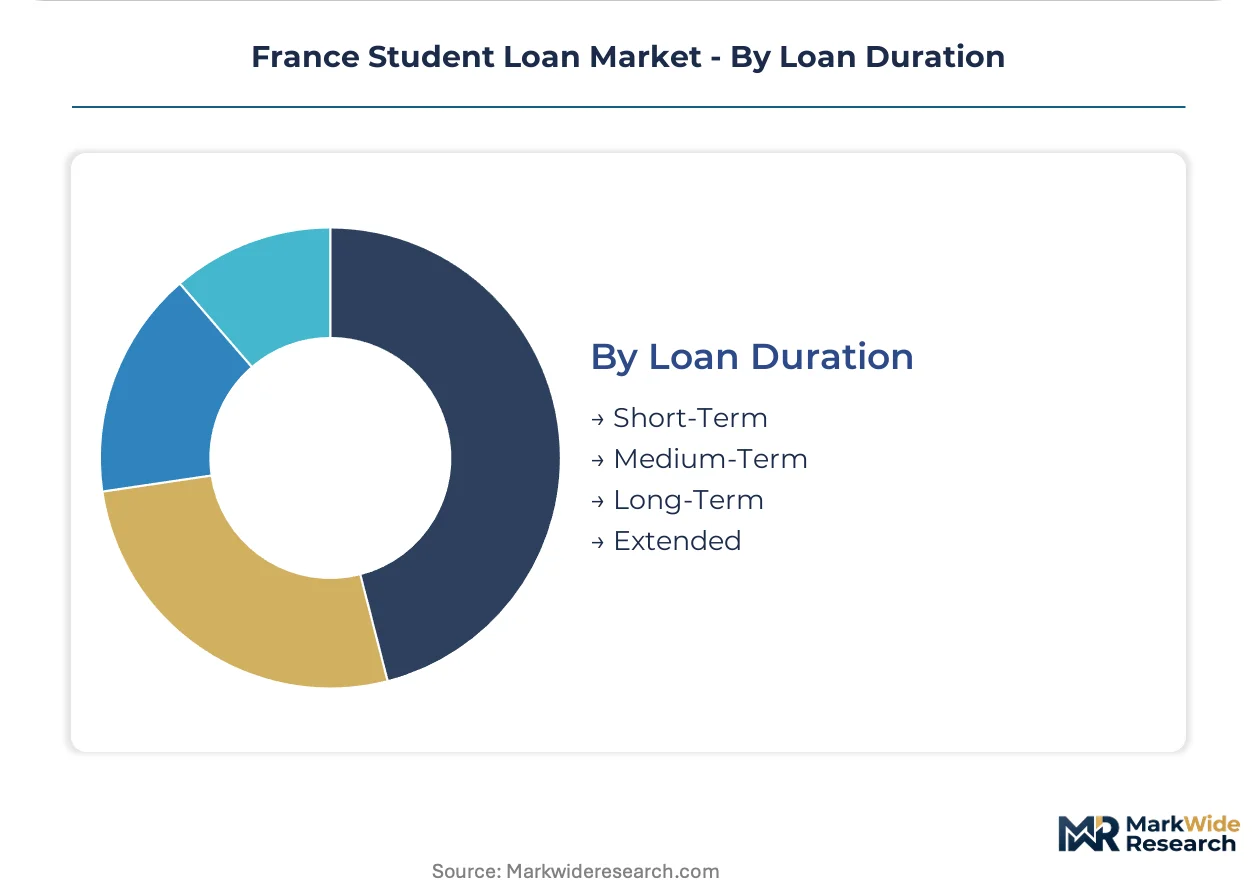
Loan Duration:
Time horizon selection reflects borrower career stage, refinancing intent, and interest rate environment expectations.
- Short-Term:Facilities under five years target living expense gaps or supplemental tuition needs, frequently originated through mobile-first platforms. Paris-Ile-de-France concentration mirrors housing cost pressure.
- Medium-Term:Five-to-ten-year structures balance manageable monthly obligations with total interest cost containment. This tier captures standard undergraduate completion-to-repayment transitions.
- Long-Term:Ten-to-twenty-year amortization accommodates larger principal amounts and lower monthly burdens, prevalent among graduate professional programs with extended earnings ramp periods.
- Extended:Beyond-twenty-year terms emerge as a margin pool for refinancing specialists targeting alumni with established credit histories seeking rate reduction through duration trade-offs.
Medium-Term facilities carry the greatest volume concentration; Extended durations are climbing the fastest as refinancing activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris-Ile-de-France concentrates the bulk of French student lending activity, with housing cost premiums and elite business school enrollment driving borrowing volumes well above provincial averages.
Île-de-France
HEC Paris and INSEAD anchor demand for international student lending products, while Caisse des Dépôts administers income-contingent repayment infrastructure for domestic borrowers. ACPR disclosure requirements shape product design for refinancing specialists targeting Paris-based alumni with cross-border earnings.
Auvergne-Rhône-Alpes
Engineering institutions in Lyon and Grenoble generate concentrated graduate borrowing as tuition costs outpace regional family savings capacity. The national student support system provides subsidized rate floors that private lenders must exceed to compete. Clusters around École Centrale de Lyon and Grenoble INP attract fintech originators testing future-income scoring models.
Occitanie
Medical and legal training programs in Toulouse and Montpellier create extended-duration borrowing demand for residency and pupillage periods. State guarantee frameworks dominate undergraduate volumes, while private issuers target post-graduation refinancing. University hospital networks in Grand Est generate parallel demand for interest-only structures.
Provence-Alpes-Côte d'Azur
Aix-Marseille University and Sophia Antipolis technology institutes drive STEM-focused lending with shorter repayment horizons. EU Consumer Credit Directive harmonization facilitates cross-border refinancing for mobile graduates with international employment. The region's lower housing cost differential relative to Paris reduces average loan sizes.
Hauts-de-France
Lille's university cluster and proximity to Belgian border labor markets create demand for multi-currency repayment products. Traditional retail banks maintain co-signer requirements that exclude non-asset-owning families, opening space for fintech alternatives. Regional volume pools attract lower competitive intensity than capital-based markets.
France Student Loan Market Competitive Landscape
Premium-margin players sit above commodity-margin players across underwriting sophistication and borrower credit profile stratification. Government-backed lending through Caisse des Dépôts retains volume dominance via subsidized rate floors, while private issuers compete for refinancing share among established graduates. Three archetypes define the competitive set: state-administered platforms with guarantee backing, fintech originators deploying algorithmic future-income scoring, and traditional retail banks with collateral-dependent underwriting. Dominant competitive moves center on technology licensing partnerships for automated underwriting and geographic expansion into provincial university clusters with lower rival density.
Within the cross-border specialist tier, Prodigy Finance and MPOWER Financing exemplify future-income underwriting models targeting international enrollees without local co-signer access. SoFi occupies a position among technology-platform originators competing for French graduates with international earning potential and multi-currency servicing needs. These three entities represent the private-market vanguard reshaping repayment product architecture around earnings-trajectory alignment rather than traditional credit history requirements.
| Leading Market Players |
|---|
| Earnest |
| College Ave |
| Prodigy Finance |
| SoFi |
| Ascent |
| MPOWER Financing |
| Sallie Mae |
| GlobCred |
| Avanse |
| Others |
Pricing and Supply Chain Analysis
Credit risk modelers concentrated in Paris-Ile-de-France drive labor-cost differentials that widen pricing spreads between algorithmic fintech originators and branch-dependent retail banks. ACPR compliance overhead feeds into premium pricing for income-contingent repayment products, while provincial university clusters attract leaner cost structures.
Pricing Analysis
Future-earnings yield anchors pricing for international student lending at HEC Paris and INSEAD, with repayment capacity projections replacing collateral thresholds. Three-tier pricing structure across premium, standard, and economy levels separates alumni refinancing from graduate enrollment from undergraduate state-backed channels. Cost compression in the standard tier intensifies because EURIBOR volatility transmits directly to floating-rate portfolios. International students with multi-currency servicing needs show least price sensitivity, while provincial undergraduate borrowers accessing government-funded programs face highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Caisse des Dépôts et Consignations as the exclusive administrator of income-contingent repayment infrastructure. Capital deployment draws from French retail banking networks, Luxembourg-based securitization vehicles, and London-based institutional investors. Regulatory restriction risk centers on ACPR cooling-off period enforcement and EU Consumer Credit Directive harmonization timelines. Distribution runs through mobile-first origination platforms for fintech originators, while traditional banks maintain branch-based channels with co-signer documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from ACPR compliance timeline compression will force smaller fintech originators into strategic exits or acquisition by scaled platforms with regulatory buffers already embedded.
For Market Incumbents: Anticipate margin compression in the undergraduate segment by accelerating alumni refinancing product development with extended-duration structures. Build regulatory technology partnerships to automate European Consumer Credit Information form generation and cooling-off period tracking. Defensive moats deepen through vertical integration into future-income scoring model development rather than third-party algorithm licensing. For New Entrants and Emerging Players: Begin with Occitanie and Grand Est university clusters where competitive intensity lags Paris-Ile-de-France and state guarantee crowding-out is less pronounced. Target medical and legal training programs in Toulouse and Montpellier with interest-only structures for residency periods. Go-to-market positioning centers on machine learning-enabled underwriting without co-signer requirements for international enrollees. For Investors and Strategic Acquirers: Re-rating potential sits with fintech originators possessing proprietary future-income scoring technology given EU Consumer Credit Directive harmonization enabling cross-border refinancing scale. Long-term viability favors platforms with diversified funding sources beyond single-country retail deposits. The signal to watch is ACPR threshold adjustments for income-contingent repayment eligibility that would expand or contract private refinancing addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Future-Income Scoring Platform Development | Machine learning models analyzing HEC Paris and INSEAD earnings trajectories enable unsecured international student lending. |
| Multi-Currency Servicing Infrastructure | Repayment options in USD and GBP capture French business school alumni with cross-border employment mobility. |
| Provincial University Cluster Expansion | Grand Est and Occitanie volume pools offer lower competitive intensity than saturated Paris-Ile-de-France markets. |
| ACPR Compliance Technology Investment | Automated European Consumer Credit Information form delivery reduces regulatory friction and cooling-off period enforcement risk. |
| Alumni Refinancing Product Launch | Extended-duration structures targeting established graduates with credit histories outside Caisse des Dépôts consolidation pathways. |
Research Methodology
Document review covered ACPR conduct guidelines, EU Consumer Credit Directive harmonization texts, and Caisse des Dépôts et Consignations program disclosures, complemented by interviews with student lending product managers at French retail banks, fintech underwriting executives, regulatory affairs specialists, university financial aid officers, and international enrollment directors. Secondary validation drew from ECB monetary policy communications, EURIBOR benchmark methodologies, and French higher education enrollment statistics. Bottom-up loan volume modeling triangulated against top-down market sizing from national student support system outflows.
Segment-level projections across loan type, borrower type, repayment model, and loan duration dimensions were generated through driver-based modeling. CAGRs were derived from enrollment trend analysis, tuition cost inflation trajectories, and refinancing penetration assumptions. Key inputs included professional degree cost inflation at French business schools, Paris-Ile-de-France housing cost differentials, and fintech originator market entry velocity.
Underlying measurement precision varies by segment; government-funded loan volumes carry tighter precision due to Caisse des Dépôts reporting transparency, while private refinancing activity involves greater estimation uncertainty. Forecasts reflect assumptions around ACPR regulatory evolution, EURIBOR trajectory, and EU cross-border lending harmonization pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Student Loan Market
Loans and Leasing
Factoring Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Loan Management Software Market