
 Indonesia Mortgage/Loan Brokers Market | 2026-2036
Indonesia Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Mortgage/Loan Brokers Market Insights
Commission-based origination revenue is reconfiguring toward fee-for-service advisory models as Indonesian borrowers demand transparent rate comparisons. PT Bank Rakyat Indonesia (Tbk) leverages its micro-lending heritage to dominate rural mortgage origination through village-level agent networks. PT Bank Central Asia (Tbk) sustains premium positioning among affluent Jakarta homeowners via dedicated wealth-advisor channels. PT Bank Mandiri (Tbk) anchors state-backed KPR FLPP distribution, controlling subsidized home-loan pipelines that competitors cannot replicate.
A mortgage/loan broker functions as an intermediary that matches borrowers with lenders, earning commissions or fees for arranging credit facilities ranging from residential mortgages to commercial property financing. The broker assesses creditworthiness, packages documentation, and negotiates terms across multiple banking partners to optimize borrower outcomes. Home loan origination captures the dominant value pool as Indonesia's housing backlog exceeds millions of units, while online platforms represent the fastest-growing distribution channel as smartphone penetration enables direct rate comparison. Advisory services command premium margins compared to application assistance, though loan comparison tools commoditize basic brokerage functions among price-sensitive first-time buyers.
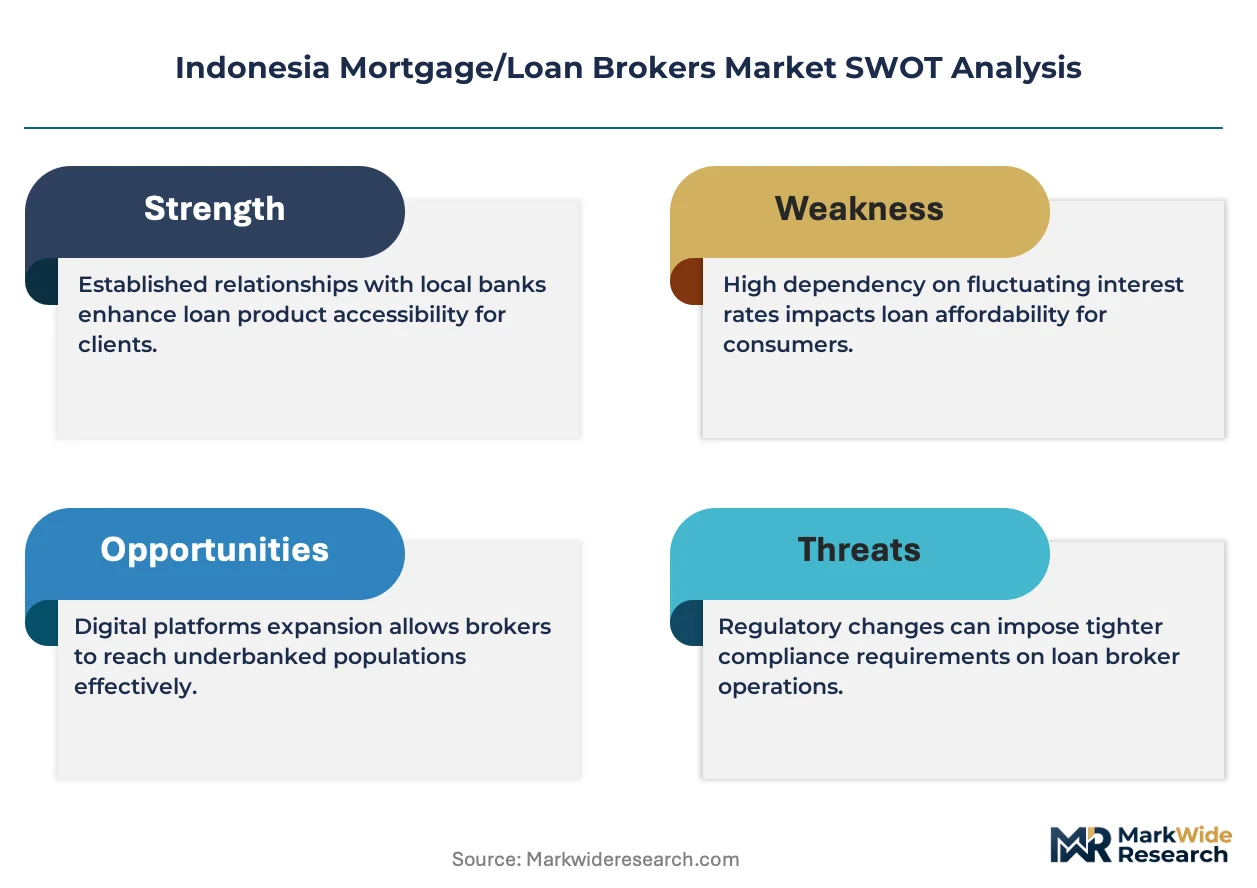
Otoritas Jasa Keuangan (OJK) licensing requirements and Bank Indonesia macroprudential rules on loan-to-value ratios shape broker compliance costs and product availability across the archipelago. BI's KPR subsidy programs and OJK fintech lending regulations collectively determine which broker channels can access retail mortgage flows, privileging bank-affiliated brokers with balance-sheet depth. Stakeholders must monitor whether OJK digital banking licenses for neobanks disintermediate traditional brokers or create new partnership tiers for technology-enabled intermediaries.
Market Dynamics
The Indonesia mortgage/loan broker market is being fundamentally restructured by the collision between Bank Indonesia's macroprudential rate adjustments and the rapid deployment of fintech origination platforms. Traditional branch-dependent brokers face margin compression as smartphone-enabled rate comparison tools concentrate demand among digitally fluent middle-class households in Greater Jakarta and Surabaya.
Growth Catalysts
- KPR FLPP Subsidy Programs:State-backed subsidized home-loan pipelines channel volume through bank-affiliated brokers with balance-sheet depth, privileging rural and first-time buyer segments that traditional lenders previously underserved.
- Smartphone Penetration:Direct rate comparison applications are collapsing information asymmetries between borrowers and lenders, accelerating broker adoption among price-sensitive households in secondary Indonesian cities.
- OJK Fintech Lending Regulations:Digital banking license frameworks for neobanks create new partnership tiers for technology-enabled intermediaries, expanding legitimate broker channel access to retail mortgage flows.
Market Restraints
- BI Loan-to-Value Macroprudential Rules:Stringent down-payment requirements for second and third properties constrain broker product availability and compress origination volumes in the investment property segment.
- Branch Infrastructure Fixed Costs:Traditional brokerage networks anchored in physical locations face structural cost disadvantages against digital-native competitors with minimal real estate overhead.
- Credit Bureau Coverage Gaps:Incomplete centralized credit data across Indonesia's archipelago elevates broker due-diligence costs and extends approval timelines for rural borrowers.
Strategic Opportunities
- East Java Secondary Cities:Surabaya and Malang exhibit underpenetrated broker penetration relative to Greater Jakarta, with rising middle-class formation creating whitespace for advisory-service positioning.
- Fee-for-Service Advisory Models:Transparent rate comparison demands from Indonesian borrowers enable margin expansion beyond commission-based origination into subscription or hourly advisory structures.
- Village-Level Agent Networks:Micro-lending heritage distribution models from rural banking partners can be repurposed for mortgage origination in areas where formal broker presence remains minimal.
Industry Challenges
- Licensed Mortgage Advisor Talent Scarcity:OJK certification requirements for complex product advisory outpace training pipeline capacity, constraining service quality at scaling broker operations.
- Legacy Core Banking Integration:Established lenders' antiquated loan origination systems create API friction for digital broker platforms attempting real-time application submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Mortgage/Loan Brokers Market |
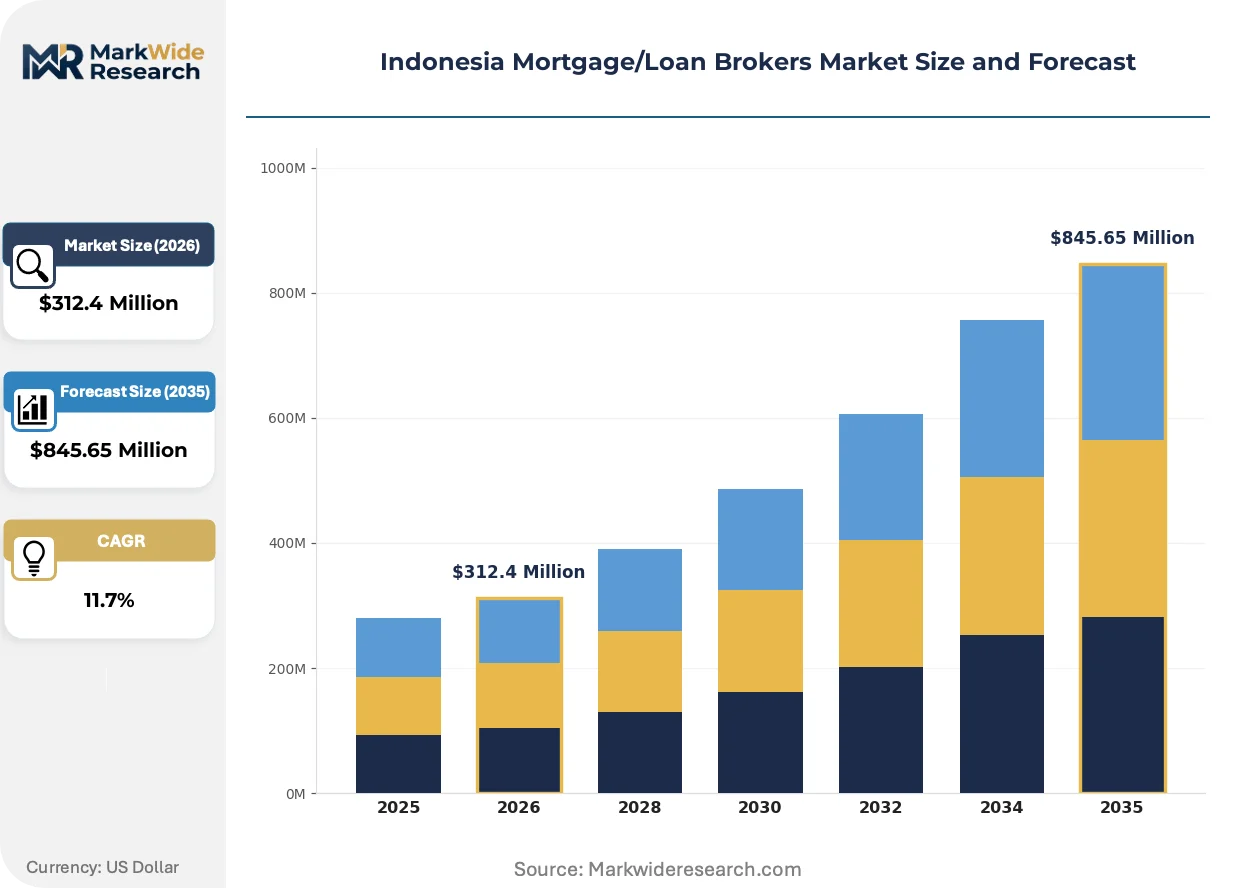
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Loan, Personal Loan, Auto Loan, Business Loan Client Type: First-time Buyers, Investors, Homeowners, Contractors Service Type: Advisory Services, Application Assistance, Loan Comparison, Remortgaging Distribution Channel: Online Platforms, Bank Branches, Mortgage Brokers, Financial Advisors |
| Companies Covered | PT Bank Mandiri (Tbk), PT Bank Rakyat Indonesia (Tbk), PT Bank Central Asia (Tbk), PT Bank Negara Indonesia (Tbk), PT Bank Tabungan Negara (Tbk), Bank Danamon Indonesia, Panin Bank, Citibank Indonesia, HSBC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Mortgage/Loan Brokers Market Trends and Innovations
Digitization is collapsing the traditional information advantage that branch-based brokers held over borrowers. Three interconnected developments are accelerating this structural shift across Indonesian mortgage intermediation.
Artificial intelligence-powered credit scoring engines are collapsing the due-diligence timeline that previously justified human broker involvement. Digital-first lenders in Greater Jakarta deploy these tools to deliver pre-approval decisions within hours rather than weeks. First-time buyers in Surabaya and Bandung are migrating toward these platforms, compressing commission pools available to traditional intermediaries.
Bank Indonesia's macroprudential regulations on loan-to-value ratios are reshaping product structuring across the archipelago. The central bank's periodic adjustments to down-payment requirements for primary and secondary residences force brokers to reconfigure affordability calculators and lender matching algorithms. Subsidized KPR FLPP distribution channels are absorbing disproportionate regulatory attention, privileging state-backed broker partnerships.
Households are unbundling mortgage origination from long-term advisory relationships. Price-sensitive borrowers in Indonesia's secondary cities now treat broker engagement as transactional, switching between comparison platforms for each property purchase. This behavior concentrates volume among aggregator applications that commoditize basic application assistance while eroding loyalty-based revenue for relationship-oriented intermediaries.
Indonesia Mortgage/Loan Brokers Market Segmentation
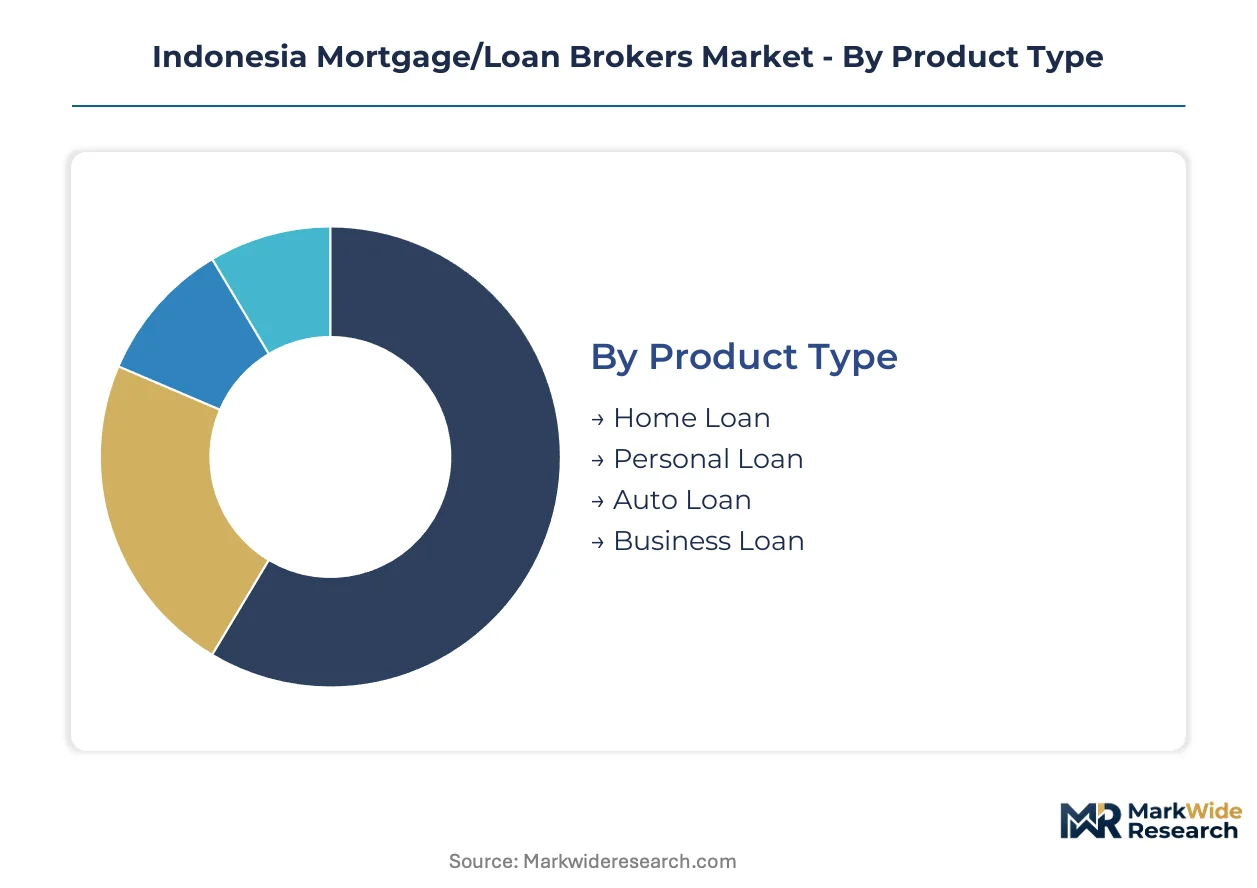
Segmentation in Indonesia's mortgage brokerage market reveals how regulatory frameworks and digital adoption patterns split revenue pools across distinct customer journeys. Understanding these divides helps stakeholders allocate origination capacity and compliance resources where structural returns concentrate.
Product Type:
Mature collateral-backed products dominate origination volumes, while unsecured lending segments exhibit divergent broker economics.
- Home Loan:Residential mortgage origination anchors broker revenue through KPR FLPP subsidy pipelines and conventional bank distribution. Demand concentrates among first-time buyers in Greater Jakarta and Surabaya where BI rate adjustments and down-payment rules reshape monthly affordability calculations.
- Personal Loan:Unsecured consumer credit facilities carry higher broker commissions but elevated default risk, driving demand toward digitally scored fintech platforms in Bandung and Medan where smartphone penetration enables rapid pre-approval workflows.
- Auto Loan:Vehicle financing origination leverages dealer-integrated broker networks with standardized collateral valuation reducing due-diligence overhead.
- Business Loan:Commercial credit placement requires specialized OJK licensing and relationship banking access, limiting viable broker participation to established financial advisory firms.
Home Loan handles the majority of throughput; Personal Loan is the fastest mover on share.
Client Type:
Customer lifecycle positioning determines advisory depth and fee structure viability across Indonesian broker operations.
- First-time Buyers:Entry-level borrowers navigating KPR FLPP eligibility and BI loan-to-value requirements generate volume-heavy, commission-thin origination flows concentrated in secondary cities.
- Investors:Multiple-property purchasers face stringent BI macroprudential down-payment rules on second and third residences, compressing origination frequency but sustaining premium advisory fees for tax-optimized structuring in Jakarta's luxury condominium market.
- Homeowners:Existing property holders seeking refinancing or top-up facilities represent recurring revenue pools for relationship-oriented brokers with established bank partnerships.
- Contractors:Project-based borrowers with irregular income documentation require specialized packaging expertise, elevating broker service fees in Surabaya's construction corridor.
First-time Buyers absorb the largest share of broker attention; Investors deliver the highest margin per transaction.
Service Type:
Service depth stratification mirrors how Indonesian borrowers unbundle origination assistance from ongoing financial advice.
- Advisory Services:Comprehensive financial planning encompassing debt structuring, tax optimization, and lender negotiation commands subscription or hourly fee models among affluent Jakarta households seeking transparency beyond commission-driven placement.
- Application Assistance:Documentation packaging and submission support for KPR FLPP and conventional mortgage applications captures volume-driven commission flows across bank-affiliated broker networks.
- Loan Comparison:Rate aggregation platforms commoditize basic brokerage functions, concentrating usage among price-sensitive smartphone-enabled borrowers in Bandung and Malang.
- Remortgaging:Refinancing facilitation for existing mortgage holders exploits BI rate adjustment cycles, with demand spiking following central bank policy announcements.
Application Assistance processes the highest transaction count; Advisory Services is climbing the fastest as fee-for-service models gain traction.
Distribution Channel:
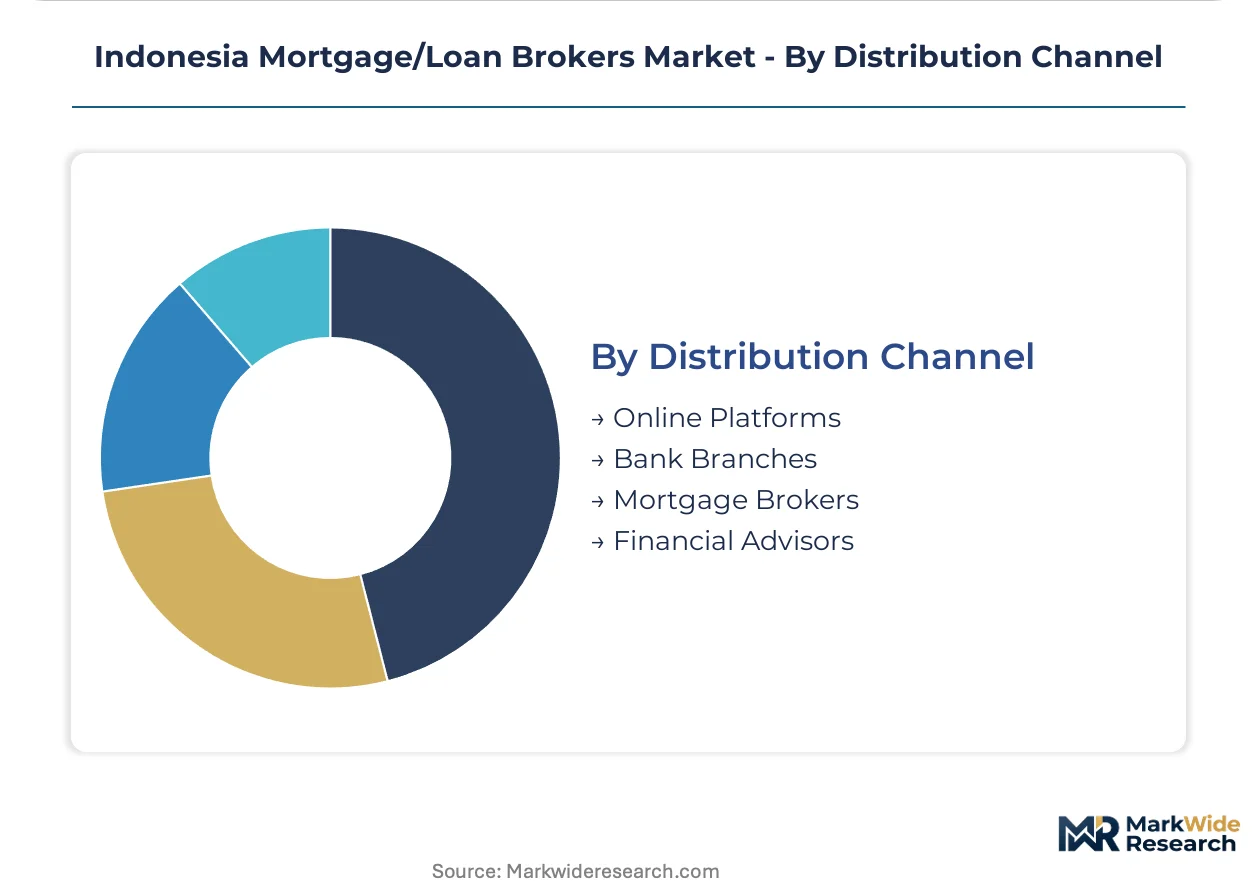
Channel economics diverge sharply between fixed-cost branch infrastructure and variable-cost digital origination platforms.
- Online Platforms:Smartphone-enabled rate comparison and application portals collapse information asymmetries, capturing digitally fluent middle-class demand in Greater Jakarta while compressing margins for traditional intermediaries.
- Bank Branches:Captive origination through PT Bank Rakyat Indonesia and PT Bank Mandiri branch networks leverages balance-sheet depth and KPR FLPP distribution rights, privileging rural penetration through village-level agent models.
- Mortgage Brokers:Independent intermediaries negotiate across multiple lenders, sustaining relevance where complex income documentation or non-standard property collateral requires human judgment.
- Financial Advisors:Wealth-integrated channels at PT Bank Central Asia and private banking units serve high-net-worth households with holistic balance-sheet management rather than transactional origination.
Bank Branches originate the largest loan volume; Online Platforms is expanding most quickly on customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyers in Greater Jakarta exhibit the highest price elasticity, while affluent homeowners in Surabaya show markedly lower sensitivity to rate fluctuations. This divergence shapes broker service models across Indonesia's urban hierarchy.
Greater Jakarta
Digital-native middle-class households drive smartphone-enabled rate comparison adoption. Bank Indonesia's macroprudential loan-to-value adjustments force monthly recalibration of affordability calculators. South Tangerang and Bekasi corridors concentrate new development broker activity.
East Java
Surabaya and Malang exhibit underpenetrated broker presence relative to capital-region saturation. KPR FLPP subsidy pipelines channel volume through state-backed distribution networks. Malang's university-town demographic generates first-time buyer flows distinct from Surabaya's industrial corridor.
West Java
Bandung's tech-sector employment base sustains demand for advisory-service positioning beyond transactional origination. OJK fintech lending regulations enable digital broker platform licensing. The northern coastal industrial zone anchors manufacturing-employee mortgage pipelines.
North Sumatra
Medan's trading-economy households require specialized income-documentation packaging. Credit bureau coverage gaps elevate due-diligence costs for rural-urban migrant borrowers. The Deli Serdang periphery concentrates new residential development broker engagement.
South Sulawesi
Makassar's port-economy professionals generate commercial-property financing demand alongside residential origination. Village-level agent networks from micro-lending heritage extend formal mortgage access. The city's secondary-city status preserves higher broker margins than saturated primary markets.
Indonesia Mortgage/Loan Brokers Market Competitive Landscape
Capability concentration sits with state-backed institutions possessing KPR FLPP distribution rights; scale advantage sits with private-sector banks with dense branch infrastructure. The market structures around three archetypes: subsidized-loan specialists, premium-affluent advisors, and digital-first aggregators. Consolidation pressure favors balance-sheet depth over pure brokerage independence. Dominant competitive moves include API partnerships with fintech platforms and geographic densification in secondary cities.
Among state-backed lenders, PT Bank Mandiri (Tbk) and PT Bank Rakyat Indonesia (Tbk) occupy positions reflecting divergent heritage advantages—Mandiri anchoring FLPP distribution infrastructure, BRI repurposing village-level micro-lending networks. PT Bank Central Asia (Tbk) represents the premium-tier archetype through wealth-integrated advisory channels. These three institutions exemplify how regulatory access and distribution heritage stratify competitive positioning beyond raw origination volume.
| Leading Market Players |
|---|
| PT Bank Mandiri (Tbk) |
| PT Bank Rakyat Indonesia (Tbk) |
| PT Bank Central Asia (Tbk) |
| PT Bank Negara Indonesia (Tbk) |
| PT Bank Tabungan Negara (Tbk) |
| Bank Danamon Indonesia |
| Panin Bank |
| Citibank Indonesia |
| HSBC |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in KPR FLPP-subsidized origination pipelines across East Java and North Sumatra drives commission compression for traditional brokers while concentrating pricing power with state-backed lenders holding exclusive distribution rights. Bank Indonesia's macroprudential adjustments feed directly into broker fee structures, as down-payment rule changes force recalibration of advisory service premiums.
Pricing Analysis
Long-term offtake contracts between bank-affiliated brokers and state-backed lenders dominate commission structures, while spot-rate advisory engagements emerge among affluent Jakarta households seeking transparency. Price differentiation hinges on OJK licensing tier and geographic delivery cost, with rural-origination premiums reflecting credit bureau coverage gaps. Pricing pressure stems from fintech platform commoditization of basic loan comparison functions. First-time buyers in secondary cities exhibit highest price sensitivity; high-net-worth investors in luxury condominiums show lowest elasticity.
Supply Chain Analysis
Upstream feedstock of licensed mortgage advisors and OJK-certified compliance personnel concentrates in Greater Jakarta and Surabaya, creating talent bottlenecks for scaling operations. Broker networks draw from village-level agent infrastructure repurposed from micro-lending heritage, bank branch distribution partnerships, and API-integrated fintech platforms. Single-source vulnerability sits with KPR FLPP distribution rights held by limited state-backed institutions. Distribution runs through captive bank channels, independent broker negotiations, and smartphone-enabled aggregator applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as Indonesian borrowers unbundle origination from advisory relationships, creating niche positioning for transparent fee-for-service models against commission-driven incumbents.
For Market Incumbents: Insulate core KPR FLPP distribution relationships through exclusive API partnerships with neobanks pursuing OJK digital banking licenses. Deepen village-level agent network penetration in underserved corridors before fintech platforms achieve comparable last-mile coverage. Threat substitution from AI-powered credit scoring engines demands accelerated advisory-service tier development to escape commoditization. For New Entrants and Emerging Players: Pursue white-space positioning in Malang and Makassar where broker penetration lags Greater Jakarta saturation. Target contractor-income documentation packaging in Surabaya's construction corridor, where specialized expertise commands premium fees. Go-to-market leverage rests on OJK fintech lending regulation compliance enabling legitimate retail mortgage flow access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital-first broker platforms as cloud infrastructure replaces branch fixed costs. Long-term viability favors technology-enabled intermediaries with balance-sheet partnerships over pure origination plays. Acquisition archetype: licensed brokers with established bank API integrations and secondary-city geographic densification. Signal to monitor: OJK neobank license issuance velocity as partnership-tier expansion indicator.| Strategic Initiative | Industry Significance |
|---|---|
| API Partnership with Neobanks | Unlocks real-time mortgage flow access under OJK digital banking frameworks. |
| Village-Level Agent Network Expansion | Extends formal origination reach into rural areas where credit bureau coverage remains incomplete. |
| Fee-for-Service Advisory Model Launch | Captures transparency-seeking affluent households in Jakarta's wealth-integrated channels. |
| AI Credit Scoring Integration | Collapses pre-approval timelines that previously justified human broker involvement. |
| East Java Geographic Densification | Exploits underpenetrated broker presence in Surabaya and Malang relative to capital-region saturation. |
Research Methodology
Initial hypotheses were tested against primary input from mortgage origination executives, OJK compliance officers, bank distribution channel managers, and fintech platform engineers and refined through secondary validation. Sources included OJK regulatory filings, Bank Indonesia macroprudential announcements, KPR FLPP program documentation, and lender annual disclosures. Bottom-up origination volume estimates triangulated against top-down addressable market calculations across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling broker commission flows against subsidized loan pipeline capacity and digital platform adoption curves. Segmentation dimensions encompassed product type, client lifecycle positioning, service depth tier, and distribution channel economics. CAGRs derived from regression analysis of historical origination trends, BI rate adjustment cycles, and smartphone penetration trajectories. Industry-specific inputs included KPR FLPP allocation trajectories and OJK licensing velocity assumptions.
Macroeconomic conditions sit as an overlay; deviation in BI policy rates, rupiah volatility, or property price inflation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory continuity and fintech platform compliance progression. Cross-checking against Bank Indonesia mortgage origination statistics and OJK licensed broker registry data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
Factoring Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Invoice Factoring Market