
 US Home Equity Lending Market | 2026-2036
US Home Equity Lending Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Equity Lending Market Analytics
Qualified mortgage certification under the Consumer Financial Protection Bureau's Ability-to-Repay rule is collapsing the field of eligible originators, forcing smaller regional lenders to retool compliance infrastructure or exit. Bank of America Corporation leverages its balance sheet depth to sustain jumbo home equity offerings across high-cost coastal metros. U.S. Bank anchors its position through branch-dense presence in Midwestern markets where relationship banking still dominates customer acquisition. PNC Financial Services Group competes on digital pre-qualification speed, reducing application-to-funding intervals below industry norms.
US Home Equity Lending denotes secured consumer credit instruments collateralized by residential real estate equity, typically structured as closed-end installment loans or open-end revolving lines with loan-to-value ratios capped between eighty and ninety percent depending on lien position and borrower credit profile. These products finance property improvements, debt consolidation, education expenses, or liquidity events while preserving existing first-mortgage terms. Home Equity Lines of Credit command the largest share of origination volume due to their draw-period flexibility and interest-only payment structures, though fixed-rate Home Equity Loans are gaining share among borrowers seeking payment certainty amid rate volatility. Cash-Out Refinancing has contracted as a share of total equity extraction as homeowners resist surrendering sub-four percent first mortgages originated during prior refinancing waves.
The Consumer Financial Protection Bureau enforces Truth-in-Lending Act disclosure requirements and qualified mortgage standards that dictate debt-to-income thresholds and fee limitations for covered loans. The Federal Reserve's Regulation Z implements annual percentage rate accuracy rules and right-of-rescission periods that shape product design and marketing timelines. State-level usury ceilings and licensing regimes administered by banking commissioners in Texas, Florida, and California create additional compliance layers that fragment national product templates. Stakeholders must monitor pending Basel III endgame proposals that could alter risk-weighted capital treatment of home equity exposures and reshape lender appetite for this asset class.
Market Dynamics
The Consumer Financial Protection Bureau's qualified mortgage rules are compressing the origination field while homeowners with sub-four percent first mortgages resist cash-out refinancing, locking equity extraction into second-lien products.
Growth Catalysts
- Sun Belt Property Appreciation:Suburban homeowners in Texas and Florida are tapping accumulated equity for renovation projects, expanding draw volumes on revolving credit lines.
- Digital Pre-Qualification Infrastructure:Automated valuation models and real-time income verification are collapsing application-to-funding intervals below traditional branch-based timelines.
- Basel III Risk-Weight Calibration:Proposed revisions to capital treatment for home equity exposures are prompting regional banks to optimize retained portfolio strategies ahead of implementation.
Market Restraints
- Interest Rate Volatility:Federal Reserve policy uncertainty is compressing net interest margins on floating-rate home equity lines of credit, constraining lender profitability.
- Regional Lender Consolidation:Compliance infrastructure costs under the Ability-to-Repay rule are forcing smaller originators to exit or sell to larger balance-sheet institutions.
- First-Lien Rate Lock-In:Borrowers with mortgages originated during prior refinancing waves are resisting any product that disturbs existing sub-four percent terms.
Strategic Opportunities
- Midwestern Relationship Banking:Branch-dense presence in Ohio and Michigan markets remains underpenetrated by digital-first competitors, preserving acquisition economics for incumbents.
- Fixed-Rate Installment Conversion:Borrowers seeking payment certainty amid rate volatility are shifting preference from revolving lines toward closed-end home equity loans.
- High-Cost Coastal Jumbo Segments:Metropolitan statistical areas in California and New York retain underserved demand for super-conforming equity products beyond agency limits.
Industry Challenges
- Valuation Model Accuracy:Automated valuation model drift in rapidly appreciating Sun Belt submarkets is creating collateral risk assessment gaps between desktop and full appraisal outcomes.
- Legacy Core System Integration:Regional lenders attempting real-time digital pre-qualification face middleware bottlenecks connecting modern front-end interfaces to decades-old loan origination platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Equity Lending Market |
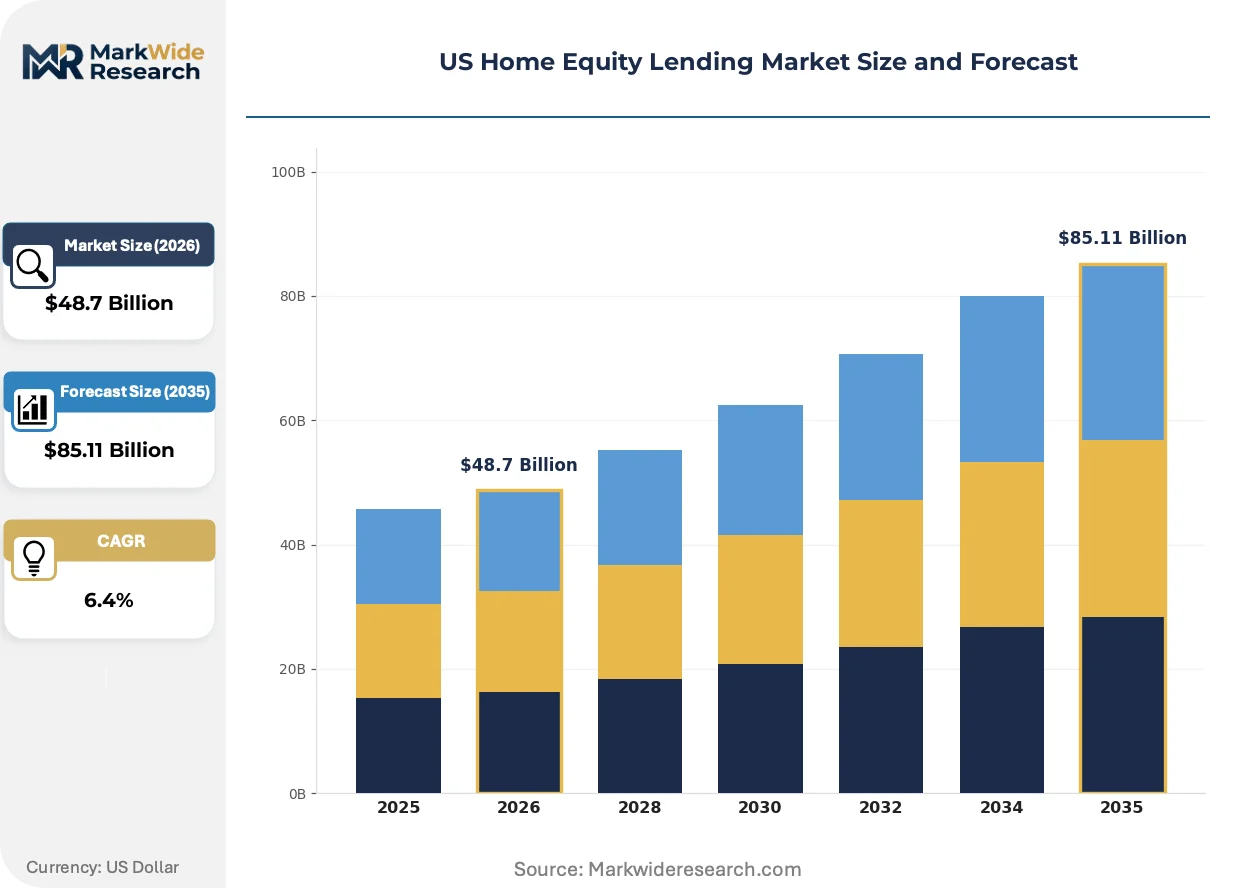
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Equity Loans, Home Equity Lines of Credit, Cash-Out Refinancing, Reverse Mortgages Customer Type: First-Time Borrowers, Homeowners, Investors, Retirees Loan Term: Short-Term, Medium-Term, Long-Term, Flexible Term Interest Rate Type: Fixed Rate, Variable Rate, Discounted Rate, Prime Rate |
| Companies Covered | Bank of America Corporation, U.S. Bank, PNC Financial Services Group, Truist Financial Corp., Figure Technologies Inc., Discover Bank, LoanDepot LLC, Spring EQ LLC, Point, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Equity Lending Market Evolving Landscape
Origination technology is compressing decision timelines while regulatory disclosure requirements reshape product marketing. Borrower preference is hardening around payment certainty structures.
Automated valuation models combined with alternative credit data are collapsing collateral assessment cycles from weeks to hours. Suburban renovation borrowers in Texas and Florida are adopting these tools fastest. The technology is fragmenting geographic concentration of appraisal management companies, dispersing valuation work across distributed data networks rather than metropolitan vendor clusters.
The Consumer Financial Protection Bureau's revised Loan Estimate and Closing Disclosure timing rules are extending the right-of-rescission window for certain open-end products. Lenders are redesigning draw-period marketing materials to accommodate extended cancellation rights. Home equity line of credit originators in California and New York are absorbing the highest compliance adaptation costs due to state-level overlay requirements.
Fixed-rate installment preference is displacing interest-only revolving structures among debt-consolidation borrowers. Credit unions and regional banks are capturing this shift through product redesigns that emphasize payment predictability. The behavioral pivot is most visible in Midwestern markets where relationship banking still dominates customer acquisition and retention economics.
US Home Equity Lending Market Segmentation
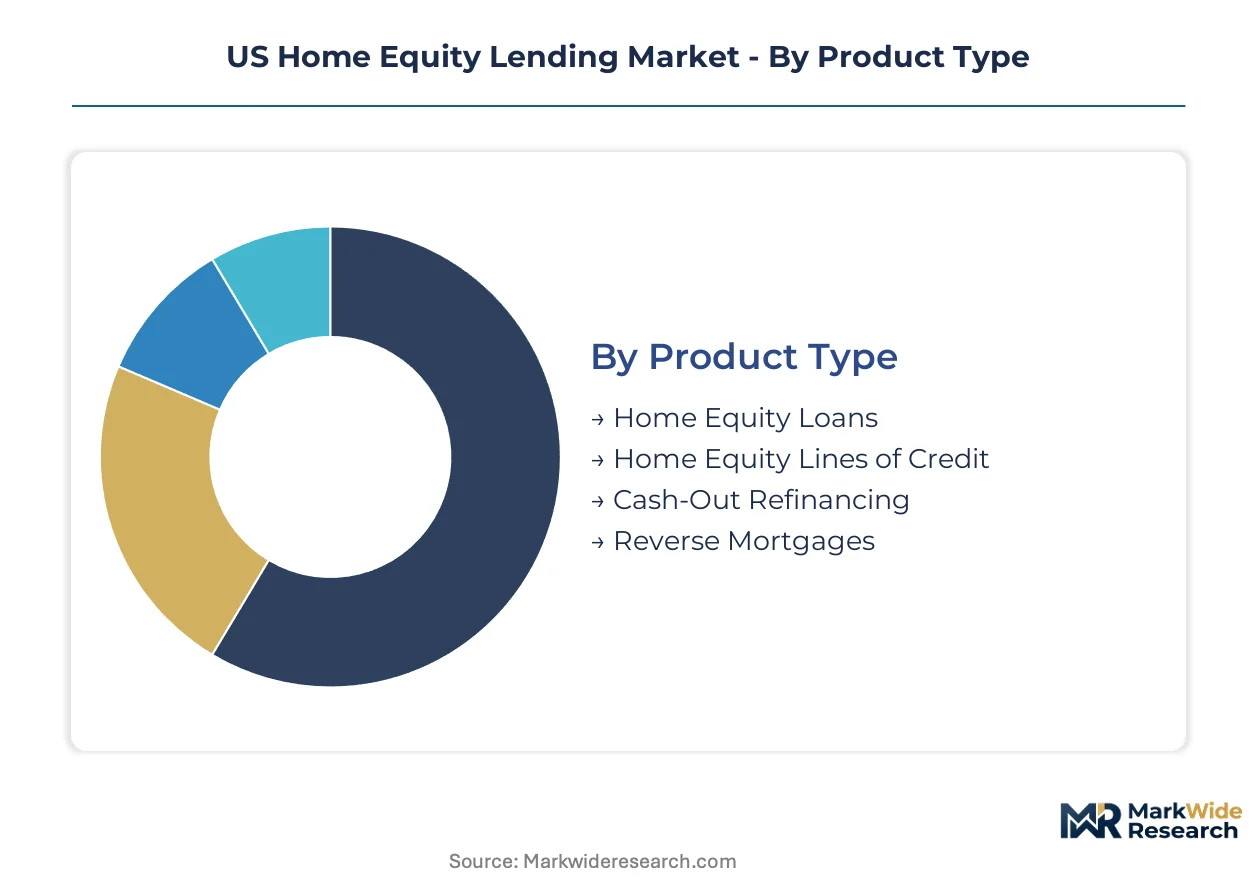
Product differentiation in home equity lending determines borrower acquisition costs and retention economics. Lenders structure offerings around payment certainty preferences, collateral position, and existing mortgage terms.
Product Type:
Cash-Out Refinancing faces the strongest substitution pressure as homeowners with sub-four percent first mortgages reject rate-reset products entirely.
- Home Equity Lines of Credit:Revolving structures with draw-period flexibility and interest-only payment options. Demand concentrates in Texas and Florida suburban markets where renovation spending is accelerating among property-rich homeowners.
- Home Equity Loans:Closed-end installment products with fixed amortization schedules. Borrowers in Midwestern states favor these instruments for debt consolidation where payment predictability outweighs draw flexibility.
- Cash-Out Refinancing:First-lien replacement products that reset entire mortgage terms. First-lien rate lock-in has collapsed origination volumes as homeowners preserve existing low-rate mortgages.
- Reverse Mortgages:Equity conversion instruments for borrowers aged sixty-two and older with no repayment obligation until property sale or death. Retirees in high-appreciation coastal metros utilize these for liquidity without disturbing investment portfolios.
Home Equity Lines of Credit retain volume leadership; Home Equity Loans hold the steepest expansion curve as fixed-rate preference hardens.
Customer Type:
Acquisition cost tiers separate relationship-banked homeowners from digitally-acquired first-time borrowers by a factor of three to five.
- Homeowners:Existing property holders with established equity positions and first-mortgage history. Sun Belt states dominate this segment where rapid appreciation has created substantial untapped collateral value.
- Investors:Non-owner-occupant borrowers leveraging rental property equity for portfolio expansion. Lenders apply stricter loan-to-value limits and higher rate spreads to compensate for default risk elevation.
- First-Time Borrowers:New entrants without prior home equity product experience. Digital pre-qualification platforms are collapsing friction for this cohort in branch-sparse Western markets.
- Retirees:Fixed-income households seeking liquidity without monthly payment burdens. Reverse mortgage specialization dominates this niche with counseling requirements extending decision timelines.
Homeowners command the largest origination share; Investors are climbing the fastest as rental property equity extraction accelerates.
Loan Term:
Duration preferences fragment along regional banking culture lines with relationship-heavy Midwestern markets favoring longer commitments.
- Long-Term:Ten-to-thirty year amortization structures minimizing monthly payment burdens. These instruments align with Midwestern relationship banking preferences where multi-decade customer ties are standard.
- Flexible Term:Draw-period-only repayment with balloon or conversion options at term end. HELOC originators in high-volatility rate environments promote these structures to preserve borrower flexibility.
- Medium-Term:Five-to-ten year installment products balancing payment affordability with total interest cost. Debt consolidation borrowers in suburban Texas markets select this duration for second-lien positioning behind low-rate first mortgages.
- Short-Term:Under-five year structures for bridge financing or rapid principal reduction. Investors utilize these instruments for property rehabilitation timelines before refinancing into permanent rental financing.
Long-Term products retain the deepest penetration; Flexible Term structures are gaining share fastest amid rate uncertainty.
Interest Rate Type:
Margin compression on floating-rate exposures is forcing lenders to steer volume toward fixed-rate products with superior yield stability.
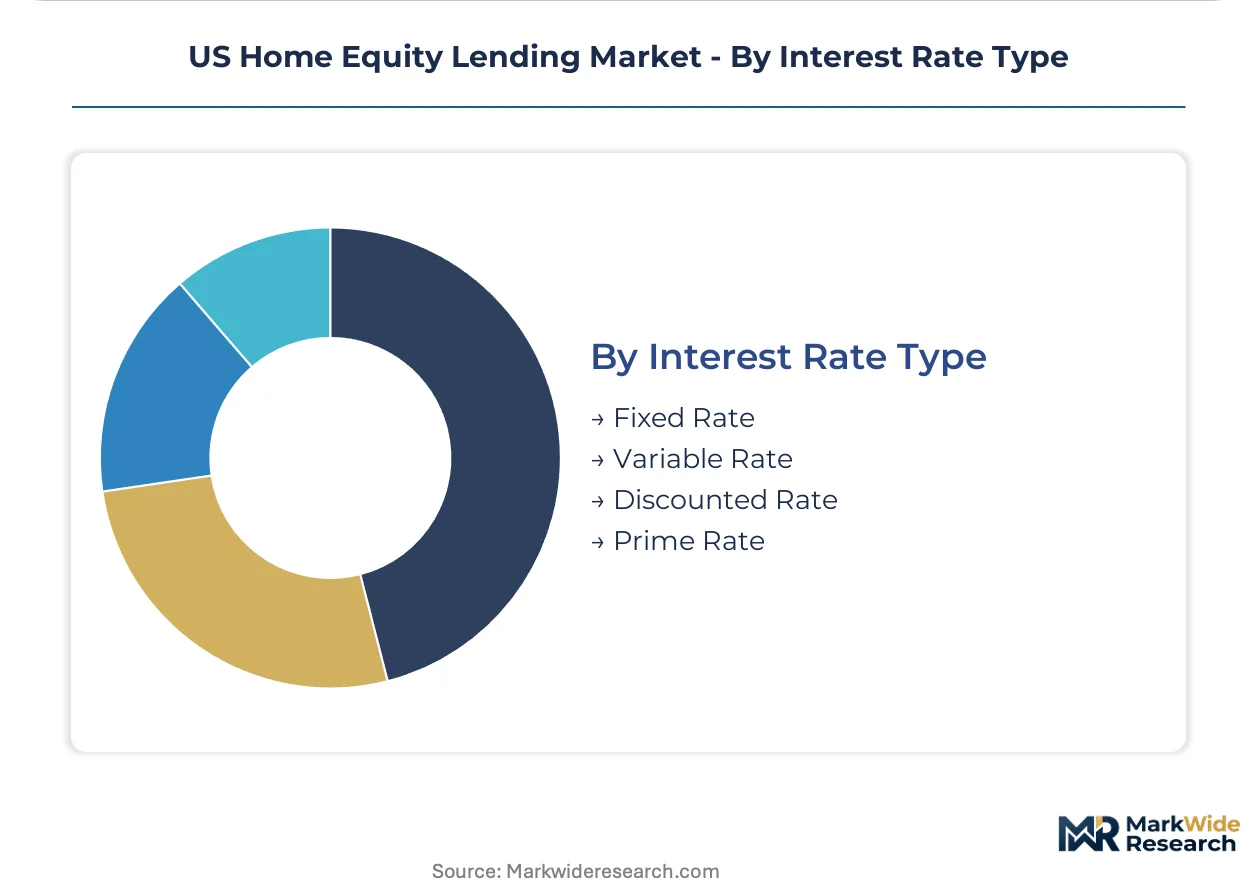
- Fixed Rate:Locked borrowing costs for the full instrument duration. Payment certainty demand has surged in Midwestern and Northeastern markets where household budgeting conservatism prevails.
- Variable Rate:Benchmark-indexed pricing that resets at defined intervals. Prime-rate-linked HELOCs in Federal Reserve tightening cycles have experienced payment shock that is accelerating conversion to fixed alternatives.
- Prime Rate:Direct Wall Street Journal prime index linkage without lender-specific spreads. Large national banks deploy this structure to compete on transparency in digitally-acquired customer segments.
- Discounted Rate:Introductory pricing that steps up to fully-indexed levels after initial periods. California and New York regulatory overlays now mandate enhanced disclosure of post-discount payment obligations.
Fixed Rate products dominate new origination preference; Variable Rate structures are contracting fastest as borrowers reject payment uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal tax incentives for energy-efficient home improvements are accelerating equity draw activity in jurisdictions with complementary state-level rebates. The Consumer Financial Protection Bureau's qualified mortgage rules apply uniformly, yet state licensing regimes create compliance fragmentation that advantages multi-state operators.
Texas
Suburban homeowners in Dallas-Fort Worth and Houston are tapping accumulated equity for renovation projects at accelerating rates. The Texas Finance Commission administers mortgage banker licensing with fee caps that limit origination cost recovery. Austin and San Antonio metro clusters are absorbing the highest concentration of digital-first HELOC originators deploying automated valuation models.
Florida
Rapid property appreciation across Tampa Bay and Orlando is creating substantial untapped collateral value among recent homebuyers. The Florida Office of Financial Regulation enforces additional disclosure requirements for open-end credit products beyond federal Truth-in-Lending Act baselines. Miami-Dade and Broward counties host the densest concentration of jumbo home equity specialists serving high-net-worth retirees.
California
Metropolitan statistical areas in Los Angeles and San Francisco retain underserved demand for super-conforming equity products beyond agency limits. The California Department of Financial Protection and Innovation mandates state-specific overlays on right-of-rescission periods that extend cancellation windows. San Diego and Sacramento submarkets are experiencing the fastest adoption of fixed-rate installment conversions from revolving HELOC structures.
New York
High-cost coastal borrowers are resisting cash-out refinancing to preserve sub-four percent first mortgages, locking demand into second-lien products. The New York Department of Financial Services imposes usury ceilings that constrain pricing flexibility on home equity loans. Long Island and Westchester County corridors concentrate relationship-banked homeowners with multi-decade institutional ties.
Ohio
Midwestern payment conservatism is driving preference for closed-end home equity loans with fixed amortization schedules. The Ohio Division of Financial Institutions coordinates with the CFPB on Ability-to-Repay rule enforcement while maintaining state-specific examination protocols. Cleveland and Columbus metro areas preserve acquisition economics for branch-dense incumbents where digital-first competitors remain underpenetrated.
US Home Equity Lending Market Competitive Landscape
Player mix skews toward balance-sheet-heavy diversified banks with compliance infrastructure depth to absorb regulatory fixed costs. National money-center institutions with jumbo lending capabilities occupy premium-tier positioning against regional relationship banks in Midwestern markets. Two strategic archetypes dominate: technology-enabled direct lenders collapsing application-to-funding intervals, and branch-network incumbents leveraging deposit-funded cost advantages. Competitive moves concentrate on digital pre-qualification infrastructure deployment and fixed-rate product redesign to capture payment-certainty demand.
Within the balance-sheet-dominant tier, Bank of America Corporation and U.S. Bank exemplify archetypes of national scale deployment against regional density concentration respectively. PNC Financial Services Group occupies a position bridging both vectors with digital acceleration layered atop legacy branch infrastructure. Among technology-native entrants, Figure Technologies Inc. represents the automated valuation and blockchain-secured documentation model that is compressing collateral assessment cycles from weeks to hours.
| Leading Market Players |
|---|
| Bank of America Corporation |
| U.S. Bank |
| PNC Financial Services Group |
| Truist Financial Corp. |
| Figure Technologies Inc. |
| Discover Bank |
| LoanDepot LLC |
| Spring EQ LLC |
| Point |
| Others |
Value Network & Pricing Analysis
Automated valuation model substitution for traditional appraisal workflows simultaneously disperses valuation work across distributed data networks and compresses collateral assessment economics from weeks to hours. This input replacement fragments geographic concentration of appraisal management companies while reshaping origination cost structures across regional and national lender tiers.
Pricing Analysis
Prime-rate-indexed cost-plus contracts with Wall Street Journal prime linkage dominate floating-rate home equity line pricing. Price differentiation hinges on borrower credit tier and lien position, with super-prime borrowers accessing spreads 50-75 basis points tighter than near-prime segments. Pricing pressure stems from Federal Reserve policy uncertainty compressing net interest margins on floating-rate exposures. First-time borrowers acquired through digital channels exhibit highest price sensitivity, while relationship-banked homeowners in Midwestern markets demonstrate lowest elasticity due to multi-decade institutional ties.
Supply Chain Analysis
The United States anchors loan origination platform development, while India and the Philippines host back-office processing and customer service operations for major lenders. Core system dependencies rest on legacy loan origination software, cloud infrastructure services, and automated valuation data feeds. Single-source vulnerability concentrates in appraisal management company networks serving Sun Belt submarkets where desktop valuation drift creates collateral risk gaps. Distribution runs through branch networks for relationship-banked segments and direct-to-consumer digital platforms for digitally-native borrower acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Home Equity Lending sits in early-cycle expansion as suburban renovation spending accelerates among property-rich Sun Belt homeowners with substantial untapped collateral value.
For Market Incumbents: Shield core deposit-funded cost advantages by deepening automated valuation model integration to collapse application-to-funding intervals below digital-native competitor benchmarks. Fortify Midwestern branch-dense positions where relationship banking economics remain insulated from technology-enabled entrants. Prioritize fixed-rate installment product redesign to capture payment-certainty demand shifting from revolving structures. For New Entrants and Emerging Players: CFPB Ability-to-Repay certification fast-tracks offer regulatory legitimacy without multi-year compliance infrastructure buildout. White-space concentrates in high-cost coastal jumbo segments where super-conforming demand exceeds agency limits and incumbent balance sheet constraints. Target digitally-acquired first-time borrowers in branch-sparse Western markets through automated pre-qualification platforms with real-time income verification. For Investors and Strategic Acquirers: Basel III endgame implementation reshapes the acquisition landscape by altering risk-weighted capital treatment of home equity exposures and forcing portfolio optimization decisions. Long-term viability favors regional lenders with existing compliance infrastructure depth and Sun Belt geographic concentration. Monitor automated valuation model accuracy divergence between desktop and full appraisal outcomes as signal for collateral risk reassessment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Pre-Qualification Platform Deployment | Automated valuation models compress application-to-funding intervals below traditional branch-based timelines. |
| Fixed-Rate Installment Product Redesign | Closed-end home equity loans capture payment-certainty demand shifting from revolving HELOC structures. |
| Midwestern Branch Network Expansion | Relationship banking economics in Ohio and Michigan preserve acquisition advantages against digital competitors. |
| Compliance Infrastructure Modernization | Ability-to-Repay rule adaptation separates viable originators from forced exit candidates. |
| Jumbo Home Equity Portfolio Buildout | Super-conforming products in California and New York metros address underserved high-net-worth demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with mortgage banking executives, loan origination platform engineers, regulatory compliance officers, and appraisal management company operators; and secondary validation through Home Mortgage Disclosure Act filings, Consumer Financial Protection Bureau enforcement actions, Federal Reserve senior loan officer opinion surveys, and state banking commissioner licensing databases. Bottom-up origination volume triangulation against top-down portfolio balance analysis anchored market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation, interest rate structure preference shifts, customer acquisition channel evolution, and regional property appreciation divergence. CAGRs derived from historical origination velocity patterns adjusted for Federal Reserve policy trajectory and first-lien rate lock-in persistence. Forecast inputs incorporated automated valuation model adoption curves and Basel III risk-weight calibration proposals.
Underlying assumptions cover Federal Reserve rate normalization path and Sun Belt property appreciation sustainability, with deviation risk concentrated in collateral valuation accuracy gaps and regional lender consolidation velocity. Recalibration cycles align with material shifts in qualified mortgage rule interpretation and automated valuation model regulatory guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Machinery Rental and Leasing Market