
 Global Automotive Rental and Leasing Market | 2026-2036
Global Automotive Rental and Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Rental and Leasing Market Analysis
The gap between premium mobility subscriptions and commodity daily rentals is repositioning capital allocation across the industry. Enterprise Holdings leverages its integrated fleet management platform to sustain density at major airport hubs. Hertz Global Holdings anchors its transformation through aggressive electrification of its rental pool. Avis Budget Group competes on price transparency while building digital-first booking infrastructure.
Automotive rental and leasing denotes the commercial provision of vehicle access through time-bound contracts, encompassing operating leases where the lessor retains ownership and residual risk alongside short-term rentals measured in hours or days. Fleet composition standards now mandate telematics integration for utilization tracking and predictive maintenance scheduling. SUVs and sedans dominate product type demand as corporate end users prioritize cabin space and fuel efficiency for executive travel. Online platforms capture the fastest-growing distribution channel as direct digital booking displaces intermediary-dependent procurement.
FDA vehicle safety guidelines inform telematics data handling in US-operated fleets, while EU Green Deal emissions targets and REACH chemical standards govern vehicle procurement and disposal protocols across European operations. EPA fuel economy regulations and NHTSA crashworthiness requirements shape model selection for US-based lessors, directly influencing manufacturer negotiations and residual value forecasting. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment competitive positioning across regional portfolios.
Market Dynamics
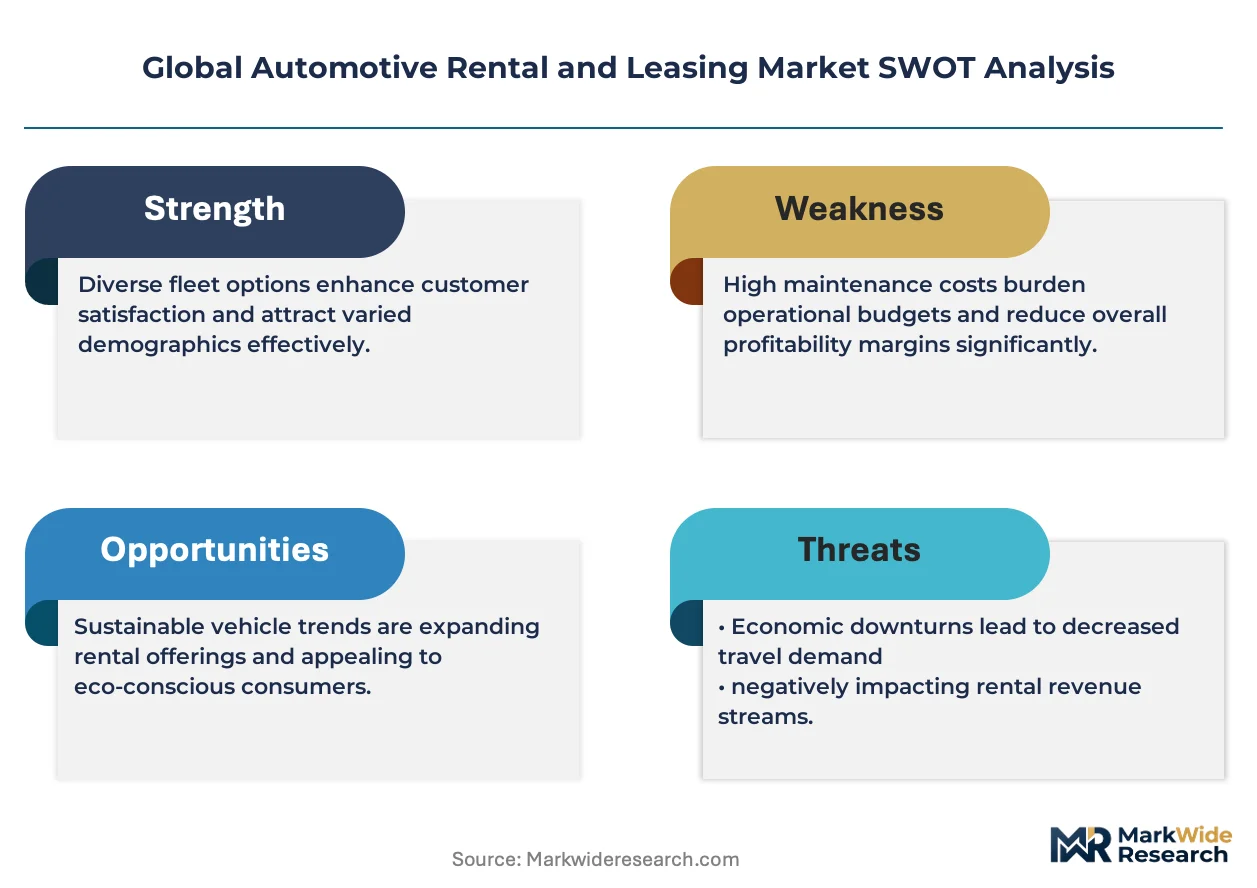
Fleet electrification mandates are compressing residual value forecasting horizons and forcing lessors to renegotiate manufacturer buyback terms across major markets.
Growth Catalysts
- EU Green Deal emissions targets:Binding fleet decarbonization timelines accelerate electrified vehicle procurement across European rental portfolios.
- Telematics integration:Real-time utilization tracking enables predictive maintenance scheduling and dynamic pricing algorithms for fleet operators.
- Corporate mobility policy tightening:Germany, the United States, and China impose stricter reporting requirements on business travel emissions.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cobalt and nickel compress electric vehicle lease margin structures.
- Charging infrastructure concentration:Dense networks cluster in Germany, the United States, and China, leaving secondary markets underserved.
- REACH chemical compliance:Extended disposal protocols for battery materials lengthen end-of-life vehicle processing cycles.
Strategic Opportunities
- India fleet electrification:PLI scheme subsidies for electric vehicle manufacturing create localized leasing entry points.
- Subscription-to-lease conversion:Premium mobility subscribers seek longer-term structures as usage patterns stabilize.
- ISO 14001 environmental certification:Verified sustainability credentials unlock corporate account procurement preferences.
Industry Challenges
- Residual value modeling:Accelerated technology obsolescence in electric powertrains complicates depreciation forecasting.
- Interoperability standards:Fragmented telematics protocols between manufacturers hinder unified fleet management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Rental and Leasing Market |
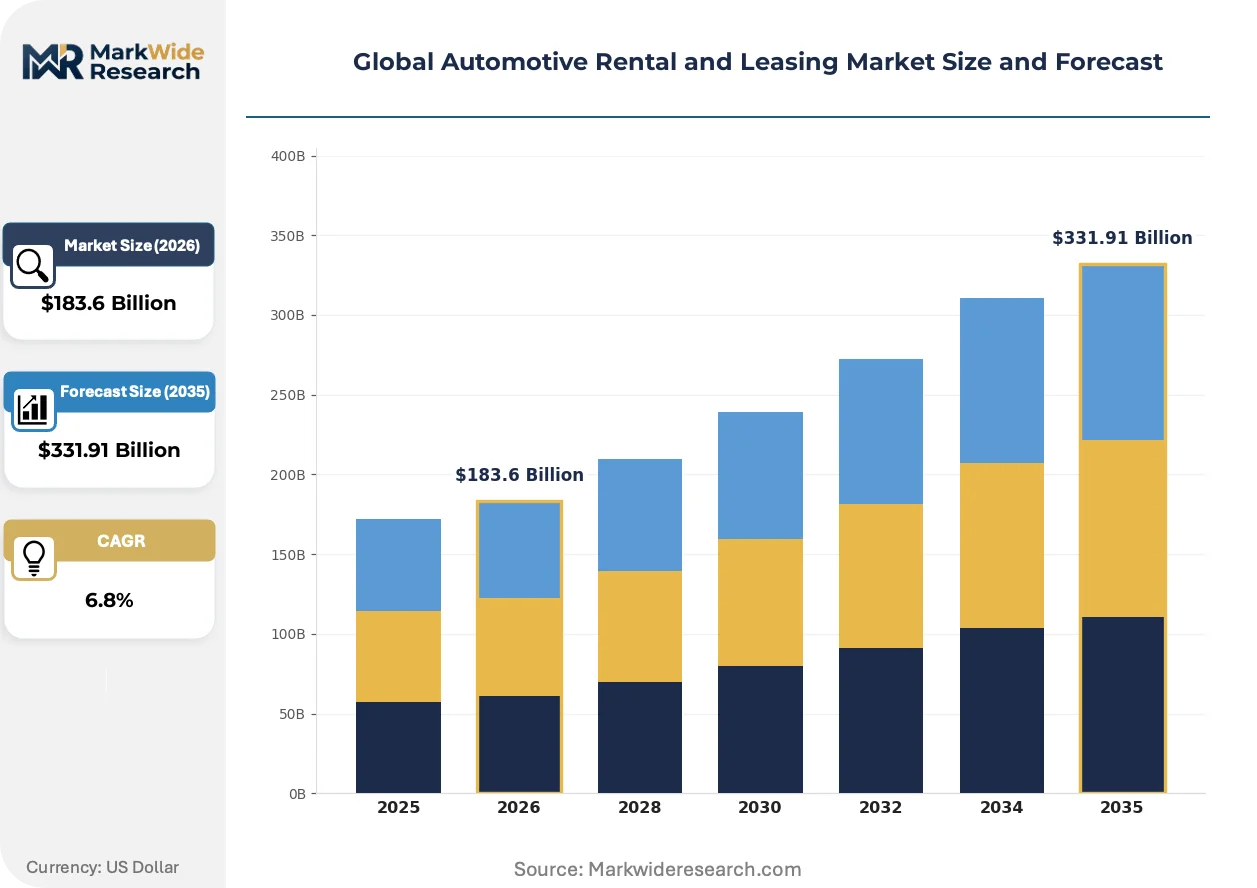
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $331.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SUVs, Sedans, Vans, Trucks Service Type: Short-term Rentals, Long-term Rentals, Leasing, Chauffeur Services End User: Corporate Clients, Individual Consumers, Tourists, Government Agencies Distribution Channel: Online Platforms, Travel Agencies, Direct Sales, Rental Offices |
| Companies Covered | Enterprise Holdings, Hertz Global Holdings, Avis Budget Group, Europcar Mobility Group, Sixt SE, ALD Automotive, LeasePlan Corporation, Localiza, Arval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Rental and Leasing Market Emerging Trajectories
Digital-native booking infrastructure and embedded connectivity are collapsing traditional intermediation layers between fleet operators and end users.
Artificial intelligence-driven demand forecasting is absorbing historical utilization patterns, weather data, and event calendars to optimize fleet positioning. Airport-based operators deploy these tools to preempt vehicle shortages during peak travel windows. The technology is absorbing manual dispatch decisions into automated rebalancing algorithms.
EPA fuel economy regulations and NHTSA crashworthiness requirements are tightening model eligibility criteria for US-based lessors. Manufacturers must certify vehicles against combined standards before fleet procurement approval. Sedan and SUV segments face divergent compliance timelines, compressing product planning cycles.
Corporate procurement departments now mandate direct digital booking platforms over intermediary-dependent travel management systems. Fleet operators respond by building API-first reservation infrastructure. This behavioral shift concentrates contract negotiations with procurement officers rather than travel coordinators.
Global Automotive Rental and Leasing Market Segmentation
Fleet operators segment their offerings to match utilization patterns against residual value risk. Distinct contract structures, vehicle classes, and procurement channels each carry different margin profiles and capital intensity requirements.
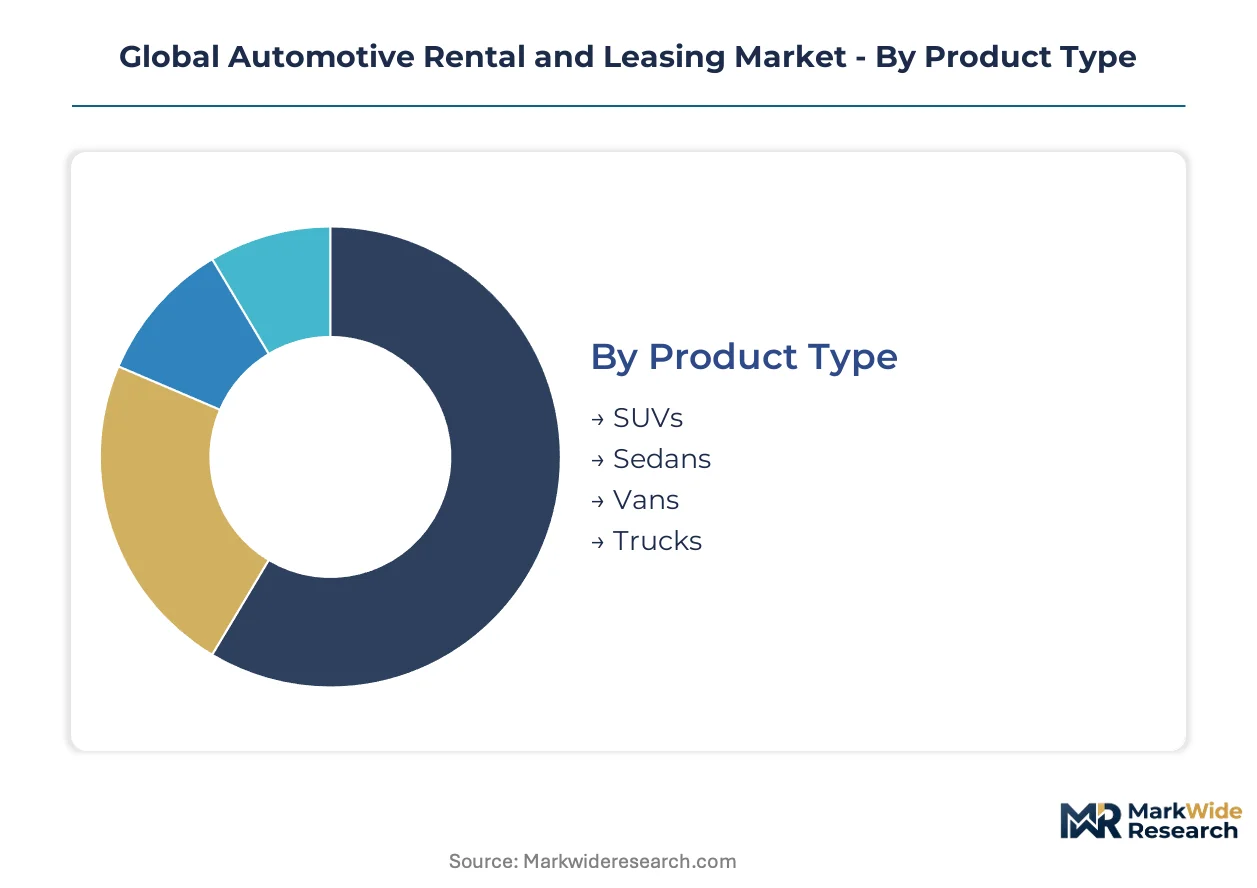
Product Type:
Vehicle replacement cycles vary dramatically across passenger and commercial categories, with electrification mandates compressing holding periods for certain powertrain configurations.
- SUVs:Higher ground clearance and flexible cargo capacity suit executive road transport and family leisure trips. Corporate fleet managers in Germany and the United States prioritize these models for their blended fuel efficiency ratings under EPA test cycles. Demand concentrates where charging infrastructure density supports heavier battery packs.
- Sedans:Lower aerodynamic drag and reduced curb weight deliver superior range per kilowatt-hour for electric powertrains. Urban corporate accounts in China specify sedans for intra-city executive transfers, with MIIT homologation standards influencing model availability.
- Vans:Box-section architecture supports last-mile logistics contracts and shuttle services. European lessors face EU Green Deal payload-range tradeoffs when electrifying these platforms.
- Trucks:Heavy-duty frames and towing capacity serve construction and freight brokerage customers. NHTSA brake performance standards govern fleet eligibility in US commercial applications.
Sedans sit at the top of the volume ranking, with SUVs climbing the fastest as corporate mobility policies expand cabin-size allowances.
Service Type:
Contract duration directly determines who carries residual value risk and how telematics data monetizes across the agreement lifecycle.
- Short-term Rentals:Hourly or daily access with full maintenance inclusion. Airport-based operators in the United States deploy dynamic pricing algorithms calibrated against TSA checkpoint throughput data.
- Long-term Rentals:Multi-month structures without ownership transfer. German corporate clients favor these for project-based workforce mobility under KBA registration protocols.
- Leasing:Operating contracts where lessors retain title and depreciation exposure. China’s MIIT new energy vehicle catalog influences eligible model lists for financial lease products.
- Chauffeur Services:Driver-supplied premium transport on fixed-route or hourly bases. UAE commercial licensing requirements through MOHAP govern operator certification in Dubai and Abu Dhabi.
Leasing commands the largest revenue pool, with short-term rentals expanding most quickly as digital booking infrastructure displaces intermediary layers.
End User:
Procurement authority and sustainability reporting obligations diverge sharply between institutional and individual customers.
- Corporate Clients:Fleet managers negotiate master service agreements with ISO 14001 certification requirements. CSRD disclosure mandates in Europe now scope business travel emissions.
- Individual Consumers:Price-sensitive leisure travelers book through comparison aggregators. Credit scoring integration varies by jurisdiction, with RBI guidelines shaping Indian lease underwriting.
- Tourists:Inbound visitors generate seasonal demand spikes at gateway airports. Visa-free access policies in Japan and South Korea concentrate volume at Narita and Incheon hubs.
- Government Agencies:Public procurement frameworks mandate domestic assembly content. PLI scheme compliance affects supplier selection for Indian federal vehicle contracts.
Corporate clients anchor contract value, with government agencies gaining share fastest as sovereign fleet electrification targets harden.
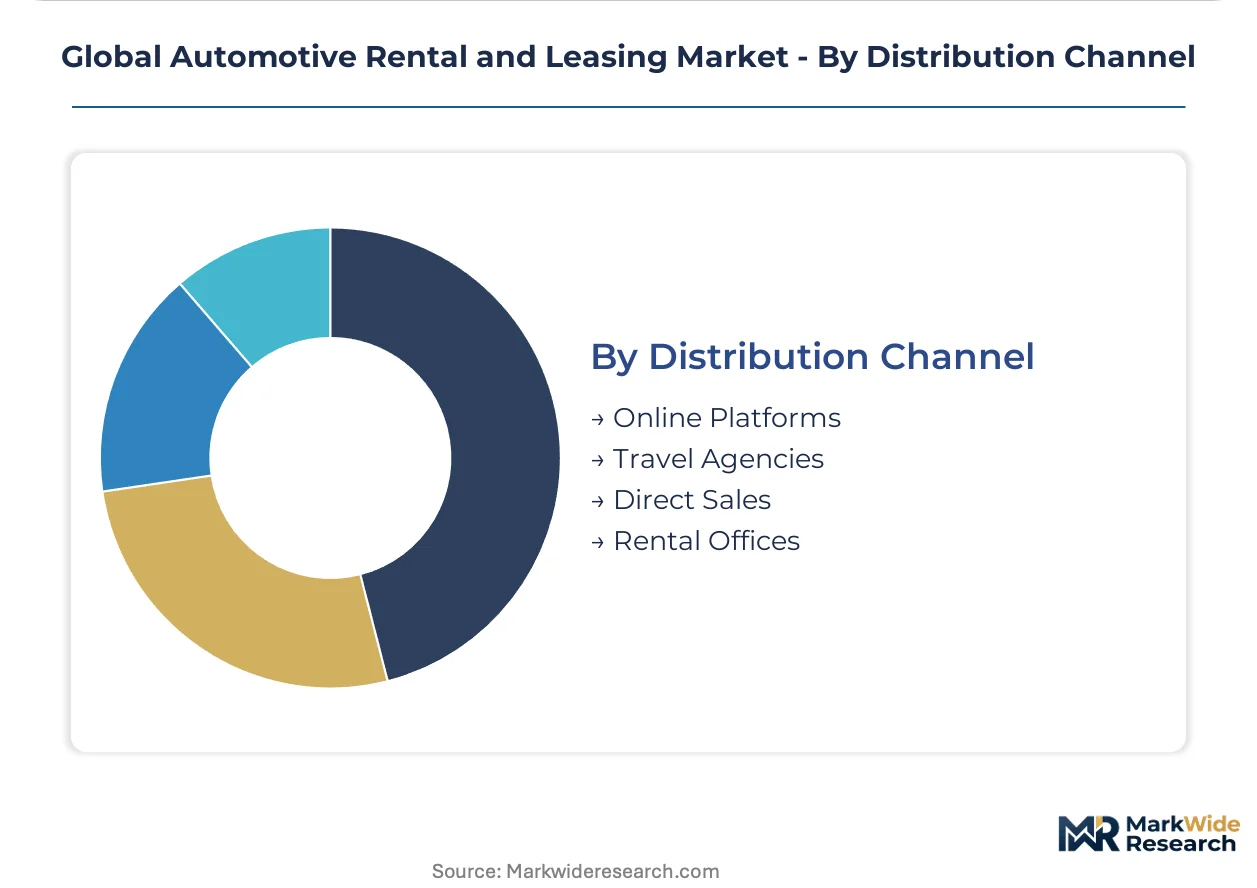
Distribution Channel:
Channel economics shift as direct digital booking captures procurement authority from travel management intermediaries.
- Online Platforms:API-first reservation systems integrate with corporate expense management software. GDPR data handling protocols govern EU customer profile storage.
- Travel Agencies:Consolidators negotiate block capacity at distressed rates. Commission structures compress as direct supplier relationships deepen.
- Direct Sales:Field representatives secure multi-year fleet contracts with telematics integration clauses. Relationship tenure correlates with renewal probability in commercial segments.
- Rental Offices:Walk-up transactions at airport and urban locations serve unplanned demand. Counter staffing models face automation pressure from kiosk and mobile check-in alternatives.
Online platforms lead transaction volume growth, with direct sales holding the steepest expansion trajectory among contract-based revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in fleet electrification velocity, with Chinese operators outpacing both in pure electric vehicle procurement volumes. Regulatory fragmentation across these three markets forces lessors to maintain parallel compliance architectures. Secondary markets in Brazil and India present contrasting infrastructure maturity profiles.
United States
Corporate fleet managers in the United States prioritize flexible leasing structures over ownership to manage residual value exposure. EPA fuel economy regulations and NHTSA crashworthiness requirements filter eligible models for fleet procurement. Airport hubs in Atlanta, Dallas-Fort Worth, and Los Angeles concentrate rental density where dynamic pricing algorithms optimize utilization.
Germany
German corporate mobility policies now mandate CO2 reporting for business travel under CSRD disclosure frameworks. KBA registration protocols govern operating lease structures while EU Green Deal timelines accelerate electrified fleet turnover. The Rhine-Ruhr corridor and Munich metropolitan area host the densest charging infrastructure networks for commercial leasing operations.
China
Chinese fleet operators leverage MIIT new energy vehicle catalog eligibility to structure financial lease products around domestic EV brands. Dual carbon goals at the national level cascade into municipal procurement mandates across tier-one cities. The Yangtze River Delta and Pearl River Delta clusters dominate leasing volume as charging infrastructure scales ahead of corporate demand.
Brazil
Brazilian corporate clients drive long-term rental demand for project-based workforce mobility in construction and agribusiness sectors. ANVISA commercial licensing requirements shape operator certification for chauffeur services in São Paulo and Rio de Janeiro. Local fleet operators concentrate in southeastern industrial corridors where domestic assembly content satisfies federal procurement preferences.
India
Indian fleet electrification accelerates through PLI scheme subsidies for electric vehicle manufacturing and localized leasing entry points. RBI guidelines shape lease underwriting standards while BIS technical regulations govern telematics device certification. Maharashtra and Karnataka states concentrate leasing operations around Mumbai, Pune, and Bangalore technology corridors.
Global Automotive Rental and Leasing Market Vendor Landscape
Top-tier vendors anchor airport-based density and integrated fleet management platforms, while mid-tier specialists compete on regional coverage and price transparency. The market structure consolidates around three strategic archetypes: integrated multinational platforms, regional fleet specialists, and manufacturer-captive finance arms. Competitive moves concentrate on electrification partnerships and API-first booking infrastructure rather than traditional capacity expansion.
Within the integrated multinational tier, Enterprise Holdings, Hertz Global Holdings, and Avis Budget Group exemplify divergent strategic postures. Enterprise Holdings represents the airport-hub density archetype through its unified fleet management systems. Hertz Global Holdings occupies a position defined by aggressive fleet electrification commitments. Avis Budget Group anchors the price-transparency vector while building digital-first reservation infrastructure. These three structures illustrate how capital allocation splits between physical network density, technology transition, and digital channel development.
| Leading Market Players |
|---|
| Enterprise Holdings |
| Hertz Global Holdings |
| Avis Budget Group |
| Europcar Mobility Group |
| Sixt SE |
| ALD Automotive |
| LeasePlan Corporation |
| Localiza |
| Arval |
| Others |
Supply Flow & Price Mechanics
Captive fleet procurement through manufacturer-captive finance arms anchors both supply security and residual value pricing power across major leasing portfolios. Lessors leveraging direct OEM relationships command preferential model allocation and buyback guarantees that insulate pricing from spot-market volatility in Germany, the United States, and China.
Pricing Analysis
Capacity additions in China are reshaping price floors for electric vehicle lease products as domestic OEMs expand financial lease offerings. Three-tier pricing structure across premium chauffeur services, standard corporate leasing, and economy daily rentals reflects divergent telematics integration levels and maintenance bundling. Cost compression in the economy tier is intensifying because aggregator platforms consolidate booking volume and squeeze intermediary margins. Individual leisure travelers exhibit highest price sensitivity while corporate fleet managers prioritize ISO 14001 certification over rate minimization.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale procurement from OEMs under multi-year supply agreements with residual value guarantees. Manufacturing concentration in China, Germany, and Japan determines vehicle availability timelines for lessors operating across multiple jurisdictions. Battery cell supply draws from South Korean and Chinese producers, with semiconductor content resting on Taiwanese foundry output. Single-source vulnerability in lithium-ion cathode materials exposes lease margin structures to cobalt and nickel price swings. Distribution runs through port-centric vehicle processing centers before regional depot allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Automotive Rental and Leasing Market functions as a regulatory compounder where EU Green Deal emissions timelines and CSRD disclosure mandates harden electrification procurement requirements across corporate accounts.
For Market Incumbents: Hedge residual value exposure by renegotiating manufacturer buyback terms for electric powertrains before technology obsolescence accelerates depreciation schedules. Expand telematics integration capabilities to capture predictive maintenance revenue streams as fleet utilization tracking becomes standard contract language. Battery cost volatility represents the primary margin threat requiring active hedging through long-term supply agreements.
For New Entrants and Emerging Players: Secondary city corporate fleets in India present the most penetrable white-space target as PLI scheme subsidies localize electric vehicle manufacturing and leasing infrastructure. Project-based workforce mobility in Brazilian construction and agribusiness sectors offers contract entry points with lower competitive density than airport-based operations. API-first direct booking platforms unlock procurement bypass of established travel management intermediaries.
For Investors and Strategic Acquirers: Consolidation pressure builds where telematics platform interoperability remains fragmented across manufacturer protocols. Long-term viability favors operators with captive charging infrastructure partnerships and ISO 14001 certification density in corporate account portfolios. Acquisition targets should demonstrate proven residual value forecasting capabilities for electric powertrains. The signal to watch is MIIT catalog expansion velocity affecting China financial lease eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Partnership | Secures MIIT catalog eligibility and EU Green Deal compliance for corporate fleet mandates. |
| Telematics Platform Integration | Enables predictive maintenance scheduling under KBA and NHTSA data handling protocols. |
| Charging Infrastructure Partnership | Addresses infrastructure concentration gaps in secondary markets beyond Germany, US, and China. |
| ISO 14001 Certification Program | Unlocks CSRD-aligned corporate procurement preferences across European leasing operations. |
| API-First Booking Infrastructure | Captures direct digital procurement authority displacing travel management intermediaries. |
Methodological Framework
Direct dialogue with fleet procurement managers, OEM platform engineers, telematics integration specialists, and corporate mobility policy officers grounded qualitative assessment of contract structure evolution. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed lessors, and EU regulatory submissions under REACH and CSRD frameworks. Bottom-up fleet size estimates triangulated against top-down market value reconstructions.
Top-down macroeconomic drivers filtered through bottom-up segment granularity across vehicle class, propulsion architecture, contract duration, and regional regulatory cluster dimensions. CAGRs were derived from fitted trend extrapolation calibrated against historical utilization patterns and electrification mandate timelines. Forecast inputs incorporated charging infrastructure deployment trajectories and battery cost curve assumptions throughout the projection horizon.
Underlying measurement precision varies by segment; short-term rental volume carries tighter precision than emerging subscription-to-lease conversion categories. Forecasts incorporate assumptions regarding regulatory enforcement consistency and manufacturer buyback term availability that may require revision. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Car Leasing Market