
 Europe Car Loan Market | 2026-2036
Europe Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Car Loan Market Insights
Product bundling of insurance, maintenance, and residual-value guarantees into single monthly payments is shifting how fleet buyers evaluate total cost of ownership. Volkswagen Financial Services leverages captive finance integration to lock in repeat commercial customers across lease-purchase cycles. BNP Paribas Personal Finance competes through unsecured personal loan structures that bypass traditional dealer channels entirely. Santander Consumer Finance dominates Southern European markets with specialized used-vehicle financing products.
A car loan constitutes a secured or unsecured credit instrument collateralized by a motor vehicle, with interest rates indexed to Euribor or central bank policy rates plus risk-adjusted spreads, and tenures typically spanning 24 to 84 months to match asset depreciation curves. Fixed-rate products anchor the majority of outstanding European volume as borrowers seek payment predictability amid monetary policy volatility. Balloon payment structures concentrate margin pools in the premium vehicle segment where residual value engineering sustains lender profitability. Variable rate offerings attract rate-sensitive first-time buyers despite exposure to European Central Bank tightening cycles.
The European Banking Authority's consumer credit directives govern disclosure standards and affordability assessments, while the EU Green Deal's sustainable finance taxonomy redirects capital toward electric vehicle portfolios. National regulators including Germany's BaFin and France's ACPR enforce local conduct rules that shape origination practices and repossession timelines. Stakeholders must monitor how the EU AI Act's credit-scoring provisions reshape automated underwriting algorithms before implementation deadlines crystallize compliance costs.
Market Dynamics
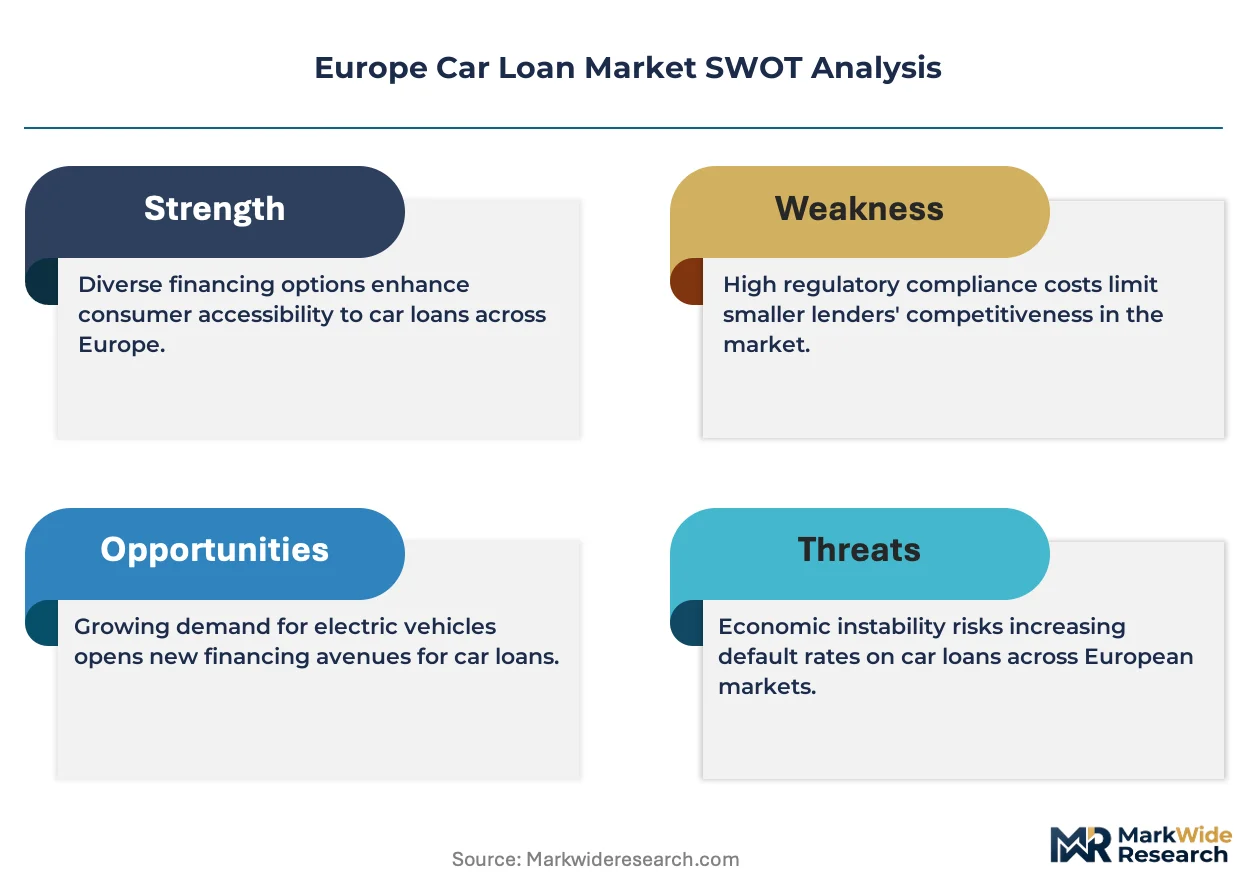
The EU Green Deal's vehicle emissions standards are compressing demand for internal combustion engine financing while channeling capital toward electrified fleet procurement. This regulatory pivot is restructuring lender portfolios, residual value models, and borrower eligibility criteria across the continent.
Growth Catalysts
- EU Green Deal taxonomy:The sustainable finance framework classifies electric vehicle loans as environmentally sustainable, unlocking preferential capital treatment for green auto portfolios.
- Fleet electrification mandates:Corporate fleet operators face binding CO2 reduction targets that accelerate replacement cycles and expand commercial vehicle financing demand.
- Berlin-Paris-Madrid corridor:Concentrated origination volume in these metropolitan clusters generates scale economies in underwriting and servicing infrastructure.
Market Restraints
- Euribor volatility:Variable-rate exposure in borrower portfolios creates margin compression when European Central Bank tightening cycles accelerate.
- Residual value uncertainty:Rapid battery technology obsolescence undermines collateral valuations for electric vehicle-backed loans.
- Dealer channel concentration:Captive finance arms of automotive OEMs lock in repeat commercial customers, constraining independent lender market access.
Strategic Opportunities
- Spain's used-vehicle financing gap:Southern European markets exhibit lower penetration of structured secondary-market lending products relative to Northern counterparts.
- Embedded insurance bundling:Integration of maintenance, warranty, and residual-value guarantees into single monthly payments creates differentiated value propositions for fleet buyers.
- EU AI Act credit-scoring provisions:Automated underwriting algorithm compliance creates first-mover advantages for lenders investing in explainable AI infrastructure ahead of implementation deadlines.
Industry Challenges
- Affordability assessment standardization:European Banking Authority disclosure requirements demand harmonized debt-service-to-income calculations across 27 national jurisdictions.
- Repossession timeline fragmentation:Germany's BaFin and France's ACPR enforce divergent conduct rules that complicate cross-border portfolio servicing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Car Loan Market |
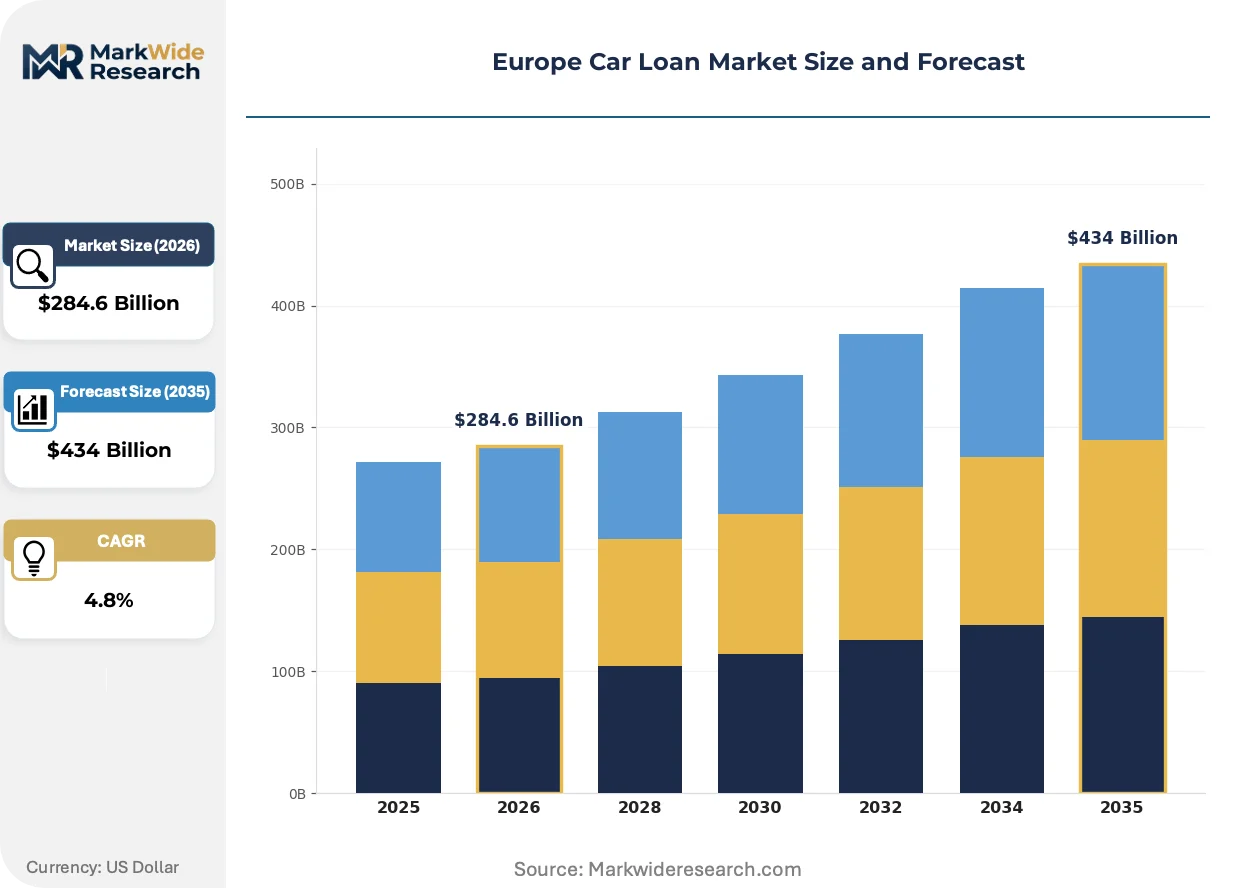
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $434 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Fixed Rate, Variable Rate, Balloon Payment, Lease Purchase Borrower Profile: First-Time Buyers, Professionals, Small Business Owners, Fleet Operators Loan Amount: Low Value, Medium Value, High Value, Premium Value Tenure: Short Term, Medium Term, Long Term, Extended |
| Companies Covered | Santander Consumer Finance, Volkswagen Financial Services, Stellantis Financial Services, BNP Paribas Personal Finance, Deutsche Bank, Mercedes-Benz Bank, BMW Financial Services, Volkswagen Bank GmbH, Commerzbank, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Car Loan Market Trends and Innovations
Digital origination platforms are compressing loan approval cycles from days to minutes while embedding alternative data streams into credit decisions. This technological shift is redistributing competitive advantage toward lenders with superior data infrastructure and automated underwriting capabilities.
Artificial intelligence-driven credit scoring is overtaking traditional bureau-dependent models in European auto lending. Fintech-enabled platforms deploy machine learning algorithms that analyze real-time cash flow patterns rather than static credit histories. Fleet operators with thin traditional credit files gain access to financing previously unavailable, expanding the addressable borrower base.
The EU AI Act's algorithmic transparency requirements are mandating explainable decision logic in automated lending systems. Lenders must document how AI models weight variables and provide adverse-action explanations to rejected applicants. German and French regulators are already interpreting these provisions through national conduct rule frameworks ahead of full harmonization.
Subscription-based vehicle access models are fragmenting traditional ownership patterns among urban consumers. Younger borrowers in Barcelona, Amsterdam, and Milan increasingly favor flexible-use contracts over fixed-term loans. This behavioral pivot pressures lenders to develop residual-value-sharing structures that align with mobility-as-a-service platform economics.
Europe Car Loan Market Segmentation
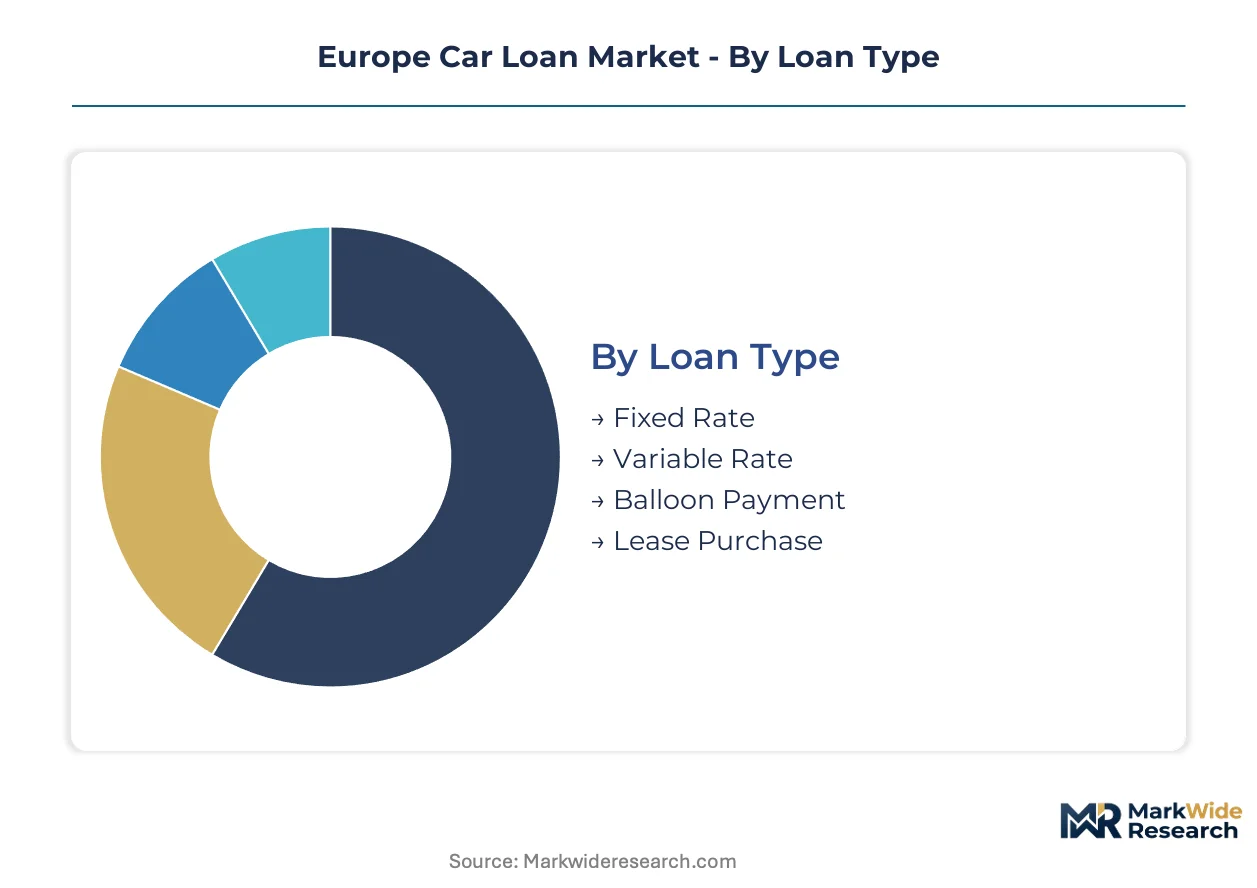
European car loan segmentation reveals distinct risk-return profiles across borrower types and product structures. Lenders calibrate pricing, collateral requirements, and servicing protocols to match each segment's depreciation curves and default probabilities.
Loan Type:
Borrowers select loan structures based on interest rate outlook certainty and residual value risk appetite.
- Fixed Rate:Interest rates lock at origination, shielding borrowers from European Central Bank tightening cycles. Payment predictability dominates volume in Germany and France where monetary policy volatility concerns household budgets.
- Variable Rate:Benchmarked to Euribor plus lender spreads, these products attract rate-sensitive first-time buyers in Spain and Italy. Margin compression risk concentrates in portfolios when ECB hiking cycles accelerate.
- Balloon Payment:Structures defer principal repayment to term-end, concentrating in premium vehicle segments where residual value engineering sustains lender profitability. Fleet operators in the Berlin-Paris corridor utilize these for commercial vehicle replacement cycles.
- Lease Purchase:Combines rental payments with ownership transfer options, embedding maintenance and warranty bundles. Captive finance arms dominate this structure through OEM dealer networks.
Volume sits with Fixed Rate products; growth tilts toward Balloon Payment structures as fleet electrification accelerates.
Borrower Profile:
Creditworthiness assessment protocols vary sharply across employment stability and fleet scale dimensions.
- First-Time Buyers:Thin credit file borrowers accessing sub-€20,000 loans through automated underwriting platforms. Fintech-enabled scoring in Barcelona and Milan expands approval rates using real-time cash flow analysis rather than bureau histories.
- Professionals:Salaried employees with documented income streams qualify for preferential rates through employer partnership programs. BNP Paribas and Santander compete for this segment via direct-to-consumer digital channels bypassing dealers.
- Small Business Owners:Self-employed borrowers face heightened documentation requirements under European Banking Authority affordability rules. Revenue verification complexity constrains origination velocity relative to salaried segments.
- Fleet Operators:Corporate buyers procuring electrified commercial vehicles under EU Green Deal CO2 mandates. Volkswagen Financial Services locks in repeat customers across lease-purchase cycles through captive finance integration.
Volume sits with Professionals; growth tilts toward Fleet Operators as binding emissions targets accelerate replacement demand.
Loan Amount:
Collateral valuation precision determines pricing tiers across vehicle value bands.
- Low Value:Sub-€15,000 loans collateralized by used vehicles aged 3-7 years. Santander Consumer Finance dominates Southern European secondary markets with specialized depreciation modeling.
- Medium Value:€15,000-€35,000 range capturing mass-market new vehicle purchases. Standardized residual value tables from automotive data providers reduce underwriting friction.
- High Value:€35,000-€70,000 segment where German premium OEMs concentrate captive finance penetration. Balloon structures proliferate as borrowers prioritize cash flow over equity accumulation.
- Premium Value:Above-€70,000 loans requiring bespoke collateral monitoring and concierge servicing. Ultra-luxury brands deploy white-glove finance origination through dedicated relationship managers.
Volume sits with Medium Value; growth tilts toward High Value as battery-electric vehicle price premiums persist.
Tenure:
Duration selection aligns monthly obligations with asset utility periods and technological obsolescence risk.
- Short Term:24-36 month structures minimizing interest burden for cash-flush borrowers. Prepayment flexibility attracts professionals in Paris and Frankfurt seeking rapid equity buildup.
- Medium Term:37-60 month standard products matching mainstream vehicle warranty coverage. This tenure anchors European origination volume through dealer captive finance programs.
- Long Term:61-84 month extensions spreading payments as vehicle prices climb. Negative equity risk escalates when battery technology advances accelerate depreciation curves.
- Extended:Beyond-84 month structures emerging for commercial fleet assets with extended utility cycles. EU Green Deal taxonomy incentives favor longer tenures for electric vehicle collateral.
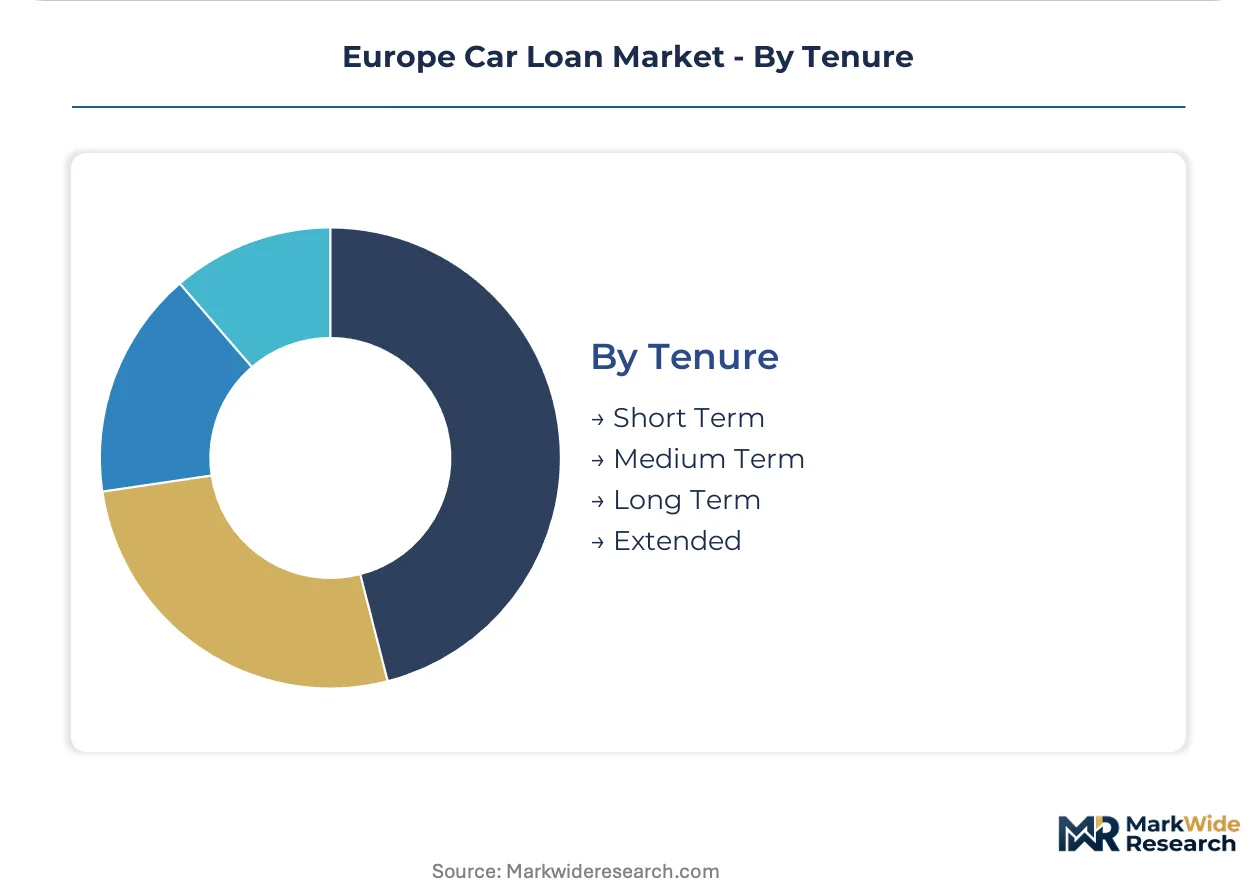
Volume sits with Medium Term; growth tilts toward Long Term as affordability pressures stretch payment schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin-Paris-Madrid corridor tax incentives for fleet electrification concentrate origination infrastructure. Germany's BaFin regulatory sandbox and France's ACPR green finance taxonomy accelerate capital deployment into sustainable auto portfolios. Metropolitan clusters generate underwriting scale economies.
Germany
Volkswagen Financial Services anchors captive finance penetration in Wolfsburg and Munich metropolitan zones. BaFin enforces stringent affordability assessment standards under European Banking Authority consumer credit directives. Berlin-Brandenburg corridor hosts dense electrified fleet procurement activity as corporate CO2 mandates tighten replacement cycles.
France
BNP Paribas Personal Finance competes through direct-to-consumer digital channels bypassing traditional dealer networks. ACPR conduct rules shape cross-border servicing protocols and repossession timelines. Île-de-France concentrates premium vehicle balloon structure origination where residual value engineering sustains lender profitability.
Spain
Santander Consumer Finance dominates Southern European used-vehicle financing with specialized secondary-market depreciation modeling. National conduct supervisors enforce local disclosure standards alongside EU Green Deal taxonomy alignment. Madrid and Barcelona metropolitan clusters exhibit expanding fintech-enabled automated underwriting for thin-credit-file borrowers.
Italy
Variable-rate products attract rate-sensitive first-time buyers in Milan and Rome despite Euribor volatility exposure. National banking regulators implement European Banking Authority harmonized debt-service-to-income calculations. Northern industrial zones concentrate small business owner financing demand with heightened documentation complexity under affordability rules.
Netherlands
Subscription-based vehicle access models fragment traditional ownership patterns among Amsterdam and Rotterdam urban consumers. Dutch financial regulators interpret EU AI Act credit-scoring provisions ahead of full harmonization. Randstad corridor lenders develop residual-value-sharing structures aligned with mobility-as-a-service platform economics.
Europe Car Loan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across origination channels. Captive finance arms of automotive OEMs lock in repeat commercial customers through integrated lease-purchase cycles. Independent banks compete via unsecured personal loan structures and direct digital distribution. Dominant competitive moves include strategic partnerships with mobility platforms and portfolio diversification into embedded insurance bundling.
Among Germany-based captive finance specialists, Volkswagen Financial Services, Mercedes-Benz Bank, and BMW Financial Services exemplify OEM-integrated origination models. These entities leverage dealer network control to sustain commercial customer retention across vehicle replacement cycles. BNP Paribas Personal Finance and Santander Consumer Finance represent independent banking archetypes competing through specialized product structures—unsecured direct lending and used-vehicle financing respectively. Deutsche Bank and Commerzbank occupy diversified universal bank positions with broader consumer credit portfolios extending beyond automotive collateral.
| Leading Market Players |
|---|
| Santander Consumer Finance |
| Volkswagen Financial Services |
| Stellantis Financial Services |
| BNP Paribas Personal Finance |
| Deutsche Bank |
| Mercedes-Benz Bank |
| BMW Financial Services |
| Volkswagen Bank GmbH |
| Commerzbank |
| Others |
Pricing and Supply Chain Analysis
Captive finance integration at Volkswagen Financial Services, Mercedes-Benz Bank, and BMW Financial Services anchors both supply-side origination capacity and pricing power across Germany and France. These vertically integrated structures compress dealer channel costs while embedding residual value guarantees that sustain premium pricing for balloon payment products.
Pricing Analysis
Short lead-time approvals command rate premiums in fleet operator segments where replacement cycle urgency compresses negotiation windows. Spot inventory financing for used vehicles in Spain and Italy carries discount pricing due to collateral depreciation uncertainty. The dominant structure remains contract-based long-term offtake through captive finance programs, with price differentiation resting on credit bureau tier and employer partnership status. First-time buyers in Barcelona and Milan exhibit highest price sensitivity, while premium vehicle borrowers in the Berlin-Paris corridor prioritize payment flexibility over rate minimization. Cost compression in variable-rate portfolios is intensifying because European Central Bank tightening cycles accelerate margin pressure.
Supply Chain Analysis
Workforce availability constraints in Germany, France, and Spain limit underwriting scale-up velocity despite digital platform deployment. Origination infrastructure concentrates in these three markets, drawing from automotive OEM dealer networks, fintech-enabled scoring platforms, and legacy banking branch systems. Key inputs include real-time cash flow data APIs, residual value forecasting engines from automotive data providers, and regulatory compliance software for EU AI Act alignment. Single-source vulnerability sits with proprietary scoring algorithms that lack explainable AI documentation. Distribution runs through captive finance dealer networks for new vehicles and direct digital channels for used-vehicle refinancing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Car Loan Market reads as a cost-of-compliance story where EU AI Act credit-scoring provisions erect barrier-to-entry moats for lenders with explainable AI infrastructure already deployed.
For Market Incumbents: Extend data infrastructure investments into explainable AI documentation systems ahead of full EU AI Act harmonization deadlines. Lock in residual value forecasting partnerships with battery technology assessors to mitigate electric vehicle collateral depreciation risk. Channel control through captive finance dealer networks remains the critical defensive lever against fintech-enabled direct lenders. For New Entrants and Emerging Players: Mobility-as-a-service platforms represent the most penetrable channel partner type for subscription-based vehicle access origination. White-space targets include Spain's used-vehicle financing gap and Netherlands residual-value-sharing structures for urban fleet operators. Direct digital origination bypassing dealer networks offers the clearest go-to-market angle against incumbent captives. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified banking conglomerates seeking auto loan portfolio diversification. Long-term viability favors lenders with compliant AI infrastructure and green auto portfolio concentration under EU Green Deal taxonomy. Watch battery technology depreciation curve acceleration as the critical inflection signal for residual value model reliability.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Infrastructure Deployment | EU AI Act compliance creates first-mover advantage against algorithm-dependent competitors in automated underwriting. |
| Green Auto Portfolio Expansion | EU Green Deal taxonomy classification unlocks preferential capital treatment for electric vehicle loan origination. |
| Embedded Insurance Bundling Integration | Volkswagen Financial Services leverages maintenance and warranty bundles to lock fleet operators across replacement cycles. |
| Direct Digital Channel Development | BNP Paribas Personal Finance bypasses dealer networks entirely through unsecured personal loan digital origination. |
| Residual Value Forecasting Partnership | Santander Consumer Finance dominates Southern European used-vehicle markets through specialized depreciation modeling. |
Research Methodology
Document review covered European Banking Authority consumer credit directives, EU Green Deal sustainable finance taxonomy filings, and national regulator conduct guidelines from Germany's BaFin and France's ACPR, complemented by interviews with captive finance executives, fintech platform operators, fleet procurement managers, and automotive dealer network heads. Secondary validation drew from ECB monetary policy disclosures, EU AI Act implementation drafts, and vehicle registration data from national transport authorities. Bottom-up origination volume estimates triangulated against top-down banking sector asset growth projections.
Cross-referencing historical loan origination patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include loan type structure, borrower employment profile, vehicle value tier, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for policy intervention effects. Industry-specific forecast inputs incorporated fleet electrification mandate timelines and residual value model reliability assessments for battery-electric collateral.
Caveats apply where European Central Bank rate trajectory shifts or battery technology obsolescence acceleration could materially shift the outlook beyond modeled scenarios. Forecasts reflect assumptions about regulatory implementation timing and borrower affordability stress thresholds. Material deviation in named triggers warrants pause and re-evaluation of portfolio concentration and origination velocity targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Alternative Financing Market