
 Global Fin Tech Blockchain Market | 2026-2036
Global Fin Tech Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fin Tech Blockchain Market Foresight
Software-defined compliance layers is recalibrating what financial institutions purchase rather than build in-house. IBM Corporation anchors enterprise blockchain deployments through its Hyperledger fabric specialization for clearing workflows. Ripple Labs Inc. competes on real-time gross settlement rails designed specifically for correspondent banking relationships. Microsoft Corporation extends cloud-native node infrastructure that reduces capital expenditure for retail banks entering the space.
Fin Tech Blockchain denotes cryptographically linked distributed ledger systems engineered for financial service workflows, typically employing consensus mechanisms such as proof-of-stake or Byzantine fault tolerance with sub-second finality parameters. Its primary commercial purpose centers on disintermediating settlement layers while preserving immutable audit trails for regulatory examination. Payments and clearing settlement platforms command the dominant margin pools given their transaction-volume economics and recurring infrastructure fees. Smart contracts within trade finance represent the fastest-expanding application segment as programmable escrow reduces documentary credit friction. Private blockchain deployments retain structural preference among investment firms and insurance underwriters prioritizing permissioned validator networks over public chain exposure.
The EU AI Act and MiCA framework impose algorithmic transparency and reserve-backing requirements on stablecoin-integrated payment gateways, directly shaping product architecture decisions. Singapore's Monetary Authority and the UAE's central bank digital currency pilots create divergent compliance baselines that vendors must navigate simultaneously. Stakeholders must monitor whether US SEC enforcement postures on tokenized securities harden into formal rulemaking or remain case-by-case, as this boundary determination will redirect capital between asset tokenization and pure payment infrastructure bets.
Market Dynamics
Cross-border payment corridors are absorbing enterprise-grade distributed ledger infrastructure at scale, forcing correspondent banks to reconfigure settlement architectures around sub-second finality parameters rather than legacy batch-processing windows.
Growth Catalysts
- MiCA framework:Europe's Markets in Crypto-Assets regulation imposes reserve-backing requirements on stablecoin-integrated payment gateways, accelerating institutional on-ramp demand for compliant infrastructure.
- Trade finance programmable escrow:Smart contracts within documentary credit workflows reduce friction in letter-of-credit processing, drawing commodity traders toward blockchain-based trade platforms.
- Singapore's regulatory sandbox:The Monetary Authority of Singapore's controlled testing environment permits live experimentation with retail payment tokens, concentrating vendor development resources in the city-state.
Market Restraints
- Validator network concentration:Permissioned blockchain deployments rely on a limited pool of accredited node operators, creating single-point-of-failure exposure in clearing workflows.
- Interoperability protocol gaps:Absence of unified messaging standards between Hyperledger Fabric, R3 Corda, and Ethereum enterprise variants forces costly middleware development.
- Energy input volatility:Proof-of-stake consensus mechanisms remain exposed to regional electricity price fluctuations, particularly affecting node operations in Germany and South Korea.
Strategic Opportunities
- UAE financial free zones:Dubai International Financial Centre and Abu Dhabi Global Market permit 100% foreign ownership of blockchain payment providers, attracting regional headquarters relocation.
- Central bank digital currency convergence:Integration of wholesale CBDC rails with private distributed ledger networks creates new settlement layer architectures for ASEAN corridor banks.
- Insurance parametric contracts:Oracle-fed smart contracts automating crop and catastrophe payouts represent an underpenetrated application segment with recurring premium economics.
Industry Challenges
- Cryptographic engineering scarcity:Zero-knowledge proof implementation and secure multi-party computation talent commands premium compensation, constraining product roadmap velocity.
- Legacy core banking integration:ISO 20022 message mapping between distributed ledger nodes and mainframe-based payment engines requires 18-24 month implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fin Tech Blockchain Market |
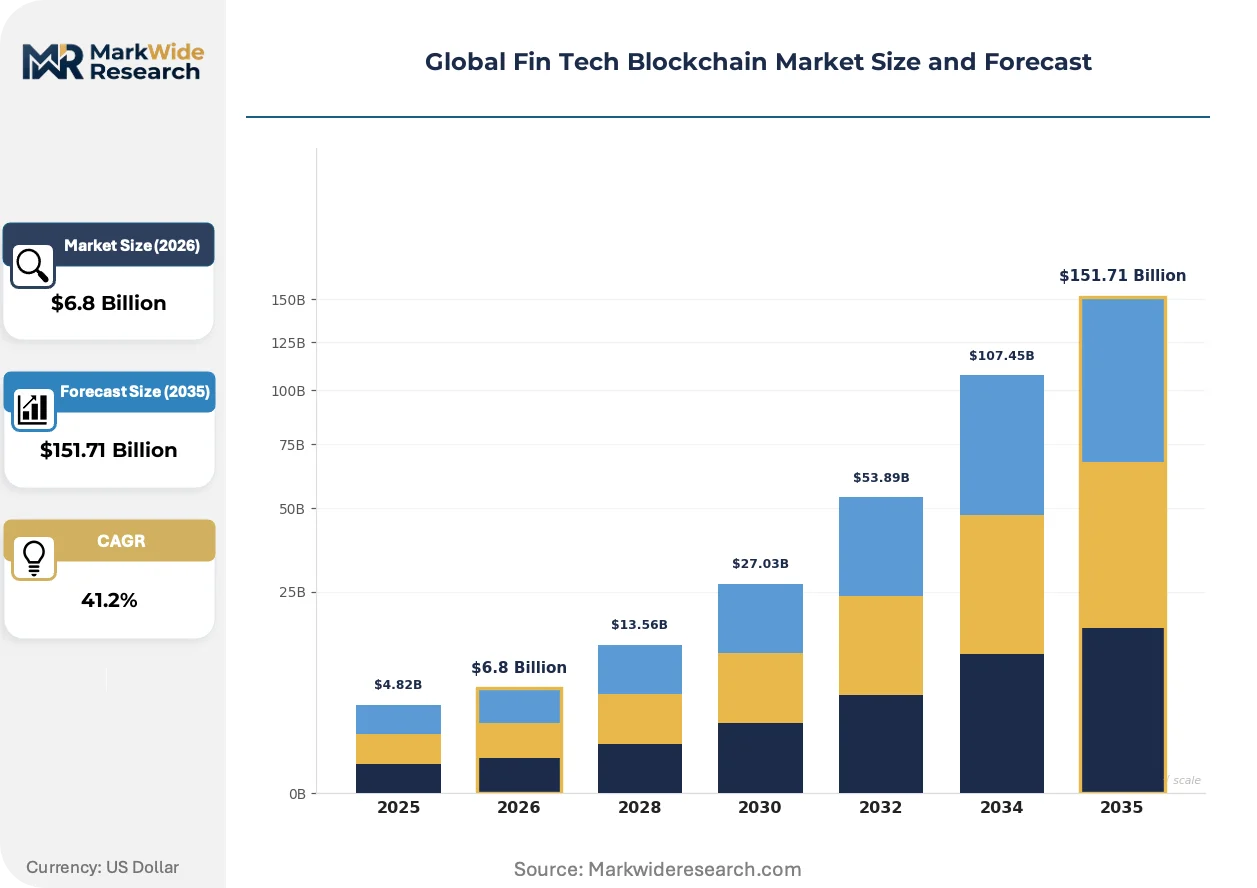
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $151.71 Billion |
| CAGR (2026 – 2036) | 41.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Payments, Digital Identity, Smart Contracts, Fraud Detection, Trade Finance, Compliance Management Deployment Model: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Solution Type: Wallets, Exchanges, Payment Gateways, Asset Tokenization, Clearing & Settlement Platforms, Regulatory Reporting End User: Retail Banks, Payment Processors, Insurance Firms, Investment Firms, Credit Unions |
| Companies Covered | Accenture PLC, AlphaPoint Corporation, Amazon Web Services Inc., Bitfury Group Limited, IBM Corporation, Microsoft Corporation, Oracle Corporation, Ripple Labs Inc., Digital Asset Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fin Tech Blockchain Market Shifts & Advancements
Software-defined compliance layers are recalibrating what financial institutions purchase versus build internally, compressing vendor evaluation cycles around pre-certified infrastructure stacks.
Zero-knowledge proof technology is decentralizing identity verification workflows by enabling credential validation without underlying data exposure. Swiss private banks and Luxembourg fund administrators are piloting ZK-KYC implementations for cross-border client onboarding. This architecture is decentralizing compliance cost structures away from centralized data repositories toward edge-verified credential ecosystems.
The EU AI Act imposes algorithmic transparency requirements on automated credit scoring and fraud detection modules embedded in blockchain payment gateways. Product teams must now document decision-tree logic for regulatory examination, extending development timelines by 4-6 months. Stablecoin issuers with EU payment institution licenses face the steepest compliance recalibration.
Correspondent banks are unbundling settlement infrastructure from proprietary technology stacks, procuring node-as-a-service offerings through cloud marketplaces rather than captive data center deployments. This procurement compression favors vendors with pre-integrated compliance modules. Singapore and UAE-based institutions lead this transition, driven by regulator-mandated sandbox graduation timelines.
Global Fin Tech Blockchain Market Segmentation
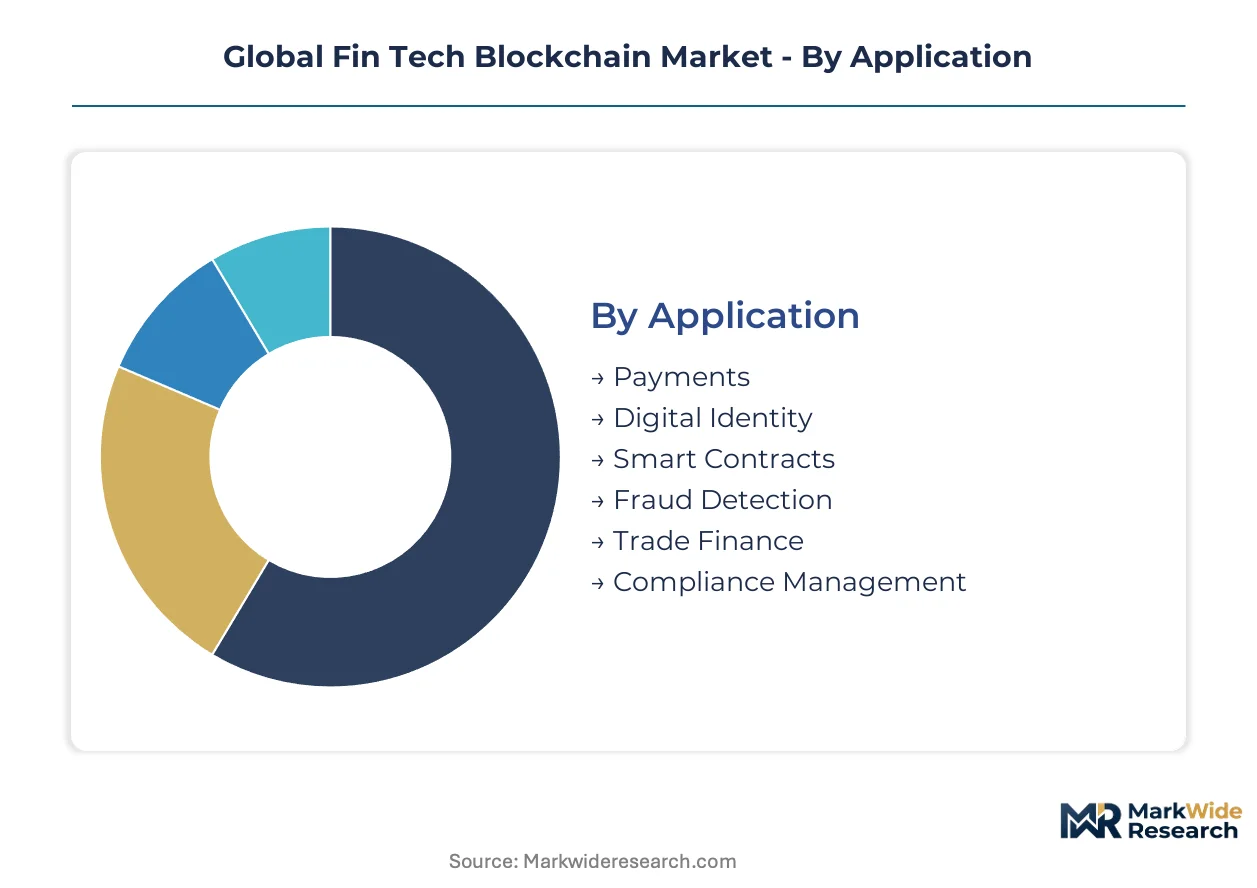
Fin Tech Blockchain vendors configure product roadmaps around four intersecting dimensions that determine pricing power and implementation complexity. Application focus dictates regulatory exposure, while deployment model selection locks in validator network economics. Solution type and end-user concentration together shape recurring revenue stability versus project-based income volatility.
Application:
Payments commands transaction-volume economics at scale, while trade finance delivers premium margins through programmable escrow complexity.
- Payments:Real-time gross settlement rails absorb the highest infrastructure deployment volume, with correspondent banks in Singapore and the UAE driving demand for sub-second finality parameters. Cross-border remittance corridors generate recurring network fees that amortize node infrastructure costs across high-velocity transaction pools.
- Trade Finance:Smart contracts within documentary credit workflows reduce letter-of-credit processing friction, drawing commodity traders toward blockchain-based platforms. Programmable escrow automates conditional release triggers, compressing settlement windows from weeks to hours.
- Smart Contracts:Self-executing agreements encode business logic directly on-chain, enabling automated compliance checks for insurance parametric payouts.
- Digital Identity:Decentralized credential verification supports KYC cost reduction for private banks managing cross-border client onboarding.
- Fraud Detection:Immutable audit trails enable pattern recognition across transaction histories, particularly valuable for retail banks monitoring synthetic identity schemes.
- Compliance Management:Automated regulatory reporting modules map distributed ledger outputs to MiCA and EU AI Act disclosure requirements.
Today's leader: Payments. Tomorrow's challenger: Trade Finance.
Deployment Model:
Permissioned architectures dominate institutional procurement, though hybrid configurations are gaining traction among ASEAN corridor banks seeking CBDC interoperability.
- Private Blockchain:Closed validator networks serve investment firms and insurance underwriters prioritizing controlled node accreditation over decentralization. Permissioned architectures limit counterparty exposure in clearing workflows while preserving immutable audit trails for regulatory examination.
- Consortium Blockchain:Multi-party governance structures enable correspondent banking coalitions to share infrastructure costs while maintaining bilateral confidentiality. R3 Corda and Hyperledger Fabric deployments concentrate in trade finance consortia led by European commodity traders.
- Public Blockchain:Open validator sets support retail payment token experiments within regulatory sandboxes, particularly Singapore's MAS-controlled testing environments.
- Hybrid Blockchain:Dual-layer architectures separate sensitive settlement data on private ledgers from transparency-optimized transaction hashes on public chains.
Private deployments anchor current procurement budgets; hybrid models are climbing the fastest as CBDC integration requirements mature.
Solution Type:
Infrastructure layers concentrate margin capture, while application-level solutions compete on implementation speed.
- Clearing & Settlement Platforms:Enterprise-grade node infrastructure commands the highest contract values, with cloud-native deployments reducing capital expenditure barriers for mid-tier retail banks. Sub-second finality parameters displace legacy batch-processing windows in correspondent banking relationships.
- Payment Gateways:Stablecoin-integrated on-ramps face steep MiCA reserve-backing requirements, reshaping product architecture toward fully collateralized settlement mechanisms. EU-licensed payment institutions lead compliance recalibration efforts.
- Asset Tokenization:Securities issuance infrastructure awaits SEC rulemaking clarity on tokenized instrument classification.
- Exchanges:Institutional-grade matching engines compete on custody insurance depth and cold-storage security certifications.
- Wallets:Multi-signature key management solutions target credit unions seeking retail member onboarding without core banking replacement.
- Regulatory Reporting:Automated disclosure modules map distributed ledger outputs to Singapore MAS and UAE central bank submission formats.
Infrastructure plays dominate current purchasing; tokenization infrastructure shows steepest expansion trajectory contingent on US regulatory resolution.
End User:
Payment processors drive volume-based pricing, while investment firms prioritize permissioned network control.
- Retail Banks:Correspondent institutions procure node-as-a-service offerings through cloud marketplaces, unbundling settlement infrastructure from captive data center deployments. Singapore and UAE-based institutions lead this procurement compression.
- Payment Processors:High-velocity transaction aggregators absorb the largest absolute infrastructure volume, with cross-border remittance specialists driving demand for real-time settlement rails.
- Investment Firms:Asset managers prioritize private blockchain deployments with accredited validator pools, limiting counterparty exposure in fund administration workflows.
- Insurance Firms:Underwriters pilot oracle-fed smart contracts for parametric crop and catastrophe coverage, automating payout triggers without claims adjustment overhead.
- Credit Unions:Member-owned institutions seek wallet and payment gateway solutions compatible with legacy core banking integration timelines.
Payment processors command current infrastructure absorption; insurance firms represent the most underpenetrated expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's regulatory sandbox attracts more vendor development resources than Germany's MiCA implementation timeline, yet both jurisdictions command disproportionate infrastructure deployment relative to their market size. The United States maintains the deepest correspondent banking network for blockchain settlement pilots. The United Arab Emirates leverages financial free zone autonomy to compress licensing timelines for payment providers.
United States
Correspondent banks in New York and Chicago drive demand for real-time gross settlement rails with sub-second finality. SEC enforcement postures on tokenized securities remain case-by-case rather than codified, redirecting capital toward pure payment infrastructure. The Chicago Mercantile Exchange cluster anchors enterprise node-as-a-service procurement for commodity clearing workflows.
Singapore
MAS-controlled testing environments permit live retail payment token experimentation, concentrating vendor engineering resources in the city-state. The Monetary Authority of Singapore's sandbox graduation timelines force institutions toward cloud-native node infrastructure. Raffles Place financial district hosts the densest concentration of blockchain payment gateway deployments in Southeast Asia.
Germany
MiCA reserve-backing requirements reshape stablecoin-integrated product architecture toward fully collateralized settlement mechanisms. BaFin licensing procedures for crypto custody create compliance bottlenecks that favor established payment institutions. Frankfurt's banking quarter anchors Hyperledger Fabric deployments for trade finance consortia led by commodity traders.
United Arab Emirates
Dubai International Financial Centre permits 100% foreign ownership of blockchain payment providers, accelerating regional headquarters relocation. The central bank's wholesale CBDC pilot creates settlement layer integration opportunities for private distributed ledger networks. Abu Dhabi Global Market competes with DIFC through accelerated licensing for institutional-grade custody providers.
Switzerland
Zurich and Geneva private banks pilot zero-knowledge proof KYC implementations for cross-border client onboarding. FINMA guidance on blockchain-based securities settlement enables tokenized asset infrastructure development. The Crypto Valley cluster in Zug anchors smart contract engineering talent for programmable escrow applications.
Global Fin Tech Blockchain Market Competitive Landscape
Top-tier vendors anchor enterprise clearing workflows, while mid-tier specialists compete on sandbox graduation speed and compliance module pre-certification. The vendor base stratifies across infrastructure layers, application stacks, and hybrid service bundles. Three archetypes dominate: cloud-native node providers, permissioned ledger fabric specialists, and stablecoin-integrated payment gateway operators. Strategic moves concentrate on M&A for cryptographic engineering talent and geographic expansion into UAE financial free zones.
Within the infrastructure tier, IBM Corporation and Microsoft Corporation occupy positions as anchors for enterprise deployments, with the former representing permissioned fabric specialization and the latter exemplifying cloud-native node economics. Amazon Web Services Inc. sits within the compute-layer vector, reducing capital expenditure barriers for mid-tier retail banks entering distributed ledger infrastructure. Ripple Labs Inc. anchors real-time gross settlement rails designed specifically for correspondent banking relationships, occupying a distinct position in cross-border payment corridor competition.
| Leading Market Players |
|---|
| Accenture PLC |
| AlphaPoint Corporation |
| Amazon Web Services Inc. |
| Bitfury Group Limited |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Ripple Labs Inc. |
| Digital Asset Holdings LLC |
| Others |
Supply & Pricing Matrix
Horizontal cloud marketplace integration anchors both supply positioning and pricing power for Fin Tech Blockchain infrastructure, as node-as-a-service procurement through AWS, Azure, and Google Cloud platforms compresses capital expenditure barriers while standardizing rate cards across retail bank buyers. This aggregation dynamic concentrates margin capture with hyperscale compute providers, forcing specialized ledger vendors toward compliance-module differentiation to defend price premiums.
Pricing Analysis
Capacity additions in Singapore and the UAE are reshaping price floors for enterprise node infrastructure, as regulatory sandbox graduation timelines compress procurement cycles toward pre-certified stacks. Three-tier pricing structure across premium, standard, and economy levels separates fully managed Hyperledger Fabric deployments from self-hosted open-source configurations and basic API access tiers. Price differentiation centers on MiCA pre-certification status and sub-second finality guarantees, with EU-licensed payment institutions showing lowest price sensitivity due to compliance-driven vendor stickiness, while ASEAN corridor banks drive hardest bargain on volume-based node pricing.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate validator node accreditation, filtering supply participation to established cloud infrastructure operators with audit-ready security postures. Hardware concentration rests on Taiwan and South Korea for specialized HSM modules, with Germany and Switzerland anchoring zero-knowledge proof cryptographic engineering talent pools. Supply chain risk centers on single-source vulnerability for FIPS 140-2 certified secure enclaves, particularly affecting permissioned deployments requiring hardware-backed key management. Distribution runs through cloud marketplace procurement channels, with direct enterprise sales retaining relevance only for bespoke trade finance consortium builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Fin Tech Blockchain Market operates as a regulatory compounder, where MiCA's reserve-backing requirements and the EU AI Act's algorithmic transparency mandates continuously escalate compliance infrastructure demand across correspondent banking networks.
For Market Incumbents: Hedge against validator network commoditization by deepening proprietary compliance layer development, particularly zero-knowledge proof implementations for cross-border KYC workflows. Secure cryptographic engineering talent through targeted acquisition in Switzerland's Crypto Valley cluster, as secure multi-party computation expertise commands premium compensation and constrains competitor roadmap velocity.
For New Entrants and Emerging Players: Zero-knowledge identity verification tooling offers the most penetrable wedge, with Swiss private banks and Luxembourg fund administrators actively piloting ZK-KYC implementations for cross-border client onboarding. Target insurance parametric contracts as the underpenetrated expansion pathway, leveraging oracle-fed smart contract architectures that automate crop and catastrophe payouts without legacy claims adjustment overhead.
For Investors and Strategic Acquirers: Roll-up economics work for compliance-module specialists because MiCA and EU AI Act disclosure requirements fragment vendor landscapes across divergent national implementation timelines. Long-term viability favors platforms with pre-integrated regulatory reporting capabilities spanning Singapore MAS, UAE central bank, and BaFin submission formats. The signal to watch is SEC rulemaking clarity on tokenized securities classification, which would redirect capital between asset tokenization infrastructure and pure payment rails.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CBDC interoperability with private distributed ledger networks creates new settlement architectures for ASEAN corridor banks. |
| Acquisition of Specialist Firm | Cryptographic engineering talent scarcity in zero-knowledge proof implementation constrains organic product roadmap velocity. |
| Strategic Partnership | Cloud marketplace listings through AWS and Azure reduce capital expenditure barriers for mid-tier retail bank procurement. |
| Geographic Expansion | Dubai International Financial Centre permits 100% foreign ownership, accelerating regional headquarters relocation timelines. |
| Product Launch | Software-defined compliance layers recalibrate build-versus-buy decisions toward pre-certified infrastructure stacks. |
Research Methodology
Bottom-up correspondent banking modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with CTOs at retail banks, platform engineers at node-as-a-service providers, regulatory affairs leads at stablecoin issuers, and integration specialists at trade finance consortia combined with secondary validation from SEC filings, MAS sandbox graduation announcements, EBA MiCA technical standards, and hyperscaler capex disclosures. Triangulation between demand-side procurement timelines and supply-side capacity expansion plans ensures dimensional consistency across segmentation outputs.
Input-output matrices map validator node deployment volumes to transaction fee economics across payments, trade finance, and CBDC integration use cases. Segmentation dimensions modeled include deployment model architecture, application workflow complexity, solution type infrastructure layer, and end-user institutional category. CAGRs derive from regression analysis against regulatory milestone timelines and sandbox graduation velocity. Industry-specific forecast inputs incorporate MiCA implementation phase transitions and wholesale CBDC pilot expansion trajectories.
The model holds under stable regulatory enforcement postures; deviation in SEC tokenized securities rulemaking or abrupt MiCA technical standard revisions would shift capital allocation between infrastructure segments. Forecasts reflect documented assumptions regarding sandbox graduation timelines and correspondent bank procurement compression rates. A model refresh is warranted upon material change in US SEC formal rulemaking posture or EU AI Act algorithmic transparency enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Asia-Pacific Neo Banking Market
FinTech
Transaction Monitoring Software Market
FinTech
Global Fundraising Software Market
FinTech
Europe Financial Analytics Market
FinTech
Global Fintech Market
FinTech
Finance Cloud Market
FinTech
Decentralized Finance Technology Market
FinTech
Supply Chain Finance Market
FinTech
Fintech Technologies Market
FinTech
India AI in Fintech Market
FinTech
Russia AI in Fintech Market
FinTech
Indonesia Financial Technology Services Market
FinTech
North America AI in Fintech Market
FinTech
China Fintech Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Artificial Intelligence (AI) in Fintech Market