
 Russia Auto Loan Market | 2026-2036
Russia Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Auto Loan Market Insights
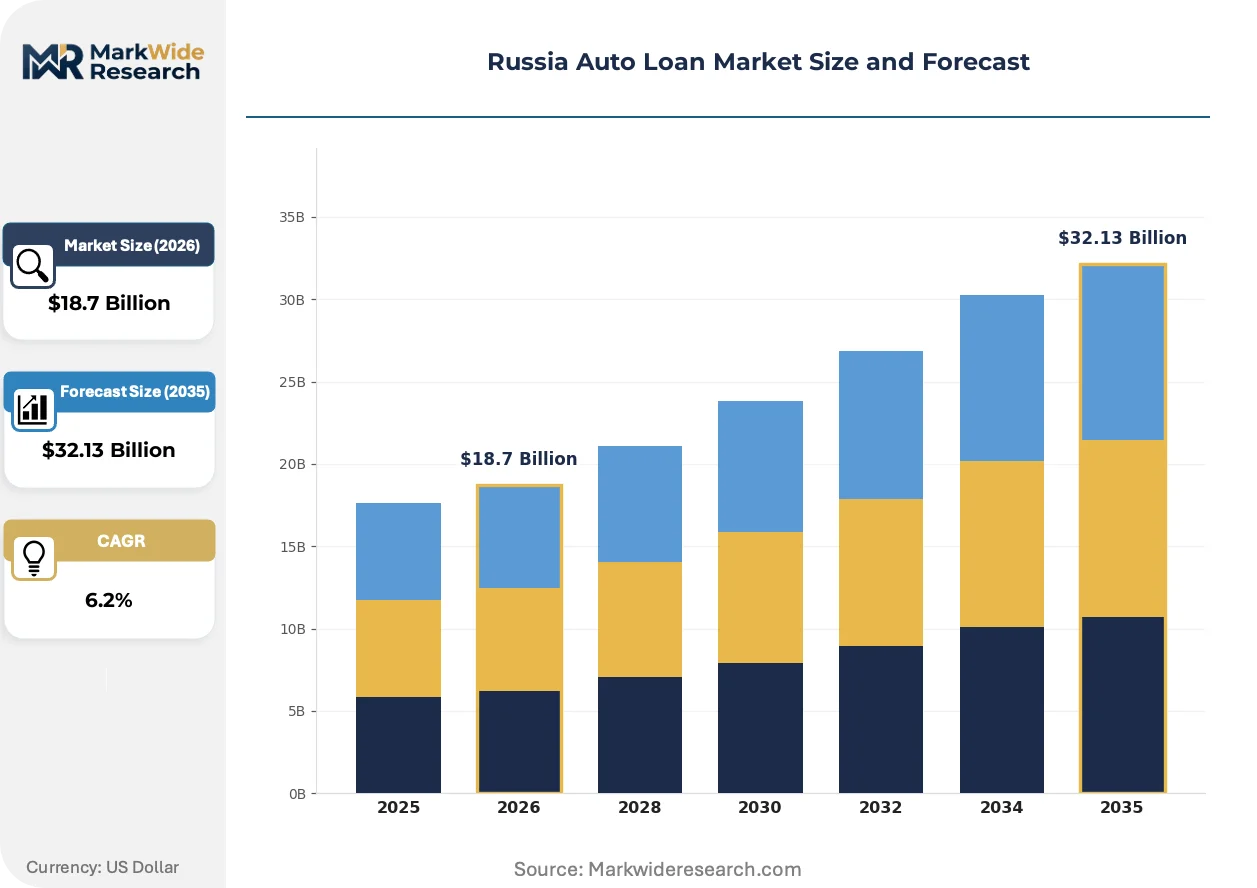
Multi-source funding partnerships between automakers and non-bank lenders is restructuring origination economics across Russia. Sberbank anchors retail auto lending through its branch network spanning over 14,000 points of presence. VTB Bank competes aggressively on used-car financing, leveraging state-backed capital advantages to undercut regional rivals. Gazprombank specializes in fleet and corporate lease structures, occupying the premium commercial segment with tailored residual-value products.
An auto loan constitutes a secured or unsecured credit instrument collateralized by a passenger or commercial vehicle, typically structured with fixed monthly payments over 24–84 month tenors and governed by Central Bank of Russia prudential norms on maximum debt-service-to-income thresholds. Its primary commercial purpose channels household and enterprise liquidity into durable goods acquisition while generating interest income and fee revenue for originating institutions. Secured loans dominate outstanding portfolio volume, reflecting borrower preference for rate advantages tied to collateralized structures and lender risk-mitigation requirements. Online platforms represent the fastest-expanding application channel, displacing branch-dependent origination as smartphone penetration and instant-scoring algorithms mature across borrower segments. Lease financing maintains concentrated margin pools within corporate and SME borrower profiles, where residual-value management and fleet administration services generate ancillary fee streams beyond pure interest spreads.
The Central Bank of Russia enforces macroprudential debt-burden limits and consumer-credit reporting standards that directly constrain maximum loan-to-value ratios and minimum down-payment thresholds for auto originations. BIS-aligned capital adequacy requirements and national GAAP provisioning rules shape lender balance-sheet capacity and pricing floors across the sector. Stakeholders must monitor regulatory calibration of unsecured lending caps and evolving electric-vehicle subsidy eligibility, as these parameters will determine which vehicle-type segments and borrower tiers remain economically viable for portfolio expansion.
Market Dynamics
Central Bank of Russia macroprudential tightening is compressing debt-service-to-income thresholds and forcing lenders to recalibrate underwriting algorithms across all borrower tiers. This regulatory pressure is restructuring origination economics and accelerating digital-channel migration.
Growth Catalysts
- Debt-to-income caps:Central Bank of Russia prudential limits on maximum debt-burden ratios are filtering out high-risk borrowers and improving portfolio quality metrics for compliant lenders.
- Smartphone penetration:Instant-scoring algorithms running on mobile platforms are collapsing application-to-disbursement timelines from days to minutes in regional cities.
- First-time buyers:Regional city households entering vehicle ownership are expanding origination volumes outside Moscow and Saint Petersburg saturation zones.
Market Restraints
- Collateral depreciation risk:Used-vehicle residual value volatility compresses secured-loan recovery rates during economic stress periods.
- Interest rate corridor:Central Bank of Russia policy rate swings transmit directly to auto-loan pricing floors, squeezing net interest margins.
- Documentation friction:GAAP provisioning rules and BIS-aligned capital adequacy requirements consume balance-sheet capacity for smaller regional banks.
Strategic Opportunities
- Electric-vehicle subsidies:Evolving eligibility criteria for state EV purchase incentives will determine which vehicle-type segments remain viable for portfolio expansion.
- Fleet lease structures:Corporate and SME borrowers generate ancillary fee streams through residual-value management and fleet administration services.
- Non-bank partnerships:Automaker-lender alliances are unlocking captive-finance economics and direct-to-consumer distribution channels.
Industry Challenges
- Algorithmic bias mitigation:Machine-learning credit models must satisfy Central Bank of Russia consumer-credit reporting standards and fair-lending scrutiny.
- Legacy system integration:Branch-dependent origination infrastructure requires costly retrofitting to support real-time digital underwriting pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Auto Loan Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Lease Financing, Personal Loans Borrower Profile: Individuals, SMEs, Corporates, Government Application Channel: Online Platforms, Dealerships, Banks, Credit Unions Vehicle Type: New Cars, Used Cars, Electric Vehicles, SUVs |
| Companies Covered | Gazprombank, Raiffeisenbank, Sberbank, Rosselkhozbank, Rosbank, VTB Bank, Unicredit Group, Credit Bank of Moscow, Alfa Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Auto Loan Market Trends and Innovations
Digital origination infrastructure is compressing decision timelines and displacing physical branch dependency across Russia's auto lending sector. Three concurrent shifts are restructuring competitive positioning.
API-based credit scoring is integrating alternative data sources—utility payments, mobile wallet histories, and e-commerce transaction patterns—into underwriting engines. Regional non-bank lenders are adopting these platforms fastest, leapfrogging legacy credit-bureau dependencies. This technology is integrating thin-file borrowers into formal credit markets previously excluded by traditional scoring methodologies.
Central Bank of Russia macroprudential requirements on maximum debt-service-to-income thresholds are tightening quarterly calibration cycles. Lenders must rebalance loan-to-value ratios and minimum down-payment structures to maintain compliance. The used-vehicle financing segment faces acute pressure as residual value uncertainty collides with stricter collateral coverage mandates.
Buyers in Russia's regional cities are migrating from dealership-floor negotiations toward smartphone-completed applications. Instant approval workflows and digital document submission are collapsing the traditional sales funnel. This behavioral pivot concentrates in Siberian and Volga Federal District urban centers where branch density remains lowest.
Russia Auto Loan Market Segmentation
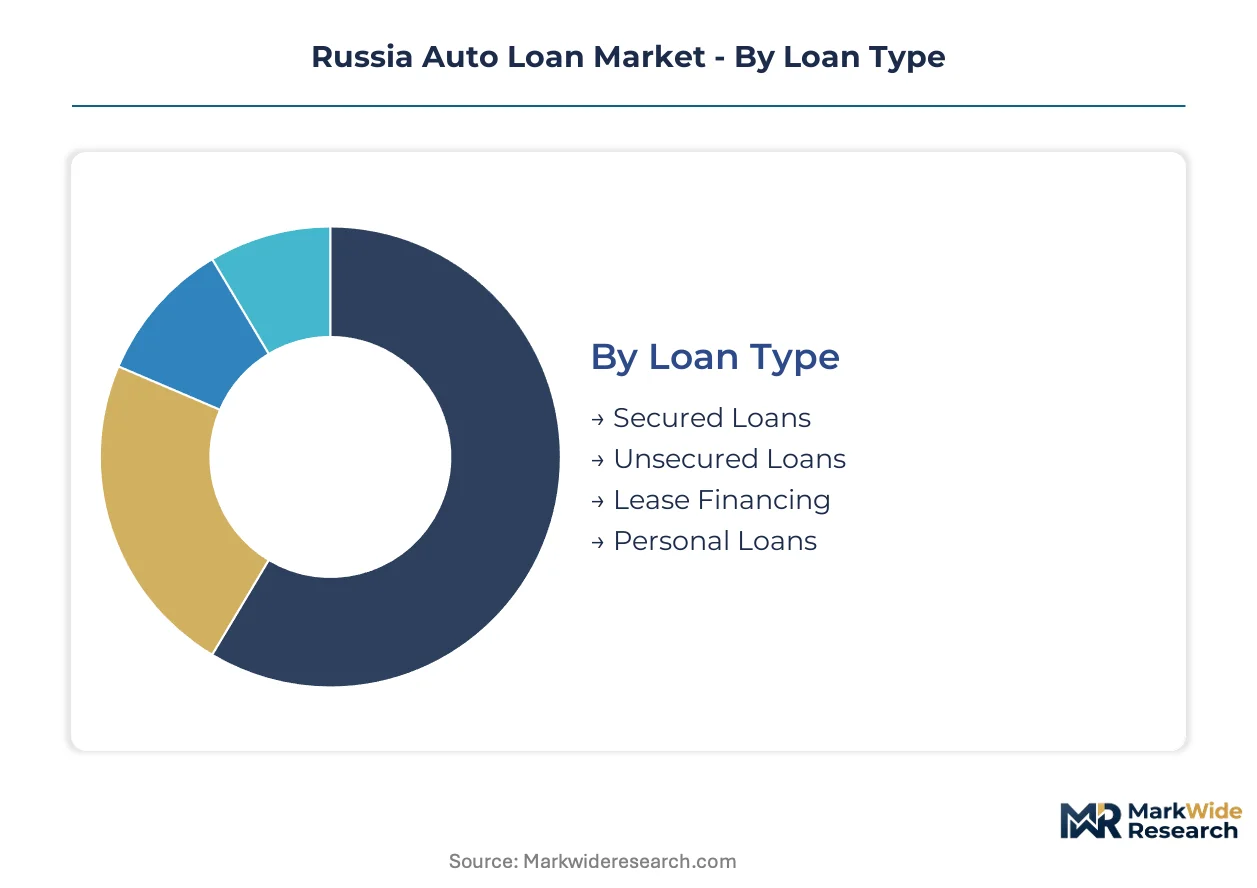
Russia's auto loan segmentation reveals how collateral structures, borrower risk profiles, and distribution channels allocate capital across vehicle acquisition pathways. Each dimension carries distinct regulatory treatment and margin economics that shape lender portfolio construction.
Loan Type:
Supply concentration in secured products reflects Central Bank of Russia collateral coverage mandates and lender risk-mitigation requirements.
- Secured Loans:Collateralized by vehicle title with fixed-asset registration through national notary systems. Demand clusters in Moscow and Saint Petersburg where dealership networks facilitate simultaneous purchase-financing workflows and residual value transparency supports loan-to-value calibration.
- Lease Financing:Structured around residual-value ownership transfer with monthly rental payments. Corporate fleet operators in the Ural Federal District favor this structure for tax depreciation advantages and off-balance-sheet treatment.
- Unsecured Loans:Signature-based credit without collateral attachment, carrying premium pricing to absorb default risk.
- Personal Loans:General-purpose consumer credit redirected toward vehicle acquisition outside formal auto-lending channels.
Today's leader: Secured Loans. Tomorrow's challenger: Lease Financing.
Borrower Profile:
Cost tier differentiation separates mass retail from commercial segments through documentation requirements and minimum exposure thresholds.
- Individuals:Retail borrowers accessing standard consumer credit frameworks with debt-service-to-income verification. First-time buyers in regional Siberian cities are expanding origination volumes as smartphone penetration enables remote application completion.
- SMEs:Small and medium enterprises financing commercial vehicle fleets through documented cash-flow underwriting. This segment generates ancillary fee streams through fleet administration and maintenance bundling.
- Corporates:Large enterprises with audited financials accessing bilateral credit facilities and master lease agreements.
- Government:Public sector procurement through tender-based vehicle acquisition with sovereign credit backing.
Volume concentration sits with Individuals. Margin expansion potential concentrates with SMEs.
Application Channel:
Digital infrastructure maturity is redistributing origination economics away from physical branch dependency.
- Online Platforms:API-integrated scoring engines processing instant approval workflows on mobile devices. Regional non-bank lenders in the Volga Federal District are adopting these platforms fastest, leapfrogging legacy credit-bureau dependencies.
- Dealerships:Captive-finance arrangements with manufacturer-affiliated lenders providing point-of-sale credit decisions. This channel maintains dominance in premium vehicle segments where negotiation complexity requires human intermediation.
- Banks:Branch-network origination through Sberbank's 14,000-point presence and VTB Bank's regional expansion.
- Credit Unions:Member-based cooperative lending with community-level underwriting discretion.
Dealerships anchor current volume. Online Platforms are climbing the fastest.
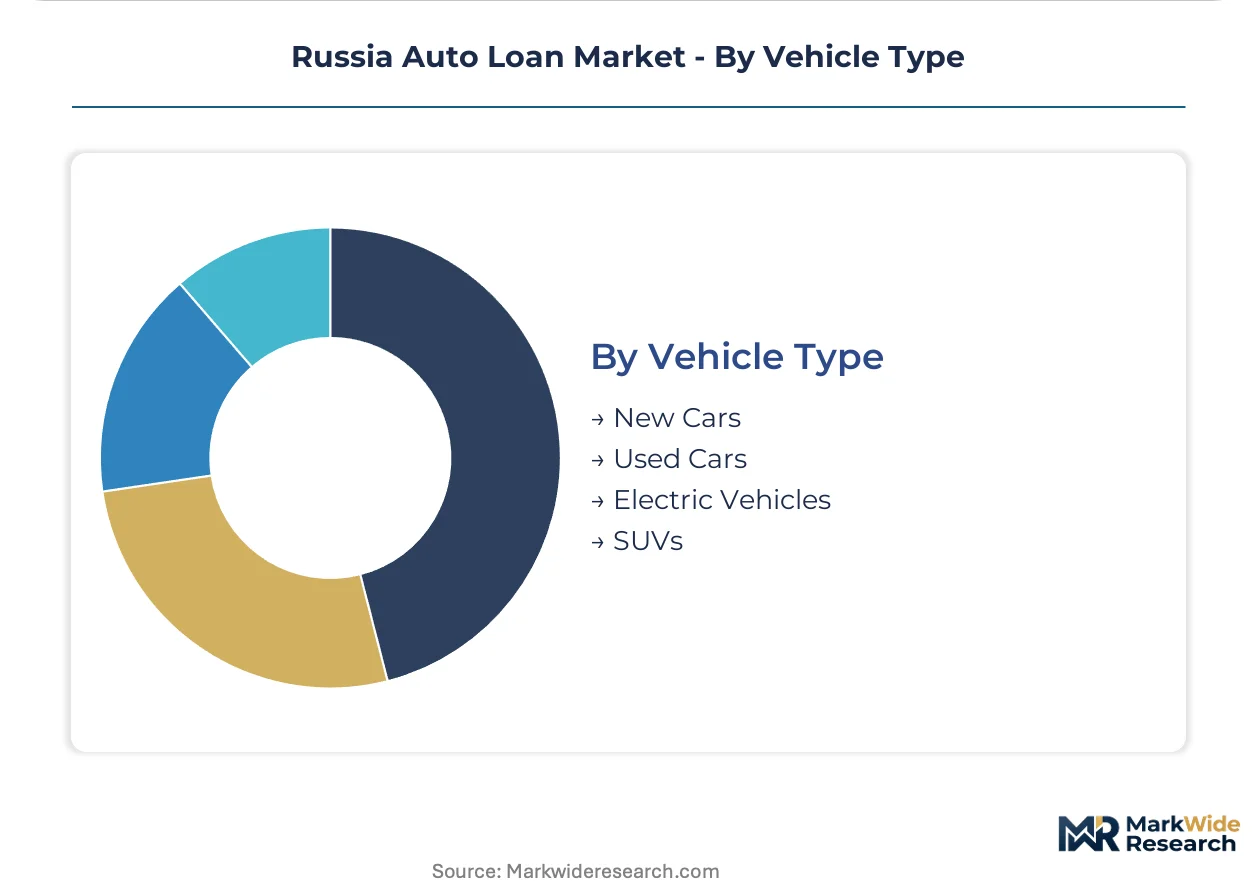
Vehicle Type:
Residual value stability and subsidy eligibility create divergent risk-return profiles across collateral categories.
- New Cars:Factory-warranty-backed collateral with predictable depreciation curves and manufacturer captive-finance support. Moscow and Saint Petersburg dealerships achieve deepest penetration here through brand-exclusive showrooms.
- Used Cars:Pre-owned vehicle financing with residual value uncertainty compressing loan-to-value ratios. VTB Bank competes aggressively in this segment, leveraging state-backed capital advantages to undercut regional rivals on pricing.
- Electric Vehicles:Battery-powered models eligible for evolving state purchase incentives. Subsidy eligibility criteria will determine which vehicle-type segments remain viable for portfolio expansion.
- SUVs:Sport utility vehicles commanding premium pricing and longer loan tenors in the mass market.
New Cars dominate outstanding balances. Electric Vehicles present the steepest expansion trajectory contingent on regulatory calibration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow anchors origination volume through dense dealership networks and digital platform penetration. Central Bank of Russia macroprudential requirements filter through regional banking subsidiaries with varying compliance capacity. The analysis examines five federal districts where auto lending concentrates.
Central Federal District
Moscow and the surrounding oblasts generate the highest per-capita origination rates through Sberbank's branch infrastructure and VTB Bank's digital channels. The Central Bank of Russia's debt-service-to-income thresholds bite hardest here given elevated household leverage ratios. Premium vehicle financing clusters in Moscow's brand-exclusive showrooms where captive-finance arrangements dominate.
Northwestern Federal District
Saint Petersburg drives volume through manufacturer-affiliated lenders and non-bank digital platforms targeting first-time buyers. Regional regulators enforce consumer-credit reporting standards that constrain algorithmic scoring models. The city's port logistics infrastructure supports commercial fleet leasing for Baltic trade corridor enterprises.
Volga Federal District
Kazan and Nizhny Novgorod exhibit the fastest digital-channel adoption among regional cities outside the two capitals. Smartphone-completed applications are collapsing traditional dealership-floor negotiations. Local non-bank lenders leapfrog legacy credit-bureau dependencies through API-based alternative data scoring.
Siberian Federal District
Novosibirsk and Krasnoyarsk represent expanding origination frontiers as first-time vehicle ownership penetrates middle-income households. Used-car financing dominates given price sensitivity and import logistics constraints. Regional banks face balance-sheet pressure from GAAP provisioning rules and BIS-aligned capital adequacy requirements.
Ural Federal District
Yekaterinburg anchors corporate fleet leasing demand tied to extractive industry logistics requirements. Residual-value management services generate ancillary fee streams beyond pure interest spreads. The district's industrial concentration shapes borrower profiles toward SME commercial vehicle acquisition.
Russia Auto Loan Market Competitive Landscape
Established state-backed lenders occupy the standard tier; emerging non-bank entrants pursue digital-first origination in regional cities. The market structures around three archetypes: universal banks with branch network dominance, specialized auto finance captives tied to manufacturer distribution, and agile fintech platforms leveraging alternative data scoring. Competitive moves concentrate on API-based underwriting partnerships and residual-value product diversification.
Among state-affiliated banking groups, Sberbank, VTB Bank, and Gazprombank anchor distinct strategic positions. Sberbank exemplifies branch-network scale advantage with nationwide physical presence. VTB Bank represents aggressive pricing competition in used-vehicle segments leveraging state capital backing. Gazprombank occupies the commercial fleet specialization tier with tailored lease structures.
| Leading Market Players |
|---|
| Gazprombank |
| Raiffeisenbank |
| Sberbank |
| Rosselkhozbank |
| Rosbank |
| VTB Bank |
| Unicredit Group |
| Credit Bank of Moscow |
| Alfa Bank |
| Others |
Pricing and Supply Chain Analysis
Central Bank of Russia macroprudential debt-burden limits gate qualified supply for premium-tier auto lending, restricting portfolio expansion to lenders meeting collateral coverage mandates and minimum down-payment thresholds. This regulatory filter concentrates pricing power among state-backed institutions while squeezing regional competitors into subprime segments.
Pricing Analysis
Input-cost pass-through from Central Bank of Russia policy rate corridors transmits directly to auto-loan pricing floors, squeezing net interest margins for originators. Three-tier pricing structure across premium, standard, and economy levels separates Sberbank's branch-network scale from VTB Bank's aggressive used-car undercutting and non-bank digital entrants. Pricing pressure stems from state-backed capital advantages allowing selective rate undercutting. First-time buyers in regional Siberian cities exhibit highest price sensitivity; corporate fleet operators in the Ural Federal District show lowest sensitivity due to bundled residual-value services.
Supply Chain Analysis
Funding supply rests on Central Bank of Russia liquidity facilities, state-affiliated bank deposit bases, and automaker captive-finance programs. Raw material dependencies include vehicle collateral depreciation curves, residual value forecasting data, and digital scoring algorithm licenses. Single-source vulnerability concentrates in Sberbank's 14,000-point branch network dominance for physical origination. Distribution runs through API-integrated mobile platforms, manufacturer-affiliated dealership networks, and direct bank branch relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's auto loan market functions as a stable compounder, with Central Bank of Russia regulatory calibration providing predictable underwriting guardrails that sustain portfolio quality across economic cycles.
For Market Incumbents: Hedge against digital-channel displacement by retrofitting legacy branch infrastructure with real-time underwriting pipelines. Acquire alternative-data scoring licenses to defend against non-bank API-based competitors in the Volga Federal District. Prioritize vertical integration into fleet residual-value management services. For New Entrants and Emerging Players: Launch via smartphone-native application channels targeting first-time buyers in Novosibirsk and Krasnoyarsk where branch density remains lowest. Penetrate the used-car financing segment through aggressive rate positioning against VTB Bank's state-backed pricing. Deploy instant-scoring algorithms leapfrogging legacy credit-bureau dependencies. For Investors and Strategic Acquirers: Roll-up economics work for regional non-bank digital lenders because Central Bank of Russia capital adequacy requirements consume balance-sheet capacity for smaller players. Five-to-ten year viability hinges on regulatory compliance capacity rather than scale alone. Monitor Central Bank of Russia calibration of electric-vehicle subsidy eligibility as inflection indicator for portfolio segment rotation.| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Credit Scoring Deployment | Regional non-bank lenders in the Volga Federal District collapse application timelines through alternative-data integration. |
| Fleet Lease Structure Expansion | Yekaterinburg extractive industry logistics demand generates ancillary fee streams beyond interest spreads. |
| Electric-Vehicle Subsidy Alignment | Portfolio expansion viability tracks evolving state incentive criteria for battery-powered collateral segments. |
| Residual Value Management Service | Corporate SME borrowers in the Ural Federal District pay premiums for off-balance-sheet fleet administration. |
| Digital Channel Migration | Siberian Federal District smartphone penetration enables leapfrog over legacy branch-dependent origination economics. |
Research Methodology
Direct dialogue with auto lending executives, Central Bank of Russia regulatory affairs specialists, dealership operations managers, and fleet procurement directors grounded qualitative findings. Secondary validation drew from Central Bank of Russia prudential reporting, vehicle registration databases, IHS Markit production data, and federal district economic statistics. Bottom-up origination volume estimates triangulated against top-down macroprudential constraint modeling.
Segmented outputs across loan type, borrower profile, application channel, and vehicle type dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from debt-service-to-income threshold calibration effects and digital-channel adoption curves. Electric-vehicle subsidy eligibility evolution and used-car residual value volatility served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Central Bank of Russia policy rate corridor swings and collateral depreciation shocks. Forecasts reflect documented assumptions on regulatory stability and technology penetration rates. A small set of named triggers warrants ongoing watch: macroprudential tightening acceleration, smartphone platform fragmentation, and state EV incentive cancellation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Auto Finance Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Europe Mortgage Lending Market