
 Brazil Home Loan Market | 2026-2036
Brazil Home Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Home Loan Market Insights
Retail banking distribution is fragmenting across Brazil's home loan sector as digital platforms erode the branch-centric model that long dominated mortgage origination. Caixa Econômica Federal anchors the public-sector channel through its nationwide correspondent network and subsidized credit lines. Itaú Unibanco competes via integrated wealth-management cross-sell and proprietary scoring engines. Nubank differentiates through app-first origination with same-day pre-approval workflows.
A home loan constitutes a secured credit instrument collateralized by residential real property, governed by Brazil's Lei de Alienação Fiduciária and typically indexed to the TR or IPCA benchmarks with amortization horizons spanning 15 to 35 years. Its primary purpose channels household savings into durable housing acquisition while generating interest income for originating institutions. Fixed-rate products dominate origination volume among conservative borrowers seeking payment predictability, while adjustable-rate contracts capture price-sensitive segments in declining-rate environments. First-time buyers represent the fastest-expanding borrower category as federal subsidy programs lower entry barriers.
Brazil's central bank, the Banco Central do Brasil, governs capital adequacy and consumer credit rules, while the CMN sets housing finance systemwide parameters including funding-source requirements. ANVISA does not regulate this sector; rather, the CVM oversees securitization of mortgage receivables through FIDCs. These frameworks shape product design, funding costs, and market access for new entrants. Stakeholders must monitor central bank SELIC trajectory and federal subsidy budget allocations to anticipate origination mix shifts.
Market Dynamics
Brazil's central bank TR methodology revision is compressing origination timelines while digital scoring engines from Itaú Unibanco and Nubank fragment the branch-centric distribution model that Caixa Econômica Federal long dominated.
Growth Catalysts
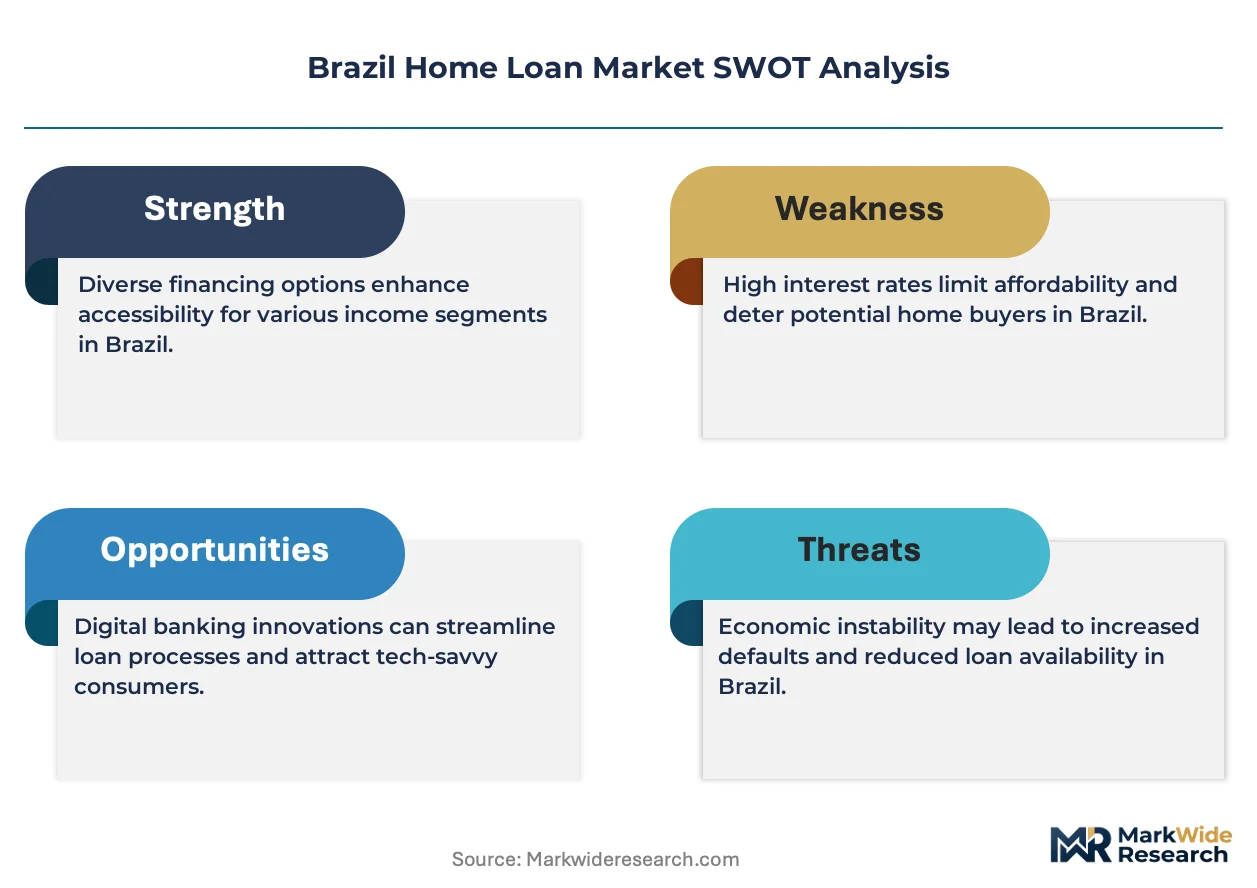
- Casa Verde e Amarela subsidies:Federal income-bracketed credit lines reduce down-payment requirements for first-time buyers in São Paulo's metropolitan corridor and peripheral municipalities.
- IPCA-indexed products:Inflation-linked amortization structures attract price-sensitive borrowers seeking real-rate transparency over nominal TR benchmarks.
- Southeast demand concentration:São Paulo state anchors origination volume as employment density and formal-sector payroll access concentrate mortgage-ready households.
Market Restraints
- SELIC volatility transmission:Brazil's central bank policy rate swings compress net interest margins for fixed-rate portfolios held by retail banks.
- Correspondent network dependence:Origination still flows through Caixa's physical agent footprint, creating geographic access asymmetries between urban centers and interior municipalities.
- Construction cost inflation:Input material price swings indexed to commodity markets delay project completions and trigger collateral-value reassessments.
Strategic Opportunities
- Northeast underpenetration:Ceará and Pernambuco exhibit formal employment growth without proportional mortgage origination depth, opening correspondent-light digital acquisition.
- FIDC securitization expansion:CVM-regulated receivable-backed instruments enable non-bank originators to access institutional funding pools beyond deposit bases.
- API-first credit bureaus:Real-time payroll and tax-data integration via Serasa Experian and Boa Vista SCPC compresses pre-approval workflows from days to hours.
Industry Challenges
- Legacy core system integration:Banks migrating from COBOL-based amortization engines to cloud-native stacks face data-migration friction and regulatory sandbox delays.
- Fiduciary lien perfection timelines:Lei de Alienação Fiduciária registration bottlenecks at cartórios extend closing cycles, eroding digital-channel conversion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Home Loan Market |
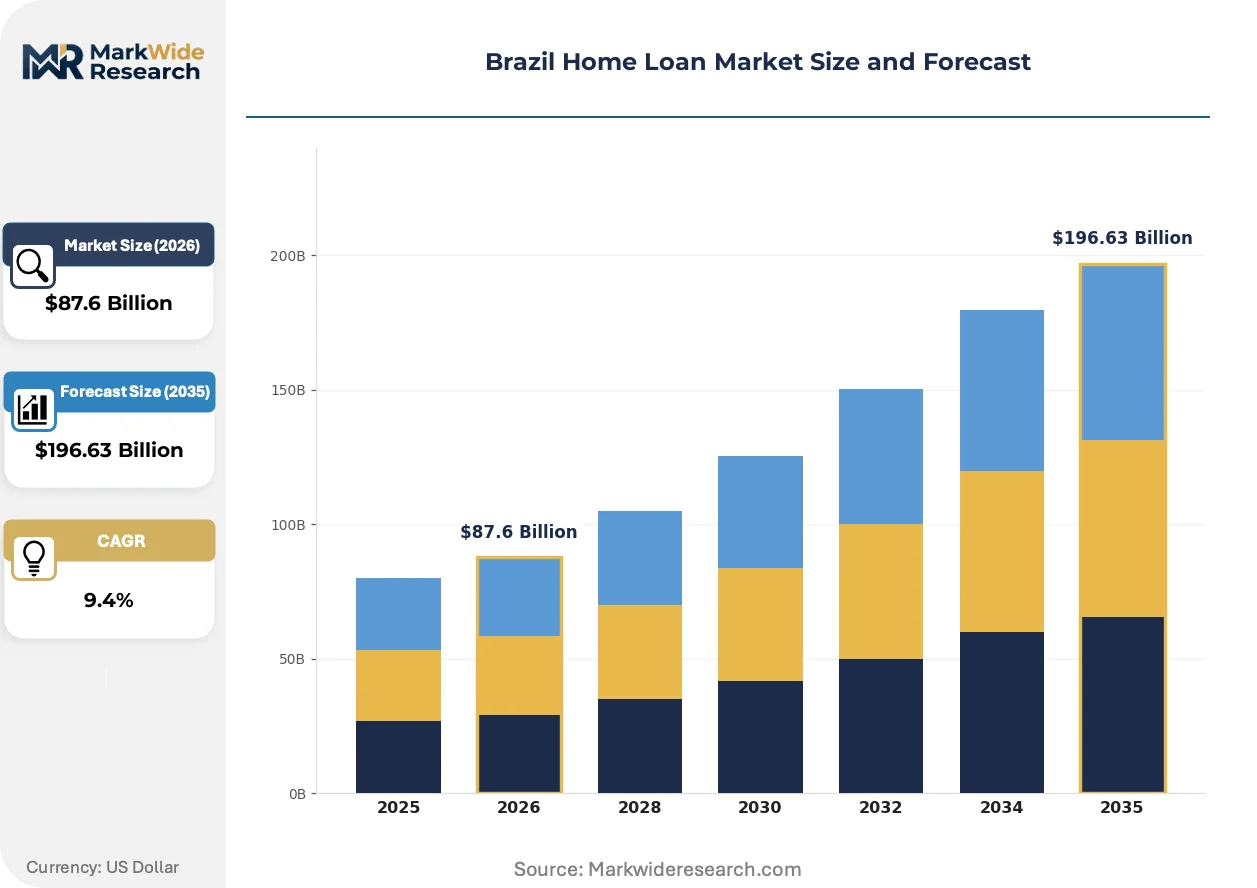
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Rate, Adjustable Rate, Hybrid, Interest-Only Loan Purpose: Purchase, Refinance, Renovation, Debt Consolidation Borrower Type: First-Time Buyers, Repeat Buyers, Investors, Self-Employed Loan Amount: Low Value, Mid Value, High Value, Jumbo |
| Companies Covered | Caixa Econômica Federal, Itaú Unibanco, Banco Bradesco, Banco do Brasil, Santander, Nubank, Associação de Poupança e Empréstimo Poupex, Creditas, Nomad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Home Loan Market Trends and Innovations
Three forces are restructuring Brazil's home loan sector: algorithmic underwriting is collapsing origination timelines, central bank regulatory recalibration is reshaping benchmark indexing, and first-time buyer channel preferences are fragmenting distribution economics.
Open banking protocols via Banco Central do Brasil's PIX and credit-data sharing mandates are collapsing the information asymmetry that previously justified branch-based document verification. Digital-native lenders now underwrite using real-time payroll, tax, and utility-payment histories. First-time buyers in São Paulo and Belo Horizonte complete pre-approval without physical document submission, compressing the funnel from weeks to hours.
Banco Central do Brasil's revised TR calculation methodology—shifting from a forward-looking expectation to a backward-looking realized-inflation proxy—is forcing product-design recalibration across retail banks. IPCA-linked contracts gain share as borrowers seek predictability against benchmark volatility. CMN capital-requirement adjustments for inflation-indexed portfolios are redirecting funding-cost strategies at public and private institutions alike.
First-time buyer segments are abandoning correspondent-broker channels for direct-to-consumer mobile origination. Nubank's same-day pre-approval workflows and Itaú's integrated wealth-management cross-sell are capturing São Paulo metropolitan corridor volume that previously flowed through Caixa's physical network. This channel rotation concentrates acquisition economics in app-install and data-scoring investments rather than brick-and-mortar expansion.
Brazil Home Loan Market Segmentation
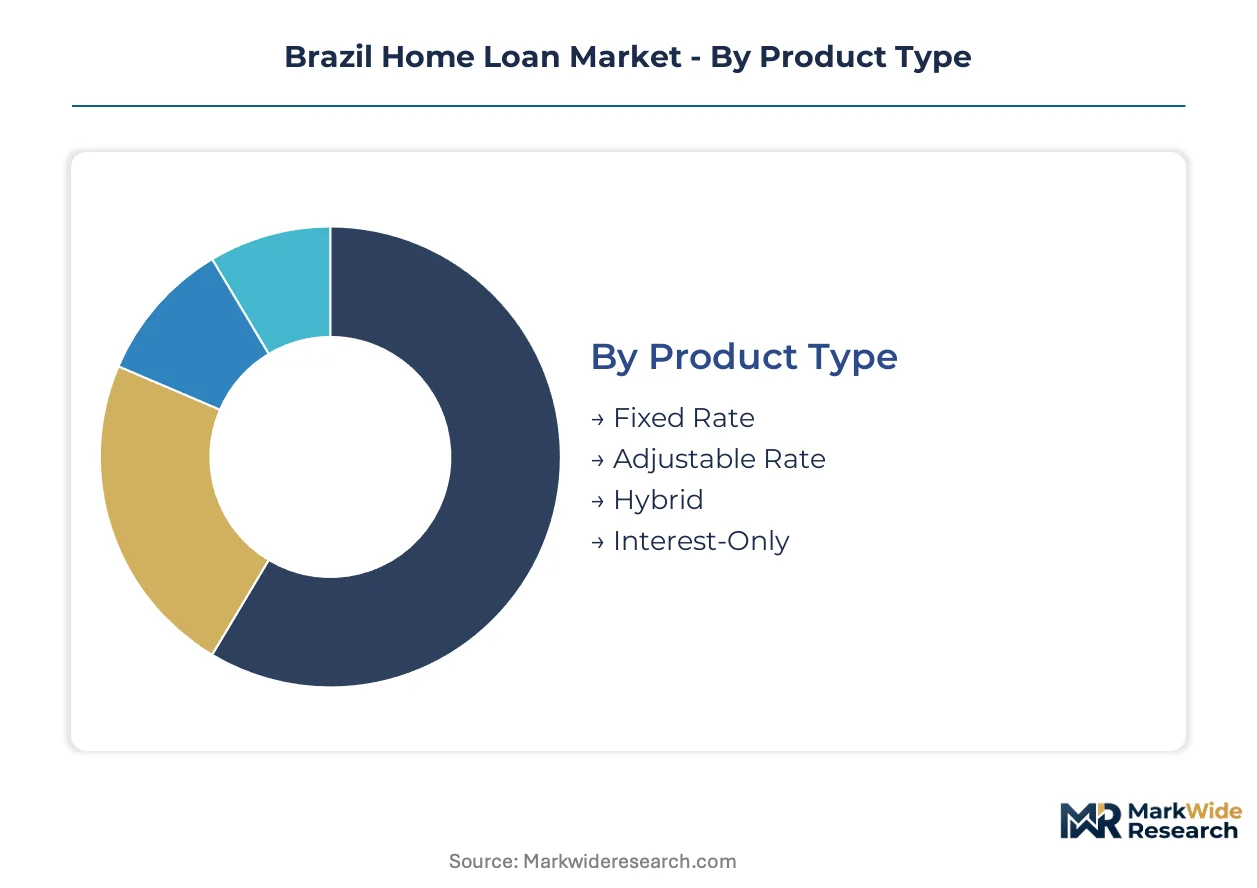
Segmentation in Brazil's home loan market determines origination economics, risk-weighting requirements, and channel strategy. Each dimension—product structure, loan purpose, borrower profile, and ticket size—carries distinct regulatory treatment and margin profiles that shape institutional positioning.
Product Type:
Cycle times vary dramatically across product structures: fixed-rate contracts lock funding costs at origination and turn over slowly, while adjustable-rate products reprice with SELIC movements and accelerate portfolio velocity.
- Fixed Rate:Contracts indexed to nominal rates with locked-in installments throughout amortization. São Paulo's metropolitan corridor concentrates conservative borrower demand where payment predictability outweighs rate premium.
- Adjustable Rate:Instruments repricing with TR or SELIC benchmarks. Price-sensitive segments in declining-rate environments favor these structures, though Banco Central do Brasil's revised TR methodology is compressing origination timelines for this category.
- Hybrid:Fixed-to-float conversion features after initial lock periods.
- Interest-Only:Deferred principal amortization structures for cash-flow managed investors.
Fixed Rate dominates installed base. Adjustable Rate is where expansion concentrates.
Loan Purpose:
Application type dictates collateral requirements and fiduciary lien perfection complexity, with purchase transactions requiring full property transfer documentation while refinances leverage existing security instruments.
- Purchase:Primary market acquisition financing governed by Lei de Alienação Fiduciária. Casa Verde e Amarela subsidies concentrate demand among first-time buyers in peripheral São Paulo municipalities where formal employment growth supports payroll-deductible origination.
- Refinance:Liability restructuring using existing collateral. Rate-sensitive borrowers in Southeast employment corridors exploit SELIC declines to reduce debt service burdens without property transfer tax triggers.
- Renovation:Improvement financing against completed collateral.
- Debt Consolidation:Multi-liability restructuring into single secured instrument.
Purchase commands origination volume. Refinance is climbing the fastest as rate volatility creates repricing windows.
Borrower Type:
Customer classification determines scoring data availability and subsidy eligibility, with formal payroll access creating sharp segmentation between document-light and document-intensive underwriting paths.
- First-Time Buyers:Federal income-bracketed credit line recipients with limited credit history. São Paulo state anchors this segment as employment density concentrates mortgage-ready households with Casa Verde e Amarela access.
- Repeat Buyers:Seasoned borrowers with established collateral equity and bureau history. Wealth-management cross-sell opportunities concentrate among Itaú Unibanco's existing depositor base in Southeast metropolitan corridors.
- Investors:Non-owner-occupied acquisition financing with distinct LTV thresholds.
- Self-Employed:Irregular income documentation requiring tax-return verification and extended underwriting cycles.
Repeat Buyers anchor portfolio profitability. First-Time Buyers represent the fastest-expanding trajectory as subsidy programs lower entry barriers.
Loan Amount:
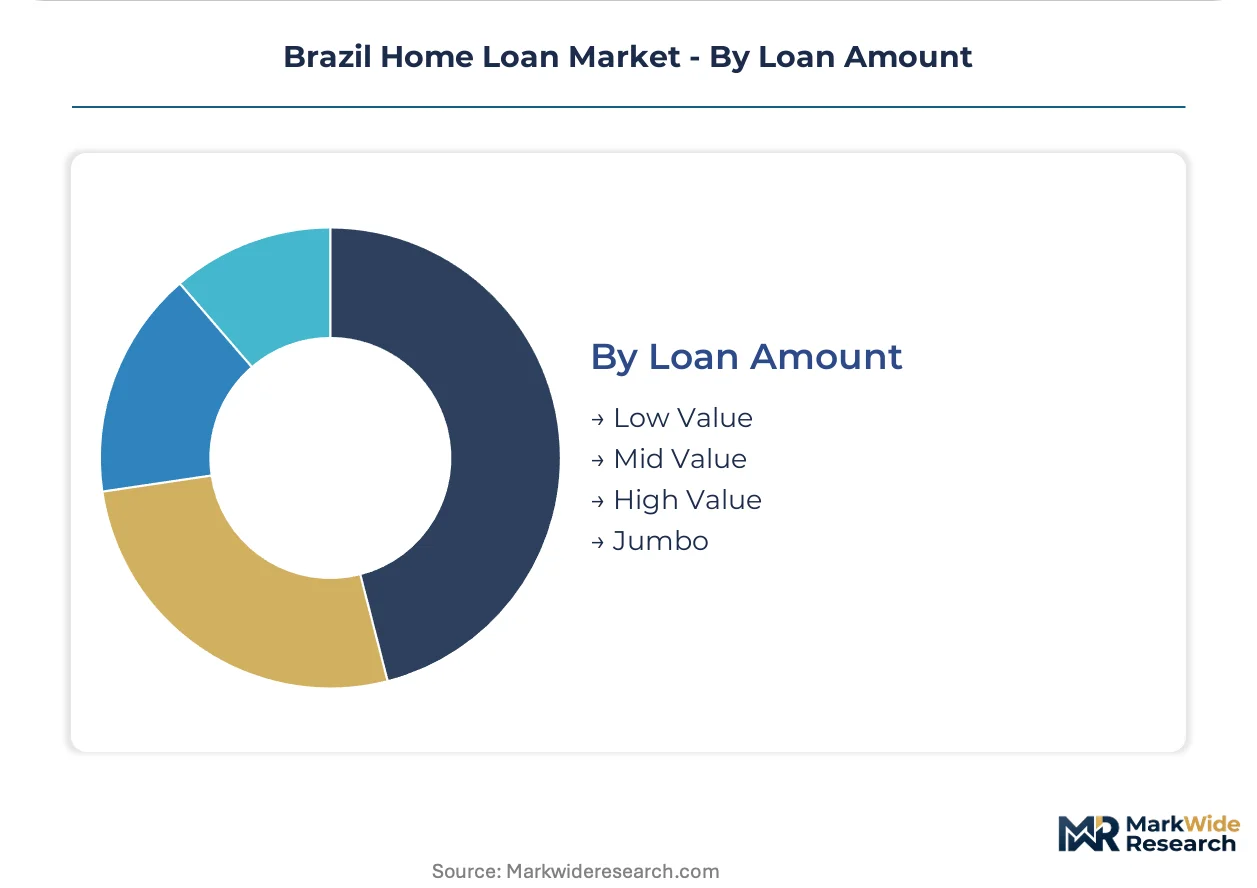
Ticket size correlates with funding source requirements and capital adequacy treatment, with CMN rules creating tiered reserve requirements that reshape institutional appetite across value bands.
- Low Value:Subsidized credit line thresholds with reduced down-payment requirements. Northeast underpenetration in Ceará and Pernambuco exhibits formal employment growth without proportional origination depth, opening correspondent-light digital acquisition.
- Mid Value:Standard amortization structures for metropolitan corridor primary residences. São Paulo's formal-sector payroll access concentrates demand in this tier where IPCA-indexed products gain share against benchmark volatility.
- High Value:Elevated LTV limits with enhanced documentation requirements.
- Jumbo:Super-prime thresholds requiring bespoke underwriting and extended fiduciary lien perfection timelines at cartórios.
Mid Value dominates origination flow. Low Value is where subsidy expansion redirects institutional focus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo-Rio de Janeiro rail corridor and Santos port complex anchor Brazil's mortgage liquidity flows, channeling payroll-deductible credit from Southeast employment clusters into housing stock across five distinct state-level markets.
São Paulo
São Paulo state's metropolitan corridor concentrates formal-sector payroll access and Casa Verde e Amarela subsidy uptake. CMN capital requirements for inflation-indexed portfolios redirect funding strategies at institutions headquartered here. The capital city's employment density generates mortgage-ready households at scale unmatched elsewhere in Brazil.
Minas Gerais
Belo Horizonte's industrial belt drives middle-income housing demand with strong manufacturing payroll growth. Banco Central do Brasil's open banking protocols enable digital-native lenders to penetrate this market without correspondent networks. The state's interior municipalities lag in origination depth despite formal employment expansion.
Rio de Janeiro
Rio de Janeiro state's tourism and services economy produces irregular income documentation challenges for underwriters. Lei de Alienação Fiduciária registration bottlenecks at cartórios extend closing cycles in the capital's high-value coastal zones. Niterói and peripheral municipalities show stronger first-time buyer subsidy penetration.
Rio Grande do Sul
Rio Grande do Sul's agribusiness payrolls support distinct seasonal income verification patterns for mortgage underwriting. The state's southern corridor exhibits below-national-average digital origination adoption, preserving branch-centric distribution. Porto Alegre anchors regional demand with manufacturing and services employment concentration.
Bahia
Bahia's Northeast positioning offers formal employment growth without proportional mortgage origination depth. API-first credit bureau integration via Serasa Experian creates correspondent-light acquisition opportunities in Salvador's metropolitan zone. The state's interior remains dependent on Caixa's physical agent footprint for market access.
Brazil Home Loan Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in origination technology and scoring infrastructure. Brazil's home loan sector structures around three archetypes: public-sector distributors with subsidized credit mandates, private universal banks with cross-sell integration, and digital-native attackers with algorithmic underwriting. Consolidation pressure concentrates among universal banks seeking scale in IPCA-indexed portfolios, while vertical integration into proprietary scoring engines differentiates app-first entrants.
Within the public-sector archetype, Caixa Econômica Federal occupies the anchor position through its nationwide correspondent network and Casa Verde e Amarela administration. Among private universal banks, Itaú Unibanco and Banco Bradesco exemplify the integrated wealth-management model, leveraging existing depositor relationships for mortgage cross-sell. Digital-native challengers include Nubank, which represents the app-first origination archetype with compressed pre-approval workflows.
| Leading Market Players |
|---|
| Caixa Econômica Federal |
| Itaú Unibanco |
| Banco Bradesco |
| Banco do Brasil |
| Santander |
| Nubank |
| Associação de Poupança e Empréstimo Poupex |
| Creditas |
| Nomad |
| Others |
Pricing and Supply Chain Analysis
São Paulo's correspondent banking infrastructure anchors origination capacity dynamics that cascade into downstream pricing power across Brazil's mortgage sector. The concentration of formal payroll access and Casa Verde e Amarela subsidy administration in this metropolitan corridor shapes how lenders calibrate rate spreads and fee structures for borrower segments nationwide.
Pricing Analysis
Volume-discount tiering structures separate jumbo thresholds from mid-value and subsidized low-value credit lines, with IPCA-indexed products commanding premium spreads over TR-linked alternatives due to inflation-hedging demand. Price differentiation hinges on borrower documentation depth and formal payroll verification status, where self-employed segments face wider spreads. Pricing pressure stems from SELIC volatility compressing net interest margins for fixed-rate portfolios held by retail banks. First-time buyers accessing federal subsidies exhibit highest price sensitivity, while repeat buyers with established bureau history negotiate preferential terms.
Supply Chain Analysis
Supplier-financing angles including extended payment terms for correspondent networks and supply-chain finance facilities for construction material vendors shape liquidity flows through Brazil's mortgage ecosystem. Funding draws from domestic deposit bases, FIDC securitization pools regulated by CVM, and Banco Central do Brasil liquidity facilities. Raw material dependencies center on cement, steel rebar, and ceramic inputs indexed to commodity markets. Single-source vulnerability concentrates in Caixa Econômica Federal's correspondent agent footprint for interior municipality access. Distribution runs through branch-correspondent hybrids, direct-to-consumer mobile platforms, and wealth-management cross-sell integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's home loan market operates as a substitution defense against fintech-led unsecured credit and rent-to-own housing models that divert household savings from traditional mortgage channels. Incumbents must navigate this threat while preserving correspondent network economics against digital-native attackers.
For Market Incumbents: Insulate core profitability by deepening proprietary scoring engine investment and compressing pre-approval workflows to match Nubank's same-day benchmarks. Defensive consolidation should prioritize IPCA-indexed portfolio scale to offset SELIC margin compression. Channel control through API-first credit bureau integration with Serasa Experian and Boa Vista SCPC reduces document-verification friction.
For New Entrants and Emerging Players: Establish a beachhead in Ceará and Pernambuco's underpenetrated Northeast corridor where formal employment growth lacks proportional mortgage origination depth. White-space targets include correspondent-light digital acquisition via real-time payroll data integration and FIDC securitization funding for non-bank originators. Go-to-market should emphasize app-first origination with compressed fiduciary lien perfection timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a financial infrastructure play because mortgage origination technology and scoring engine IP compound defensive moats against rate-cycle volatility. Acquisition targets should concentrate on digital-native lenders with proven São Paulo metropolitan corridor penetration and algorithmic underwriting capabilities. The signal to watch is Banco Central do Brasil TR methodology recalibration frequency as a proxy for benchmark volatility and product-design reinvestment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FIDC Securitization Expansion | CVM-regulated instruments unlock institutional funding beyond deposit bases for non-bank originators. |
| API-First Credit Bureau Integration | Real-time Serasa Experian and Boa Vista SCPC data compresses pre-approval from days to hours. |
| IPCA-Indexed Product Scaling | Inflation-linked contracts gain share as borrowers seek predictability against TR benchmark volatility. |
| Correspondent Network Optimization | Digital channel migration reduces Caixa Econômica Federal's geographic access asymmetries. |
| Open Banking Protocol Adoption | Banco Central do Brasil PIX integration collapses information asymmetry justifying branch verification. |
Research Methodology
A standing panel of mortgage origination executives, correspondent network managers, central bank policy researchers, and fintech product officers provided ongoing calibration across primary fieldwork. Secondary validation drew from Banco Central do Brasil statistical releases, CMN regulatory circulars, CVM securitization filings, and FIDC issuance prospectuses. Bottom-up origination volume modeling triangulated against top-down housing credit stock aggregates.
Scenario-bracketing framed SELIC trajectory sensitivity and subsidy budget allocation variants across the projection horizon. Segmentation dimensions modeled included product structure, loan purpose, borrower profile, ticket size, and regional formal employment density. CAGRs derived from compound growth pathing anchored to central bank policy rate assumptions and housing stock formation rates. Forecast inputs incorporated TR methodology revision impacts and open banking adoption curves.
Sensitivities concentrate around Banco Central do Brasil monetary policy pivot timing and Casa Verde e Amarela budget continuity. Forecasts embed assumptions regarding correspondent network digital migration velocity and cartório registration bottleneck resolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
United States Car Loan Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Alternative Lending Platform Market