
 Russia Student Loan Market | 2026-2036
Russia Student Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Student Loan Market Insights
Product unbundling is shifting how Russian students assemble financing packages across multiple credit sources. Sberbank leverages its branch network to dominate retail distribution of education credit products. VTB Bank competes through specialized lending programs tied to public university partnerships. Gazprombank anchors corporate-linked education finance for employees and their dependents.
A student loan constitutes a term credit facility extended to enrolled learners for tuition, living expenses, and academic materials, typically carrying deferred repayment until degree completion or income threshold attainment. Federal loans backed by state guarantees represent the mature segment with established volume but compressed margins, while private loans to vocational students at technical colleges represent the fastest-growing margin pool as skill-based labor demand intensifies. Income-based repayment models are gaining structural traction as regulators push alignment between debt service capacity and graduate earnings trajectories.
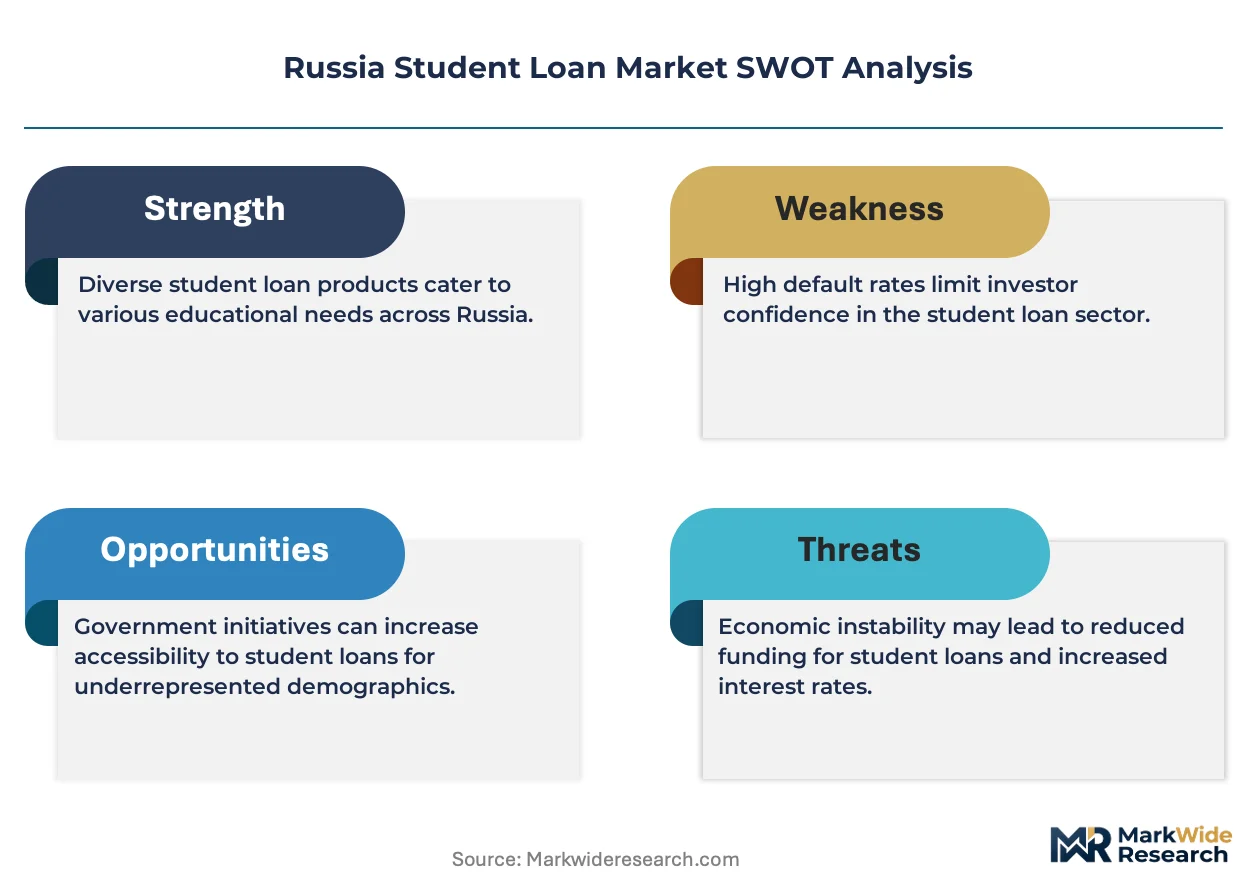
The Central Bank of Russia supervises lender capital adequacy and consumer protection standards for education credit, while the Ministry of Education and Science administers federal subsidy programs and borrower eligibility frameworks. Federal Fund for Student Loans (FZFA) intermediation shapes market access by determining which institutions qualify for guaranteed lending. Stakeholders must monitor regulatory recalibration of subsidized rate tiers and university accreditation criteria as policy prioritizes workforce-relevant degree pathways.
Market Dynamics
Federal Fund for Student Loans accreditation criteria are concentrating disbursement flows toward workforce-aligned degree pathways, compressing lender participation margins while expanding volume guarantees for qualifying institutions.
Growth Catalysts
- Ministry of Education and Science subsidy expansion:State-backed interest rate reductions lower effective borrowing costs for undergraduate enrollees at public universities. This mechanism pulls first-generation students into formal credit markets.
- Technical college vocational pipelines:Skill-based labor shortages in manufacturing and IT sectors accelerate demand for applied credential programs. Federal guarantees now extend to polytechnic and trade school financing.
- Moscow-Saint Petersburg enrollment clustering:Geographic concentration of elite university seats creates predictable demand pools. Lenders optimize branch placement and underwriting models around these catchment zones.
Market Restraints
- Ruble-denominated funding volatility:Currency fluctuation elevates cost-of-funds for private lenders without state swap lines. Foreign-currency borrowing becomes prohibitively expensive during stress periods.
- Central Bank of Russia capital adequacy thresholds:Education credit risk-weighting consumes more balance sheet capacity than secured retail products. Smaller regional banks exit the segment rather than rebuild capital buffers.
- Income verification opacity:Shadow economy participation limits reliable earnings data for graduate repayment capacity assessment. Underwriting relies on university placement rates rather than individual credit histories.
Strategic Opportunities
- Siberian and Far Eastern regional penetration:Federal university expansion programs in Tomsk, Novosibirsk, and Vladivostok create underserved borrower populations. Early-mover lenders capture relationship primacy before branch networks saturate.
- Digital disbursement-to-university pipelines:API integration between lender core systems and university bursar offices eliminates manual verification delays. Real-time tuition payment confirmation reduces fraud and dropout risk.
- Income-contingent repayment mandates:Draft legislation from the Ministry of Finance proposes automatic payroll deduction thresholds. Product design around earnings-linked servicing creates differentiation from fixed-schedule competitors.
Industry Challenges
- Data science talent scarcity:Predictive modeling for graduate earnings trajectories requires econometricians with regional labor market expertise. Compensation benchmarks lag fintech and e-commerce sectors.
- University accreditation surveillance:Continuous monitoring of Federal Fund for Student Loans eligibility status demands dedicated compliance infrastructure. Sudden disqualification events trigger portfolio concentration risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Student Loan Market |
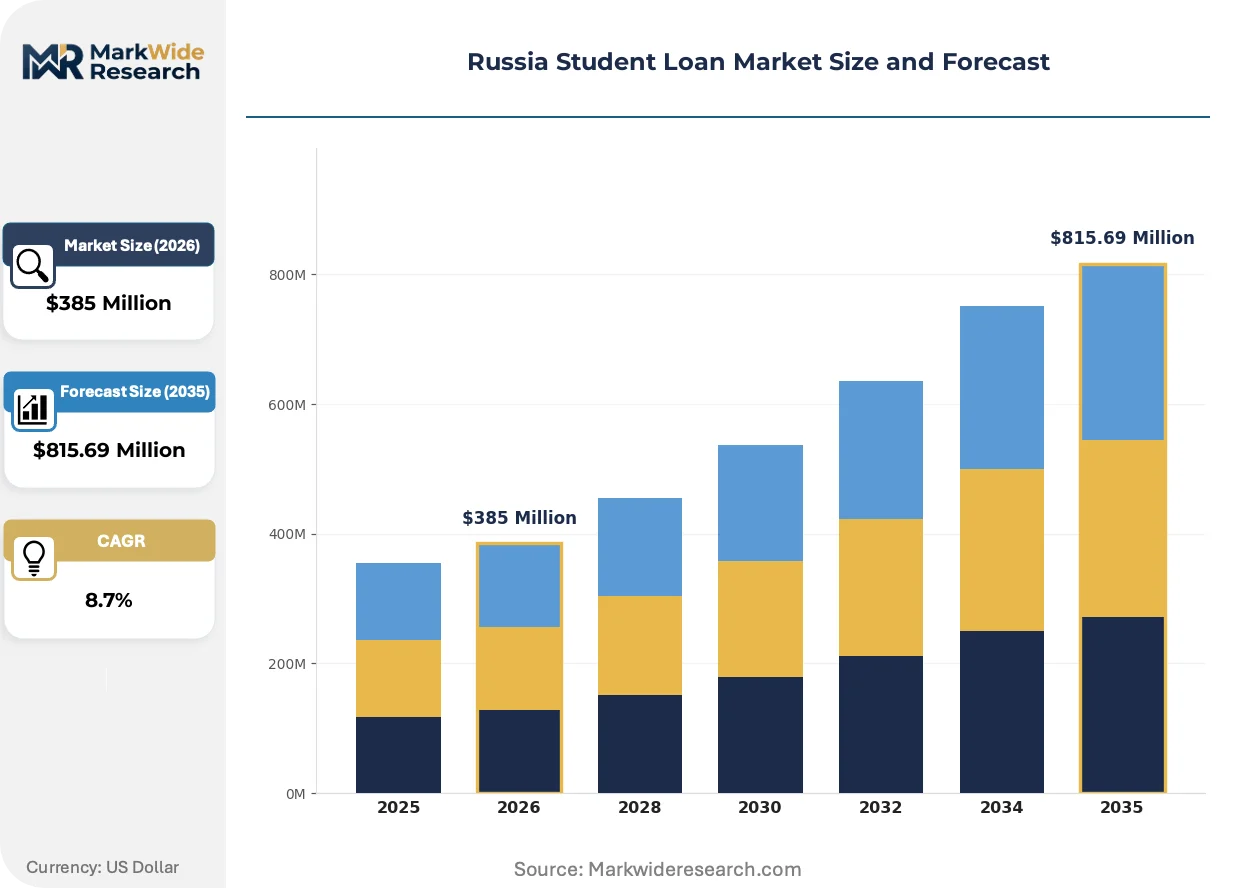
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $815.69 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Federal Loans, Private Loans, Credit Lines, Refinanced Loans Repayment Model: Deferred Payments, Income-Based Payments, Interest-Only Payments, Standard Payments Borrower Type: Undergraduate Students, Graduate Students, International Students, Vocational Students Institution Type: Public Universities, Private Universities, Technical Colleges, Online Colleges |
| Companies Covered | Vnesheconombank (VEB), Gazprombank, Sberbank, Tinkoff Bank, Rosselkhozbank, VTB Bank, Federal Fund for Student Loans (FZFA), Promsvyazbank, Alfa Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Student Loan Market Trends and Innovations
Digital origination platforms and alternative data integration are compressing decision timelines from weeks to minutes. These shifts reshape borrower expectations and lender cost structures simultaneously.
Machine learning-driven credit scoring is rewriting how underwriters assess repayment probability without traditional collateral. Regional banks and fintech entrants deploy alternative data models incorporating university-specific completion rates and field-of-study earnings premiums. This compression of information asymmetry enables thinner pricing for qualified cohorts.
Central Bank of Russia consumer protection mandates now require standardized disclosure of total cost of credit and post-graduation repayment scenarios. Lenders must reformat marketing materials and retool call center scripts to comply with plain-language requirements. The regulatory friction falls most heavily on legacy institutions with paper-based application workflows.
Borrower preference is rotating toward bundled financing packages covering tuition, housing, and device procurement in single credit facilities. Students at technical colleges and online programs drive this demand for consolidated disbursement. Saint Petersburg and Kazan markets exhibit the strongest uptake of unified-product structures over discrete loan types.
Russia Student Loan Market Segmentation
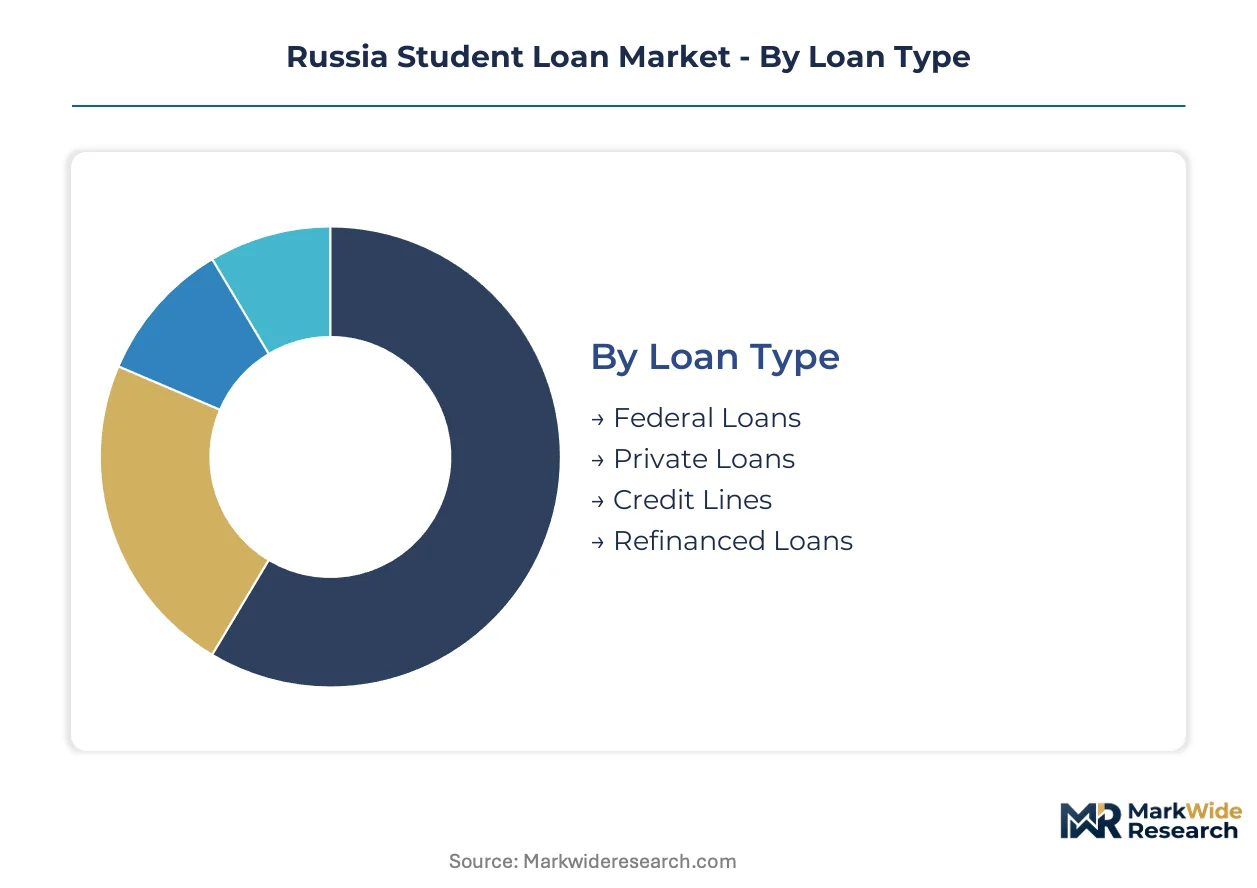
Segmentation in the Russia student loan market reveals how lender product design, borrower risk profiles, and institutional accreditation intersect. Each dimension carries distinct regulatory treatment and margin characteristics that shape portfolio construction.
Loan Type:
Federal loans operate as standalone guaranteed instruments with state-backed principal protection, while private credit products embed within broader retail banking relationships.
- Federal Loans:State-guaranteed term facilities carry subsidized interest rates set by the Ministry of Education and Science. Disbursement concentrates at Moscow and Saint Petersburg public universities where Federal Fund for Student Loans accreditation is most established.
- Private Loans:Unsecured credit products from commercial banks fill gaps between federal coverage and total cost of attendance. VTB Bank and Sberbank dominate this segment through branch-based origination.
- Credit Lines:Revolving facilities tied to university bursar accounts enable semester-by-semester drawdowns.
- Refinanced Loans:Consolidation products for graduates seeking rate reduction or term extension.
Volume placements concentrate in Federal Loans; the faster expansion belongs to Private Loans.
Repayment Model:
Cost tier differentiation separates premium flexibility products from standardized schedules, with income-linked structures commanding higher servicing fees.
- Deferred Payments:Principal and interest suspension until degree completion or grace period expiration. Undergraduate borrowers at public universities drive demand for this mature structure.
- Income-Based Payments:Servicing obligations scale with verified post-graduation earnings. Draft legislation from the Ministry of Finance would mandate payroll deduction infrastructure for this expanding category.
- Interest-Only Payments:Reduced servicing during enrollment with balloon principal obligations.
- Standard Payments:Immediate amortization schedules typical of parent co-signed loans.
Deferred Payments dominate current volume; Income-Based Payments are climbing the fastest as regulatory frameworks mature.
Borrower Type:
Application context varies sharply between degree-seeking populations, with vocational pipelines offering distinct collateralization through workforce placement guarantees.
- Undergraduate Students:First-degree seekers at accredited institutions constitute the core addressable market. Federal subsidy eligibility concentrates this demand at public universities in major metropolitan clusters.
- Vocational Students:Polytechnic and trade school enrollees access newly extended federal guarantee programs. Manufacturing and IT sector labor shortages in Siberian industrial zones accelerate origination.
- Graduate Students:Advanced degree candidates with existing credit histories.
- International Students:Non-citizen borrowers requiring co-signers or collateral.
Undergraduate Students anchor portfolio composition; Vocational Students are gaining share fastest on policy tailwinds.
Institution Type:
Geography and accreditation tier determine lender participation, with federal guarantee availability creating sharp segmentation between eligible and excluded institutions.
- Public Universities:State-funded institutions with established Federal Fund for Student Loans accreditation. Moscow State University and Saint Petersburg State University generate predictable, concentrated demand pools.
- Technical Colleges:Applied credential providers benefiting from expanded federal guarantee eligibility. Tomsk and Novosibirsk regional campuses represent underserved expansion frontiers.
- Private Universities:Tuition-dependent institutions with variable accreditation status.
- Online Colleges:Distance-learning providers with emerging eligibility frameworks.
Public Universities command placement concentration; Technical Colleges show the steepest expansion trajectory as workforce alignment priorities reshape accreditation criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Loan disbursement concentrates in Moscow and Saint Petersburg while origination infrastructure lags in Siberian and Far Eastern territories. Federal university expansion programs are redistributing demand toward secondary academic clusters.
Central Federal District
Moscow State University and Higher School of Economics generate concentrated demand for federal guaranteed products. The Ministry of Education and Science channels subsidized rate tiers through accredited public institutions. Lender branch density peaks in the capital, compressing customer acquisition costs for Sberbank and VTB Bank.
Northwestern Federal District
Saint Petersburg State University anchors the second-largest enrollment pool for undergraduate financing. Federal Fund for Student Loans accreditation covers polytechnic institutes serving manufacturing sector workforce pipelines. Gazprombank leverages corporate linkages to capture employee-dependent borrowers in the region's energy sector.
Siberian Federal District
Tomsk and Novosibirsk state universities represent underserved expansion frontiers with rising technical college enrollment. Central Bank of Russia capital adequacy thresholds deter smaller regional banks from establishing education credit operations. Early-mover lenders are deploying digital origination platforms to offset sparse physical infrastructure.
Far Eastern Federal District
Vladivostok Federal University enrollment is climbing on government-backed territorial development incentives. The Ministry of Finance draft legislation on income-contingent repayment would mandate payroll deduction infrastructure for this remote borrower population. Currency volatility elevates funding costs for private lenders without state swap line access.
Southern Federal District
Rostov-on-Don and Krasnodar host growing vocational student populations targeting agricultural and logistics sector employment. Federal guarantee program extensions now cover polytechnic credentials aligned with regional labor shortages. Income verification opacity complicates underwriting as shadow economy participation limits reliable earnings data.
Russia Student Loan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across origination channels and borrower segments. State-backed universal banks dominate volume through branch network density and federal guarantee program participation. Three archetypes structure competition: state-owned universal banks with subsidy access, corporate-linked lenders with captive employee populations, and digital-native entrants with alternative data scoring. Consolidation pressure intensifies as Central Bank capital requirements force smaller regional banks toward exit or acquisition.
Within the state-backed universal bank tier, Sberbank, VTB Bank, and Gazprombank anchor competitive positioning. Sberbank exemplifies branch-network scale advantages across Moscow and Saint Petersburg enrollment clusters. VTB Bank occupies a position tied to public university partnership programs. Gazprombank represents corporate-linked education finance archetypes serving energy sector employees and dependents. The Federal Fund for Student Loans operates as a non-competing intermediary determining institutional eligibility rather than direct lending.
| Leading Market Players |
|---|
| Vnesheconombank (VEB) |
| Gazprombank |
| Sberbank |
| Tinkoff Bank |
| Rosselkhozbank |
| VTB Bank |
| Federal Fund for Student Loans (FZFA) |
| Promsvyazbank |
| Alfa Bank |
| Others |
Pricing and Supply Chain Analysis
Federal subsidy tier divergence separates state-guaranteed instruments from private credit products, concentrating pricing power at Sberbank and VTB Bank where branch density meets subsidized rate eligibility. This bifurcation manifests in compressed margins for guaranteed lending against wider spreads for unsecured vocational financing, while supply chain configuration privileges Moscow and Saint Petersburg enrollment clusters over remote territories.
Pricing Analysis
Margin tightening in federal guaranteed products reflects Ministry of Education and Science rate caps that compress lender spreads to basis points above funding costs. Private loans to vocational students at technical colleges command wider pricing flexibility through risk-based underwriting, with three-tier pricing structure across premium income-contingent, standard deferred-payment, and economy immediate-amortization levels. Price differentiation hinges on university accreditation tier and field-of-study placement rates. Cost-down pressure on standard deferred products accelerates because Central Bank capital adequacy thresholds elevate risk-weighted balance sheet consumption. Vocational borrowers in Siberian industrial zones exhibit highest price sensitivity; Moscow public university enrollees with federal subsidy access show lowest.
Supply Chain Analysis
Data science talent scarcity in Moscow and Saint Petersburg constrains predictive model deployment for regional expansion. Lending infrastructure draws from three geographic concentrations: branch networks in Central Federal District, API-integrated digital platforms from fintech development hubs, and compliance infrastructure concentrated in capital cities. Raw material dependencies include graduate earnings data feeds from tax authorities, university bursar system integrations, and payroll deduction infrastructure from employer networks. Supply chain risk centers on single-source vulnerability to Federal Fund for Student Loans accreditation decisions that trigger sudden portfolio concentration events. Distribution runs through dual channels: physical branch origination for federal guaranteed products and mobile-first platforms for private credit lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital scarcity among regional banks props pricing power for state-backed universal lenders with balance sheet depth. This supply-constrained structure favors early movers in underserved territories before digital infrastructure saturates.
For Market Incumbents: Anticipate regulatory recalibration of income-contingent repayment mandates by building payroll deduction API infrastructure ahead of Ministry of Finance legislation. Consolidate position through backward integration into university bursar system partnerships that lock in real-time disbursement pipelines. Defend against fintech entrants by capturing technical college accreditation relationships before federal guarantee expansion completes. For New Entrants and Emerging Players: University bursar offices in Tomsk, Novosibirsk, and Vladivostok represent the most penetrable origination channel given sparse incumbent branch presence. White-space targets include vocational student populations at polytechnic institutes and online program enrollees seeking bundled tuition-housing-device financing. Go-to-market execution should anchor on API-first disbursement integration that eliminates manual verification delays. For Investors and Strategic Acquirers: Re-rating potential sits with digital-native lenders possessing alternative data scoring capabilities given Central Bank consumer protection mandates that disadvantage paper-based legacy workflows. Long-term viability favors platforms with regional labor market econometric expertise and university-specific completion rate databases. Acquisition target archetype: fintech entrants with deployed Siberian digital infrastructure and established Federal Fund for Student Loans intermediary relationships. Signal to watch: draft income-contingent repayment legislation progression through Ministry of Finance.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration with University Bursar Systems | Eliminates manual verification delays and reduces dropout-linked credit losses through real-time enrollment confirmation. |
| Income-Contingent Repayment Infrastructure Buildout | Positions lenders ahead of Ministry of Finance payroll deduction mandates for differentiated servicing capabilities. |
| Siberian and Far Eastern Digital Expansion | Captures relationship primacy in Tomsk and Vladivostok before state-backed universal banks deploy physical branches. |
| Alternative Data Scoring Investment | Enables thinner pricing for qualified vocational cohorts using field-of-study earnings premiums and regional placement rates. |
| Technical College Partnership Program | Locks in federal guarantee eligibility for polytechnic credentials aligned with manufacturing sector workforce shortages. |
Research Methodology
Central Bank of Russia regulatory filings, Ministry of Education and Science subsidy program disclosures, and Federal Fund for Student Loans accreditation databases formed the secondary backbone for market sizing and policy trajectory assessment. Primary fieldwork encompassed interviews with education credit product managers at state-owned universal banks, university financial aid officers, and vocational school placement directors. Bottom-up and top-down triangulation validated enrollment-driven demand estimates against lender disbursement aggregates.
Bottom-up modeling segmented volume across loan type, repayment model, borrower category, and institution tier, while top-down analysis cross-checked aggregate credit growth against Central Bank sectoral exposure data. Segmentation dimensions encompassed federal versus private origination, deferred versus income-based servicing structures, undergraduate versus vocational populations, and public university versus technical college accreditation status. CAGRs were derived from enrollment projections, subsidy program expansion trajectories, and regional university development incentives. Forecast inputs incorporated ruble funding cost volatility assumptions and draft legislation progression on income-contingent repayment.
Caveats apply where Federal Fund for Student Loans accreditation criteria recalibration or Central Bank capital adequacy threshold adjustments could materially shift the outlook. Forecasts embed assumptions regarding Ministry of Finance legislative timelines and regional enrollment clustering persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Europe Auto Loan Market