
 Australia Automotive Financing Market | 2026-2036
Australia Automotive Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Automotive Financing Market Outlook
Subscription-based vehicle ownership and software-defined feature bundling is restructuring how Australian lenders structure repayment products and residual value calculations. Toyota Finance Australia leverages its captive finance model to anchor end-to-end customer retention across dealership networks. Commonwealth Bank (CommBank) competes through digital origination platforms that compress approval timelines for retail borrowers. Macquarie Leasing & Asset Finance specializes in novated leasing and salary packaging structures that dominate the fleet and corporate segments.
Australia automotive financing encompasses credit instruments, lease structures, and chattel mortgage products secured against passenger cars, commercial vehicles, and electric vehicles, with loan terms typically spanning 12 to 84 months and interest rates indexed to the Reserve Bank of Australia cash rate plus lender margins. The primary purpose is to enable vehicle acquisition without full upfront capital outlay while allowing lenders to monetize asset-backed cash flows over defined amortization schedules. Chattel mortgage products for commercial and fleet operators carry lower loss rates and generate superior margin pools compared with unsecured retail auto loans. Electric vehicle financing is expanding fastest within the vehicle type dimension as battery electric and plug-in hybrid models attract preferential rates from lenders seeking green asset portfolio growth.
ASIC enforces responsible lending conduct under the National Consumer Credit Protection Act, requiring verification of borrower suitability and sustainable debt serviceability before automotive loan approval. The Australian Prudential Regulation Authority (APRA) sets capital adequacy requirements for bank-owned finance entities including Westpac Banking Corporation and ANZ Banking Group, influencing their risk-weighted pricing for vehicle-secured credit. The Treasury's ongoing Buy Now Pay Later regulatory review threatens to capture emerging point-of-sale auto finance products under existing credit licensing frameworks. Stakeholders must monitor APRA's evolving macroprudential settings and state-level EV incentive durability to calibrate portfolio concentration and product mix decisions.
Market Dynamics
Electrification mandates and ASIC's responsible lending obligations under the NCCP Act are restructuring credit assessment protocols and procurement criteria across Australian automotive financing, forcing lenders to recalibrate risk-weighted pricing and residual value models for battery electric vehicle portfolios.
Growth Catalysts
- New South Wales EV incentives:State-based stamp duty exemptions and rebate programs accelerate buyer conversion toward battery electric vehicles, concentrating financed demand within premium passenger segments.
- NCCP Act enforcement:ASIC's responsible lending conduct requirements standardize borrower suitability verification, reducing systemic default risk and improving portfolio quality metrics for secured auto credit.
- Fleet electrification mandates:Corporate procurement policies favoring low-emission vehicles expand financed commercial portfolios, with novated leasing structures capturing salary packaging demand from enterprise customers.
Market Restraints
- Interest rate volatility:Reserve Bank of Australia cash rate movements transmit directly into lender margins, compressing net interest income on fixed-rate auto loan products during tightening cycles.
- Residual value uncertainty:Battery degradation curves and technology obsolescence risk for electric vehicles inflate lessor exposure on closed-end lease products with guaranteed buyback obligations.
- Buy Now Pay Later regulatory review:Treasury's examination of point-of-sale credit threatens to capture emerging auto finance products under existing credit licensing frameworks, increasing compliance overhead.
Strategic Opportunities
- Subscription-based ownership models:Software-defined vehicle feature bundling enables recurring revenue structures that decouple hardware financing from service monetization.
- Victoria state incentives:Complementary EV rebate programs create geographic diversification for green asset portfolio concentration beyond New South Wales.
- Chattel mortgage expansion:Commercial and fleet segments carry lower loss rates than unsecured retail auto loans, offering superior margin pools for specialized asset finance providers.
Industry Challenges
- Credit assessment automation:Digital origination platforms require real-time integration with income verification systems and bureau data, straining legacy core banking infrastructure.
- Greenwashing compliance:APRA's evolving climate risk disclosure standards demand granular carbon footprint tracking for labeled sustainable auto finance products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Automotive Financing Market |
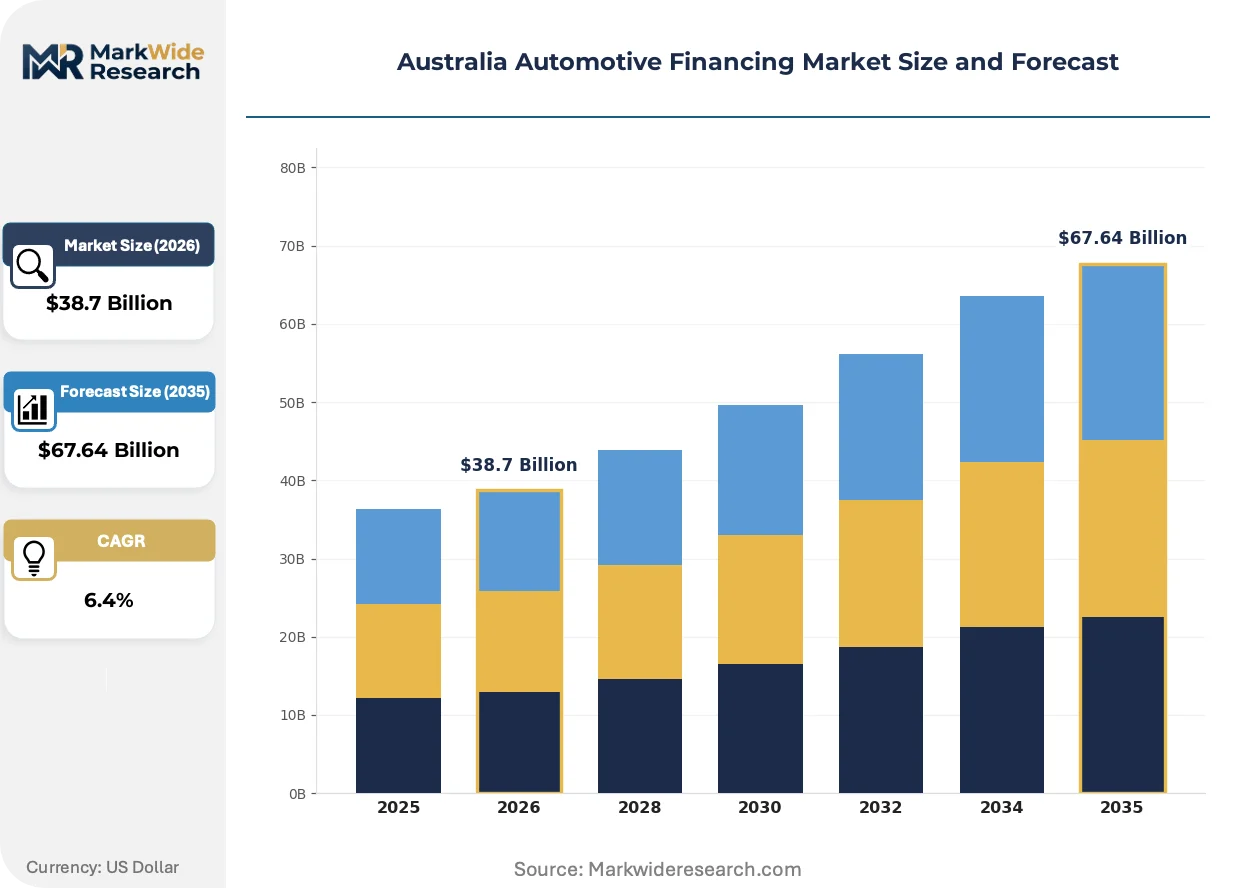
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Lease, Loan, Hire Purchase, Chattel Mortgage Customer Type: Individual Buyers, Dealerships, Fleet Operators, Corporates Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Electric Vehicles Loan Term: Short-Term, Medium-Term, Long-Term, Flexible |
| Companies Covered | Macquarie Leasing & Asset Finance, Westpac Banking Corporation, Toyota Finance Australia, Hyundai Capital Australia, Pepper Money, ANZ Banking Group, Commonwealth Bank (CommBank), SG Fleet Group, National Australia Bank (NAB), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Automotive Financing Market Strategic Shifts
Digital origination platforms and software-defined vehicle architectures are compressing approval timelines while enabling feature-based subscription monetization that restructures how Australian lenders calculate residual values and structure repayment products.
Embedded finance APIs are modularizing the point-of-sale credit experience, allowing dealership management systems to pre-populate loan applications with vehicle specification and buyer identity data. Fleet operators and retail dealerships are adopting these integrations fastest, cutting approval-to-delivery cycles from days to minutes. This technology is modularizing the traditional separation between vehicle selection and financing origination into a single interface.
ASIC's responsible lending enforcement under the NCCP Act mandates documented verification of borrower suitability and sustainable debt serviceability before automotive loan approval. The regulation forces lenders to maintain granular audit trails of income verification and expense assessment, elevating compliance technology spending. Retail auto loan originators face the steepest operational adaptation requirements as they retrofit digital workflows to capture mandatory verification evidence.
Fleet procurement is consolidating around total cost of ownership models that internalize carbon accounting and charging infrastructure access into lease rate calculations. Salary packaging providers and corporate fleet managers are displacing traditional capital purchase decisions with fully maintained operating leases. This behavioral shift concentrates demand within Victoria and New South Wales where state incentive stacking maximizes after-tax cost advantages for electric vehicle novated leases.
Australia Automotive Financing Market Segmentation
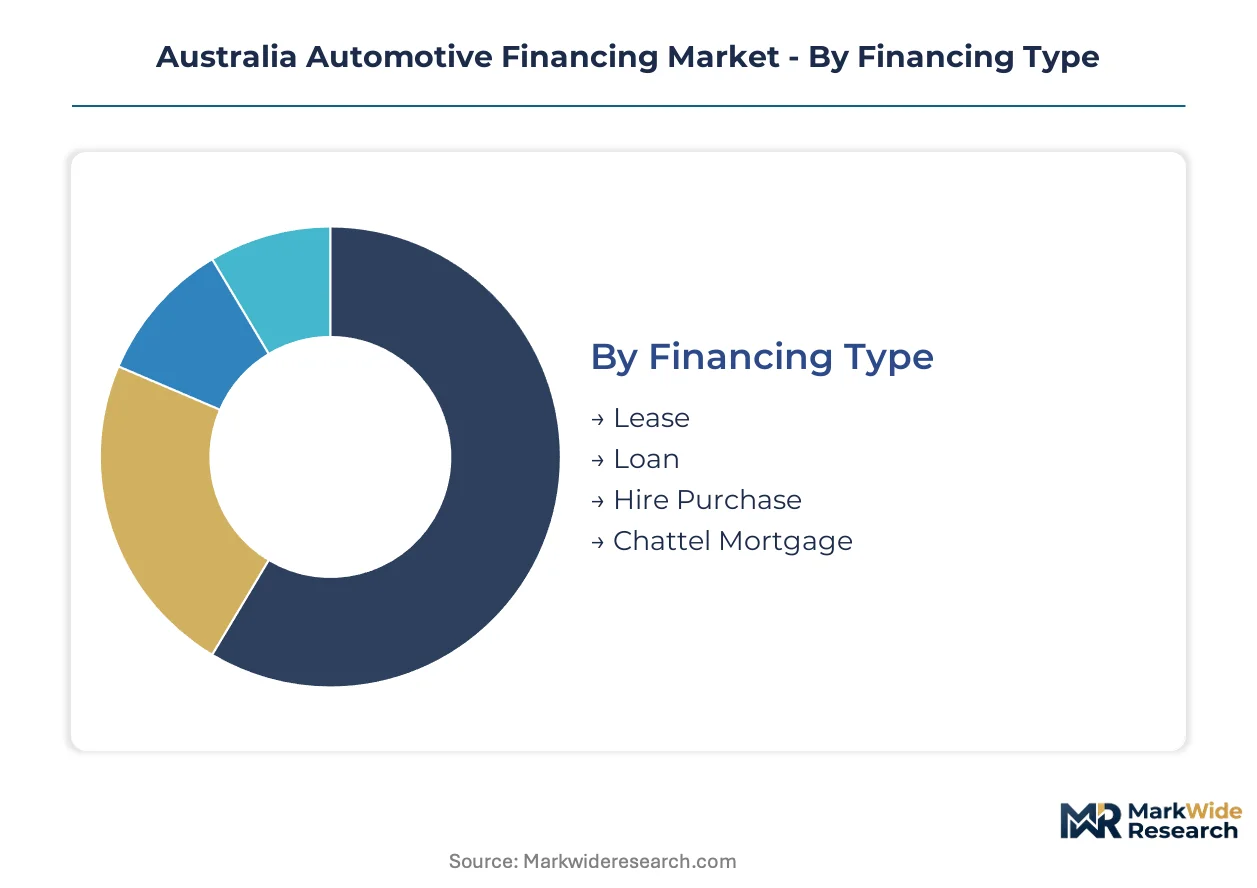
Segmentation in Australian automotive financing reveals how lender product design, risk pricing, and distribution strategy must adapt to divergent borrower cash flow patterns and asset utilization profiles across consumer, commercial, and fleet channels.
Financing Type:
Structural choice between ownership transfer and asset control separates borrowers seeking balance sheet assets from those prioritizing operational flexibility and tax efficiency.
- Lease:Closed-end and operating lease structures transfer residual value risk to lessors while providing fleet operators and corporates with off-balance-sheet treatment. Novated leasing through salary packaging providers dominates enterprise procurement in New South Wales and Victoria where state EV incentives maximize after-tax advantages.
- Loan:Secured term loans with fixed or variable interest rates indexed to the Reserve Bank of Australia cash rate represent the dominant retail channel. Digital origination platforms at major banks compress approval timelines to minutes, capturing individual buyer demand for passenger cars and SUVs.
- Hire Purchase:Installment structures with nominal ownership transfer at term completion serve commercial borrowers seeking depreciation benefits without upfront capital outlay.
- Chattel Mortgage:Asset-backed financing for business use delivers lower loss rates than unsecured retail products, concentrating specialist lender activity in fleet and SME segments.
Loan products lead volumes today; lease structures are gaining share fastest among electrifying corporate fleets.
Customer Type:
Procurement scale and credit assessment complexity vary dramatically between fragmented retail borrowers and concentrated enterprise accounts with negotiated fleet terms.
- Individual Buyers:Retail borrowers accessing dealer-arranged or direct-to-lender channels face ASIC's responsible lending verification under the NCCP Act. Income and expense documentation requirements elevate compliance technology spending for originators serving this segment.
- Dealerships:Floorplan financing and captive finance arrangements enable inventory carrying capacity, with Toyota Finance Australia anchoring end-to-end customer retention across its network.
- Fleet Operators:Multi-vehicle accounts with standardized replacement cycles negotiate total cost of ownership models incorporating charging infrastructure and carbon accounting.
- Corporates:Enterprise procurement policies mandating low-emission vehicles drive novated leasing volume through salary packaging specialists like Macquarie Leasing.
Individual buyers anchor current origination volumes; fleet operators are expanding most rapidly as electrification mandates reshape procurement.
Vehicle Type:
Asset depreciation curves and residual value uncertainty vary substantially between established internal combustion segments and emerging battery electric categories.
- Passenger Cars:Sedan and hatchback categories face compressed demand as buyer preference shifts toward larger vehicle formats, though financing penetration remains high among price-sensitive retail borrowers.
- Commercial Vehicles:Utility vans and light trucks serve trades and last-mile delivery operators, with chattel mortgage structures dominating due to business-use tax treatment.
- SUVs:Sport utility vehicles command premium pricing and longer loan terms, generating superior margin pools for lenders despite higher absolute exposure.
- Electric Vehicles:Battery electric and plug-in hybrid models attract preferential rates from lenders building green asset portfolios, with demand concentrating in New South Wales and Victoria where state-based stamp duty exemptions and rebate programs accelerate conversion.
SUVs dominate current financed volumes; electric vehicles are climbing the fastest as technology costs converge with conventional powertrains.
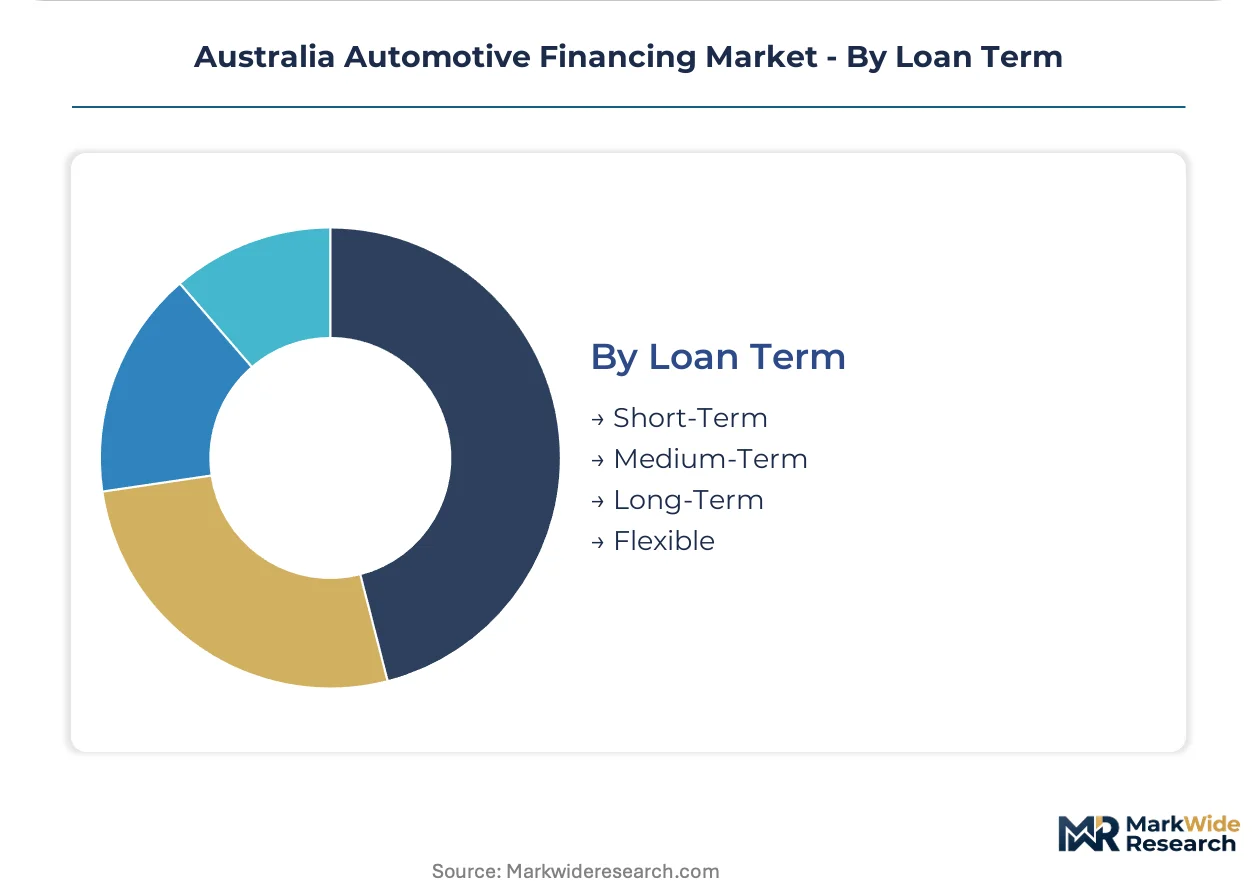
Loan Term:
Duration selection reflects borrower cash flow stability, asset replacement cycles, and interest rate risk tolerance across tightening and easing monetary policy environments.
- Short-Term:12-36 month structures minimize interest burden for borrowers with liquidity or those anticipating early vehicle replacement, common among fleet operators with standardized cycling policies.
- Medium-Term:37-60 month products balance affordable monthly payments with reasonable total interest cost, representing the retail standard for passenger cars and SUVs.
- Long-Term:61-84 month amortizations reduce monthly obligations but extend negative equity risk, attracting borrowers in higher interest rate environments.
- Flexible:Variable duration products with redraw or early termination options accommodate irregular income patterns among gig economy and seasonal workers.
Medium-term products capture the largest share of origination volume; flexible structures are expanding most quickly as non-standard employment patterns proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland trails New South Wales and Victoria in electric vehicle financing penetration, while Western Australia's mining-driven commercial vehicle demand sustains chattel mortgage volumes that outpace passenger car lending growth.
New South Wales
Stamp duty exemptions and rebate programs for battery electric vehicles accelerate financed buyer conversion toward premium passenger segments. ASIC's responsible lending conduct requirements under the NCCP Act standardize borrower verification protocols across Sydney-based lender operations. The Sydney-Canberra corridor concentrates novated leasing activity as salary packaging providers capture enterprise fleet electrification mandates.
Victoria
Complementary state-based EV incentives create geographic diversification for green asset portfolio concentration beyond neighboring New South Wales. The state's consumer credit framework aligns with federal NCCP Act enforcement, requiring documented income verification for Melbourne-originated retail auto loans. Greater Melbourne anchors captive finance operations for multinational automotive brands seeking end-to-end dealership network retention.
Queensland
Commercial vehicle financing for mining and agricultural operators sustains chattel mortgage demand despite slower electric vehicle adoption in passenger segments. State-level regulatory harmonization with federal credit protection standards ensures consistent responsible lending enforcement across Brisbane-based originators. The Brisbane-Gold Coast corridor supports fleet leasing growth as regional logistics operators expand electrified last-mile delivery capacity.
Western Australia
Resource sector procurement drives heavy commercial vehicle financing volumes that dwarf passenger car lending in absolute dollar terms. APRA's capital adequacy requirements for bank-owned finance entities influence risk-weighted pricing structures at Perth-based lender operations. The Perth metropolitan area concentrates specialist asset finance providers serving mining fleet operators with standardized replacement cycles.
South Australia
Smaller market scale enables faster regulatory adaptation as local lenders pilot digital origination platforms ahead of national rollout schedules. The state's alignment with federal consumer credit frameworks ensures NCCP Act compliance without additional jurisdictional overlay. Adelaide-based fleet operators leverage total cost of ownership models incorporating charging infrastructure access into lease rate calculations.
Australia Automotive Financing Market Competitive Environment
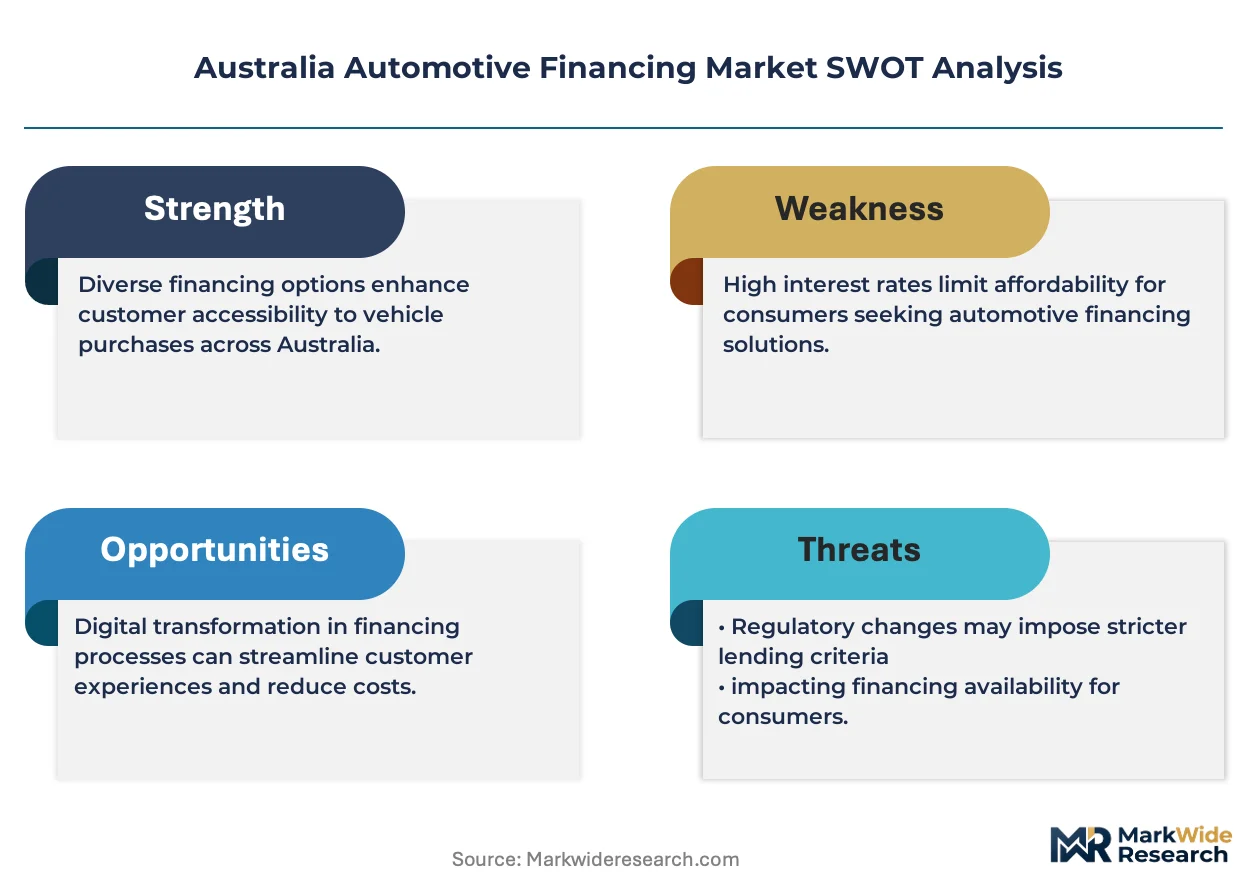
Top-tier vendors anchor the banking segment, while specialized leasing firms and captive finance units occupy distinct competitive tiers. The market structure concentrates around four major banking groups alongside niche providers serving fleet and salary packaging segments. Strategic archetypes include integrated banking groups with digital origination capabilities, captive finance arms tethered to automotive OEM distribution networks, and specialist asset finance providers focused on commercial and novated leasing structures. Competitive moves center on embedded finance API development and portfolio diversification into electric vehicle green asset categories.
Among the banking group tier, Commonwealth Bank (CommBank) and Westpac Banking Corporation exemplify integrated lenders with national digital origination platforms compressing approval timelines. Macquarie Leasing & Asset Finance occupies a specialist position within the novated leasing and salary packaging segment, anchoring enterprise fleet procurement activity. Toyota Finance Australia represents the captive finance archetype, leveraging OEM-tethered distribution to structure end-to-end customer retention across dealership networks.
| Leading Market Players |
|---|
| Macquarie Leasing & Asset Finance |
| Westpac Banking Corporation |
| Toyota Finance Australia |
| Hyundai Capital Australia |
| Pepper Money |
| ANZ Banking Group |
| Commonwealth Bank (CommBank) |
| SG Fleet Group |
| National Australia Bank (NAB) |
| Others |
Value Chain & Pricing Dynamics
Fleet operator consolidation around novated leasing structures in New South Wales and Victoria anchors pricing power with salary packaging providers who bundle vehicle acquisition with tax-optimized financing products. This buyer archetype concentration enables volume-based rate negotiations that compress margins for retail auto loan originators competing outside enterprise procurement channels.
Pricing Analysis
Capacity additions in embedded finance API development are reshaping price floors for digital origination platforms across Australian automotive lending. Three-tier pricing structure across premium captive finance, standard bank-direct, and economy non-bank lender levels stratifies by approval speed and residual value guarantee depth. Cost compression in unsecured retail auto loans is intensifying because ASIC's NCCP Act compliance elevates verification technology spending. Individual buyers accessing dealer-arranged channels exhibit highest price sensitivity; fleet operators negotiating total cost of ownership models demonstrate lowest sensitivity due to tax arbitrage benefits.
Supply Chain Analysis
Vehicle sourcing rests on Japanese, South Korean, and Thai manufacturing hubs that feed Australian import-dependent automotive markets. Lithium-ion battery cells, semiconductor components, and steel feedstock constitute critical input dependencies with concentrated Asian supply bases. Single-source vulnerability in battery cell supply from Chinese producers exposes lessors to residual value volatility when replacement cost curves shift unpredictably. Distribution runs through captive finance arms at OEM dealership networks, direct-to-consumer digital platforms at major banks, and specialist novated leasing intermediaries serving corporate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's state-level EV incentive divergence creates geographic arbitrage opportunities, with Victoria's complementary rebate programs offering cost advantages against New South Wales procurement despite harmonized federal credit protection standards.
For Market Incumbents: Deploy embedded finance API integration to defend against fintech point-of-sale disruptors threatening dealership channel control. Commonwealth Bank and Westpac should deepen proprietary digital origination capabilities while Toyota Finance Australia extends captive retention models into subscription-based ownership products. NCCP Act compliance technology spending represents the critical defensive investment area. For New Entrants and Emerging Players: Begin with Queensland commercial vehicle financing where mining and agricultural chattel mortgage demand sustains specialist lender margins below major bank radar. White-space targets include Western Australia resource sector fleet procurement and South Australia pilot markets for accelerated digital platform rollout. A go-to-market angle through total cost of ownership modeling with integrated charging infrastructure access captures electrifying corporate procurement. For Investors and Strategic Acquirers: Specialist asset finance providers with novated leasing infrastructure are the most active acquirer targets in this space as banking groups seek fleet segment exposure. Long-term viability centers on green asset portfolio construction capability across the medium-term projection horizon. Watch APRA's evolving climate risk disclosure standards as the inflection indicator for sustainable auto finance product differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Development | Compresses approval timelines from days to minutes at dealership point-of-sale. |
| Green Asset Portfolio Construction | Captures state-based EV incentive arbitrage across New South Wales and Victoria. |
| NCCP Act Compliance Technology | Enables documented borrower verification for ASIC audit trail requirements. |
| Subscription-Based Ownership Models | Decouples hardware financing from software-defined feature monetization streams. |
| Chattel Mortgage Expansion | Accesses lower loss rate commercial segments in mining and agricultural verticals. |
Study Parameters
Multiple input streams — primary interviews with captive finance executives, digital platform engineers, and fleet procurement managers; secondary validation through APRA prudential filings, ASIC regulatory guidance, and vehicle registration databases; plus customs trade data — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations captured perspectives from novated leasing specialists, dealership operations directors, and corporate salary packaging administrators. Secondary sources encompassed Reserve Bank of Australia cash rate policy statements, state treasury EV incentive program documentation, and competitor annual report disclosures.
Data-stream reconciliation anchored forecast outputs across financing type, customer segment, vehicle propulsion architecture, and state-level regulatory cluster dimensions. CAGRs were derived from trend extrapolation calibrated against macroeconomic scenario modeling. Industry-specific forecast inputs included electrification mandate timelines and residual value depreciation curves for battery electric vehicle portfolios throughout the projection horizon.
Several conditions sit outside the modeled scope, including potential Treasury capture of point-of-sale auto finance under Buy Now Pay Later licensing frameworks and unanticipated state incentive program discontinuation. Forecasts reflect stated assumptions regarding RBA monetary policy trajectory and EV technology cost convergence. A small set of named triggers — APRA macroprudential tightening, ASIC enforcement pattern shifts, and battery supply disruption events — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Housing Finance Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Micro Lending Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Global Revenue-Based Financing Market