
 Micro Lending Market | 2026-2036
Micro Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Lending Market Intelligence
ISO 22222 certification for personal financial planning is rotating as a de facto gatekeeper for institutional credibility among micro lending platforms. Grameen Bank leverages its cooperative ownership model to sustain grassroots borrower loyalty across rural Bangladesh. LendingClub Corporation anchors its position through algorithmic credit scoring that dominates the US peer-to-peer origination pipeline. Kiva Microfunds differentiates via zero-interest crowdfunding structures that compete for socially motivated capital pools.
Micro lending denotes unsecured or minimally collateralized credit disbursed in small principal amounts, typically under $1,000, with repayment cycles spanning 30 days to 24 months and interest structures calibrated to borrower cash-flow cadence rather than fixed amortization schedules. Its primary commercial purpose is to bridge liquidity gaps for excluded borrowers who lack formal credit histories, collateral assets, or banking relationships. Personal loans and business loans represent the deepest margin pools where risk-based pricing stratifies across informal wage workers and registered microenterprises. Peer-to-peer platforms and microfinance institutions constitute the fastest-growing funding source channel as digital onboarding displaces branch-based origination. Women entrepreneurs form a structurally underserved borrower profile where repayment rates consistently outperform portfolio averages.
India's RBI mandates priority-sector lending quotas while the US Consumer Financial Protection Bureau enforces truth-in-lending disclosure standards that shape product design and pricing transparency across originators. The EU's Consumer Credit Directive and GDPR compliance requirements add layered operational costs for cross-border platform expansion. Stakeholders must monitor how open banking API regulations and real-time payment infrastructure investments reshape borrower acquisition economics and default prediction accuracy.
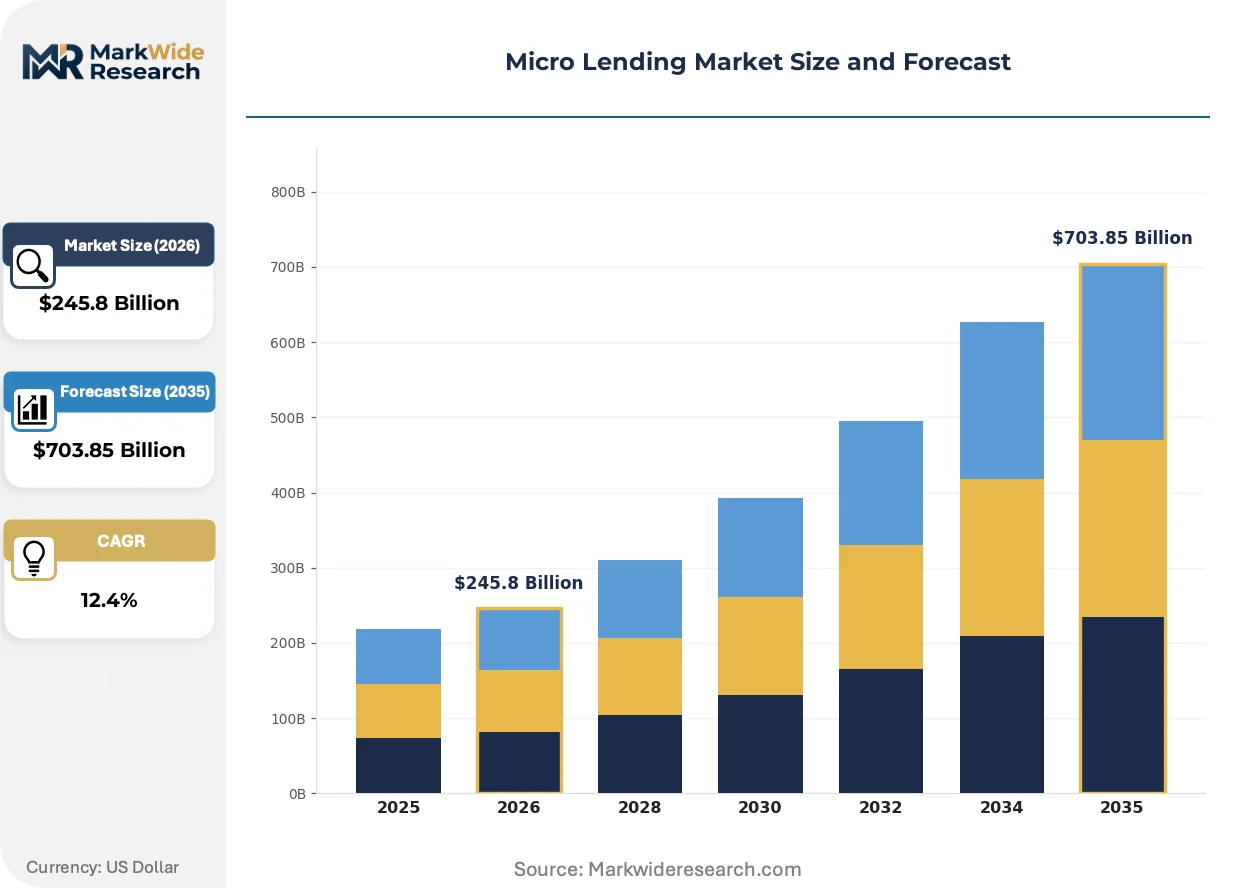
Market Dynamics
Digital-first onboarding protocols are compressing origination timelines from weeks to hours across micro lending platforms, while Aadhaar-linked KYC infrastructure in India and similar biometric identity frameworks in Bangladesh and Indonesia are redefining borrower verification economics.
Growth Catalysts
- RBI Priority-Sector Lending Mandates:India's central bank requires scheduled commercial banks to allocate 40% of adjusted net bank credit to priority sectors including micro enterprises, forcing formal credit expansion into previously excluded borrower pools.
- Mobile Penetration Surge:Smartphone ownership among rural wage workers across Southeast Asia enables app-based loan applications, repayment scheduling, and real-time disbursement tracking without physical branch infrastructure.
- Peer-to-Peer Platform Architecture:Algorithmic credit scoring engines match retail capital providers directly with verified borrowers, eliminating intermediary margin extraction and lowering effective interest burdens.
Market Restraints
- Informal Collateral Limitations:Absence of formal property titles or registered assets among target borrowers restricts recovery options during default events, elevating loss-given-default assumptions in pricing models.
- Cross-Border Regulatory Friction:EU GDPR compliance requirements impose data localization and consent management costs on platforms seeking to operate across multiple European jurisdictions.
- Substitute Informal Finance:Rotating savings and credit associations (ROSCAs) and moneylender networks retain borrower loyalty through relationship-based flexibility that standardized digital products cannot replicate.
Strategic Opportunities
- Women Entrepreneur Segments:Structurally underserved female-led microenterprises demonstrate consistently superior repayment performance, creating a risk-adjusted return premium for targeted products.
- Open Banking API Integration:Real-time transaction data access through standardized banking interfaces enables cash-flow-based underwriting that transcends traditional credit bureau limitations.
- Zero-Interest Crowdfunding Structures:Socially motivated capital pools seek non-extractive deployment vehicles, matching philanthropically oriented lenders with community-verified borrowers.
Industry Challenges
- ISO 22222 Certification Complexity:Personal financial planning accreditation demands specialized training infrastructure and audit protocols that stretch operational capacity at smaller institutions.
- Legacy Core Banking Integration:Microfinance institutions migrating from paper-based systems to digital platforms face middleware development costs and data migration risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Lending Market |
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $703.85 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Personal Loans, Business Loans, Education Loans, Agricultural Loans Borrower Profile: Women Entrepreneurs, Small Business Owners, Students, Farmers Funding Source: Microfinance Institutions, NGOs, Peer-to-Peer Platforms, Crowdfunding Repayment Terms: Short-Term, Flexible, Installment Payments, Lump Sum |
| Companies Covered | LendingClub Corporation, Funding Circle, Zopa Bank Limited, Grameen Bank, Accion International, ASA International, Bandhan Bank, Kiva Microfunds, OnDeck Capital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Lending Market Strategic Shifts & Innovations
Algorithmic decisioning is displacing human judgment across origination workflows, while regulatory sandboxes and biometric identity infrastructure are compressing the gap between informal borrower profiles and formal credit access.
Machine learning credit scoring is displacing traditional bureau-dependent underwriting in emerging market micro lending. Rural wage workers without formal credit histories now access capital through alternative data proxies including mobile money transaction patterns and utility payment regularity. This displacement is compressing default prediction timelines from months to real-time behavioral signals.
India's RBI has mandated video-based customer identification processes for remote account opening, reducing physical branch dependency for KYC completion. The industrial consequence is a surge in fully digital micro lending platforms operating without brick-and-mortar presence. Bangladesh and Indonesia are observing similar regulatory trajectory, with their central banks piloting equivalent remote verification frameworks.
Borrower preference is rotating toward embedded finance interfaces where credit surfaces within agricultural input marketplaces and ride-hailing driver apps rather than standalone lending platforms. Disbursement velocity and contextual relevance are displacing rate shopping as primary selection criteria. This shift concentrates in India, where UPI infrastructure enables seamless loan disbursement into merchant settlement flows.
Micro Lending Market Segmentation
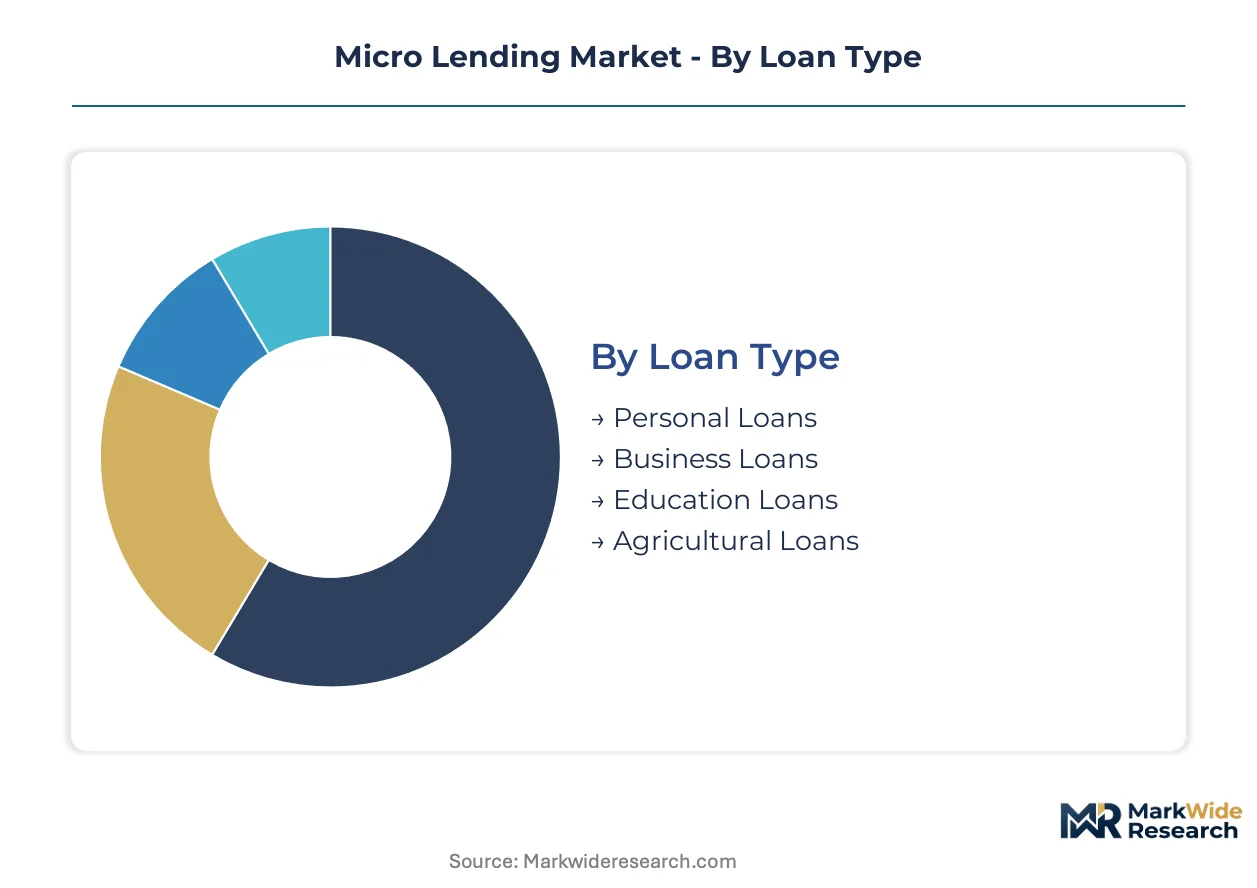
Micro lending segmentation reveals how capital flows differentially across borrower circumstances and funding architectures. Loan type and borrower profile together determine risk-adjusted pricing, while funding source and repayment structure shape operational economics for originators.
Loan Type:
Margin pools concentrate in products serving borrowers with irregular cash flows and limited collateral, where risk-based pricing extracts premium returns.
- Personal Loans:Unsecured credit for consumption smoothing, medical emergencies, or household liquidity gaps. Demand clusters among informal wage workers in India and Bangladesh where Aadhaar-linked KYC enables rapid disbursement without formal income documentation.
- Business Loans:Working capital for inventory, equipment, or operational expansion of microenterprises. Small business owners across Southeast Asia drive origination volume as RBI priority-sector mandates force commercial banks downstream into previously excluded segments.
- Education Loans:Tuition and fee financing for vocational or skills training programs. Students in Indonesia and Vietnam access these through mobile-first platforms integrated with technical institute enrollment systems.
- Agricultural Loans:Seasonal input financing for seeds, fertilizers, and harvest labor. Farmers in rural Bangladesh and India's Maharashtra state rely on Grameen-style cooperative structures with harvest-linked repayment schedules.
The dominant share belongs to Personal Loans, while Business Loans are expanding most quickly as formalization of microenterprises accelerates across South Asia.
Borrower Profile:
Customer acquisition costs vary dramatically across profiles, with some segments demonstrating superior repayment discipline that justifies targeted outreach investment.
- Women Entrepreneurs:Female-led microenterprises with documented repayment rates exceeding portfolio averages. RBI mandates and social impact mandates from development finance institutions channel preferential capital toward this segment across India and Bangladesh.
- Small Business Owners:Registered or unregistered microenterprises seeking inventory or equipment financing. Digital onboarding via UPI-linked merchant accounts in India compresses verification timelines from weeks to hours.
- Students:Enrolled learners financing tuition, devices, or living expenses during training. Demand surfaces through embedded finance partnerships with vocational platforms in Indonesia and the Philippines.
- Farmers:Agricultural producers with seasonal income patterns requiring harvest-aligned repayment structures. Crop insurance linkages and weather-indexed products from microfinance institutions reduce default correlation.
Women Entrepreneurs command the deepest risk-adjusted returns, while Small Business Owners are gaining share fastest as digital KYC infrastructure matures.
Funding Source:
Capital cost structures diverge sharply between balance-sheet lenders and marketplace architectures, with implications for borrower pricing and platform scalability.
- Microfinance Institutions:Regulated deposit-taking or non-deposit entities with branch-based origination heritage. India's NBFC-MFIs and Bangladesh's NGO-MFIs dominate deployed capital volume through priority-sector lending arbitrage.
- NGOs:Mission-driven entities subsidizing interest through donor grants or concessional debt. Kiva Microfunds exemplifies zero-interest crowdfunding structures attracting socially motivated capital pools.
- Peer-to-Peer Platforms:Algorithmic marketplaces matching retail lenders with verified borrowers. LendingClub Corporation's credit scoring engines anchor US origination while Indian platforms leverage RBI's video-KYC protocols for remote onboarding.
- Crowdfunding:Community-based capital aggregation with social verification mechanisms. This channel concentrates in diaspora-funded projects and disaster response micro lending across Southeast Asia.
Microfinance Institutions retain the largest deployed base, though Peer-to-Peer Platforms are climbing the fastest as regulatory sandboxes legitimize marketplace lending across multiple jurisdictions.
Repayment Terms:
Structural flexibility in repayment design determines product-market fit for borrowers with lumpy or unpredictable income streams.
- Short-Term:30-90 day cycles with single or few payments, typical of payday-adjacent products and emergency liquidity provision. Mobile money repayment rails in Kenya and Nigeria enable automated collection.
- Flexible:Repayment amounts and dates adjustable to borrower cash flow realization. Agricultural borrowers in India's Punjab and Haryana states prefer harvest-aligned schedules over fixed monthly obligations.
- Installment Payments:Regular fixed-amount deductions aligned with wage or revenue cycles. Auto-debit from UPI-linked accounts dominates Indian digital micro lending, reducing collection costs.
- Lump Sum:Single end-of-term repayment with interest capitalized, common in trade finance and seasonal working capital products. ROSCA-compatible structures retain loyalty among community-based borrower groups.
Installment Payments anchor the majority of outstanding volume, yet Flexible structures are gaining traction fastest as cash-flow-based underwriting displaces traditional fixed-schedule products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI priority-sector lending mandates are forcing commercial banks downstream into previously excluded borrower pools across South Asia, while biometric identity infrastructure and mobile penetration reshape origination economics in emerging markets worldwide.
India
Small business owners in Maharashtra and Karnataka accelerate digital onboarding as UPI-linked merchant accounts compress verification timelines from weeks to hours. RBI's video-KYC protocols for remote account opening enable fully digital platforms to operate without brick-and-mortar presence. Mumbai and Bangalore anchor the deepest concentration of peer-to-peer lending infrastructure.
Bangladesh
Grameen-style cooperative structures sustain grassroots borrower loyalty among rural agricultural producers with harvest-linked repayment schedules. The central bank pilots remote verification frameworks equivalent to India's video-KYC standards. Dhaka and rural delta regions concentrate microfinance institution branch networks serving female-led microenterprises.
United States
Algorithmic credit scoring engines match retail capital providers directly with verified borrowers, eliminating intermediary margin extraction. The Consumer Financial Protection Bureau enforces truth-in-lending disclosure standards shaping product design and pricing transparency. San Francisco and New York anchor marketplace lending platform headquarters.
Indonesia
Mobile-first platforms integrate with vocational institute enrollment systems to surface education loan demand among technical students. The central bank advances biometric identity frameworks redefining borrower verification economics. Jakarta and Surabaya concentrate digital lending infrastructure targeting informal wage workers.
United Kingdom
Peer-to-peer platforms leverage algorithmic marketplaces to lower effective interest burdens for borrowers excluded from traditional banking relationships. FCA regulatory frameworks legitimize marketplace lending across the jurisdiction. London anchors the European headquarters concentration for alternative lending platforms.
Micro Lending Market Key Industry Players
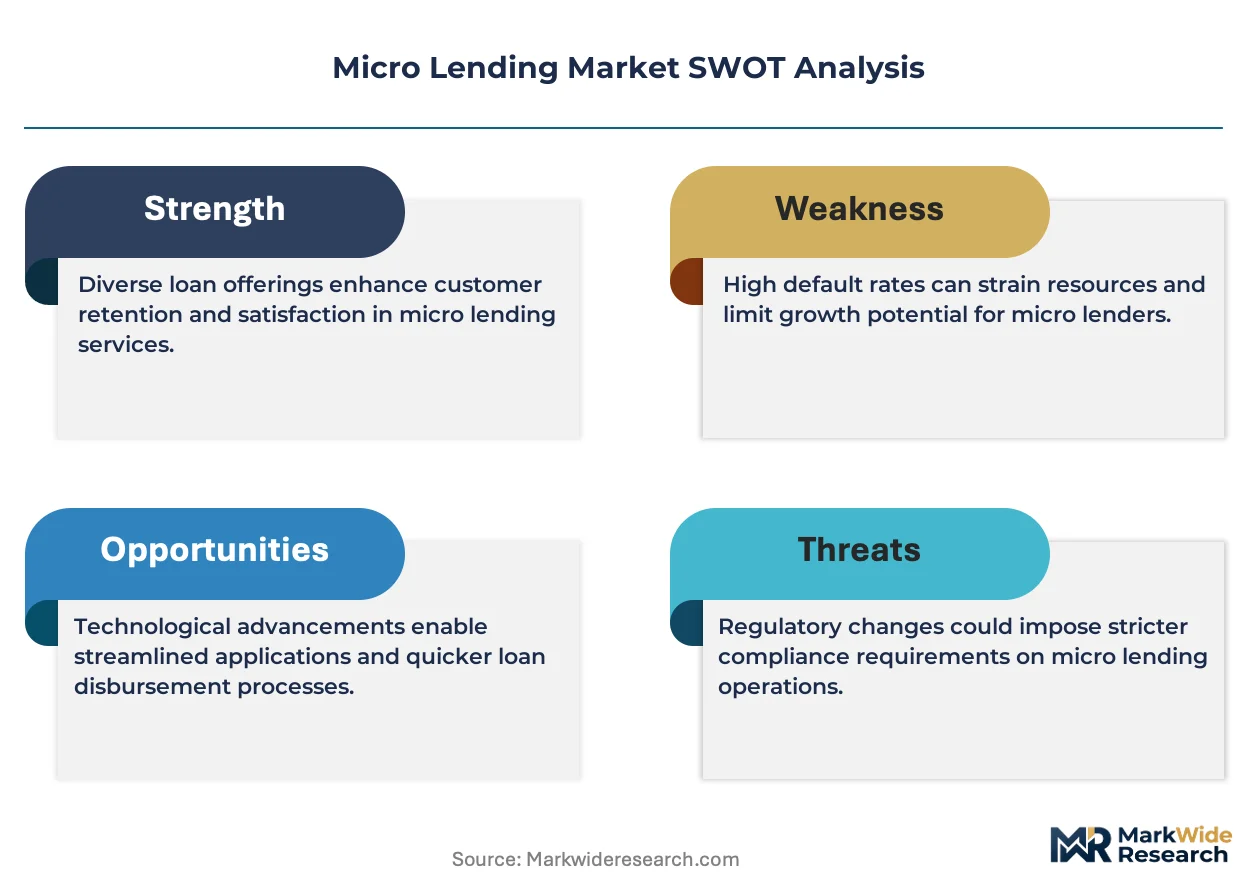
Player mix skews toward algorithmic marketplace operators and cooperative ownership structures. The competitive field fragments across three tiers: global peer-to-peer platforms with proprietary credit scoring engines, deposit-taking microfinance institutions with branch-based origination heritage, and mission-driven NGOs subsidizing interest through donor capital. Strategic moves concentrate on open banking API integration and biometric KYC infrastructure deployment.
Within the cooperative ownership tier, Grameen Bank exemplifies grassroots borrower loyalty structures across rural South Asia. Kiva Microfunds occupies a position representing zero-interest crowdfunding architectures attracting socially motivated capital pools. LendingClub Corporation anchors the algorithmic credit scoring archetype dominating marketplace origination pipelines.
| Leading Market Players |
|---|
| LendingClub Corporation |
| Funding Circle |
| Zopa Bank Limited |
| Grameen Bank |
| Accion International |
| ASA International |
| Bandhan Bank |
| Kiva Microfunds |
| OnDeck Capital |
| Others |
Cost & Logistics Intelligence
ISO 22222 certification gates institutional credibility for micro lending platforms while simultaneously stratifying price differentiation across accredited and non-accredited originators. India's RBI video-KYC protocols and the US Consumer Financial Protection Bureau disclosure standards compress supply qualification timelines while elevating compliance costs that pass through to borrower pricing.
Pricing Analysis
Cost-plus contracts indexed to priority-sector lending arbitrage spreads dominate Indian microfinance institution pricing, with RBI-mandated rate caps compressing margins for non-compliant players. Risk-based pricing stratifies across Aadhaar-verified informal wage workers and unregistered microenterprises, where cash-flow-based underwriting commands premium spreads over bureau-dependent scoring. Price differentiation hinges on certification tier and geographic delivery cost, with digital-first platforms in Mumbai and Bangalore extracting efficiency premiums over branch-based competitors. Margins are tightening due to algorithmic marketplace entry, while small business owners with UPI-linked merchant accounts demonstrate lowest price sensitivity given embedded finance convenience.
Supply Chain Analysis
Port congestion on the Singapore-Jakarta trade lane elevates inbound logistics costs for hardware-dependent biometric KYC infrastructure deployed across Southeast Asian platforms. Capital concentration rests on India, Bangladesh, and Indonesia as the three dominant funding origination hubs, with India's NBFC-MFIs and Bangladesh's NGO-MFIs anchoring deposit-taking capacity. Raw material dependencies include smartphone handsets for borrower-facing apps, server infrastructure for algorithmic scoring engines, and biometric sensor hardware for remote verification. Single-source vulnerability concentrates in Aadhaar-stack API providers and UPI rail operators. Distribution runs through peer-to-peer marketplaces, mobile network operator partnerships, and embedded finance integrations with agricultural input suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among algorithmic marketplace operators as LendingClub-style credit scoring engines consolidate retail capital provider relationships. This fragmentation among traditional microfinance institutions with branch-based heritage weakens their pricing leverage against digitally native competitors.
For Market Incumbents: Compound defensive positioning through ISO 22222 certification investment and backward integration into proprietary biometric KYC infrastructure. Threats from zero-interest crowdfunding structures and open banking API entrants demand channel control reinforcement. Priority levers include vertical integration into data analytics capabilities and capacity addition in Maharashtra and Karnataka's UPI-dense merchant corridors. For New Entrants and Emerging Players: Rural agricultural borrower segments in India's Punjab and Haryana states represent the most penetrable white-space target, where harvest-linked flexible repayment products remain underserved by fixed-schedule incumbents. Women entrepreneur segments in Bangladesh's delta regions offer second-mover advantage given documented repayment outperformance. Go-to-market execution should anchor in embedded finance partnerships with agricultural input marketplaces and ride-hailing driver platforms. For Investors and Strategic Acquirers: RBI's video-KYC mandate and equivalent remote verification frameworks piloted by Bangladesh Bank and Bank Indonesia reshape the acquisition landscape toward algorithmic marketplace operators with regulatory sandbox approvals. Long-term viability favors platforms with demonstrated cash-flow-based underwriting capabilities and open banking API integration. Acquisition target archetypes include mid-tier peer-to-peer platforms with proprietary scoring engines but subscale capital provider bases. The signal to watch is central bank digital currency interoperability announcements affecting disbursement velocity economics.| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Integration | Real-time transaction data access through RBI-mandated interfaces transcends traditional credit bureau limitations for informal borrowers. |
| Biometric KYC Infrastructure Deployment | Aadhaar-linked and video-based verification protocols eliminate physical branch dependency across Indian and Bangladeshi markets. |
| Zero-Interest Crowdfunding Structure | Kiva-style architectures attract socially motivated capital pools seeking non-extractive deployment vehicles. |
| Embedded Finance Partnership | Credit surfacing within agricultural marketplaces and driver apps displaces standalone platform rate shopping. |
| Algorithmic Credit Scoring Investment | Machine learning engines displace human judgment and compress default prediction timelines to real-time behavioral signals. |
Research Approach
A standing panel of microfinance institution CEOs, peer-to-peer platform risk officers, central bank regulatory leads, and agricultural cooperative managers provided ongoing calibration across primary fieldwork. Secondary validation drew from RBI circulars, Bangladesh Bank policy frameworks, SEC filings for US-listed marketplace lenders, and priority-sector lending performance disclosures. Bottom-up origination volume estimates triangulated against top-down addressable market calculations for informal borrower populations.
Consistency checks validated model outputs against external benchmarks including central bank microfinance portfolio reports and peer-to-platform transaction disclosures. The analytical framework segmented across loan type, borrower profile, funding source, and repayment structure dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical disbursement velocity and mobile penetration trajectories. Industry-specific forecast inputs included UPI transaction growth rates and biometric identity infrastructure deployment schedules.
Forecasts assume regulatory continuity in RBI priority-sector mandates, EU GDPR compliance requirements, and US Consumer Financial Protection Bureau disclosure standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Asia-Pacific Used Car Financing Market