
 Global Financial Leasing Market | 2026-2036
Global Financial Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Financial Leasing Market Analysis
Institutional-grade lease underwriting is reorganizing competitive dynamics across the Global Financial Leasing Market. BNP Paribas leverages its pan-European balance sheet to dominate cross-border equipment finance for mid-market industrials. Wells Fargo Bank anchors North American commercial vehicle leasing through captive relationships with fleet operators. SMBC Group specializes in structured aviation and maritime leases across Asia-Pacific corridors, sustaining deep ties with export-credit agencies.
Financial leasing denotes a contractual arrangement where the lessor purchases an asset and transfers substantially all risks and rewards of ownership to the lessee, with lease terms typically matching the asset's economic life of three to ten years and residual value calculations determining end-of-term options. This mechanism preserves lessee working capital while providing lessors with collateralized yield streams and potential tax-advantaged depreciation benefits. Equipment leasing under the Asset Type dimension leads transaction volumes, particularly for manufacturing and logistics infrastructure, while Technology leasing represents the fastest-expanding category as enterprises shift from capex to opex models for cloud infrastructure and enterprise software. Sale and Leaseback structures within Lease Structure concentrate margin pools, offering corporates immediate liquidity without operational disruption.
The Basel Committee on Banking Supervision shapes capital reserve requirements for lease exposures, compelling institutions to optimize risk-weighted asset calculations across portfolios. The European Banking Authority enforces IFRS 16 disclosure standards, transforming how lessees report obligations and altering credit assessment frameworks. The Financial Accounting Standards Board in the United States maintains parallel ASC 842 guidelines, creating compliance complexity for multinational lessors operating across jurisdictions. Stakeholders must monitor divergence between regional accounting standards and emerging climate-risk disclosure mandates that could reclassify certain asset categories.
Market Dynamics
Basel III capital adequacy frameworks are forcing banks to restructure off-balance-sheet lease vehicles, compressing risk-weighted asset calculations while preserving yield streams through synthetic securitization and residual value insurance overlays.
Growth Catalysts
- Healthcare capital preservation:Hospital systems in Germany, Japan, and Brazil are expanding medical equipment leasing programs to maintain liquidity for patient care investments.
- IFRS 16 disclosure mandates:The European Banking Authority's enforcement of lease obligation transparency is standardizing credit assessment frameworks across EU member states.
- Sale-and-leaseback modernization:China's state-owned manufacturers deploy these structures to upgrade aging production lines without balance-sheet expansion.
Market Restraints
- Residual value volatility:Aircraft and maritime asset valuations fluctuate with fuel cost cycles and trade route disruptions, compressing lessor margin buffers.
- Regulatory fragmentation:Divergence between ASC 842 in the United States and IFRS 16 in Europe creates compliance complexity for multinational lessors.
- Interest rate sensitivity:Central bank policy shifts in major economies directly pressure lease pricing spreads and portfolio yields.
Strategic Opportunities
- Technology leasing expansion:Enterprise software and cloud infrastructure migrations create demand for opex-model financing alternatives to traditional capex procurement.
- India's infrastructure buildout:The country's PLI scheme and renewable energy targets generate equipment financing demand for solar arrays and manufacturing automation.
- Green lease structuring:EU Green Deal taxonomy alignment offers preferential capital treatment for energy-efficient asset classes and circular economy equipment.
Industry Challenges
- Specialized underwriting talent:Complex residual value modeling for technology assets requires actuarial and data science capabilities that traditional equipment finance teams lack.
- Legacy system integration:Lessors migrating to automated lease management platforms face data migration friction and workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Financial Leasing Market |
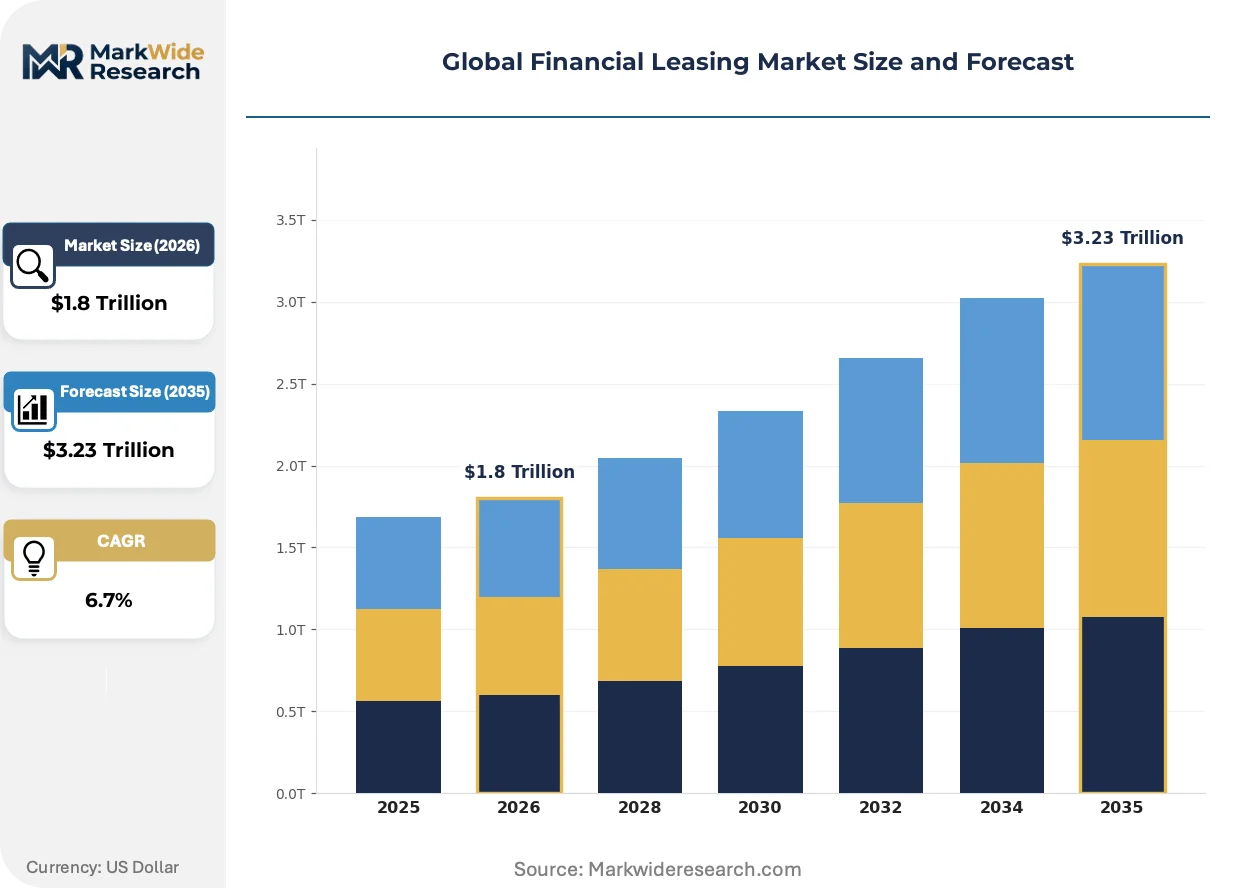
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $3.23 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Growth, Expansion, Maturity Asset Type: Vehicles, Equipment, Real Estate, Technology Client Type: SMEs, Corporations, Startups, Government Lease Structure: Operating Lease, Financial Lease, Sale and Leaseback, Master Lease |
| Companies Covered | Fifth Third Bank, SMBC Group, Sumitomo Mitsui Finance and Leasing, Texas Capital Bancshares, Commerce Bancshares, BNP Paribas, Wells Fargo Bank, North Star Leasing, HSBC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Financial Leasing Market Emerging Trajectories
Digital asset tracking and embedded finance are restructuring how lessors monitor collateral performance and originate transactions, compressing underwriting cycles while expanding addressable borrower segments.
Blockchain-enabled smart contracts for lease documentation are bifurcating the market between institutional players with distributed ledger infrastructure and regional lessors reliant on paper-based processes. Aviation and container leasing firms with cargo-tracking IoT integration capture real-time utilization data. This technology is bifurcating residual value forecasting accuracy between digitized and analog portfolio managers.
The EU AI Act's risk classification framework for automated credit decisions is reshaping algorithmic underwriting protocols across European lease portfolios. Lessors must document human oversight for high-risk borrower assessments. Aviation and maritime segments face heightened compliance documentation requirements.
Enterprise buyers now demand usage-based billing structures that align lease payments with actual equipment utilization rather than fixed schedules. Manufacturing lessees in Germany and Japan negotiate sensor-derived payment adjustments. This pattern concentrates among precision tooling and industrial robotics contracts.
Global Financial Leasing Market Segmentation
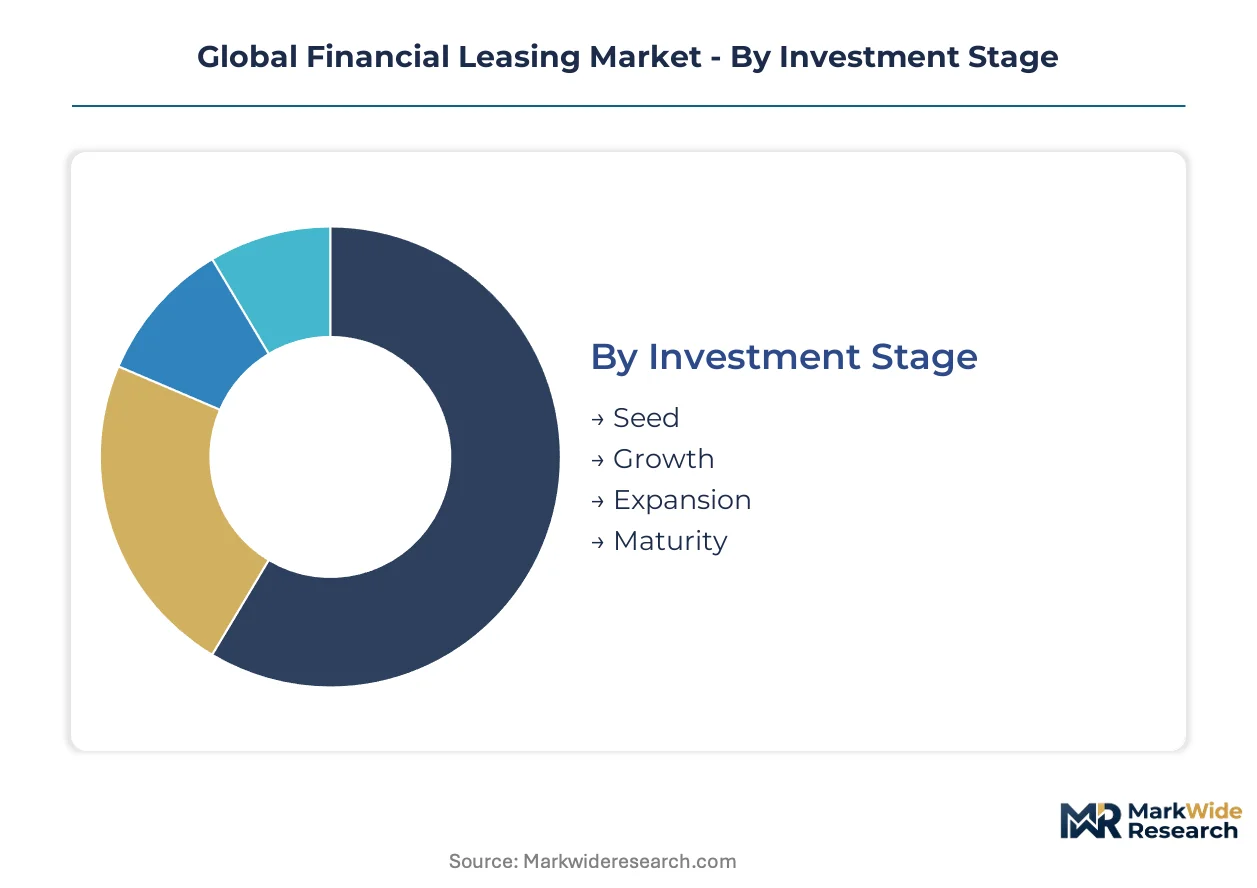
Financial leasing segmentation reveals how capital flows concentrate across asset classes and client risk profiles. Regulatory capital requirements under Basel III and IFRS 16 reshape which structures dominate transaction economics.
Investment Stage:
Basel III risk-weighting creates divergent capital treatment across maturity tiers, with expansion-stage exposures commanding elevated provisioning.
- Seed:Early-stage ventures access equipment financing through venture debt hybrids. German and Japanese lessors specialize in laboratory instrumentation for biotech startups.
- Growth:Scaling enterprises deploy leasing to preserve runway capital. Chinese manufacturers utilize this tier for automation upgrades under state-backed credit guarantees.
- Expansion:Mature revenue streams unlock larger ticket sizes and longer tenors. Brazilian hospital networks concentrate demand for diagnostic imaging at this stage.
- Maturity:Established cash flows optimize tax-efficient structures. Sale-and-leaseback volume peaks here as corporates monetize owned assets.
Established volume favors Maturity; emerging adoption favors Growth.
Asset Type:
Collateral liquidity and depreciation curves determine residual value risk and lessor margin structures.
- Vehicles:Fleet operators in the United States dominate transaction flow through captive finance programs. Wells Fargo Bank anchors commercial vehicle origination with telematics-integrated underwriting.
- Equipment:Manufacturing and logistics infrastructure commands the largest transaction volumes. Germany's Mittelstand drives precision tooling demand through KfW-backed leasing windows.
- Real Estate:Long-dated tenors match property economic lives. Japanese institutional investors favor this category for yield matching against liability profiles.
- Technology:Enterprise software and cloud infrastructure migrations accelerate fastest. ASC 842 and IFRS 16 convergence pressures opex-model adoption across multinational lessees.
Equipment sustains dominant share; Technology climbs the fastest as capex-to-opex transitions deepen.
Client Type:
Risk assessment protocols diverge sharply between relationship-driven corporate banking and automated SME scoring.
- SMEs:Fragmented demand requires standardized underwriting templates. India's PLI scheme channels equipment finance to manufacturing SMEs through SIDBI-linked programs.
- Corporations:Investment-grade ratings unlock cross-border lease facilities. BNP Paribas structures pan-European master leases for mid-market industrials.
- Startups:Venture-backed balance sheets attract specialized lessors. Silicon Valley Bank's collapse redirected demand to equipment finance specialists with equity warrant overlays.
- Government:Sovereign immunity clauses and procurement rules complicate documentation. Brazilian federal health programs expand medical equipment leasing through BNDES credit lines.
Corporations anchor fee generation; SMEs offer origination scale through platform automation.
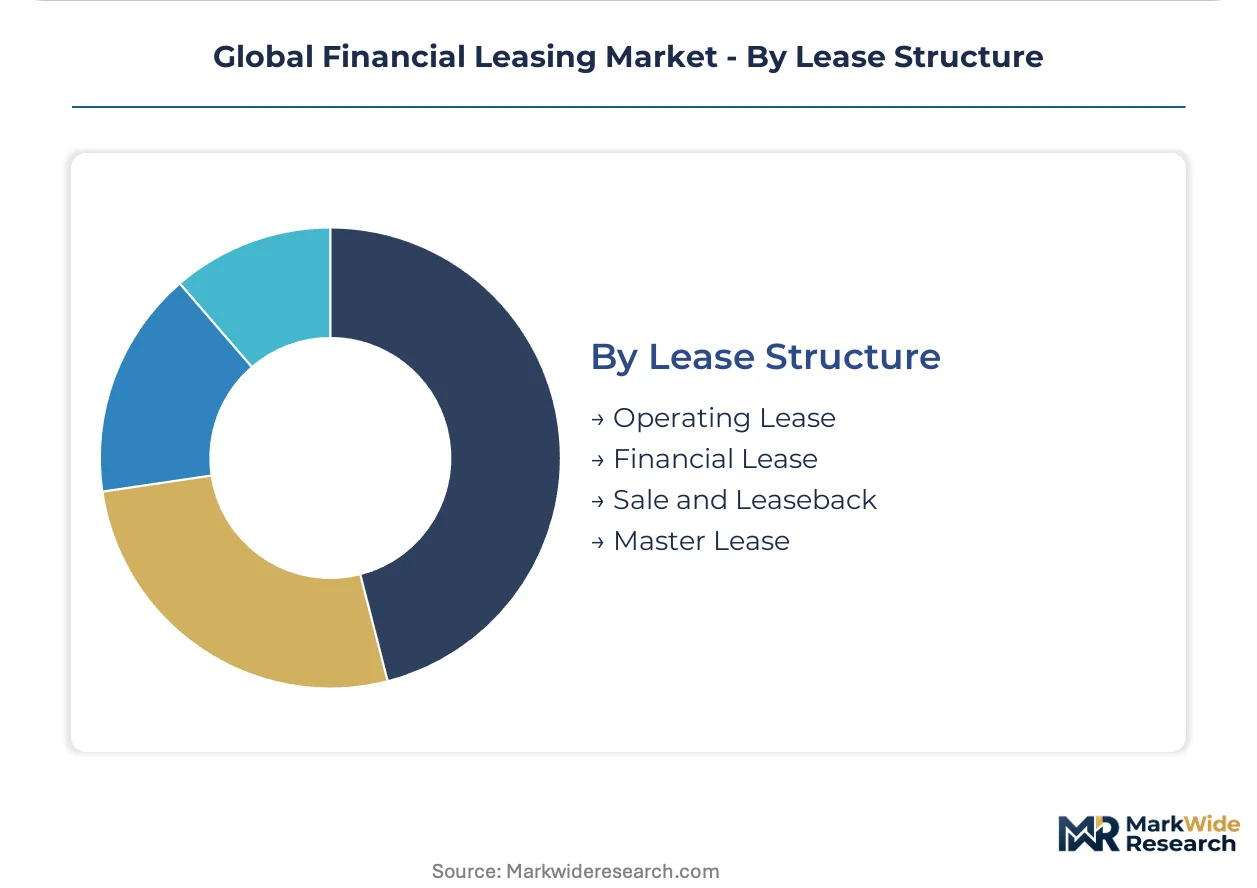
Lease Structure:
Accounting classification under ASC 842 and IFRS 16 determines balance-sheet impact and drives structural preference.
- Operating Lease:Off-balance-sheet treatment preserves debt capacity. Airlines favor this structure for fleet flexibility amid fuel price volatility.
- Financial Lease:Substantial risk transfer triggers capitalization. Germany's tax depreciation rules enhance lessor yield on industrial equipment.
- Sale and Leaseback:Immediate liquidity without operational disruption. China's state-owned manufacturers deploy this structure to modernize aging production lines.
- Master Lease:Framework agreements reduce transaction friction for recurring acquisitions. Japanese trading houses utilize these for rolling stock across Southeast Asian infrastructure projects.
Financial Lease dominates booked assets; Sale and Leaseback captures margin expansion in volatile credit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-credit backed leasing flows concentrate in surplus manufacturing economies, while capital-importing jurisdictions deploy financial leasing to bridge infrastructure gaps without sovereign debt expansion.
United States
Commercial fleet operators and healthcare systems drive equipment finance demand across the Southeast and Midwest manufacturing corridors. The SEC and FASB enforce ASC 842 disclosure standards, compressing off-balance-sheet structuring options for corporate lessees. Dallas-Fort Worth anchors aviation leasing origination, with lessors structuring tax-efficient cross-border facilities through Delaware statutory trusts.
Germany
Mittelstand precision manufacturers leverage leasing to preserve liquidity for export order fulfillment. The KfW development bank channels subsidized credit lines through regional leasing windows, particularly in Baden-Württemberg and Bavaria. Frankfurt's banking cluster hosts pan-European master lease structuring for mid-market industrials operating across EU member states.
China
State-owned manufacturers deploy sale-and-leaseback arrangements to modernize aging production lines in the Yangtze River Delta. SAMR and MIIT oversight shapes residual value calculations for industrial equipment under dual carbon transition mandates. Shenzhen's fintech corridor incubates blockchain-enabled lease documentation platforms targeting SME origination scale.
Japan
Hospital networks and precision tooling shops concentrate demand in the Chubu and Kansai industrial belts. METI guidelines on equipment depreciation influence lessor yield optimization for robotics and automation assets. Tokyo-based trading houses structure rolling stock leases across Southeast Asian infrastructure projects through Singapore booking centers.
Brazil
Federal health programs expand diagnostic imaging leasing through BNDES credit lines, preserving municipal budget liquidity. ANVISA certification requirements for medical equipment complicate documentation but create captive demand for specialized lessors. São Paulo's financial district hosts the dominant share of Latin American aviation lease origination.
Global Financial Leasing Market Vendor Landscape
Concentration sits with diversified banking groups that leverage balance sheet scale to anchor cross-border equipment finance. The market structure tiers between global universal banks with captive leasing arms, regional specialists focused on single asset classes, and emerging fintech platforms automating SME origination. Dominant competitive moves include synthetic securitization to optimize Basel III risk-weighted assets and residual value insurance overlays to compress margin volatility.
Among North American banking groups, Fifth Third Bank and Wells Fargo Bank occupy positions within the commercial vehicle and mid-market industrial segments. SMBC Group exemplifies the Asia-Pacific specialist archetype, anchoring aviation and maritime lease structuring across export-credit corridors. BNP Paribas represents the pan-European universal bank model, utilizing its balance sheet footprint to dominate cross-border master lease facilities for industrials.
| Leading Market Players |
|---|
| Fifth Third Bank |
| SMBC Group |
| Sumitomo Mitsui Finance and Leasing |
| Texas Capital Bancshares |
| Commerce Bancshares |
| BNP Paribas |
| Wells Fargo Bank |
| North Star Leasing |
| HSBC Group |
| Others |
Supply Flow & Price Mechanics
Balance-sheet scale economies at major banking groups compress origination costs and establish pricing floors that regional lessors cannot match. This concentration shapes both supply-side origination capacity and the residual value insurance overlays that stabilize lease pricing across volatile asset classes.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy service levels. Price differentiation rests on residual value guarantee depth and telematics integration density. Pricing pressure intensifies as central bank rate shifts compress net interest margins on floating-rate lease portfolios. SMEs exhibit highest price sensitivity due to limited bargaining power against concentrated lessor balance sheets.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for containerized equipment collateral. Supply concentrates in Germany, Japan, and China for precision manufacturing assets and in the United States for commercial vehicle fleets. Raw material dependencies span aviation-grade aluminum, semiconductor components, and battery-grade lithium. Single-source vulnerability sits with specialized lessor software platforms. Distribution runs through captive finance subsidiaries and independent broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Financial Leasing Market is experiencing high-growth disruption as Basel III capital adequacy frameworks and IFRS 16 disclosure mandates restructure competitive economics. These regulatory inflections favor institutions with advanced risk-weighted asset optimization capabilities.
For Market Incumbents: Shield residual value exposure through synthetic securitization and insurance overlay expansion. Consolidate underwriting talent pools in aviation and maritime segments where specialized modeling capabilities are scarce. Deepen backward integration into asset remarketing channels to capture end-of-lease value recovery. For New Entrants and Emerging Players: Anchor in India's infrastructure buildout and SME equipment finance gaps where platform automation can outpace legacy lessor workflows. Target solar array and manufacturing automation segments under the PLI scheme. Deploy embedded finance partnerships with industrial OEMs to bypass balance-sheet scale requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lessors with algorithmic underwriting infrastructure and distributed ledger documentation capabilities. Long-term viability hinges on climate-risk disclosure readiness and EU Green Deal taxonomy alignment. Watch for divergence between ASC 842 and IFRS 16 enforcement as a signal for multinational lessor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Securitization Deployment | Compresses Basel III risk-weighted assets while preserving yield streams for BNP Paribas-scale balance sheets. |
| Residual Value Insurance Expansion | Stabilizes margin buffers against aircraft and maritime asset volatility for SMBC Group portfolios. |
| Blockchain Documentation Platform | Accelerates SME origination cycles through smart contract automation in Shenzhen's fintech corridor. |
| Green Lease Structuring | Unlocks preferential capital treatment under EU Green Deal taxonomy for energy-efficient asset classes. |
| Telematics-Integrated Underwriting | Captures real-time utilization data for usage-based billing structures demanded by German manufacturing lessees. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with equipment finance executives, risk officers, and aviation leasing portfolio managers, combined with secondary validation through SEC 10-K filings, Basel Committee regulatory texts, and customs trade data on capital goods flows. Bottom-up lease origination volumes triangulated against top-down banking sector asset disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including lease structure type, asset class collateral liquidity, client risk tier, and regional regulatory cluster. CAGRs derived from historical origination trajectories adjusted for Basel III implementation timelines and IFRS 16 adoption curves. Forecast inputs incorporated central bank policy rate assumptions and industrial capacity utilization indices.
Material uncertainties — sovereign debt stress in emerging markets, abrupt regulatory divergence between US and EU accounting standards, and technology asset obsolescence acceleration — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Factoring Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Global Revenue-Based Financing Market