
 Refinancing Market | 2026-2036
Refinancing Market Size, Share, and Industry Trends Forecast 2026-2036
Refinancing Market Intelligence
Multi-sourced origination is restructuring how lenders compete for refinancing volume. Rocket Mortgage leverages proprietary digital platforms to compress closing timelines. U.S. Bank anchors its position through integrated depository relationships and branch-based consultation. Freedom Mortgage competes in government-backed segments where specialized underwriting creates defensible niches.
Refinancing constitutes the replacement of an existing debt obligation with a new facility bearing modified terms, typically involving interest rate adjustment, term extension, or principal restructuring, executed through note substitution and lien perfection processes. Fixed-rate products dominate transaction flow due to borrower preference for payment certainty amid monetary volatility, while adjustable-rate instruments attract risk-tolerant segments seeking front-loaded savings. Online application services capture accelerating share as automated valuation models and e-closing infrastructure reduce friction, though broker-sourced volume retains significance among first-time homeowners requiring advisory support.
The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures that standardize cost comparison across competing offers, while FHA and VA programs administered through HUD and the Department of Veterans Affairs establish credit box parameters for government-insured refinances. Fannie Mae and Freddie Mac conservatorship frameworks dictate conforming loan limits and eligibility criteria that shape product design and pricing architecture. Stakeholders must monitor Federal Reserve balance sheet policy and corresponding Treasury yield curve movements as primary determinants of refinance incentive eligibility.
Market Dynamics
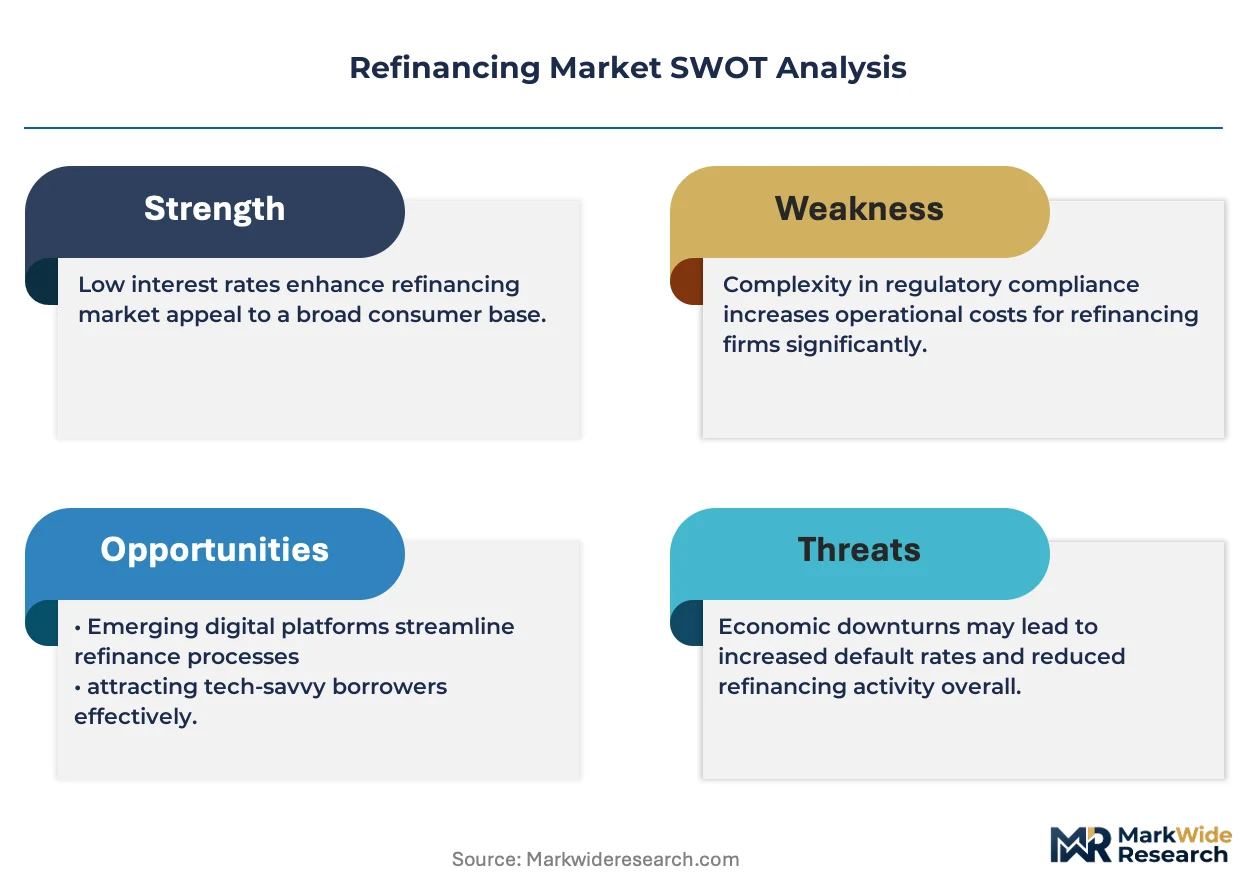
Federal Reserve monetary policy shifts are compressing origination windows and forcing lenders to rebuild technology stacks for rate volatility rather than volume stability. Digital underwriting platforms now determine competitive survival.
Growth Catalysts
- Rate Reduction Incentive:Homeowners holding mortgages originated during elevated rate environments face substantial payment relief through refinancing, creating automatic demand pools when Treasury yields decline.
- FHA Streamline Programs:The Department of Housing and Urban Development's reduced documentation requirements for government-insured refinances accelerate closing velocity for credit-constrained borrowers.
- Automated Valuation Models:Desktop appraisal technologies eliminate traditional inspection delays, compressing origination timelines from weeks to days.
Market Restraints
- Rate Volatility:Rapid Federal Reserve policy pivots render pipeline hedges ineffective, exposing lenders to basis risk between locked rates and secondary market execution.
- Concentrated Servicing Rights:Ginnie Mae pooling requirements and MSR investor concentration in private equity hands limit originator flexibility on product mix.
- Yield Curve Inversion:Prolonged negative spreads between short-term funding costs and long-term mortgage rates squeeze net operating margins regardless of volume.
Strategic Opportunities
- Texas Cash-Out Refinance:State homestead laws and rapid property appreciation create sustained demand for equity extraction products unavailable in recourse-restricted jurisdictions.
- VA IRRRL Expansion:The Department of Veterans Affairs Interest Rate Reduction Refinance Loan program offers streamlined eligibility for military households with minimal documentation.
- API-Enabled LOS Integration:Open banking data feeds and income verification exchanges reduce manual processing costs for correspondent lenders.
Industry Challenges
- Underwriting Talent Scarcity:Experienced government program specialists command premium compensation, constraining capacity at non-depository lenders.
- Legacy System Integration:Core banking platforms at regional depositories require costly middleware development to support e-closing and remote notarization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refinancing Market |
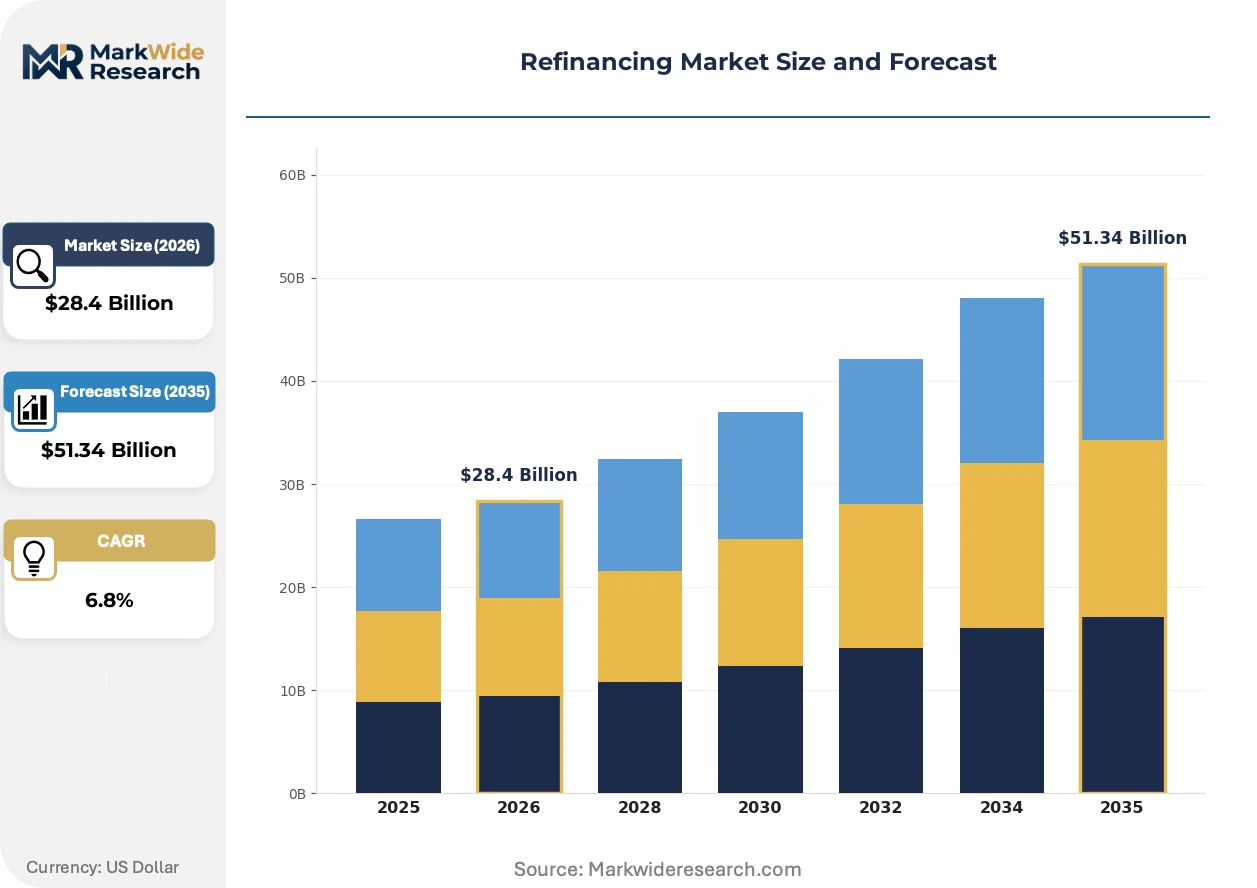
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Rate, Adjustable-Rate, Home Equity, Personal Loan Customer Type: First-Time Homebuyers, Real Estate Investors, Homeowners, Small Business Owners Service Type: Online Applications, In-Person Consultations, Broker Services, Direct Lenders Interest Rate Type: Variable, Fixed, Promotional, Discounted |
| Companies Covered | United Wholesale Mortgage, Rocket Mortgage, Freedom Mortgage, PennyMac, loanDepot, Chase, U.S. Bank, Newrez, Mr. Cooper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refinancing Market Strategic Shifts & Innovations
Origination economics are fragmenting across channel types as rate-sensitive borrowers migrate toward lowest-cost execution paths. Technology investment now targets margin preservation rather than growth capture.
Machine learning-powered automated underwriting engines are rewriting credit decisioning velocity. Non-bank lenders deploy these systems to price loans in seconds rather than days. The structural consequence is compressing the rate-quote-to-lock window, rewarding platforms with real-time capital markets connectivity.
The Consumer Financial Protection Bureau's forthcoming open banking rule under Section 1033 of Dodd-Frank mandates financial data portability. This regulatory shift forces lenders to rebuild application workflows around consumer-permissioned account aggregation. Depository institutions with existing core banking relationships gain first-mover advantage in consent management infrastructure.
Direct-to-consumer digital channels are displacing traditional broker networks for rate-and-term refinances. Borrowers with established equity positions and strong credit profiles self-serve through comparison platforms, while broker-sourced volume concentrates among cash-out and government-backed transactions requiring specialized guidance. This bifurcation is most pronounced in high-cost metropolitan markets where loan officer compensation structures vary dramatically by channel.
Refinancing Market Segmentation
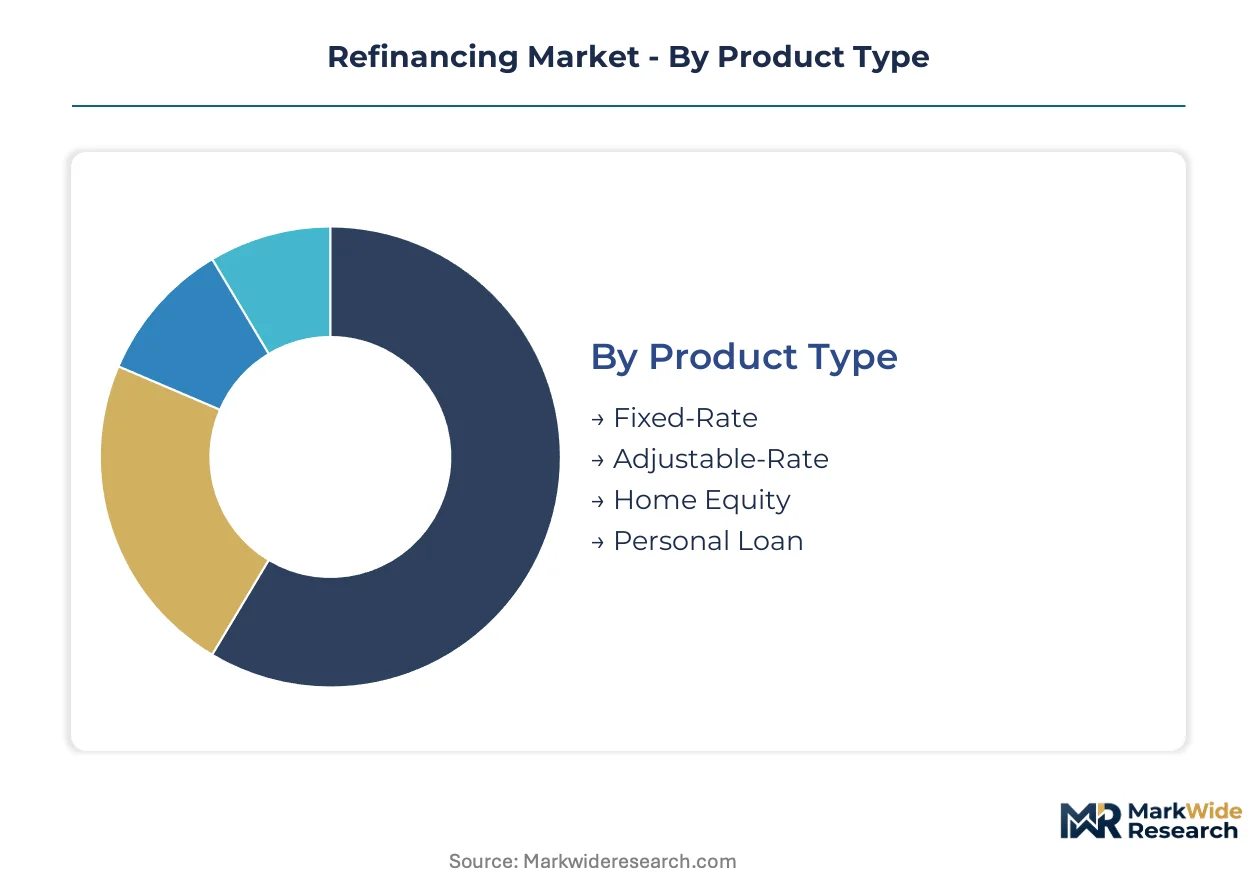
Refinancing market segmentation reveals divergent profit pools across rate sensitivity, channel economics, and documentation complexity. Lenders configure product portfolios around borrower risk profiles and origination cost structures rather than uniform distribution.
Product Type:
Fixed-rate products command volume dominance while adjustable-rate instruments capture premium pricing from risk-tolerant segments.
- Fixed-Rate:Borrowers lock nominal rates for the full amortization period, eliminating payment uncertainty during Federal Reserve tightening cycles. Demand concentrates among rate-sensitive homeowners in high-balance coastal markets where basis point movements translate to substantial monthly savings.
- Adjustable-Rate:Products feature initial fixed periods followed by periodic resets indexed to SOFR or Treasury yields. Real estate investors seeking short-term holding periods dominate uptake, accepting reset risk for front-loaded payment reductions that improve cash-on-cash returns.
- Home Equity:Second-lien structures extract accumulated property value without disturbing primary mortgage terms. Texas homestead law restrictions and rapid appreciation in Sun Belt metros sustain specialized demand.
- Personal Loan:Unsecured refinancing consolidates high-interest consumer debt outside mortgage lien frameworks. Fintech platforms automate underwriting for sub-$100,000 balances.
Today's leader: Fixed-Rate. Tomorrow's challenger: Home Equity.
Customer Type:
Homeowner segments drive transaction velocity while investor and business categories deliver superior unit economics through complexity premiums.
- Homeowners:Primary residence borrowers pursue rate reduction or term restructuring to accelerate equity buildup. FHA and VA streamline programs reduce documentation burdens for government-backed refinances.
- Real Estate Investors:Portfolio holders optimize debt service coverage ratios through cash-out refinancing of stabilized rental properties. DSCR-based underwriting replaces personal income verification.
- First-Time Homebuyers:Recent purchase mortgage holders monitor rate environments for early refinancing windows. Down payment assistance recapture clauses constrain timing flexibility.
- Small Business Owners:Self-employed borrowers leverage stated-income alternatives or bank statement programs where tax return documentation understates actual cash flow.
Volume concentrates with Homeowners. Margin expansion sits with Real Estate Investors.
Service Type:
Digital channels compress acquisition costs while advisory-heavy segments retain pricing power through complexity navigation.
- Online Applications:Automated valuation models and e-closing infrastructure enable same-day rate locks. Rocket Mortgage and comparable platforms target rate-and-term refinances with FICO scores above 720.
- Broker Services:Intermediaries source multiple wholesale offerings for borrowers with non-standard employment or credit profiles. Compensation shifts from yield-spread premiums to borrower-paid fees under Dodd-Frank.
- Direct Lenders:Balance-sheet lenders retain servicing rights and cross-sell deposit products. U.S. Bank and regional depositories leverage existing customer data for pre-qualified offers.
- In-Person Consultations:Branch-based consultation addresses cash-out and construction-to-permanent refinances requiring lien position analysis. High-touch model sustains relevance in government-backed segments.
Online Applications capture share fastest. Broker Services defend margin through specialization.
Interest Rate Type:
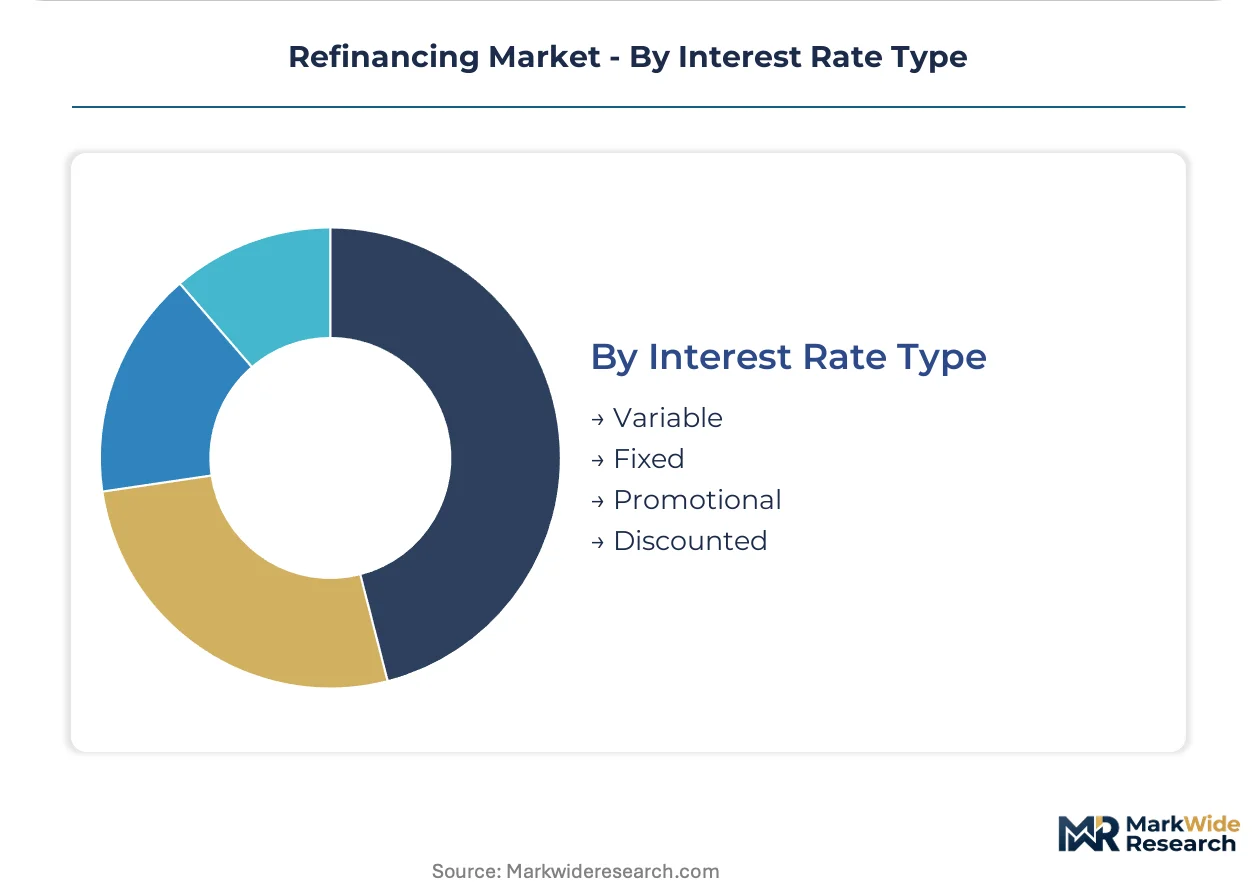
Pricing architecture stratifies across certainty premiums, risk transfer mechanisms, and promotional acquisition tactics.
- Fixed:Nominal rate remains constant through maturity, transferring interest risk to the lender. Ginnie Mae pooling requirements standardize prepayment assumptions.
- Variable:Rates reset at prescribed intervals based on published indices plus margin. SOFR transition displaced LIBOR referencing.
- Promotional:Teaser rates convert to market-indexed pricing after initial periods. CFPB disclosure rules mandate fully-indexed payment examples.
- Discounted:Relationship pricing reduces basis points for borrowers maintaining deposit balances or automated payment enrollment.
Fixed structures anchor the market. Variable products gain traction in investor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
American mortgage origination clusters concentrate refinancing volume in rate-sensitive metropolitan corridors. Federal Reserve policy transmission varies across national banking systems, creating divergent incentive structures for borrower conversion.
United States
Rate reduction incentives dominate borrower behavior in high-balance coastal markets. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure standards that standardize cost comparison. Los Angeles and New York metropolitan areas generate concentrated transaction volume through jumbo refinancing channels.
Germany
Pfandbrief-covered mortgage banks compete with direct consumer platforms for refinancing volume. The European Central Bank's monetary policy transmission affects variable-rate repricing schedules. Frankfurt's banking cluster anchors continental mortgage securitization infrastructure.
United Kingdom
Fixed-rate product switching accelerates during Bank of England policy transition periods. The Financial Conduct Authority's mortgage conduct rules mandate affordability stress testing. London's fintech corridor hosts automated valuation model providers serving direct-to-consumer platforms.
Canada
Five-year term renewal cycles create predictable refinancing windows for chartered banks. The Office of the Superintendent of Financial Institutions sets capital requirements for mortgage insurers. Toronto and Vancouver metropolitan areas concentrate high-ratio refinancing demand.
Australia
Brokers intermediate the majority of refinancing volume through comparison platforms. The Australian Prudential Regulation Authority's serviceability buffers constrain maximum borrowing capacity. Sydney and Melbourne housing markets sustain cash-out refinancing for property investment leverage.
Refinancing Market Key Industry Players
Global majors compete with regional champions across origination channel economics. The refinancing market consolidates around non-bank lenders with specialized government program expertise and depository institutions with cross-sell infrastructure. Three archetypes dominate: technology-enabled direct platforms, government-backed specialists, and integrated banking conglomerates. Competitive positioning hinges on automated underwriting deployment and servicing rights retention strategies.
Within the technology-enabled tier, Rocket Mortgage exemplifies platform-driven origination velocity. Freedom Mortgage occupies a specialized position in government-insured segments. U.S. Bank anchors the integrated banking archetype through depository relationship leverage.
| Leading Market Players |
|---|
| United Wholesale Mortgage |
| Rocket Mortgage |
| Freedom Mortgage |
| PennyMac |
| loanDepot |
| Chase |
| U.S. Bank |
| Newrez |
| Mr. Cooper |
| Others |
Cost & Logistics Intelligence
Rate-sensitive homeowners in high-balance coastal markets anchor pricing power for originators, locking in execution fees through rate-and-term refinances while cash-out products command complexity premiums. Pricing stratifies across digital self-service platforms, broker-mediated channels, and high-touch advisory models based on documentation intensity and borrower credit profile.
Pricing Analysis
Secondary market execution spreads and servicing rights valuations pass through to borrower-facing rate quotes. Price differentiation rests on automated underwriting deployment and correspondent lender relationships. Pricing pressure stems from yield curve inversion compressing gain-on-sale margins. First-time homeowners with government-backed eligibility exhibit highest price sensitivity; jumbo borrowers with established equity positions show lowest.
Supply Chain Analysis
Regional loan fulfillment centers and correspondent lending networks distribute origination capacity across mortgage banking hubs. Concentration centers on the United States, with secondary nodes in Canada and Australia for cross-border capital flows. Mortgage-backed securities pipelines draw from Ginnie Mae pooling requirements, Fannie Mae and Freddie Mac conforming standards, and private-label securitization channels. Single-source vulnerability sits with Federal Reserve balance sheet policy affecting MBS demand. Distribution runs through wholesale broker networks, direct-to-consumer platforms, and depository branch infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refinancing market reads as a late-cycle quality story where borrower migration toward streamlined digital execution favors platforms with pre-positioned automated underwriting infrastructure. Demand is concentrating among rate-sensitive homeowners seeking payment certainty through fixed-rate products.
For Market Incumbents: Deploy API-enabled loan origination system integration to compress processing costs against non-bank digital competitors. Defensive consolidation through correspondent lending network expansion protects volume share as rate volatility reduces origination windows. Threat from fintech platforms with real-time capital markets connectivity demands servicing rights retention to capture recurring revenue streams.
For New Entrants and Emerging Players: Begin with government-backed streamline programs where documentation complexity creates defensible positioning against pure-play digital lenders. White-space targets include VA IRRRL expansion for military households and Texas cash-out refinancing under homestead law restrictions. Go-to-market angle centers on specialized underwriting expertise for credit-constrained borrower segments.
For Investors and Strategic Acquirers: Non-bank lenders with scaled servicing portfolios are the most active acquirer in this space, seeking origination capacity to feed retained servicing rights. Long-term viability favors platforms with technology-enabled cost structures capable of profitability across rate cycles. Acquisition target archetype: regional depositories with underutilized digital infrastructure. Signal to watch: Federal Reserve balance sheet normalization affecting MBS demand and corresponding origination economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Underwriting Deployment | Rocket Mortgage and comparable platforms reduce rate-quote-to-lock windows through machine learning credit decisioning. |
| Correspondent Lending Network Expansion | Non-bank originators secure volume commitments from regional depositories seeking outsourced fulfillment capacity. |
| Servicing Rights Retention Strategy | MSR investors gain recurring cash flows and cross-sell opportunities through retained customer relationships. |
| Government Program Specialization | FHA and VA streamline expertise creates defensible niches where reduced documentation requirements accelerate velocity. |
| Digital Closing Infrastructure Investment | E-closing and remote notarization capabilities reduce friction for rate-sensitive borrowers in competitive markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mortgage banking executives, loan origination officers, secondary market traders, servicing portfolio managers, and regulatory compliance leads with secondary validation. Sources included Ginnie Mae issuance data, Fannie Mae and Freddie Mac conforming loan disclosures, Federal Reserve flow of funds reports, and SEC filings from publicly traded non-bank lenders. Bottom-up origination volume modeling and top-down macroeconomic scenario analysis enabled triangulation.
Comparable historical rate cycles anchored the projection framework across the analysis window. Segmentation dimensions modeled encompass product type, customer risk profile, service delivery channel, and interest rate structure. CAGRs derived from regression analysis against Treasury yield movements and corresponding refinance incentive indices. Industry-specific inputs included Federal Reserve policy rate assumptions and housing price appreciation trajectories.
Several conditions sit outside the modeled scope, including unanticipated Federal Reserve policy pivots, housing market dislocation events, and regulatory changes to government-backed program eligibility. Forecasts reflect assumptions about monetary policy transmission and borrower behavior patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
Embedded Lending Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
US Home Equity Lending Market