
 Global Mortgage/Loan Brokers Market | 2026-2036
Global Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mortgage/Loan Brokers Market Foresight
Residential investor participation is shifting toward self-employed borrowers and credit-challenged applicants who require specialized documentation support. Rocket Mortgage leverages proprietary algorithmic underwriting to reduce manual review cycles. United Wholesale Mortgage sustains dominance through its broker-exclusive channel, refusing direct-to-consumer origination. CrossCountry Mortgage specializes in non-qualified mortgage products that larger depositories avoid.
A mortgage or loan broker functions as an intermediary that solicits, negotiates, and arranges loans between borrowers and wholesale lenders, earning compensation through yield-spread premiums, borrower-paid fees, or lender-paid commissions rather than balance-sheet lending. The broker evaluates debt-to-income ratios, loan-to-value thresholds, and credit profiles to match applicants with appropriate capital sources across correspondent, wholesale, and warehouse lending channels. Fixed-rate products anchor volume in stable-rate environments but yield thinner margins than adjustable-rate and interest-only structures where broker compensation widens. Online platforms and automated matching services are capturing the fastest growth as distributed workforce models reduce dependency on physical branch infrastructure.
The US Consumer Financial Protection Bureau enforces Loan Originator Compensation Rules that restrict steering incentives and mandate fee transparency, directly shaping how brokers structure borrower interactions. The UK's Financial Conduct Authority applies Mortgage Conduct of Business rules that enforce affordability stress-testing and advice suitability standards, elevating compliance costs for cross-border operators. Australia's ASIC licensing framework imposes responsible lending obligations that require verification of borrower financial circumstances beyond stated income. Stakeholders must monitor how open-banking data portability and AI-driven pre-approval engines reshape the broker's value proposition against direct lender digitization.
Market Dynamics
Digital underwriting platforms and open-banking APIs are compressing origination timelines from weeks to days, forcing traditional broker networks to restructure compensation models and physical branch footprints around algorithmic pre-approval engines.
Growth Catalysts
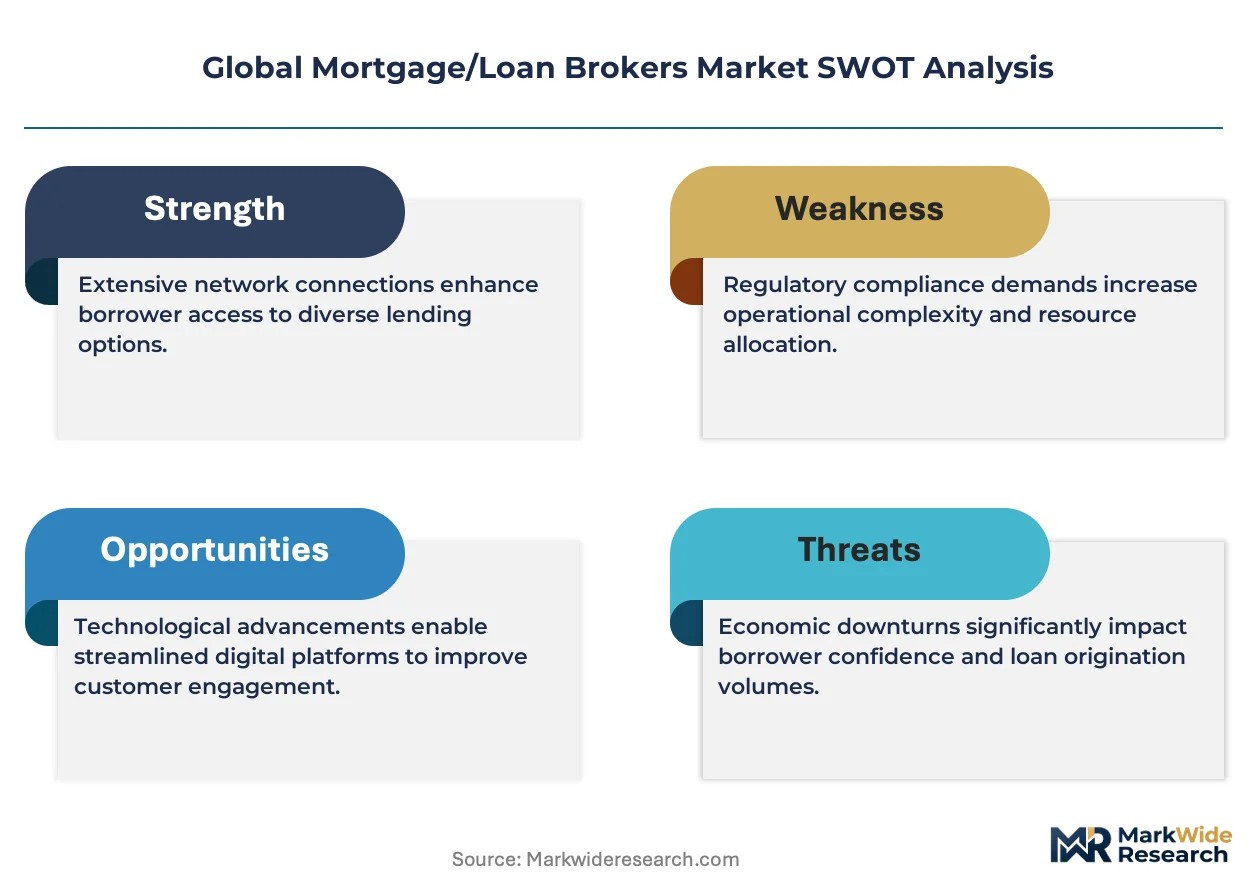
- Self-Employed Borrower Demand:Suburban housing corridors across the United States, the United Kingdom, and Australia are drawing first-time buyers with non-standard income documentation requirements.
- CFPB Loan Originator Compensation Rules:Fee transparency mandates are eliminating steering incentives and building borrower trust in broker-mediated channels over direct-to-consumer alternatives.
- Open-Banking APIs:Real-time financial data portability is collapsing verification cycles and expanding broker capacity to serve credit-challenged applicants.
Market Restraints
- ASIC Responsible Lending Obligations:Australia's verification requirements beyond stated income are elevating compliance costs and extending file preparation timelines for cross-border operators.
- Yield-Spread Compression:Fixed-rate product dominance in stable-rate environments is narrowing broker compensation margins relative to adjustable-rate structures.
- Direct Lender Digitization:Proprietary algorithmic underwriting at balance-sheet lenders is eroding the broker's traditional speed advantage in prime-credit segments.
Strategic Opportunities
- Non-Qualified Mortgage Products:Specialized documentation support for investors and credit-impaired borrowers represents white space that larger depositories avoid.
- Warehouse Lending Channel Expansion:Correspondent relationships with regional banks in Australia and the United Kingdom offer origination volume outside dominant wholesale networks.
- AI-Driven Pre-Approval Convergence:Integration of automated valuation models with open-banking data streams is creating new service tiers for high-net-worth applicants.
Industry Challenges
- Algorithmic Underwriting Talent Scarcity:Brokerages lack data-science capacity to maintain parity with direct lenders' proprietary scoring systems.
- Legacy CRM Integration Friction:Distributed workforce models require reconfiguration of physical branch infrastructure and compliance documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mortgage/Loan Brokers Market |
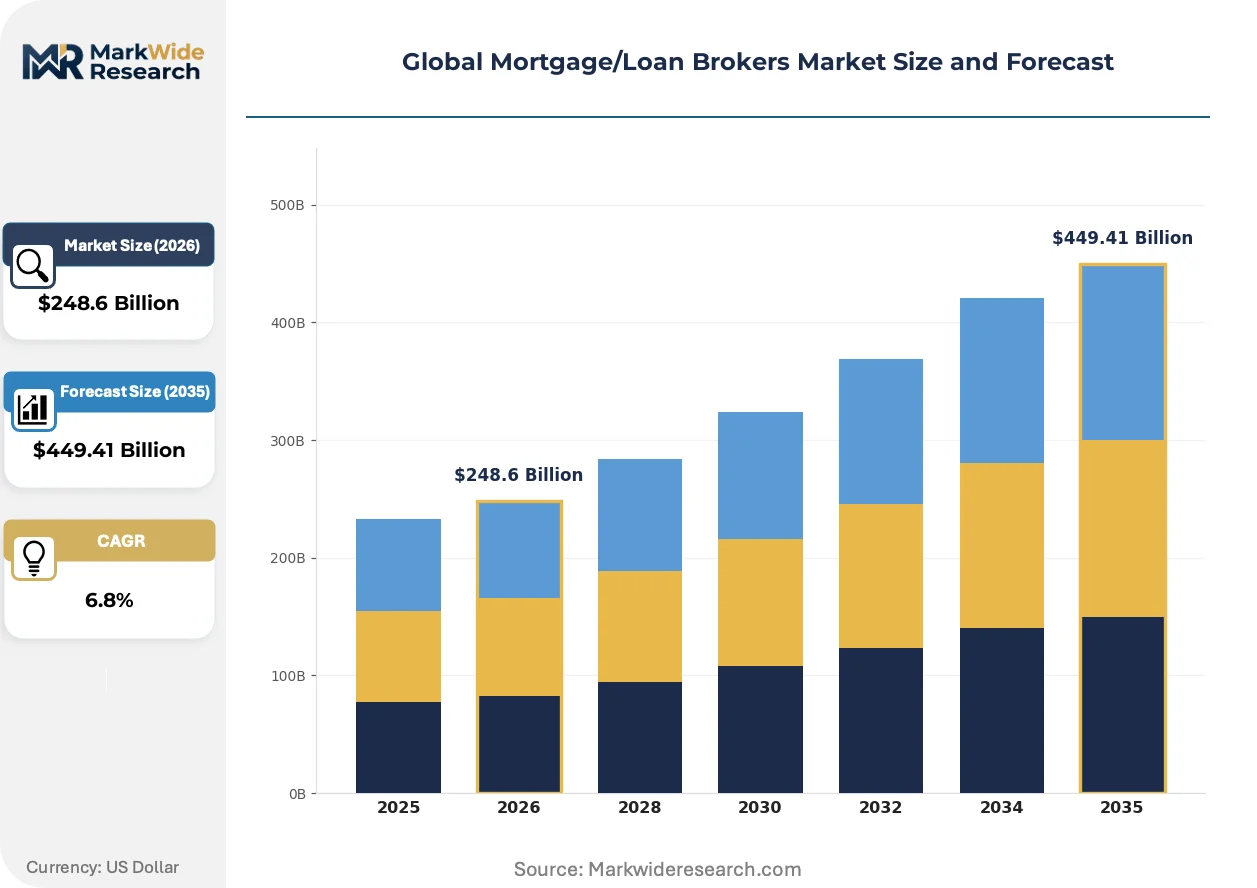
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $449.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Fixed-Rate, Adjustable-Rate, Interest-Only, Balloon, Reverse Mortgage Customer Type: First-Time Buyers, Refinancers, Real Estate Investors, Self-Employed Borrowers, Credit Challenged Distribution Channel: Online Platforms, Branch Offices, Call Centers, Partnership Networks, Direct Sales Service Model: Full-Service Brokerage, Fee-Based Brokerage, Hybrid Advisory, Automated Matching Services, Subscription-Based |
| Companies Covered | Truist Financial Corporation, United Wholesale Mortgage, Bank of America, CrossCountry Mortgage, Rocket Mortgage, Royal Bank of Canada, Mitsubishi UFJ Financial Group, JPMorgan Chase Bank, BNP Paribas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mortgage/Loan Brokers Market Shifts & Advancements
Automated matching services and distributed workforce models are dismantling the branch-centric origination model, compressing cost structures while expanding geographic coverage through cloud-based underwriting infrastructure.
Application programming interfaces connecting credit bureaus, asset verification services, and automated valuation models are unifying previously siloed data streams into single-workflow origination platforms. Suburban brokerages in the United States and Australia are adopting these stacks to reduce manual document collection. The structural consequence is collapsing the traditional 45-day closing cycle into sub-10-day executions for standard file types.
The UK's Financial Conduct Authority Mortgage Conduct of Business rules are enforcing affordability stress-testing that exceeds baseline regulatory requirements. Origination platforms serving British borrowers must now document income sustainability under rate-shock scenarios. Non-bank lenders and broker networks are responding by embedding dynamic stress-testing calculators directly into consumer-facing pre-qualification interfaces.
First-time buyer segments are migrating from branch-based advice to mobile-optimized application portals with embedded video consultation scheduling. The traditional face-to-face mortgage interview is fragmenting into asynchronous document upload and scheduled virtual advisory sessions. This behavioral pivot is most pronounced in Australian and United Kingdom metropolitan markets where digital-native demographics dominate entry-level housing corridors.
Global Mortgage/Loan Brokers Market Segmentation
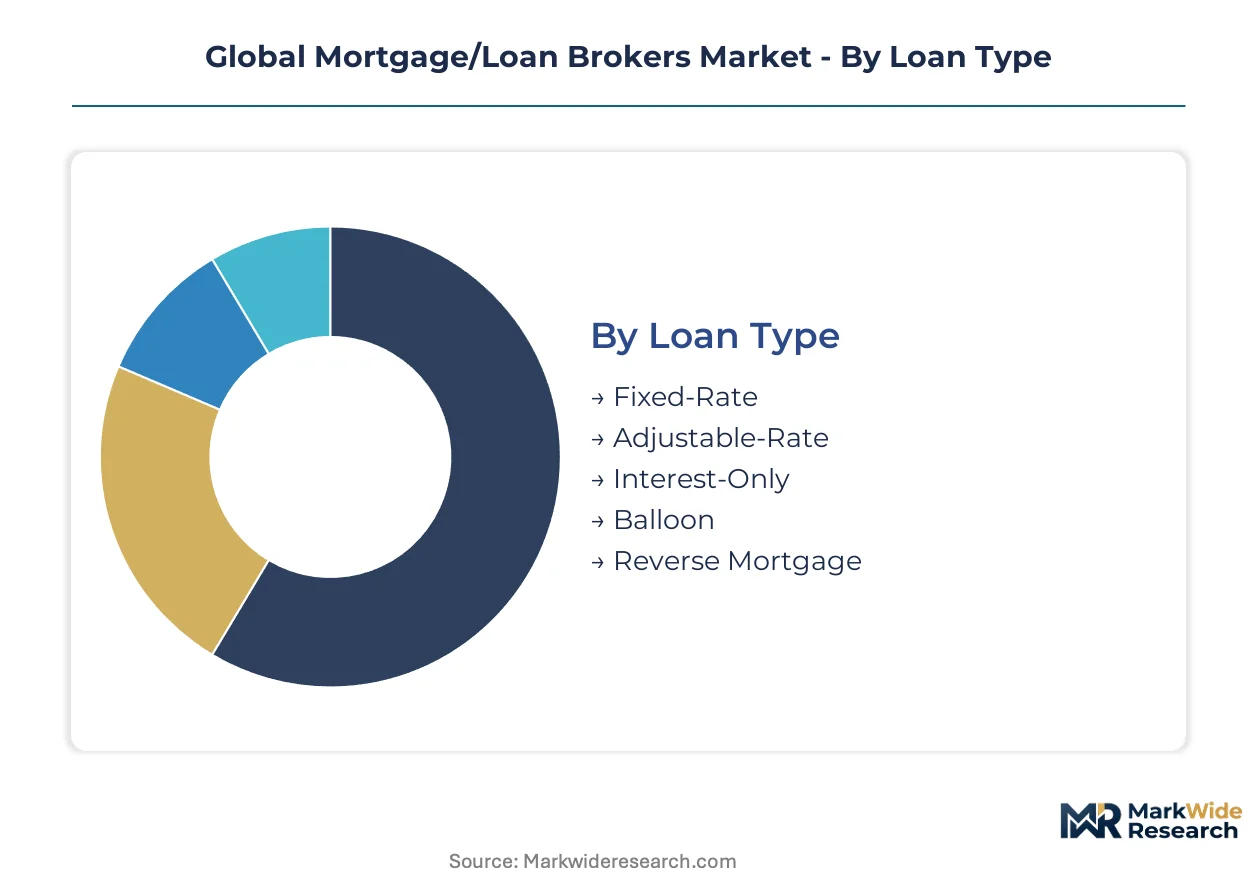
Mortgage broker segmentation reveals how compensation structures, documentation complexity, and channel economics split the intermediary landscape into distinct operational models. Each category captures a different dimension of borrower matching, from product design to service delivery architecture.
Loan Type:
Standardization dominates fixed-rate products while adjustable and exotic structures demand bespoke underwriting workflows and specialized lender relationships.
- Fixed-Rate:Fully amortizing loans with locked interest rates across 15-30 year terms. Demand concentrates in United States suburban corridors where first-time buyers prioritize payment stability amid rate volatility.
- Adjustable-Rate:Hybrid structures with initial fixed periods transitioning to floating indices. Real estate investors in Australian metropolitan markets favor these for cash-flow optimization on rental properties.
- Interest-Only:Payment structures deferring principal amortization. High-net-worth applicants use these for liquidity management.
- Balloon:Short-term amortization schedules with large terminal payments. Commercial property investors in United Kingdom secondary cities deploy these for bridge financing.
- Reverse Mortgage:Equity-conversion products for senior homeowners. Australia's aging demographic is expanding origination volume.
Most installed capacity flows through Fixed-Rate. Expansion is steepest in Adjustable-Rate.
Customer Type:
Documentation burden and credit complexity create tiered service economics, with standard W-2 borrowers subsidizing manual underwriting for non-conventional profiles.
- First-Time Buyers:Entry-level purchasers navigating federal guarantee programs and down-payment assistance. United Kingdom Help-to-Buy corridors and United States FHA-eligible zip codes generate concentrated volume.
- Refinancers:Existing homeowners seeking rate reduction or cash extraction. Rate-sensitive cohorts trigger surge capacity requirements.
- Real Estate Investors:Portfolio builders requiring DSCR-based qualification. Australian negative gearing policies sustain this segment.
- Self-Employed Borrowers:Applicants with non-standard income documentation. Bank statement programs and 1099-only underwriting expand broker differentiation.
- Credit Challenged:Subprime and near-prime applicants excluded from automated approval engines. Manual review specialists capture margin premiums.
Refinancers generate the highest volume velocity. Self-Employed Borrowers command the steepest fee structures.
Distribution Channel:
Physical infrastructure costs versus digital acquisition efficiency determine broker network profitability across channel mix decisions.
- Online Platforms:API-integrated application portals with algorithmic pre-qualification. United States and United Kingdom digital-native demographics drive fastest adoption.
- Branch Offices:Face-to-face advisory with document notarization and closing coordination. Australian regional markets retain dependency.
- Call Centers:Phone-based origination with centralized underwriting support. Refinance waves trigger capacity scaling.
- Partnership Networks:Referral arrangements with real estate agencies and financial advisors. Commission splits define unit economics.
- Direct Sales:Broker-prospected relationships bypassing referral intermediaries. Self-employed niches require targeted outreach.
Branch infrastructure absorbs the largest fixed-cost base. Online Platforms are climbing the fastest.
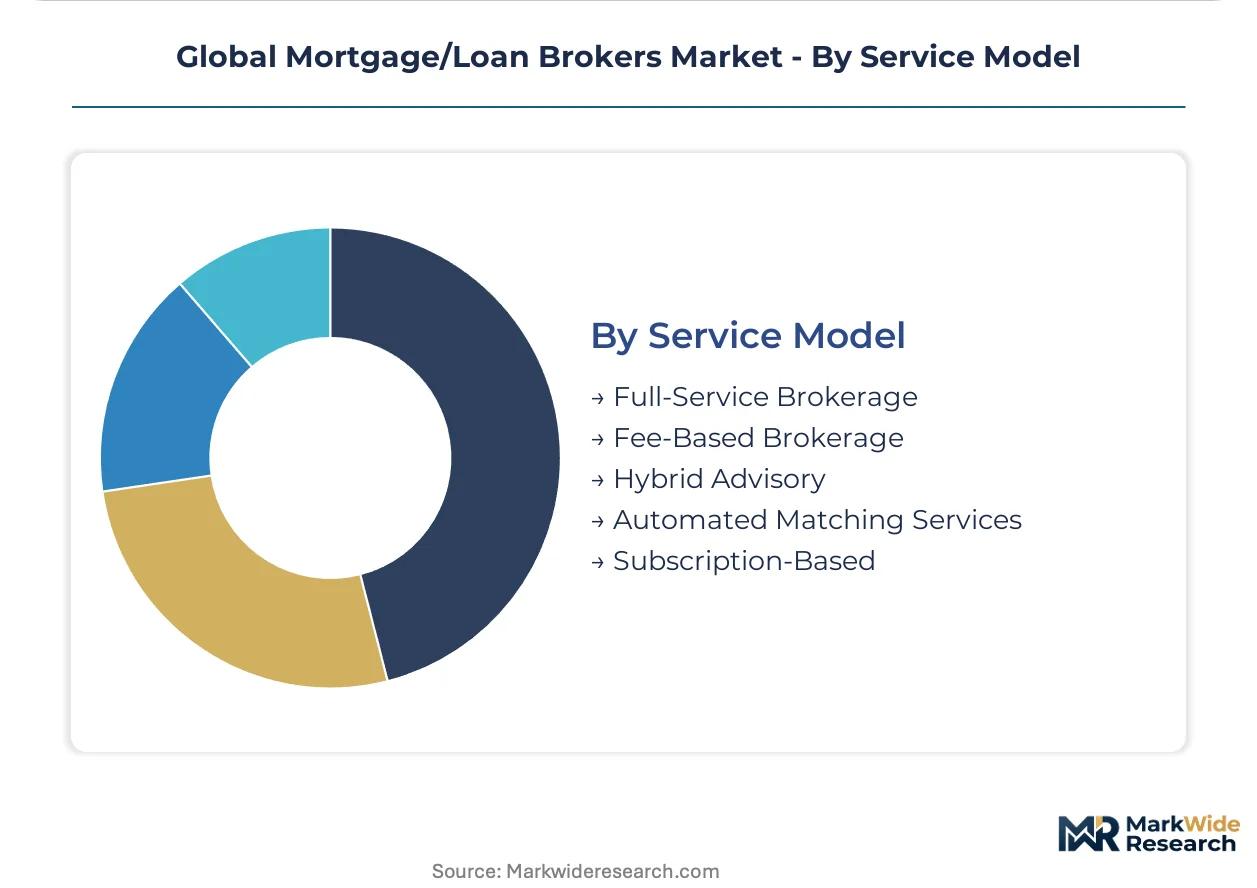
Service Model:
Fee transparency mandates and regulatory compensation rules are fragmenting traditional yield-spread models into disclosed fee structures and technology-enabled self-service tiers.
- Full-Service Brokerage:End-to-end advisory with lender negotiation and closing management. Complex files in United States and Australia justify premium pricing.
- Fee-Based Brokerage:Borrower-paid compensation eliminating lender yield-spread premiums. United Kingdom FCA disclosure rules accelerate adoption.
- Hybrid Advisory:Technology-assisted document collection with human underwriting review. Cost-sensitive segments favor this middle tier.
- Automated Matching Services:Algorithmic lender pairing with minimal human intervention. Prime-credit standard files migrate here.
- Subscription-Based:Flat-fee access to broker platforms and rate monitoring tools. Refinance-ready homeowners sustain recurring revenue.
Full-Service Brokerage retains the largest revenue pool. Automated Matching Services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater London metropolitan corridor concentrates the highest density of mortgage brokerage transactions outside North America, with fintech-integrated advisory models displacing traditional branch networks across suburban commuter belts.
United States
First-time buyer demand clusters in Sun Belt suburban corridors from Austin to Phoenix, where non-standard income documentation requirements favor broker-mediated channels. The Consumer Financial Protection Bureau enforces Loan Originator Compensation Rules that eliminate steering incentives and mandate fee transparency. Dallas-Fort Worth and Atlanta metropolitan statistical areas exhibit the fastest platform adoption for algorithmic pre-approval engines.
United Kingdom
Help-to-Buy corridors across Southeast England and Midlands conurbations sustain concentrated first-time buyer volume through broker networks. The Financial Conduct Authority applies Mortgage Conduct of Business rules enforcing affordability stress-testing and advice suitability standards. London and Manchester brokerages are embedding dynamic stress-testing calculators directly into consumer-facing pre-qualification interfaces.
Australia
Negative gearing policies sustain real estate investor demand across Sydney and Melbourne metropolitan markets, with self-employed borrowers requiring specialized documentation support. ASIC licensing framework imposes responsible lending obligations requiring verification beyond stated income. Brisbane and Perth suburban corridors exhibit accelerating migration from branch-based advice to mobile-optimized application portals.
Canada
Refinance waves triggered by rate volatility concentrate in Toronto and Vancouver metropolitan areas, where mortgage stress-test regulations shape borrower qualification pathways. The country's national banking regulator maintains uninsured mortgage underwriting standards that elevate broker relevance for alternative lender placement. Calgary and Montreal broker networks are restructuring physical branch footprints around distributed workforce models.
Germany
Pfandbrief-covered bond market conventions create structural demand for fixed-rate intermediation across Munich, Frankfurt, and Hamburg metropolitan regions. The country's federal financial supervisory authority applies consumer credit directives requiring standardized disclosure of total borrowing costs. Berlin and Stuttgart brokerages are piloting open-banking API integration to compress verification cycles for credit-challenged applicants.
Global Mortgage/Loan Brokers Market Competitive Landscape
Channel exclusivity dominates the current landscape as brokerages defend positioning against direct-to-consumer digitization. The vendor base stratifies across three tiers: balance-sheet lenders operating captive broker networks, independent mortgage banks with wholesale-only distribution, and technology-enabled platforms algorithmically matching borrowers to capital sources. Strategic archetypes include the broker-exclusive pure-play, the depository-anchored hybrid, and the fintech-integrated aggregator. M&A activity concentrates on acquiring digital underwriting capabilities, while strategic partnerships with real estate platforms reshape referral economics.
Within the broker-exclusive tier, United Wholesale Mortgage and CrossCountry Mortgage exemplify divergent specialization strategies. United Wholesale Mortgage sustains positioning through refusal of direct-to-consumer origination, maintaining wholesale-only distribution. CrossCountry Mortgage occupies a position specializing in non-qualified mortgage products that larger depositories avoid. Rocket Mortgage anchors the technology-integrated archetype, representing algorithmic underwriting convergence against traditional broker speed advantages.
| Leading Market Players |
|---|
| Truist Financial Corporation |
| United Wholesale Mortgage |
| Bank of America |
| CrossCountry Mortgage |
| Rocket Mortgage |
| Royal Bank of Canada |
| Mitsubishi UFJ Financial Group |
| JPMorgan Chase Bank |
| BNP Paribas |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up broker networks in the United States and Australia anchor supply-side consolidation, concentrating origination capacity within scaled platforms that extract volume discounts from wholesale lenders while compressing yield-spread premiums across standardized product tiers.
Pricing Analysis
Lender-paid commission structures dominate broker compensation, with yield-spread premiums varying by loan complexity and credit tier. Fee differentiation rests on documentation burden and regulatory compliance intensity, with self-employed borrower files commanding premium pricing versus standard W-2 salaried applications. Cost compression in fixed-rate origination is intensifying because algorithmic underwriting at direct lenders erodes the broker's speed premium in prime-credit segments. First-time buyers exhibit highest price sensitivity, while high-net-worth applicants seeking interest-only structures show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from correspondent lenders mandate brokerages maintain relationships with multiple wholesale funding sources to ensure capacity during rate-lock volatility. Capital provision concentrates in the United States, the United Kingdom, and Australia, where warehouse lending facilities and securitization markets feed liquidity into broker channels. The supply chain draws from credit bureau data, automated valuation models, and open-banking API infrastructure. Single-source vulnerability in algorithmic underwriting talent creates operational risk. Distribution runs through broker-exclusive wholesale networks, direct-to-consumer platforms, and hybrid advisory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Mortgage/Loan Brokers Market functions as a geographic-arbitrage play where regulatory divergence between the United States and Australia creates compliance-cost differentials that favor cross-border platform operators with modular technology stacks.
For Market Incumbents: Deploy proprietary algorithmic underwriting as the primary defensive lever. United Wholesale Mortgage's broker-exclusive channel model demonstrates how refusing direct-to-consumer origination preserves wholesale relationships. Incumbents must consolidate digital underwriting capabilities through targeted acquisition of fintech-integrated platforms before balance-sheet lenders close the speed gap entirely. Channel control through exclusive lender agreements remains critical as Rocket Mortgage's technology-integrated archetype erodes traditional broker advantages. For New Entrants and Emerging Players: Begin with non-qualified mortgage documentation support for self-employed borrowers and credit-challenged applicants in Australian and United States suburban corridors. These segments remain underserved by automated approval engines at major depositories. The most penetrable entry point combines mobile-optimized application portals with specialized manual underwriting expertise for complex income verification. A go-to-market angle anchored in open-banking API integration can collapse verification cycles and differentiate against legacy broker networks. For Investors and Strategic Acquirers: Balance-sheet lenders with captive broker networks are the most active acquirers in this space, seeking digital underwriting capabilities to defend against fintech disintermediation. Long-term viability hinges on the broker's ability to maintain relevance in prime-credit segments where direct lender digitization accelerates. Acquisition targets should display algorithmic pre-approval engines paired with specialized non-QM product expertise. The signal to watch is regulatory relaxation of responsible lending obligations in Australia or yield-spread premium compression in United States fixed-rate markets.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Banking API Integration | Real-time financial data portability collapses verification cycles for credit-challenged applicants across Australian and United Kingdom markets. |
| Non-Qualified Mortgage Product Expansion | Specialized documentation support captures white space that larger depositories avoid in self-employed borrower segments. |
| Algorithmic Pre-Approval Engine Development | Automated valuation model integration compresses origination timelines from weeks to days in United States suburban corridors. |
| Broker-Exclusive Channel Commitment | Refusal of direct-to-consumer origination preserves wholesale lender relationships and defends against Rocket Mortgage's technology convergence. |
| Distributed Workforce Infrastructure | Cloud-based underwriting platforms reduce physical branch dependency and expand geographic coverage in United Kingdom metropolitan markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mortgage brokerage executives, wholesale lender relationship managers, regulatory compliance officers, and technology platform engineers with secondary validation. Secondary sources encompassed CFPB enforcement actions, FCA Mortgage Conduct of Business guidance, ASIC licensing determinations, and securitization prospectuses from major broker networks. Bottom-up origination volume estimates and top-down market sizing triangulated across correspondent lending disclosures and warehouse line utilization data.
Historical reference periods spanning the pre-pandemic baseline through recent rate volatility anchored the forecast window. The analytical framework segmented volume across loan type, customer profile, distribution channel, and service model dimensions. CAGRs derived from regression analysis against housing starts, mortgage rate movements, and regulatory change indicators. Industry-specific inputs included first-time buyer participation rates, refinance incentive sensitivity, and open-banking adoption curves.
Several conditions sit outside the modeled scope, including abrupt shifts in central bank monetary policy, wholesale lender capacity contractions, and disruptive regulatory reinterpretations of responsible lending obligations. Forecasts reflect assumptions about steady housing demand and incremental technology adoption rather than step-change disruption. Deviation in algorithmic underwriting penetration at direct lenders or yield-spread compression severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
North America Mortgage/Loan Brokers Market