
 Global Automotive Electronic Brake System Market | 2026-2036
Global Automotive Electronic Brake System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Electronic Brake System Market Intelligence
The modularization of braking components into integrated safety packages is hardening the specification requirements for Tier-1 suppliers. Robert Bosch GmbH leverages its extensive portfolio in sensors and control units to offer complete systems. Continental AG specializes in advanced driver-assistance system (ADAS) integration with its braking solutions. ZF Friedrichshafen AG competes with its expertise in both conventional and brake-by-wire technologies, targeting diverse vehicle platforms.
An automotive electronic brake system is a network of sensors, electronic control units (ECUs), and actuators that manage vehicle braking. These systems modulate brake pressure at individual wheels to prevent lock-up and maintain stability. While Electronic Stability Control constitutes a mature product category, brake-by-wire systems linked to regenerative braking technology are expanding rapidly, particularly in the Electric Vehicles application. This evolution serves to enhance vehicle safety and control during emergency maneuvers or on low-friction surfaces.
Regulatory mandates for vehicle safety are a primary market accelerator. The United States' NHTSA and the European Union's General Safety Regulation require features like Electronic Stability Control in all new vehicles. In parallel, China's GB standards for vehicle safety performance create stringent requirements for market entry. System suppliers must now navigate the diverging technical standards for autonomous driving integration and cybersecurity protocols.
Market Dynamics
The convergence of vehicle electrification and stringent safety mandates defines the market's core dynamic. This dual pressure forces a rapid evolution from standalone components to deeply integrated systems where regenerative braking, stability control, and driver-assistance functions are inseparable.
Growth Catalysts
- Regulatory Mandates:The European Union's General Safety Regulation and similar NHTSA rules in the United States requiring Electronic Stability Control and advanced emergency braking in new vehicles provide a foundational demand floor.
- Electric Vehicle Adoption:The technical requirements of EVs, specifically the need to blend friction braking with regenerative braking to maximize range and efficiency, necessitate more sophisticated electronic control systems.
- Manufacturing Scale in China:Government support for the New Energy Vehicle (NEV) industry and a vast domestic automotive production base make China a primary growth engine for advanced braking system deployment.
Market Restraints
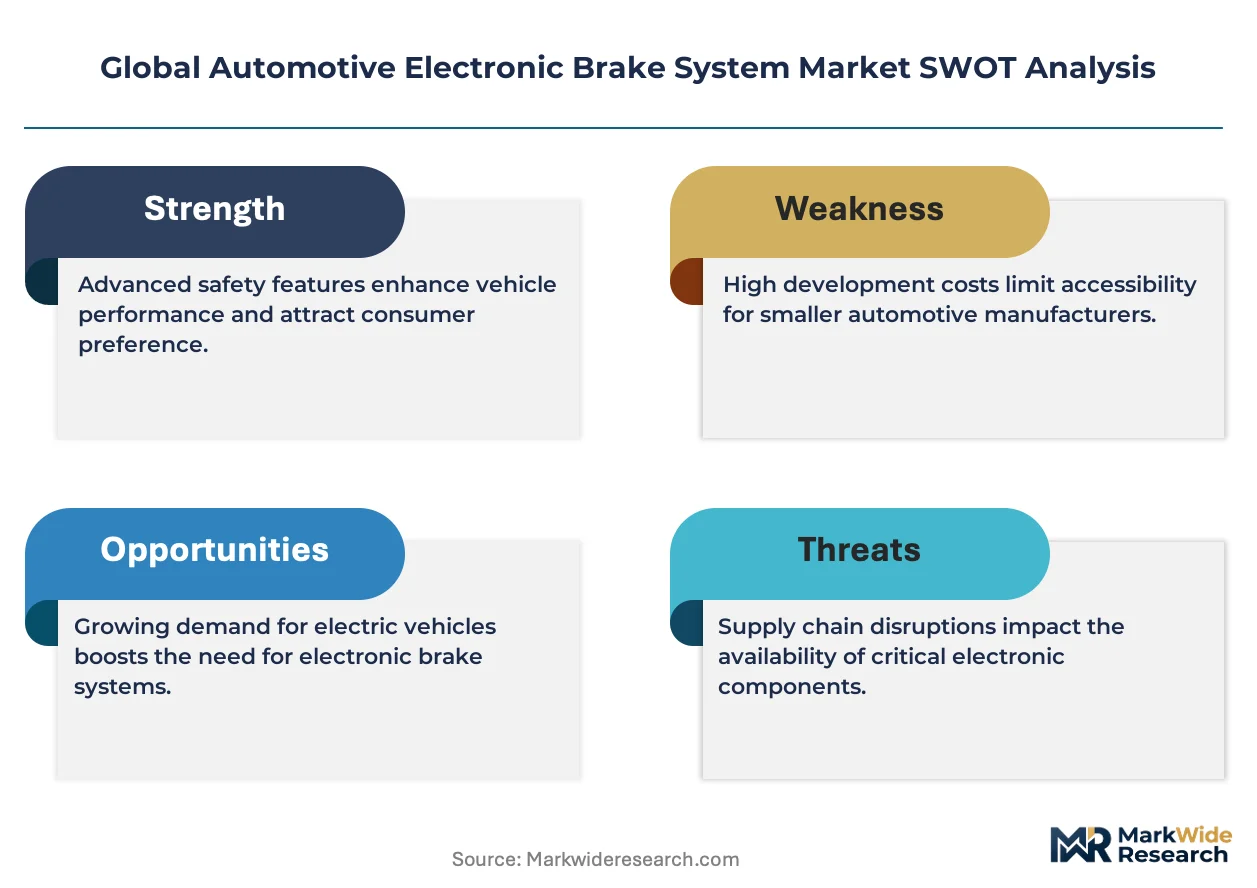
- System Complexity and Cost:The high initial cost and software development complexity of brake-by-wire systems limit their application in cost-sensitive, economy vehicle segments, slowing mass-market penetration.
- Semiconductor Supply Chain Vulnerability:Heavy reliance on microcontrollers, sensors, and other specialized semiconductors for ECUs exposes the supply chain to the volatility and shortages seen in the global chip market.
- Cybersecurity Risks:As braking systems become more connected and software-defined, they represent a larger attack surface for malicious actors, creating significant technical and liability hurdles for manufacturers.
Strategic Opportunities
- Software-Defined Braking:The development of braking systems whose performance characteristics can be modified via over-the-air (OTA) updates creates new revenue streams through subscription services and feature upgrades.
- Commercial Vehicle Integration:There is a significant opportunity to adapt advanced electronic braking, including stability control and autonomous emergency braking, for heavy-duty trucks and buses to improve fleet safety and efficiency. *Sensor Fusion for Predictive Braking: Integrating brake control logic with data from V2X (Vehicle-to-Everything) communication and advanced sensor suites enables predictive braking actions that anticipate hazards before a driver can react.
Industry Challenges
- Standardization Gaps:A lack of universal standards for communication protocols and hardware interfaces between braking components and other vehicle domains complicates development and increases integration costs for Tier-1 suppliers.
- Functional Safety Expertise Shortage:The industry faces a persistent talent gap for systems engineers and software developers with deep expertise in functional safety standards like ISO 26262, which are critical for safety-critical systems.
- Legacy System Integration:Implementing modern electronic brake systems into vehicle platforms that were not originally designed for them presents significant technical and validation challenges, particularly in mixed-powertrain fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Electronic Brake System Market |
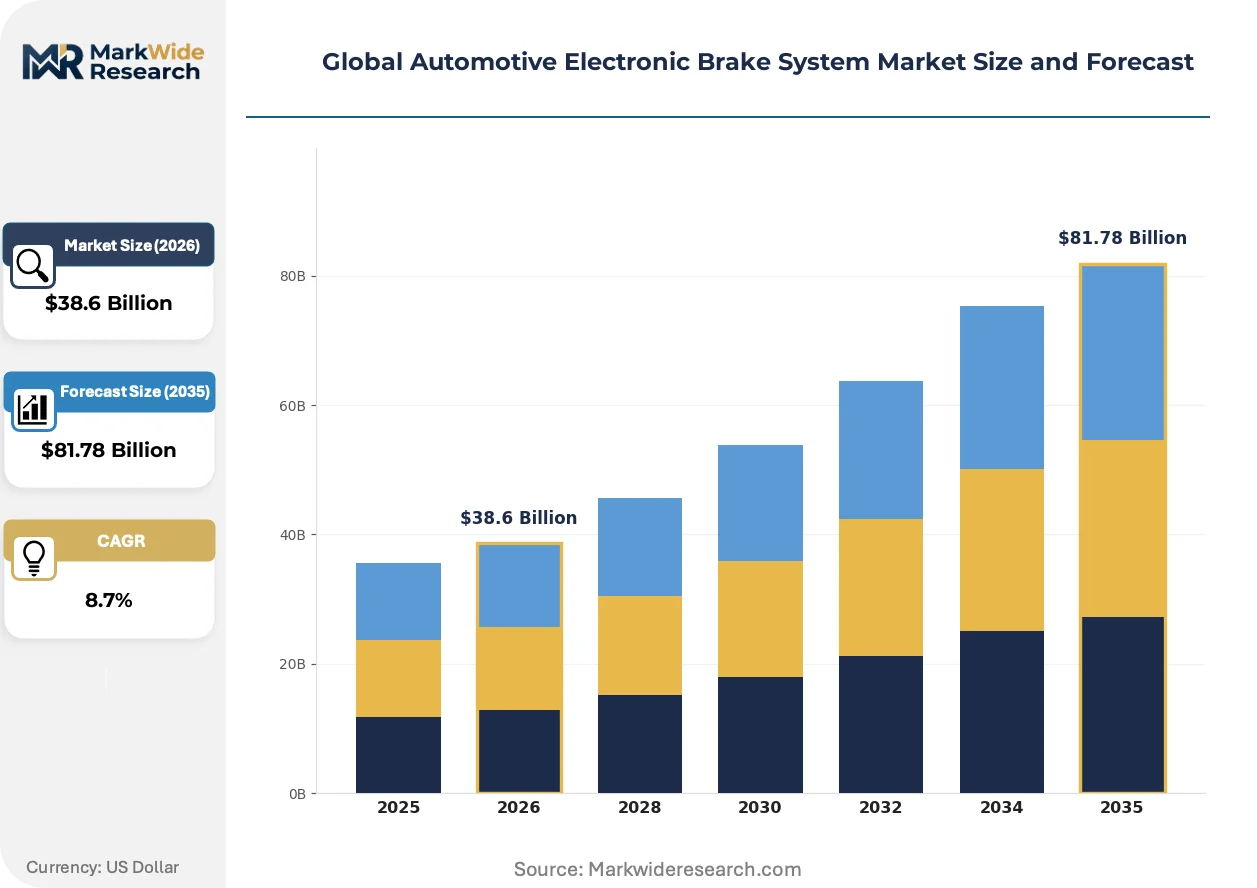
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antilock Braking System, Electronic Stability Control, Traction Control System, Brake-by-Wire, Emergency Brake Assist Technology: Hydraulic, Electro-Mechanical, Electro-Hydraulic, Pneumatic, Regenerative Braking Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Off-Highway Vehicles, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Service Providers |
| Companies Covered | Aisin Corporation, Knorr-Bremse AG, Robert Bosch GmbH, Hitachi Astemo Ltd., Mando Corporation, Continental AG, Brembo S.p.A., Akebono Brake Industry Co. Ltd., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Electronic Brake System Market Strategic Shifts & Innovations
The transition from hardware-dominated components to software-defined functions is the principal theme shaping innovation. This evolution is driven by the parallel needs for enhanced vehicle efficiency in EVs and the fail-operational safety required for higher levels of autonomous driving.
Distributed control logic is a key architectural evolution, using smart actuators with integrated micro-controllers at each wheel. This approach is gaining traction first in premium electric vehicles and performance cars due to its enhanced redundancy. This architectural shift is decentralizing control logic away from a single, central ECU, improving system response time and fault tolerance.
Global cybersecurity regulations, such as UNECE WP.29 R155, are directly influencing system design. This mandate requires automakers to implement and certify comprehensive cybersecurity management systems across the entire vehicle lifecycle, from development to post-production. The electronic brake system, as a primary safety-critical function, receives the most scrutiny, demanding robust protection against remote intrusion.
Value perception is pivoting from purely mechanical specifications to software-enabled capabilities, such as driver-selectable regenerative braking modes or one-pedal driving features. This shift alters procurement conversations between automakers and suppliers, focusing on feature sets and upgradability over simple component cost. The trend is most pronounced in the competitive EV markets of Europe and China.
Global Automotive Electronic Brake System Market Segmentation
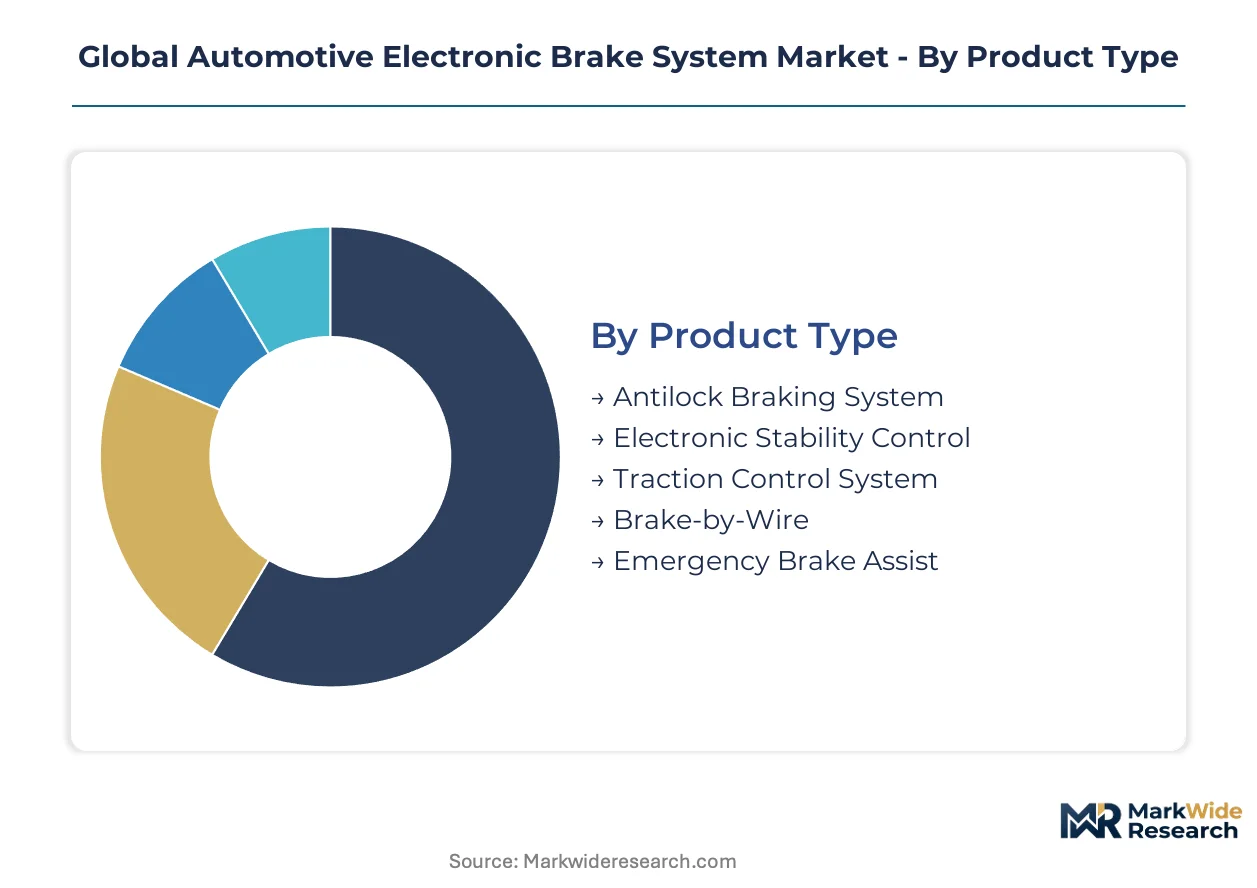
Segmentation of the global automotive electronic brake system market illuminates the diverse technological requirements and strategic priorities across various vehicle platforms. This granular analysis helps manufacturers align product development with specific end-user demands and identify high-growth segments for targeted investment strategies.
Product Type:
The product type segmentation delineates the integration depth of braking components, from standalone safety features to deeply embedded system architectures within modern vehicles.
- Electronic Stability Control:This system automatically modulates individual wheel braking to prevent skidding and maintain vehicle control during critical maneuvers. Demand is foundational in Europe and the United States due driven by stringent regulatory mandates for vehicle safety.
- Brake-by-Wire:This advanced technology replaces conventional hydraulic or mechanical linkages with electronic signals for precise braking actuation. Demand is concentrating in Electric Vehicles, driven by the need for seamless integration with regenerative braking to enhance overall vehicle efficiency.
- Antilock Braking System:This system prevents wheel lock-up during hard braking, allowing the driver to maintain steering control.
- Traction Control System:Limits wheel spin during acceleration, improving vehicle stability and grip, particularly on slippery surfaces.
- Emergency Brake Assist:Augments braking force when a driver initiates emergency deceleration, optimizing stopping performance.
Volume placements concentrate in Electronic Stability Control; the faster expansion belongs to Brake-by-Wire.
Technology:
The technology segmentation traces the evolution of braking actuation, from conventional fluid-based systems to advanced energy recovery mechanisms and fully electronic control.
- Hydraulic:This traditional technology utilizes fluid pressure to transmit braking force from the pedal to the calipers, providing a reliable stopping mechanism. Hydraulic systems remain prevalent in most conventional vehicles, forming the backbone of many braking architectures.
- Regenerative Braking:This innovative technology converts kinetic energy into electrical energy during deceleration, recharging the vehicle's battery. Regenerative braking is critical for Electric Vehicles to maximize range and efficiency, significantly reducing wear on friction brakes.
- Electro-Mechanical:Employs electric motors and gears to apply braking force, offering precise control and eliminating hydraulic fluids.
- Electro-Hydraulic:Combines hydraulic power with electronic control for enhanced responsiveness and integration with advanced safety features.
- Pneumatic:Uses compressed air to actuate brakes, primarily found in heavy-duty commercial vehicles due to its power and reliability.
Hydraulic systems remain the dominant technology, while regenerative braking is rapidly gaining traction in new vehicle designs.
Application:
The application segmentation highlights diverse demand sources for electronic brake systems across various vehicle types and operational profiles, each with unique performance requirements.
- Passenger Cars:This segment represents the largest volume for electronic brake systems, driven by widespread adoption of safety features and evolving consumer expectations. Regulatory mandates in Europe and the United States ensure a consistent demand floor for these vehicles.
- Electric Vehicles:Requires specialized electronic brake systems to seamlessly integrate friction and regenerative braking for optimal performance. Demand is accelerating in China due to significant government support for New Energy Vehicles and range extension priorities.
- Commercial Vehicles:Integrates advanced braking for enhanced safety, stability, and load management in heavy-duty transport and logistics fleets.
- Two-Wheelers:Incorporates electronic braking systems for improved rider safety, stability, and accident prevention, especially in adverse conditions.
- Off-Highway Vehicles:Utilizes robust electronic braking solutions for challenging terrain, heavy-load operations, and specialized industrial applications.
Passenger Cars hold the largest share, but Electric Vehicles are experiencing the steepest growth trajectory.
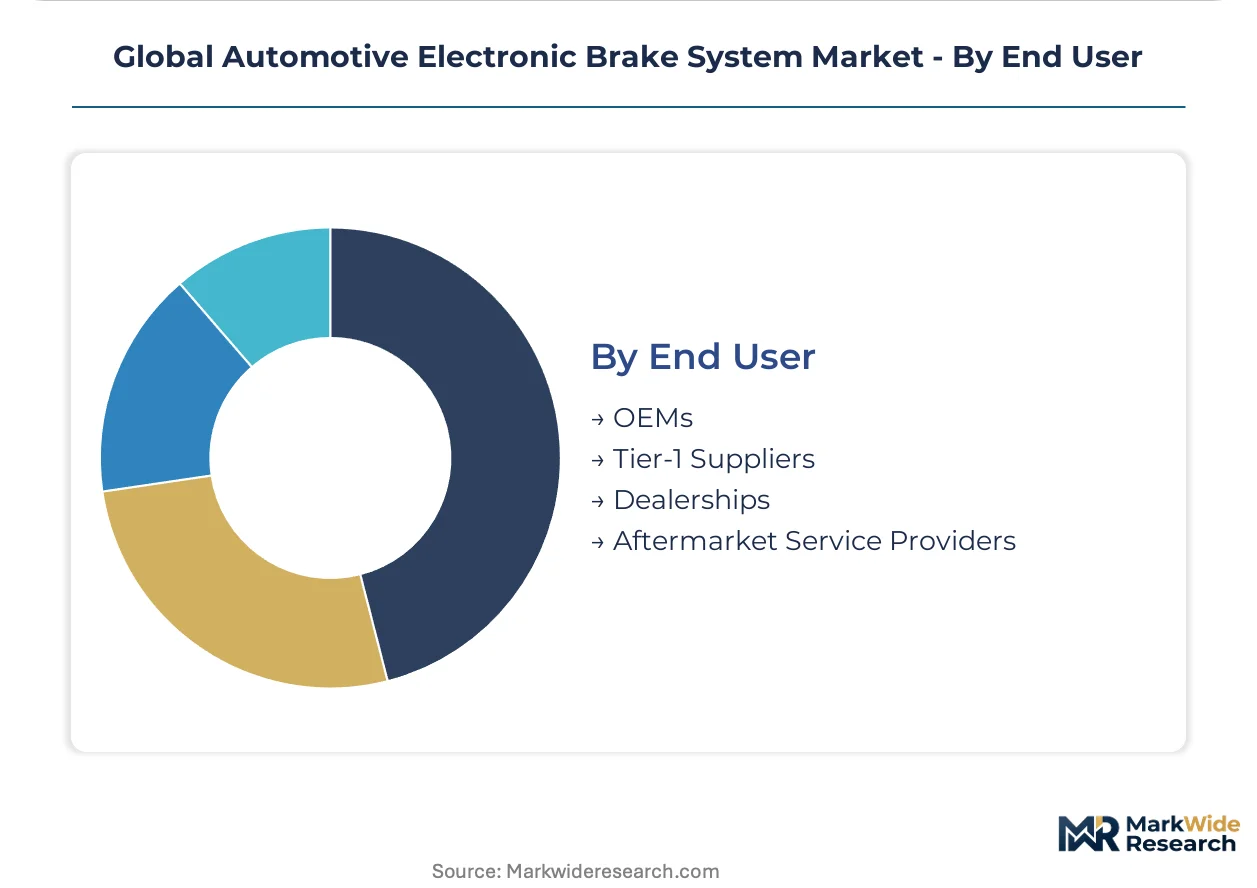
End User:
The end-user segmentation maps the primary procurement points and integration stages for electronic brake system components across the automotive value chain, from manufacturing to maintenance.
- OEMs:Original Equipment Manufacturers integrate electronic brake systems directly into new vehicle production lines, setting specifications and managing final assembly. Their demand is driven by new model launches and evolving safety standards from bodies like NHTSA.
- Tier-1 Suppliers:These companies develop and supply complete electronic brake system modules and sub-systems directly to OEMs. Their strategic importance stems from specialized expertise in areas like sensor fusion and control unit software development.
- Dealerships:Provide installation and maintenance services for electronic brake components, especially for upgrades or repairs during the vehicle's lifecycle.
- Aftermarket Service Providers:Focus on repair, replacement, and diagnostics of electronic brake systems for vehicles outside warranty periods, ensuring continued operational safety.
OEMs and Tier-1 suppliers represent the primary demand, while dealerships and aftermarket providers offer crucial support services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust support for its New Energy Vehicle (NEV) industry, particularly in zones like the Yangtze River Delta, drives significant demand for advanced electronic brake systems. This strategic focus positions the country as a primary growth engine for global automotive technology. Diverse regional dynamics across key automotive manufacturing hubs further shape market development.
China
China's accelerating Electric Vehicle adoption and vast domestic automotive production base create substantial demand for electronic brake systems. Its GB standards for vehicle safety performance impose stringent requirements for market entry. Automotive manufacturing clusters in Shanghai, Shenzhen, and Guangzhou actively integrate advanced braking technologies into new vehicle platforms.
United States
United States demand for electronic brake systems stems from stringent NHTSA safety mandates and consumer preferences for advanced driver-assistance features. The agency's regulations, including those for Electronic Stability Control, establish a foundational demand floor for new vehicles. Research and development hubs in Detroit and Silicon Valley focus on integrating brake-by-wire systems with autonomous driving platforms.
Germany
Germany's strong premium automotive sector and advanced engineering capabilities drive demand for sophisticated electronic braking solutions. The European Union's General Safety Regulation mandates features like Electronic Stability Control in all new vehicles. Major automotive centers in Bavaria and Baden-Württemberg lead innovation in brake-by-wire and integrated safety systems.
Japan
Japan exhibits steady demand for electronic brake systems, driven by its robust hybrid vehicle production and emphasis on advanced safety features. Compliance with JIS standards for automotive components ensures high-quality system integration across vehicle platforms. Manufacturing hubs in Aichi Prefecture and Kanagawa Prefecture specialize in precision engineering for braking control units.
India
India's market for electronic brake systems is expanding due to rapid urbanization, rising safety awareness, and emerging EV adoption. Upcoming safety norms, such as those under the BNVSAP, will accelerate the integration of advanced braking technologies. Automotive manufacturing centers in Chennai and Pune are increasing local production capabilities for these critical components.
Global Automotive Electronic Brake System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the global automotive electronic brake system market, creating a dynamic competitive environment. The market exhibits a tiered structure, ranging from broad-portfolio Tier-1 suppliers providing comprehensive solutions to niche technology providers specializing in specific components. Strategic archetypes include integrated system providers, component specialists, and software-centric innovators developing next-generation control logic. Dominant competitive moves involve forming strategic partnerships for ADAS integration and continuous investment in advanced brake-by-wire technology development and refinement.
Within the integrated system provider archetype, Robert Bosch GmbH, a diversified German conglomerate, leverages its extensive portfolio in sensors and control units to offer complete electronic brake systems. Continental AG, another prominent German-based public limited company, occupies a strong position as a specialist in advanced driver-assistance system integration, embedding these capabilities within its braking solutions. ZF Friedrichshafen AG, also a significant German entity, exemplifies a competitor with expertise spanning both conventional hydraulic braking and advanced brake-by-wire technologies, catering to diverse vehicle platforms.
| Leading Market Players |
|---|
| Aisin Corporation |
| Knorr-Bremse AG |
| Robert Bosch GmbH |
| Hitachi Astemo Ltd. |
| Mando Corporation |
| Continental AG |
| Brembo S.p.A. |
| Akebono Brake Industry Co. Ltd. |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
Stringent regulatory mandates from the United States' NHTSA and the European Union's General Safety Regulation create a foundational demand floor for electronic brake systems. This pressure forces suppliers to integrate advanced safety features, influencing pricing dynamics and requiring significant investment in compliant supply chains.
Pricing Analysis
Premium pricing for short lead times and customized solutions reflects the urgency of OEM integration cycles. Contract-based long-term offtake agreements dominate the market, driven by the need for stable supply and partnership-based development. Price differentiation stems from functional safety certifications like ISO 26262 and the level of customization for specific vehicle platforms. OEM cost optimization and intense competition among Tier-1 suppliers exert downward pricing pressure, with economy vehicle segments exhibiting the highest price sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle the majority of electronic brake system distribution for new vehicle production. Supply concentration centers in Germany, China, and Japan, reflecting the presence of major Tier-1 suppliers and automotive manufacturing hubs. The system relies heavily on microcontrollers, sensors, and specialized semiconductors as key component dependencies. Semiconductor supply chain vulnerability represents a significant structural risk, impacting production stability for these complex systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global automotive electronic brake system market is fundamentally a cost-of-compliance story, where regulations like UNECE WP.29 R155 for cybersecurity establish a significant barrier-to-entry moat for non-compliant players.
For Market Incumbents:Lock in long-term development partnerships with major OEMs to co-develop next-generation brake-by-wire and software-defined braking solutions. Acquire niche software specialists to bolster in-house functional safety expertise, mitigating the threat from emerging software-centric players. Invest heavily in advanced R&D for cybersecurity protocols and fail-operational architectures, securing market position against increasing attack surfaces. Deepen vertical integration into critical component manufacturing to reduce supply chain dependencies.
For New Entrants and Emerging Players:A price-point gap exists between premium and economy vehicle segments for advanced electronic brake systems, offering an entry opportunity. Target cost-effective brake-by-wire solutions for mid-range electric vehicles or specialized cybersecurity modules for commercial fleets. Partner with smaller EV startups or commercial vehicle manufacturers seeking agile, customized solutions. Focus on aftermarket upgrades for older vehicle platforms where advanced features can be retrofitted.
For Investors and Strategic Acquirers:Re-rating potential sits with software-centric innovators and specialized sensor manufacturers given the accelerating shift towards software-defined vehicles. Long-term viability is anchored in the continuous integration of braking systems with autonomous driving platforms and EV powertrain management. Identify acquisition targets with deep expertise in functional safety software or advanced sensor fusion capabilities. The acceleration of Level 3+ autonomous driving deployments serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs and accelerates deployment of electronic brake systems across diverse vehicle models for OEMs. |
| Software-Defined Vehicle Investment | Enables over-the-air updates and new revenue streams through feature upgrades for advanced braking functionalities. |
| Strategic Partnership | Integrates advanced driver-assistance systems and V2X communication with core braking control logic. |
| Acquisition of Specialist Firm | Bolsters expertise in cybersecurity protocols and functional safety for critical electronic brake system components. |
| Geographic Manufacturing Footprint | De-risks supply chains and optimizes delivery costs for electronic brake systems in key markets like China. |
Research Approach
Automotive industry reports, regulatory body publications from NHTSA, and company financial filings formed the secondary backbone for this analysis. Primary interviews with OEM platform engineers, Tier-1 procurement leads, functional safety experts, and aftermarket distributors provided direct market insights. This approach combined bottom-up data collection with top-down validation, ensuring comprehensive market understanding.
Historical trendline analysis and market sizing models underpinned the projection of growth across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional production cluster. Compound annual growth rates were derived from historical growth rates and projected adoption curves for new technologies. Key forecast inputs included global vehicle production forecasts and electric vehicle adoption rates.
Inputs from industry reports and company disclosures were available through the study window; gaps in granular regional EV policy impacts introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Radio Dot System (RDS) Market