
 Sound Reception System Market | 2026-2036
Sound Reception System Market Size, Share, and Industry Trends Forecast 2026-2036
Sound Reception System Market Analytics
Marine electronics distribution is reconfiguring as vessel operators consolidate procurement through integrated maritime communication suppliers. Kongsberg Maritime leverages its Nordic shipyard relationships to sustain long-term service contracts for bridge audio systems. Jotron AS anchors its position through SOLAS-compliant product portfolios that dominate offshore platform installations. Zenitel competes in the commercial shipping channel by specializing in IP-based public address and general alarm systems.
A sound reception system comprises microphones, transducers, amplifiers, and signal processing units engineered to capture, convert, and reproduce acoustic energy across defined frequency ranges, typically spanning 20 Hz to 20 kHz for full-spectrum applications. These systems serve critical functions in telecommunications infrastructure, broadcast studios, and maritime safety bridges where intelligibility under ambient noise conditions determines operational effectiveness. Digital technology leads professional audio segments due to networked Dante and AES67 protocol integration that reduces cabling complexity in live events and music production environments. Wireless technology grows fastest in broadcast and live events as spectrum-efficient UHF and 5 GHz solutions displace cabled stage monitoring. Analog maintains residual share in legacy automotive and healthcare installations where electromagnetic interference resilience outweighs connectivity benefits.
FCC Part 15 regulations in the United States govern unlicensed wireless microphone operations in the 600 MHz band, directly constraining product development cycles for manufacturers targeting North American broadcast and live events customers. The EU Radio Equipment Directive and CE marking requirements enforce electromagnetic compatibility and spectrum efficiency standards that shape market access for wireless audio equipment across European member states. IEC 60945 maritime equipment standards, administered by classification societies, mandate environmental testing protocols for bridge-mounted sound reception systems that Jotron and Kongsberg must satisfy for type approval. Stakeholders must monitor ongoing spectrum reallocation proceedings and emerging low-latency wireless protocols to anticipate product obsolescence risks and certification timeline shifts.
Market Dynamics
The transition from analog to networked digital architectures is compressing installation timelines and reshaping supplier relationships across professional audio segments. Dante and AES67 protocol adoption is collapsing traditional cabling requirements in live events and broadcasting studios, forcing equipment manufacturers to recalibrate hardware margins against software licensing revenues.
Growth Catalysts
- EU Radio Equipment Directive:Electromagnetic compatibility mandates for wireless audio equipment are accelerating replacement cycles in European broadcast infrastructure.
- Maritime safety bridge retrofits:SOLAS compliance requirements for intelligible alarm systems are expanding addressable market in offshore platform installations.
- 5 GHz spectrum allocation:Spectrum-efficient wireless protocols are enabling stage monitoring applications previously constrained by UHF congestion.
Market Restraints
- Rare earth magnet supply concentration:Neodymium dependency on Chinese processing capacity creates input cost volatility for transducer manufacturers.
- FCC Part 15 spectrum reallocation:600 MHz band restrictions constrain product development cycles for North American wireless microphone vendors.
- Legacy analog installed base:Electromagnetic interference resilience in automotive and healthcare settings slows digital substitution timelines.
Strategic Opportunities
- IP-based public address systems:Ethernet infrastructure convergence offers white space in commercial shipping channel against traditional analog installations.
- German pro-audio manufacturing cluster:Berlin and Munich supplier concentration creates partnership opportunities for component sourcing optimization.
- Healthcare acoustic monitoring:FDA-regulated patient monitoring applications represent underpenetrated end-use for intelligibility-optimized microphone arrays.
Industry Challenges
- IEC 60945 type approval timelines:Maritime classification society testing protocols extend certification cycles for bridge-mounted equipment.
- Dante/AES67 integration complexity:Networked audio protocol interoperability demands specialized firmware engineering talent scarce among traditional analog vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sound Reception System Market |
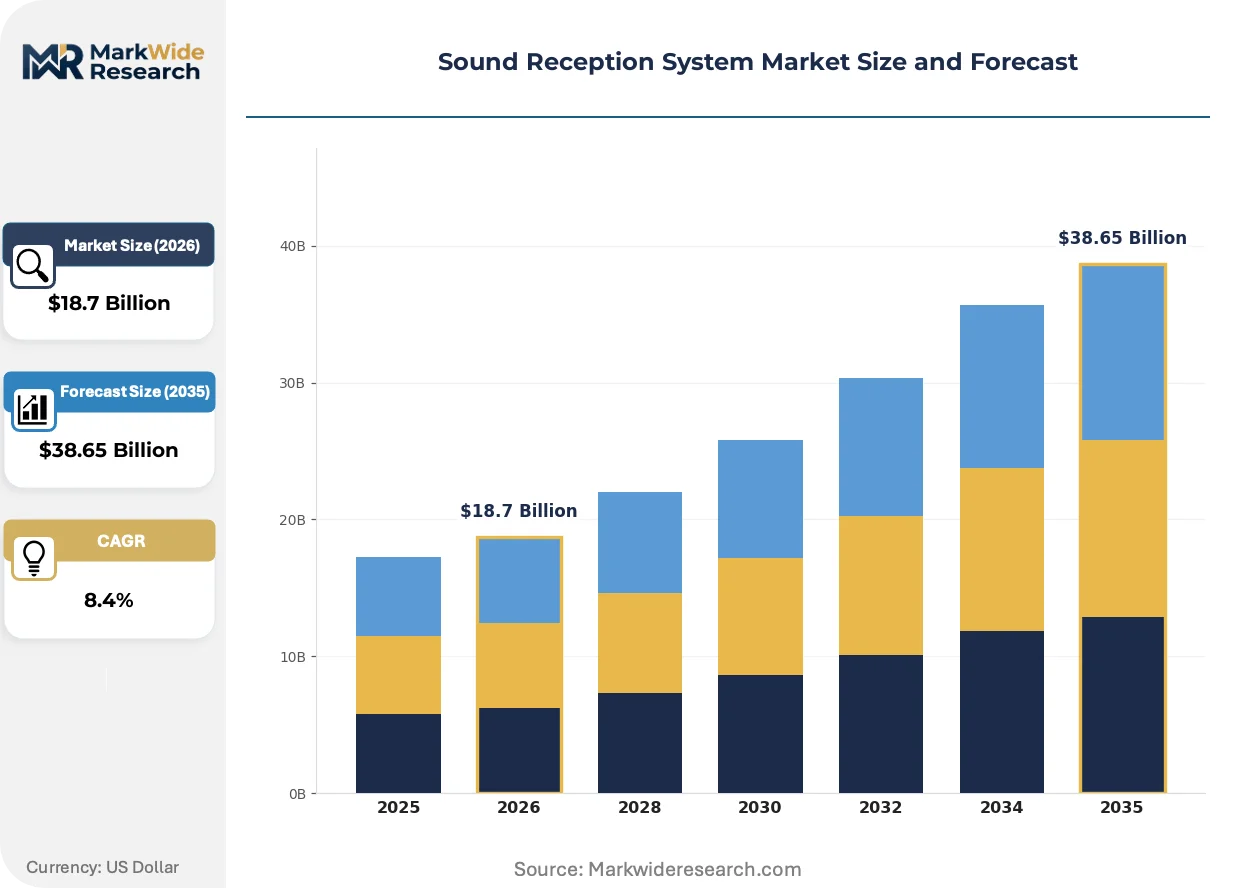
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Transducers, Speakers, Amplifiers Application: Telecommunications, Music Production, Broadcasting, Live Events Technology: Wireless, Analog, Digital, Hybrid End User: Consumer Electronics, Professional Audio, Automotive, Healthcare |
| Companies Covered | Jotron AS, Kongsberg Maritime, Zenitel, Mackay Communications, Omega Integration, H. Brennan, PacAtlantic, JBL, QSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sound Reception System Market Evolving Landscape
Wireless protocol evolution and regulatory spectrum management are restructuring competitive advantage around software-defined signal processing rather than hardware differentiation. The convergence of professional audio with IT infrastructure is blurring traditional category boundaries between broadcast, telecommunications, and maritime safety equipment.
Beamforming microphone arrays is collapsing the distinction between capture and processing stages in conference room installations. Corporate IT departments are adopting these systems at accelerated pace to support hybrid work infrastructure. The technology is collapsing hardware component counts while shifting value capture toward DSP algorithm licensing.
REACH substance restrictions on hazardous materials in electrical equipment are forcing transducer manufacturers to reformulate magnet assemblies and cone materials. Supply chain requalification costs are compressing margins for European-market products. German and Danish suppliers are responding fastest with alternative material certifications.
Long-term service contracting is displacing transactional equipment sales in maritime bridge audio segments. Shipyard consolidation favors integrated maritime communication suppliers with captive installation and maintenance capabilities. Nordic vessel operators are driving this shift through preference for single-source accountability across navigation and alarm systems.
Sound Reception System Market Segmentation
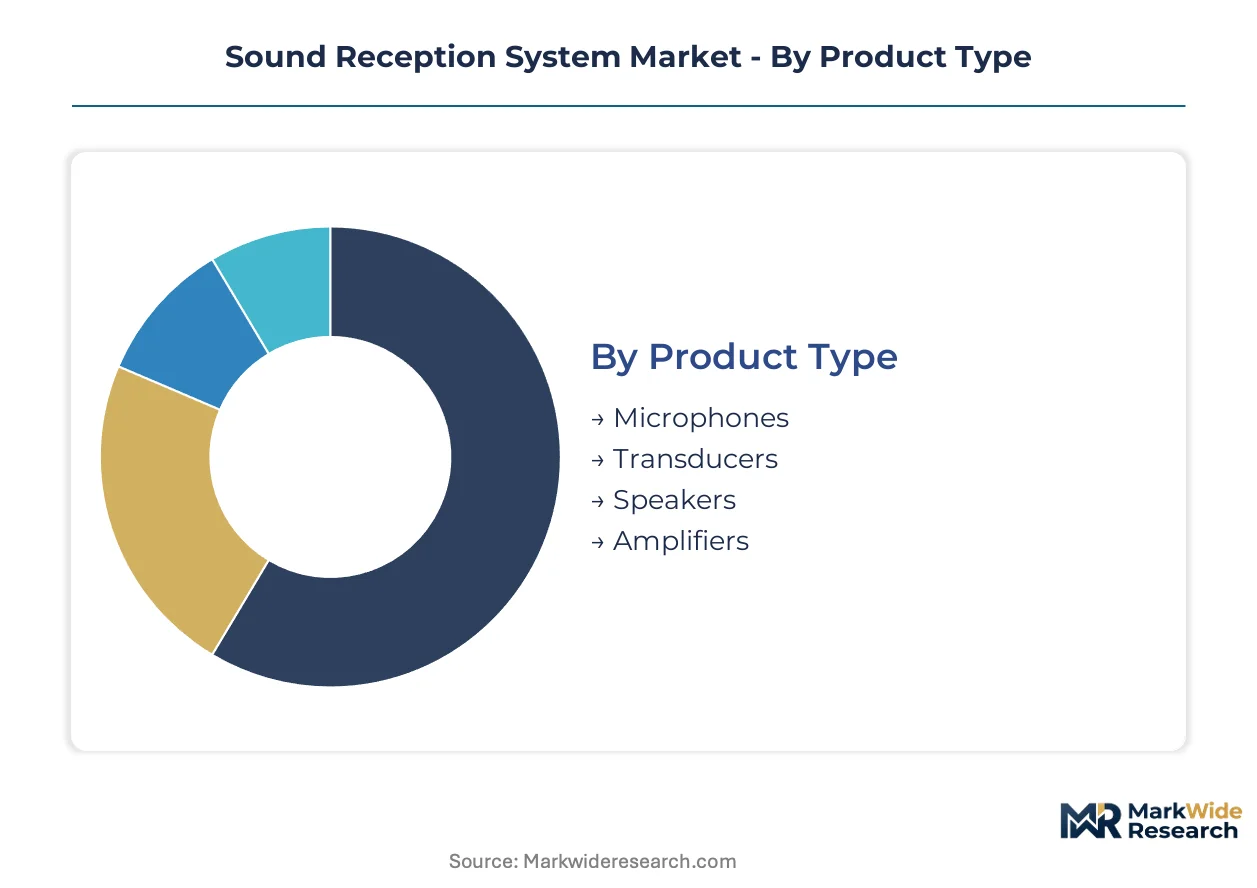
Sound reception system procurement patterns diverge sharply across product architectures, end-use environments, and technology generations. Vendors must align R&D roadmaps and distribution channels with segment-specific certification requirements and buyer consolidation trends.
Product Type:
Cost tier stratification determines margin structure and customer concentration across the four hardware categories.
- Microphones:Electret condenser and MEMS designs dominate consumer electronics, while large-diaphragm condensers anchor professional studio installations. Demand concentrates in Germany's pro-audio manufacturing cluster around Berlin, where broadcast infrastructure upgrades under EU Radio Equipment Directive compliance timelines accelerate replacement cycles.
- Transducers:Neodymium magnet assemblies and voice coil configurations convert electrical signals to mechanical vibration across frequency ranges. Rare earth supply concentration in Chinese processing capacity creates input cost volatility that German and Danish suppliers are addressing fastest through alternative material certifications under REACH substance restrictions.
- Speakers:Driver arrays span coaxial stage monitors to line-array concert systems.
- Amplifiers:Class-D switching topologies displace linear designs in weight-sensitive live events applications.
Microphones hold installed capacity. Transducers are rotating up the share rankings.
Application:
Application maturity determines protocol standardization and vendor consolidation intensity.
- Broadcasting:Networked Dante and AES67 protocol integration collapses traditional cabling requirements in television and radio studios. FCC Part 15 regulations in the 600 MHz band constrain product development cycles for North American wireless microphone vendors, while EU electromagnetic compatibility mandates accelerate European infrastructure replacement.
- Live Events:Spectrum-efficient UHF and 5 GHz wireless solutions displace cabled stage monitoring in concert touring and corporate events. 5 GHz spectrum allocation enables applications previously constrained by UHF congestion, though venue-specific RF coordination demands specialized engineering talent.
- Telecommunications:Beamforming microphone arrays support hybrid work infrastructure in enterprise conference rooms.
- Music Production:Project studio proliferation sustains demand for entry-level monitoring systems.
Broadcasting holds installed capacity. Live Events is climbing the fastest.
Technology:
Technology generation determines interoperability requirements and firmware engineering intensity.
- Digital:Networked architectures with Dante and AES67 protocol integration reduce cabling complexity and enable centralized DSP management. Professional audio installations in live events and broadcasting studios are expanding adoption, forcing equipment manufacturers to recalibrate hardware margins against software licensing revenues.
- Wireless:Software-defined signal processing and spectrum-efficient protocols are restructuring competitive advantage around algorithm licensing rather than hardware differentiation. UHF and 5 GHz solutions are gaining share fastest in broadcast and live events as stage monitoring applications escape cable constraints.
- Analog:Electromagnetic interference resilience sustains residual share in legacy automotive and healthcare installations where connectivity benefits are outweighed by reliability requirements.
- Hybrid:Mixed-signal designs bridge analog sensor front-ends with digital processing backplanes.
Analog holds installed capacity. Wireless is rotating up the share rankings.
End User:
End-user regulatory exposure determines certification timeline risk and long-term contracting preferences.
- Professional Audio:Live events and broadcasting studios drive networked digital system adoption with stringent intelligibility requirements under ambient noise conditions. SOLAS compliance requirements for maritime safety bridge retrofits expand addressable market in offshore platform installations served by integrated maritime communication suppliers.
- Healthcare:FDA-regulated patient monitoring applications represent underpenetrated end-use for intelligibility-optimized microphone arrays, with acoustic monitoring systems subject to electromagnetic compatibility standards that differ from consumer electronics.
- Consumer Electronics:MEMS microphone integration in smartphones and wearables sustains high-volume, low-margin production.
- Automotive:Legacy analog installations persist where electromagnetic interference resilience outweighs connectivity benefits, though infotainment system upgrades are pressuring digital substitution timelines.
Consumer Electronics holds installed capacity. Professional Audio is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government spectrum management and maritime safety mandates are redirecting procurement flows across major economies. National regulators are tightening electromagnetic compatibility standards while industrial clusters concentrate specialized manufacturing capabilities.
Germany
Broadcast infrastructure upgrades and pro-audio manufacturing expansion drive equipment demand. The EU Radio Equipment Directive enforces electromagnetic compatibility standards that accelerate replacement cycles in studio installations. Berlin and Munich host dense supplier networks where Dante protocol integration expertise concentrates among component specialists.
United States
Live events touring and broadcast studio retrofits sustain professional audio procurement. FCC Part 15 regulations constrain wireless microphone development in the 600 MHz band, compressing product cycles for domestic vendors. Nashville and Los Angeles anchor post-production and touring equipment distribution channels.
China
Neodymium processing dominance and consumer electronics manufacturing shape transducer supply dynamics. MIIT spectrum allocation policies govern wireless audio device certification timelines. Shenzhen and Dongguan clusters concentrate MEMS microphone fabrication for smartphone and wearable integration.
Norway
Offshore platform installations and Nordic shipyard relationships sustain maritime bridge audio demand. SOLAS compliance requirements administered by classification societies mandate IEC 60945 environmental testing for type approval. Kongsberg maintains integrated service contracts through long-term vessel operator partnerships.
Japan
Precision transducer engineering and broadcast infrastructure modernization support component demand. METI industrial standards coordinate with IEC frameworks for professional audio equipment certification. Tokyo and Osaka metropolitan areas concentrate R&D facilities for voice coil and magnet assembly optimization.
Sound Reception System Market Competitive Landscape
On the supply side, the industry is bifurcated between maritime safety specialists and professional audio generalists. Consolidation pressure concentrates around integrated maritime communication suppliers capturing long-term service contracts. Three strategic archetypes dominate: Nordic maritime system integrators, German pro-audio component fabricators, and Asian consumer electronics scale producers. Competitive moves center on protocol licensing partnerships and backward integration into transducer magnet supply chains.
Among Nordic maritime specialists, Jotron AS and Kongsberg Maritime exemplify the integrated service contracting model. Zenitel occupies a position bridging IP-based public address specialization with commercial shipping channel penetration. These three entities anchor the maritime safety segment where SOLAS compliance requirements and classification society relationships create defensive positioning.
| Leading Market Players |
|---|
| Jotron AS |
| Kongsberg Maritime |
| Zenitel |
| Mackay Communications |
| Omega Integration |
| H. Brennan |
| PacAtlantic |
| JBL |
| QSC |
| Others |
Value Network & Pricing Analysis
Shenzhen's MEMS microphone fabrication capacity anchors cost structures for consumer-grade transducers, while German precision manufacturing clusters command premium pricing for broadcast-certified components. This geographic bifurcation concentrates pricing power among REACH-compliant European suppliers serving professional audio segments.
Pricing Analysis
Certification level creates the primary spread across product tiers, with IEC 60945 maritime-grade equipment commanding substantial premiums over consumer electronics. Three-tier pricing structure across premium, standard, and economy levels segments by electromagnetic compatibility grade and protocol integration depth. Pricing pressure stems from rare earth magnet cost volatility in neodymium-dependent transducer assemblies. Healthcare facilities exhibit lowest price sensitivity due to FDA-mandated reliability requirements, while commercial shipping procurement teams drive hardest bargain through consolidated fleet contracts.
Supply Chain Analysis
Export-control restrictions on advanced signal processing semiconductors constrain flows between US design houses and Asian foundries. Component sourcing draws from China's rare earth processing dominance, Japan's precision magnet engineering, and Germany's pro-audio component fabrication. Voice coil copper and neodymium magnet assemblies represent critical input dependencies. Single-source vulnerability concentrates in Chinese neodymium separation capacity. Distribution runs through integrated maritime communication suppliers capturing long-term vessel service contracts alongside professional audio distributors serving broadcast and live events channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sound reception system market is accelerating through wireless protocol disruption and regulatory spectrum reallocation, with 5 GHz adoption and SOLAS compliance mandates compressing replacement cycles across maritime and broadcast infrastructure.
For Market Incumbents: Harden defensive positioning through captive neodymium sourcing partnerships that buffer transducer margin volatility from Chinese supply concentration. Deepen certification investment in IEC 60945 type approval capabilities to extend maritime service contract tenures against integrated communication supplier consolidation. Prioritize firmware engineering talent acquisition for Dante/AES67 protocol integration as analog vendors face technical obsolescence. For New Entrants and Emerging Players: Mid-market commercial shipping fleets in Southeast Asia represent the most penetrable entry point, with IP-based public address retrofits displacing legacy analog installations. Healthcare acoustic monitoring for FDA-regulated patient surveillance offers second white-space avenue with limited incumbent specialization. Pursue channel partnerships with German pro-audio component fabricators to bypass direct certification timeline disadvantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined signal processing specialists with algorithm licensing revenue models over hardware-dependent transducer manufacturers. Long-term viability hinges on protocol standardization influence across Dante and AES67 ecosystems. Monitor FCC spectrum reallocation proceedings and EU Radio Equipment Directive enforcement intensity as inflection indicators for wireless audio equipment valuation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Licensing Partnership | Dante/AES67 integration expertise captures recurring software revenue from hardware manufacturers. |
| Backward Integration into Magnet Supply | Neodymium sourcing control insulates transducer margins from Chinese processing volatility. |
| Maritime Service Contract Expansion | Long-term vessel operator agreements lock out competing bridge audio equipment suppliers. |
| Healthcare Certification Pathway | FDA acoustic monitoring approval opens underpenetrated hospital procurement channels. |
| 5 GHz Product Platform Launch | Spectrum-efficient wireless solutions displace UHF-constrained stage monitoring applications. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Conversations with maritime bridge system integrators, broadcast studio engineers, pro-audio procurement managers, and healthcare biomedical equipment specialists informed demand-side dynamics. Secondary sources encompass FCC spectrum allocation dockets, EU Radio Equipment Directive implementation guidance, IEC 60945 certification records, and customs trade data for transducer component flows. Bottom-up equipment shipment analysis triangulates against top-down professional audio market sizing.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering shapes the projection framework. Segmentation dimensions span product architecture, application environment, technology generation, and end-user regulatory exposure across the modeling period. CAGRs derive from equipment lifecycle analysis and certification-driven replacement elasticity. Forecast inputs incorporate SOLAS amendment implementation schedules and spectrum reallocation proceeding outcomes.
Stress conditions across rare earth supply disruption scenarios and maritime fleet contraction assumptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding wireless protocol adoption curves and electromagnetic compliance timeline adherence. Material shifts in FCC Part 15 enforcement intensity or EU REACH substance restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Embedded Computing Systems Market