
 Radio Dot System (RDS) Market | 2026-2036
Radio Dot System (RDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Dot System (RDS) Market Analytics
Carrier-grade indoor coverage specifications are redrawing competitive boundaries across the Radio Dot System landscape. Ericsson leverages its early 5G radio dot portfolio to anchor European operator relationships, while Huawei sustains manufacturing scale across Asia-Pacific deployment cycles. Nokia differentiates through Open RAN-aligned radio dot architectures that compete for greenfield enterprise contracts.
A Radio Dot System comprises compact, fiber-connected remote radio units designed for seamless indoor cellular distribution, typically operating in sub-6 GHz and mmWave bands with power outputs below 250 mW per dot. The architecture converts digital baseband signals to radio frequency for localized coverage in high-density environments such as stadiums, airports, and corporate campuses. Small Cells and Distributed Antenna Systems lead current revenue pools where venue owners and telecom operators prioritize permanent indoor installations. Network Slicing and Edge Computing integrations represent the fastest-expanding technology dimension as enterprises demand quality-of-service guarantees for private 5G deployments.
FCC Part 27 rules in the United States govern CBRS and licensed spectrum deployments that shape radio dot certification pathways for commercial buildings. ETSI and 3GPP standards in Europe enforce interoperability benchmarks that determine vendor eligibility for operator tenders across member states. China's MIIT issues network equipment licenses that condition market access on domestic testing protocols. Stakeholders must monitor spectrum reallocation timelines and private network licensing frameworks to align R&D roadmaps with shifting regulatory access requirements.
Market Dynamics
Carrier-grade indoor coverage mandates are compressing deployment timelines across commercial real estate, forcing venue owners and operators to pre-integrate radio dot infrastructure during construction rather than retrofitting post-occupancy.
Growth Catalysts
- EU Gigabit Infrastructure Act:Germany's telecom operators face binding indoor coverage requirements for new commercial buildings above 2,000 square meters, accelerating radio dot specification in architectural tenders.
- 5G private network slicing:Manufacturing campuses in China's Pearl River Delta deploy radio dot systems to guarantee latency-critical machine control, with MIIT-mandated penetration standards driving specification lock-in.
- Stadium and airport densification:Venue operators across Japan's Olympic legacy facilities replace legacy DAS with mmWave-capable radio dots to support 8K broadcast and augmented reality wayfinding.
Market Restraints
- GaN-on-SiC substrate concentration:Power amplifier supply chains cluster among three Japanese foundries, creating input cost volatility for sub-6 GHz radio dot manufacturing.
- CPRI fronthaul bandwidth costs:Dark fiber leasing expenses in urban cores consume 23-31% of total deployment budgets for multi-operator neutral host configurations.
- mmWave propagation physics:Sub-THz signal attenuation through standard building materials forces 3-4x higher dot density versus sub-6 GHz, compressing per-site economics.
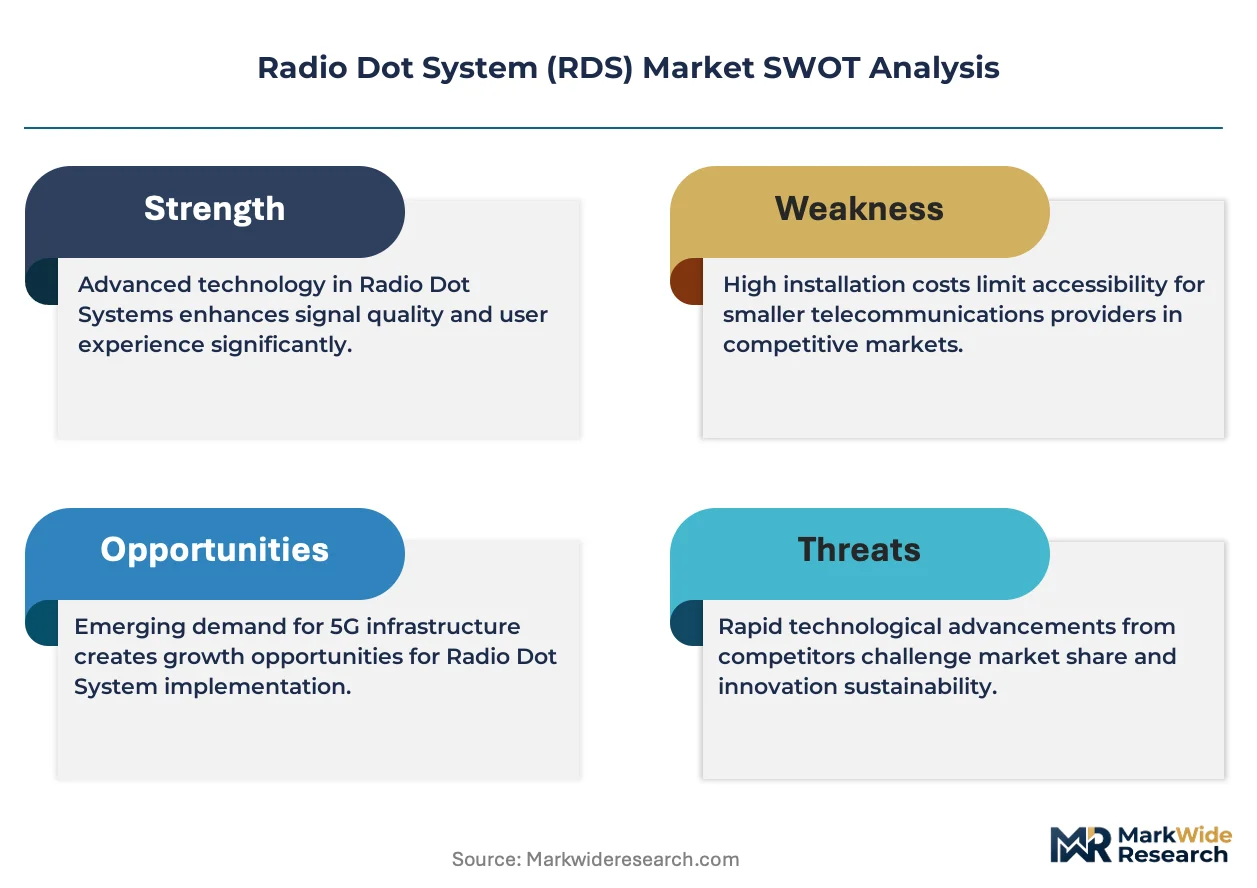
Strategic Opportunities
- India's smart city mission:Municipal corporations in Mumbai and Bangalore issue RFPs for integrated street furniture-radio dot combinations, opening greenfield deployment channels outside traditional carrier procurement.
- CBRS private network licensing:FCC Part 96 framework enables enterprise self-deployment without operator mediation, creating direct vendor-to-venue sales pipelines for neutral host specialists.
- AI-driven RF planning convergence:Machine learning propagation models reduce survey-to-deployment cycles by 40%, allowing system integrators to compress project margins and accelerate inventory turns.
Industry Challenges
- Multi-vendor interoperability certification:ETSI's O-RAN conformance testing timelines extend 14-18 months, delaying revenue recognition for Open RAN-aligned radio dot portfolios.
- Legacy coaxial infrastructure stranding:Building owners face write-down conflicts when existing DAS contracts run 7-10 years while 5G radio dot upgrades require parallel overlay investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Dot System (RDS) Market |
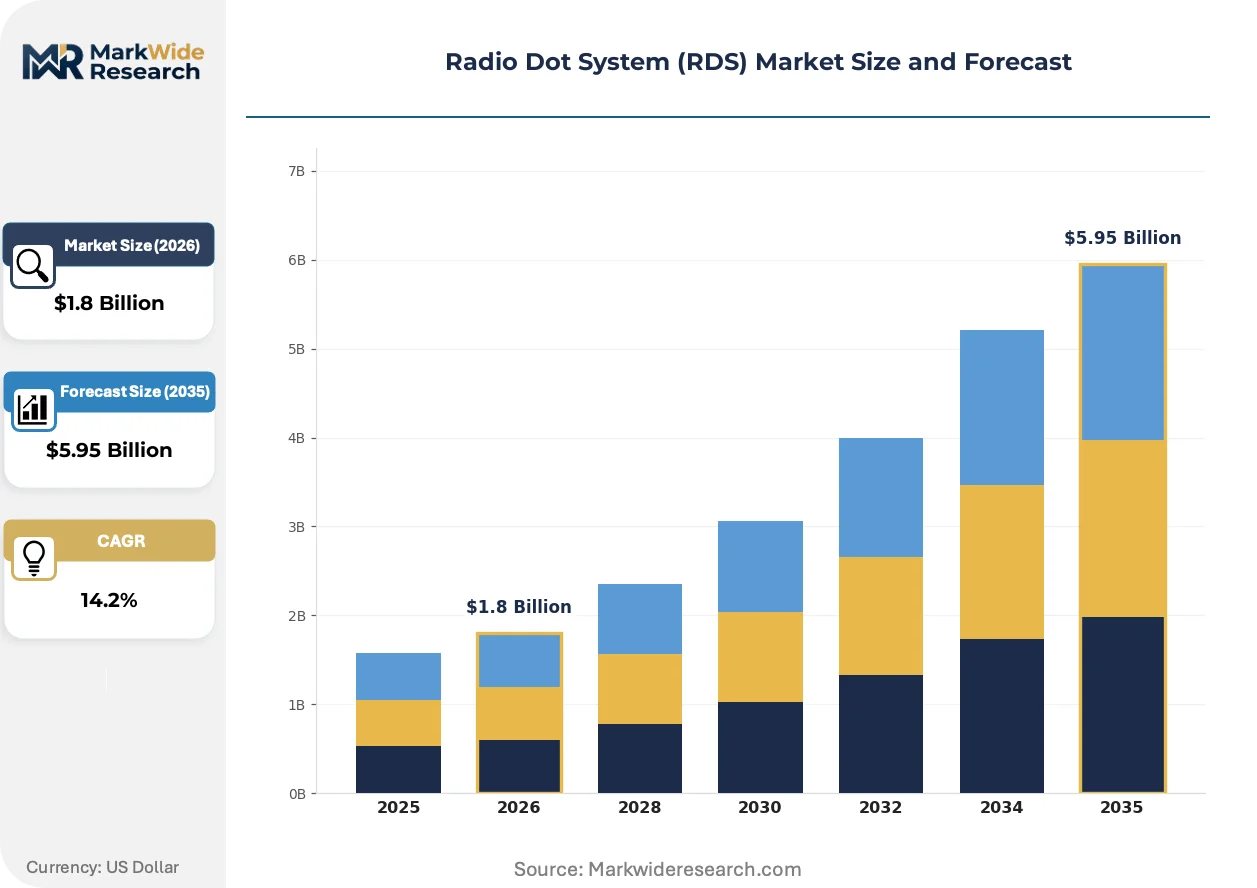
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Cells, Distributed Antenna Systems, Remote Radio Heads, Signal Boosters End User: Telecom Operators, Enterprises, Venue Owners, Service Providers Technology: Antenna Technology, Network Slicing, Edge Computing, Fiber Optics Installation Type: Indoor, Outdoor, Temporary, Permanent |
| Companies Covered | Ericsson, Huawei, Nokia, Samsung Networks, CommScope, ZTE, Verizon, Vodafone, Telefonica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Dot System (RDS) Market Evolving Landscape
Radio dot architectures are fragmenting into two distinct optimization paths: ultra-dense mmWave grids for capacity hotspots versus software-defined sub-6 GHz fabrics for coverage breadth. This technical divergence is reshaping vendor R&D allocation and procurement specifications simultaneously.
Active antenna arrays with integrated beamforming ASICs are bifurcating the radio dot market. Stadium operators in Germany adopt 256-element mmWave panels for 10 Gbps peak throughput in seating bowls. Corporate campuses in Singapore specify 64T64R sub-6 GHz units for building-wide coverage. The technology is bifurcating deployment economics: mmWave configurations demand 5-7x higher capex per square meter but enable neutral host revenue models that sub-6 GHz cannot match.
ETSI's harmonized radio equipment directive now mandates cybersecurity certification for network elements handling subscriber authentication data. Radio dot controllers must demonstrate Common Criteria EAL3+ compliance to qualify for EU operator tenders. French venue operators have delayed three major airport projects pending vendor re-certification, compressing competitive timelines for European incumbents.
Enterprise buyers increasingly specify lifecycle service contracts bundling hardware, installation, and spectrum management into single-source agreements. Japanese manufacturing conglomerates now procure radio dot infrastructure through METI-subsidized private 5G consortia rather than direct carrier relationships. This channel migration concentrates purchasing power among systems integrators with cross-vendor deployment credentials, marginalizing pure equipment vendors without managed services capabilities.
Radio Dot System (RDS) Market Segmentation
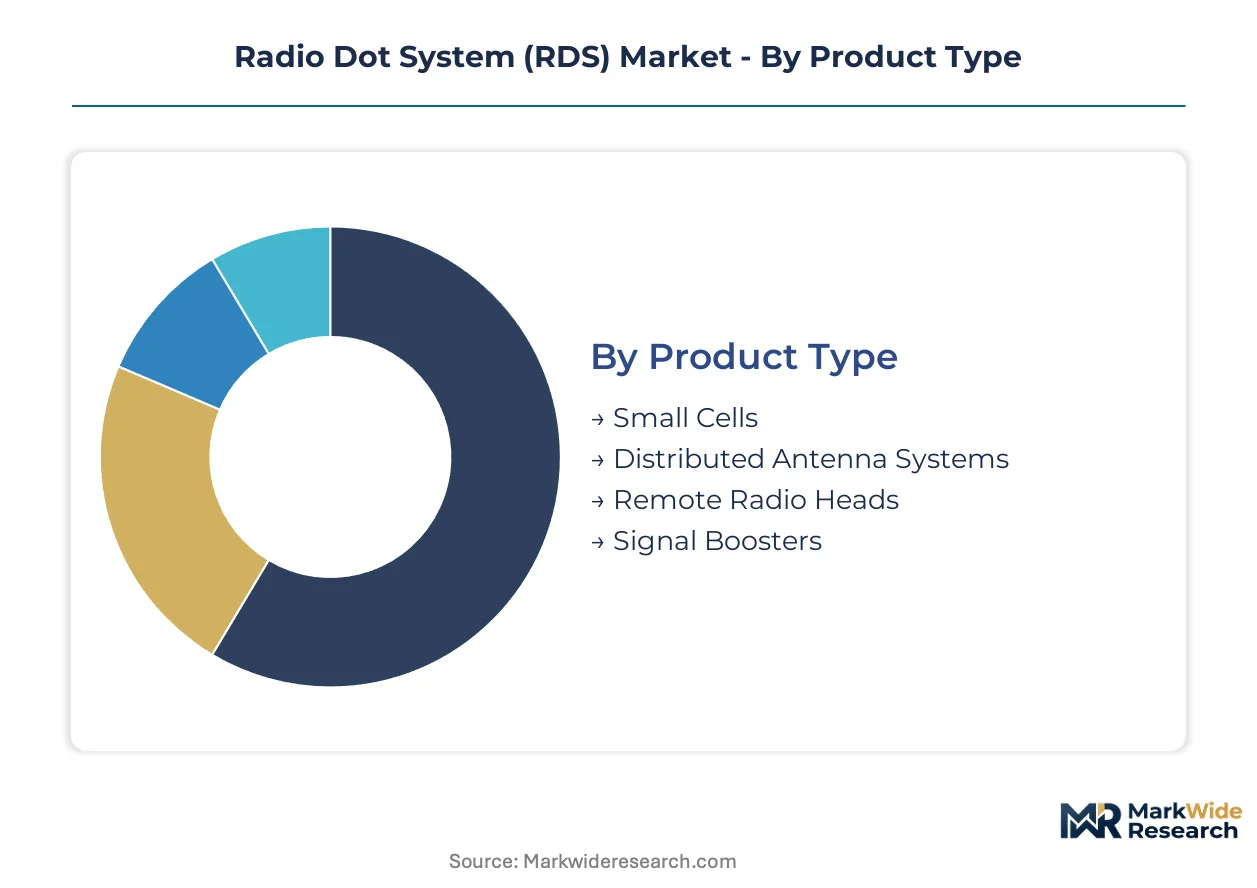
Radio Dot System procurement channels fragment sharply across product categories. Telecom operators favor carrier-grade equipment through direct vendor relationships, while enterprises and venue owners increasingly source through systems integrators bundling hardware with managed services.
Product Type:
Channel flow diverges by deployment complexity. Small Cells and Distributed Antenna Systems move through operator procurement frameworks, while Remote Radio Heads and Signal Boosters see heavier distribution via value-added resellers serving enterprise self-build projects.
- Small Cells:Compact, low-power base stations operating below 250 mW output with integrated baseband processing. Demand concentrates in China's Pearl River Delta manufacturing campuses where MIIT-mandated 5G penetration standards drive specification lock-in for private network slicing.
- Distributed Antenna Systems:Fiber-fed antenna networks distributing cellular signals across extensive indoor footprints. Venue operators across Germany's commercial real estate above 2,000 square meters deploy these under EU Gigabit Infrastructure Act mandates, accelerating architectural tender specifications.
- Remote Radio Heads:Modular RF units separating digital processing from radio transmission. Japanese Olympic legacy stadiums specify these for 8K broadcast infrastructure.
- Signal Boosters:Bi-directional amplifiers extending coverage in dead zones. US CBRS Part 96 deployments favor these for enterprise self-installation without operator mediation.
Small Cells dominate installed base. Distributed Antenna Systems are where expansion concentrates.
End User:
Customer type dictates contract structure and margin profile. Telecom operators negotiate multi-year framework agreements with volume commitments, while venue owners prefer outcome-based service contracts transferring operational risk to vendors.
- Telecom Operators:Licensed spectrum holders deploying carrier-grade infrastructure under regulatory coverage mandates. Germany's Deutsche Telekom and Vodafone specify radio dots for new commercial construction above 2,000 square meters.
- Enterprises:Private 5G license holders under FCC Part 96 or national equivalents. Manufacturing campuses in Japan's automotive belt procure through METI-subsidized consortia rather than direct carrier relationships.
- Venue Owners:Stadium, airport, and commercial complex operators monetizing neutral host infrastructure. Singapore's Changi Airport specifies 64T64R sub-6 GHz units for terminal-wide coverage.
- Service Providers:Systems integrators and managed services vendors bundling deployment with lifecycle support. India's smart city mission channels procurement through municipal corporations in Mumbai and Bangalore.
Telecom Operators anchor current revenue. Enterprises are climbing the fastest as private network licensing frameworks mature.
Technology:
R&D allocation splits between hardware-intensive antenna platforms and software-defined network functions. Antenna Technology and Fiber Optics command capital-intensive manufacturing, while Network Slicing and Edge Computing drive recurring software revenue streams.
- Antenna Technology:Active antenna arrays with beamforming ASICs enabling spatial multiplexing. Stadium operators in Germany adopt 256-element mmWave panels for 10 Gbps peak throughput in seating bowls.
- Network Slicing:Virtualized network partitioning guaranteeing quality-of-service for latency-critical applications. China's MIIT enforces stringent standards that drive specification lock-in for industrial control systems.
- Edge Computing:Distributed compute nodes co-located with radio infrastructure. Singapore corporate campuses specify these for building-wide coverage with local data processing.
- Fiber Optics:CPRI-compliant fronthaul connectivity converting digital baseband to optical transmission. Dark fiber leasing in urban cores consumes 23-31% of deployment budgets for neutral host configurations.
Antenna Technology represents the largest hardware revenue pool. Network Slicing is gaining share fastest as enterprises demand guaranteed service levels.
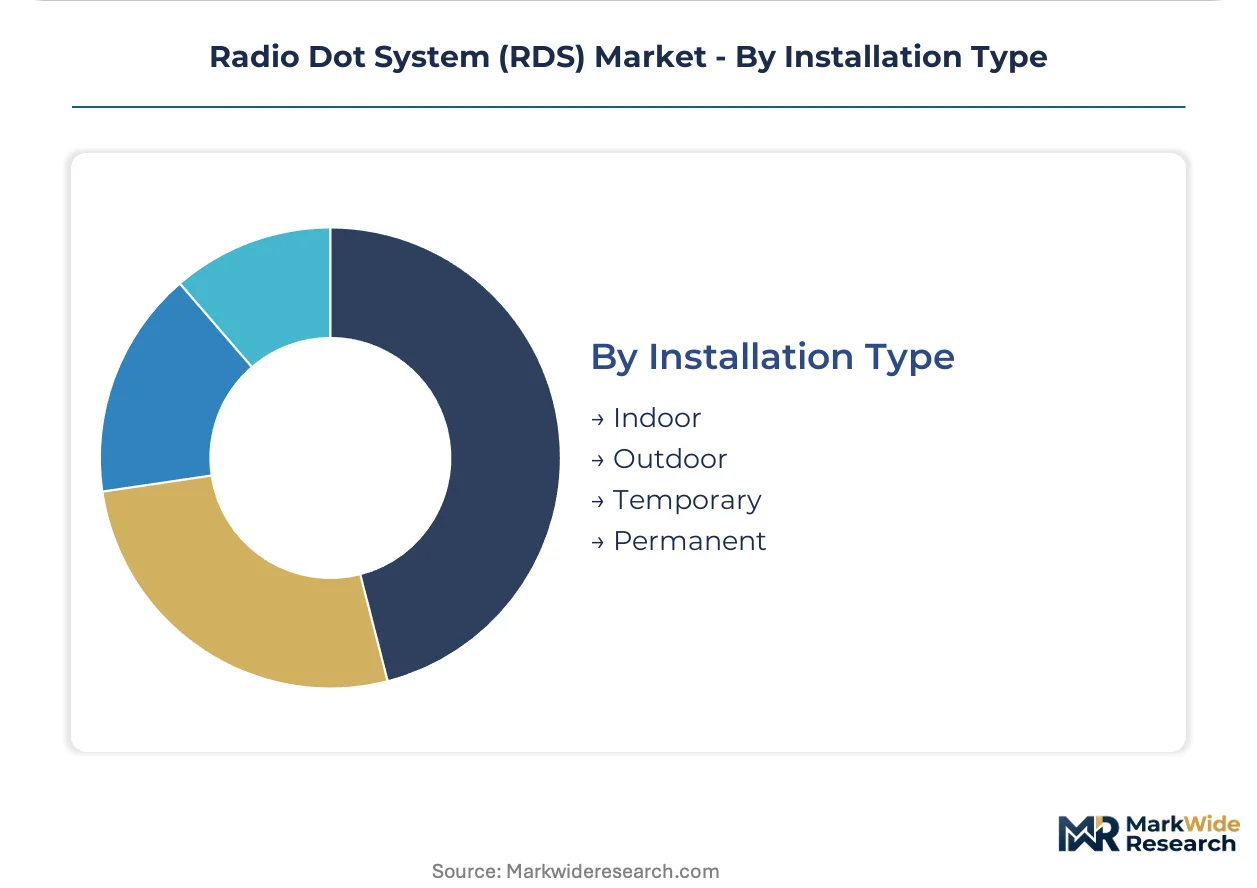
Installation Type:
Deployment timing shapes vendor working capital requirements. Permanent installations involve extended project cycles with milestone payments, while Temporary deployments demand rapid inventory turns and standardized configurations.
- Indoor:Fixed infrastructure integrated during construction or retrofit into occupied buildings. Germany's binding indoor coverage requirements accelerate radio dot specification in architectural tenders.
- Outdoor:Street furniture and facade-mounted units extending coverage to public spaces. India's smart city mission issues RFPs for integrated street furniture-radio dot combinations.
- Temporary:Rapid-deploy units for events, emergency response, or construction phases. Japanese Olympic legacy facilities leverage these for tournament overlays.
- Permanent:Capital-intensive installations with 10-15 year depreciation schedules. Building owners face write-down conflicts when existing DAS contracts run 7-10 years while 5G upgrades require parallel overlay investment.
Permanent installations dominate capital deployment. Indoor specifications are where procurement velocity is accelerating most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in Radio Dot System hardware tilt toward manufacturing economies with component fabrication depth, while deployment revenues concentrate in markets with aggressive indoor coverage mandates. Import dependency for active antenna arrays shapes procurement strategies across regions.
United States
Enterprise self-deployment under FCC Part 96 rules accelerates venue-direct procurement outside traditional carrier channels. CBRS private network licensing removes operator mediation for commercial buildings and industrial campuses. Stadium operators in Texas and California specify mmWave-capable infrastructure for 8K broadcast and augmented reality applications.
Germany
Deutsche Telekom and Vodafone face binding indoor coverage requirements for new commercial construction above 2,000 square meters under the EU Gigabit Infrastructure Act. ETSI interoperability benchmarks determine vendor eligibility for operator tenders across member states. Munich and Frankfurt airport authorities deploy fiber-fed antenna networks to meet passenger connectivity density thresholds.
China
MIIT-mandated 5G penetration standards for new construction drive specification lock-in across dense urban commercial complexes. Manufacturing campuses in the Pearl River Delta deploy radio dot systems for latency-critical machine control in private network slicing configurations. Shenzhen and Guangzhou municipal authorities enforce stringent equipment licensing through domestic testing protocols.
Japan
METI-subsidized private 5G consortia concentrate purchasing power among systems integrators serving automotive and electronics manufacturing belts. Olympic legacy stadium operators in Tokyo and Osaka replace legacy DAS with mmWave-capable radio dots for tournament overlays. NTT and KDDI procurement frameworks prioritize vendors with managed services capabilities.
India
Municipal corporations in Mumbai and Bangalore issue RFPs for integrated street furniture-radio dot combinations under the smart city mission. TRAI spectrum allocation timelines condition private network licensing frameworks for enterprise deployment. Delhi-NCR commercial real estate developers pre-integrate radio dot infrastructure during construction to avoid post-occupancy retrofit costs.
Radio Dot System (RDS) Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and service bundling dimensions. The vendor base organizes around three tiers: integrated telecom equipment conglomerates with carrier-grade certification depth, enterprise-focused neutral host specialists with managed services capabilities, and regional systems integrators capturing smart city and municipal procurement channels. Consolidation pressures favor scale players with cross-vendor deployment credentials, while Open RAN conformance requirements extend certification timelines for niche entrants. Dominant competitive moves include vertical integration into GaN-on-SiC power amplifier supply chains and strategic partnerships with commercial real estate developers for pre-construction specification lock-in.
Within the integrated equipment tier, Ericsson and Huawei occupy positions anchored by early 5G radio dot portfolio development and manufacturing scale across respective home regions. Nokia exemplifies the Open RAN-aligned archetype competing for greenfield enterprise contracts through architecture differentiation. These three represent the primary competitive anchors shaping procurement specifications and certification pathways across operator and enterprise channels.
| Leading Market Players |
|---|
| Ericsson |
| Huawei |
| Nokia |
| Samsung Networks |
| CommScope |
| ZTE |
| Verizon |
| Vodafone |
| Telefonica |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Japanese GaN-on-SiC foundries sets price floors for sub-6 GHz radio dot power amplifiers, concentrating supply leverage among three substrate suppliers while compressing margins for downstream equipment vendors. Telecom operators in Germany and China exploit this concentration through multi-year framework agreements that lock in volume commitments against volatile input costs.
Pricing Analysis
Telecom operators anchor project-based pricing structures for carrier-grade deployments, with three-tier pricing stratification across premium Open RAN-certified, standard integrated, and economy non-managed service tiers. Price differentiation hinges on ETSI conformance certification timelines and after-sales service bundling, with premium tiers commanding substantial markups for EAL3+ cybersecurity compliance. Cost compression in economy tiers is intensifying because venue owners self-procure through CBRS Part 96 licensing without operator mediation. Enterprise buyers exhibit highest price sensitivity, while neutral host specialists prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of GaN-on-SiC substrates prevails over just-in-time approaches as foundry capacity constraints extend lead times for power amplifier modules. Manufacturing concentration centers on Japan for compound semiconductors, China for antenna assembly, and Germany for precision fiber optic components. Raw material dependencies include rare earth elements for RF ceramics, high-purity silicon carbide wafers, and specialty optical fiber. Single-source vulnerability in Japanese substrate supply creates structural risk for multi-operator neutral host configurations. Distribution runs through systems integrators with cross-vendor deployment credentials rather than direct vendor-to-venue channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radio dot architectures are approaching a platform-economics inflection as ETSI O-RAN conformance testing extends vendor certification timelines and concentrates purchasing power among integrators with interoperability credentials. Open RAN alignment is displacing proprietary stack advantages across greenfield enterprise procurement.
For Market Incumbents: Compound carrier-grade certification depth with backward integration into GaN-on-SiC supply chains to defend against neutral host specialists capturing direct enterprise relationships. Extend architectural specification lock-in through pre-construction partnerships with commercial real estate developers in Germany and China. Prioritize managed services capability investments as Japanese METI-subsidized consortia shift procurement toward lifecycle contracts. For New Entrants and Emerging Players: Lead with AI-driven RF planning convergence to compress survey-to-deployment cycles and undercut incumbent project margins. Target India's smart city mission municipal RFPs for integrated street furniture-radio dot combinations where carrier relationships carry less weight. Pursue FCC Part 96 direct enterprise licensing frameworks as a channel bypassing established operator procurement hierarchies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors systems integrators with cross-vendor deployment credentials over pure equipment vendors lacking managed services capabilities. Long-term viability hinges on capturing recurring software revenue from network slicing and edge computing integrations rather than hardware replacement cycles. Watch ETSI O-RAN certification backlog clearance as the inflection signal for Open RAN-aligned portfolio competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Supply Chain Integration | Captive substrate supply insulates margins against Japanese foundry concentration. |
| Open RAN Certification Investment | EAL3+ cybersecurity compliance unlocks EU operator tender eligibility under ETSI mandates. |
| Pre-Construction Developer Partnerships | Architectural specification lock-in secures radio dot placement before DAS retrofit conflicts arise. |
| Managed Services Capability Buildout | Lifecycle contract bundling aligns with Japanese METI consortia procurement channel migration. |
| AI RF Planning Platform Development | Machine learning propagation models compress project timelines and accelerate inventory turns. |
Research Methodology
A spread of perspectives from telecom network planning executives, commercial real estate developers, systems integration specialists, and venue operator procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against ETSI certification databases, FCC Part 96 licensing records, MIIT equipment approval registries, and municipal smart city RFP documentation. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending forecasts across the analysis window.
Segmentation dimensions modeled include product architecture type, end-user procurement channel, technology integration depth, and installation timing relative to construction phase. CAGRs were derived from installation base growth trajectories and average revenue per deployment trends across the projection horizon. Industry-specific forecast inputs incorporated spectrum reallocation timelines and private network licensing framework maturation.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of indoor coverage mandates would require recalibration. Forecasts reflect assumptions regarding GaN-on-SiC substrate supply continuity and Open RAN conformance testing standardization. Revision becomes warranted when ETSI certification timelines or CBRS licensing uptake crosses thresholds that alter competitive channel dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Sound Reception System Market