
 Global Electro Hydraulic Servo Valve Market | 2026-2036
Global Electro Hydraulic Servo Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electro Hydraulic Servo Valve Market Foresight
Military-grade specification tiers is rotating toward commercial aerospace and renewable energy applications, broadening addressable volume beyond traditional defense procurement. Moog Inc. leverages its heritage in flight control actuation to anchor premium positioning across FAA-certified platforms. Bosch Rexroth AG sustains manufacturing scale through captive foundry capacity and integrated electronics assembly. Parker Hannifin Corporation competes on global channel density, with distribution hubs spanning fifteen countries.
An electro hydraulic servo valve is a precision fluid control device that modulates hydraulic flow through electromechanical actuation of a pilot stage, typically achieving frequency response above 100 Hz with hysteresis below 0.5%. It converts low-power electrical signals into proportional hydraulic output for position, velocity, or force control in closed-loop automation systems. Jet pipe valve architectures retain dominance in aerospace applications where contamination tolerance and fail-safe positioning justify premium cost structures, while spool valve designs capture volume in construction machinery through simpler maintenance profiles. Digital valve technology is displacing analog architectures in energy generation installations, enabling real-time diagnostics and predictive maintenance protocols that reduce unplanned downtime.
FAA airworthiness directives and EASA certification requirements shape product development cycles for aerospace-qualified valves, mandating traceable material lots and environmental stress screening. EPA spill prevention regulations and ISO 4406 cleanliness standards constrain hydraulic system designs, filtering valve specifications toward higher filtration ratings and sealed actuator configurations. Stakeholders must monitor evolving EU Green Deal industrial emissions benchmarks and China's GB standard harmonization initiatives, as these frameworks will determine market access conditions and qualification burden for cross-border suppliers.
Market Dynamics
Digital valve architectures are bifurcating the installed base, forcing legacy analog suppliers to accelerate electronics integration or retreat to aftermarket service revenue pools.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant compatibility mandates are accelerating material upgrades in sealing technologies across German and French industrial automation clusters.
- Next-generation flight control platforms:Aerospace OEM procurement of precision hydraulic actuation systems is expanding specification intensity for FAA-certified servo valves.
- Digital predictive maintenance:Real-time diagnostics capability is displacing scheduled maintenance protocols in energy generation installations.
Market Restraints
- Specialized alloy input costs:Maraging steel and superalloy price volatility constrains margin flexibility for high-performance valve manufacturers.
- Contamination sensitivity:Jet pipe architectures require ISO 4406 Class 14/12/9 filtration systems that inflate total cost of ownership in construction machinery.
- Electromechanical substitution:All-electric actuation systems are capturing position control applications below 50 kW hydraulic output.
Strategic Opportunities
- China GB standard harmonization:Cross-border qualification alignment is opening procurement access to state-owned energy and steel producers.
- Offshore wind turbine pitch control:Extreme environment servo valve specifications represent uncontracted demand in North Sea and East Asian installations.
- AI-integrated valve health monitoring:Machine learning convergence with embedded pressure sensors enables outcome-based service contracts.
Industry Challenges
- Systems integration engineering scarcity:Closed-loop hydraulic-electronic control expertise concentrates at a handful of specialized engineering consultancies.
- EASA certification timeline compression:Traceable material lot documentation and environmental stress screening extend new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electro Hydraulic Servo Valve Market |
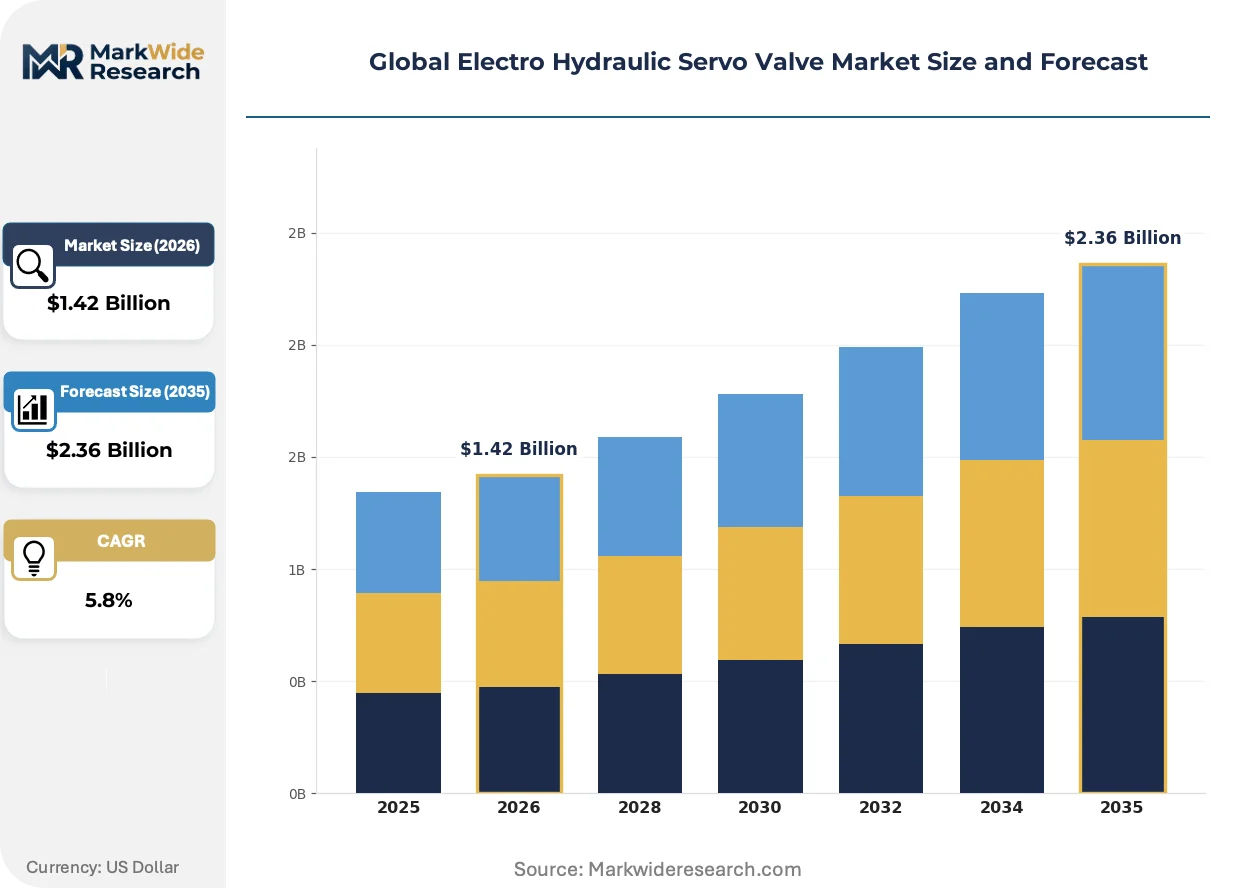
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proportional Valve, Flapper Nozzle Valve, Jet Pipe Valve, Spool Valve, Rotary Valve Technology: Closed Loop, Open Loop, Digital Valve, Analog Valve, Electro-Mechanical Valve Application: Aerospace, Defense Systems, Marine Equipment, Construction Machinery, Energy Generation End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Equipment Manufacturers, Green Energy Firms |
| Companies Covered | Moog Inc., Bosch Rexroth AG, Parker Hannifin Corporation, Eaton Corporation plc, HAWE Hydraulik SE, YUKEN KOGYO Co. Ltd., Honeywell International Inc., Woodward Inc., Duplomatic Motion Solutions S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electro Hydraulic Servo Valve Market Shifts & Advancements
Electromechanical integration depth is reshaping competitive differentiation, separating suppliers with captive electronics assembly from those dependent on outsourced control modules.
Digital valve technology is bifurcating the product architecture landscape. These devices integrate embedded processors and fieldbus communication directly into the pilot stage, enabling closed-loop self-diagnostics. Wind turbine OEMs and semiconductor fabrication facilities are specifying digital interfaces at replacement cycle points. The technology is bifurcating supplier tiers into integrated platform vendors and component assemblers without firmware capabilities.
EPA spill prevention regulations and ISO 4406 cleanliness standards are tightening hydraulic system design constraints. These frameworks mandate sealed actuator configurations and elevated filtration ratings that disqualify legacy open-reservoir architectures. Aerospace-qualified valve manufacturers face the steepest compliance burden, as traceability requirements extend through three tiers of material sourcing.
Specification authority is migrating from distributor sales engineers to end-user reliability teams. Procurement teams in German automotive press shops and Japanese machine tool builders now require MTBF documentation and predictive maintenance API access before contract award. This shift is most visible in Stuttgart and Nagoya industrial clusters, where buyer technical staff conduct direct supplier capability audits.
Global Electro Hydraulic Servo Valve Market Segmentation
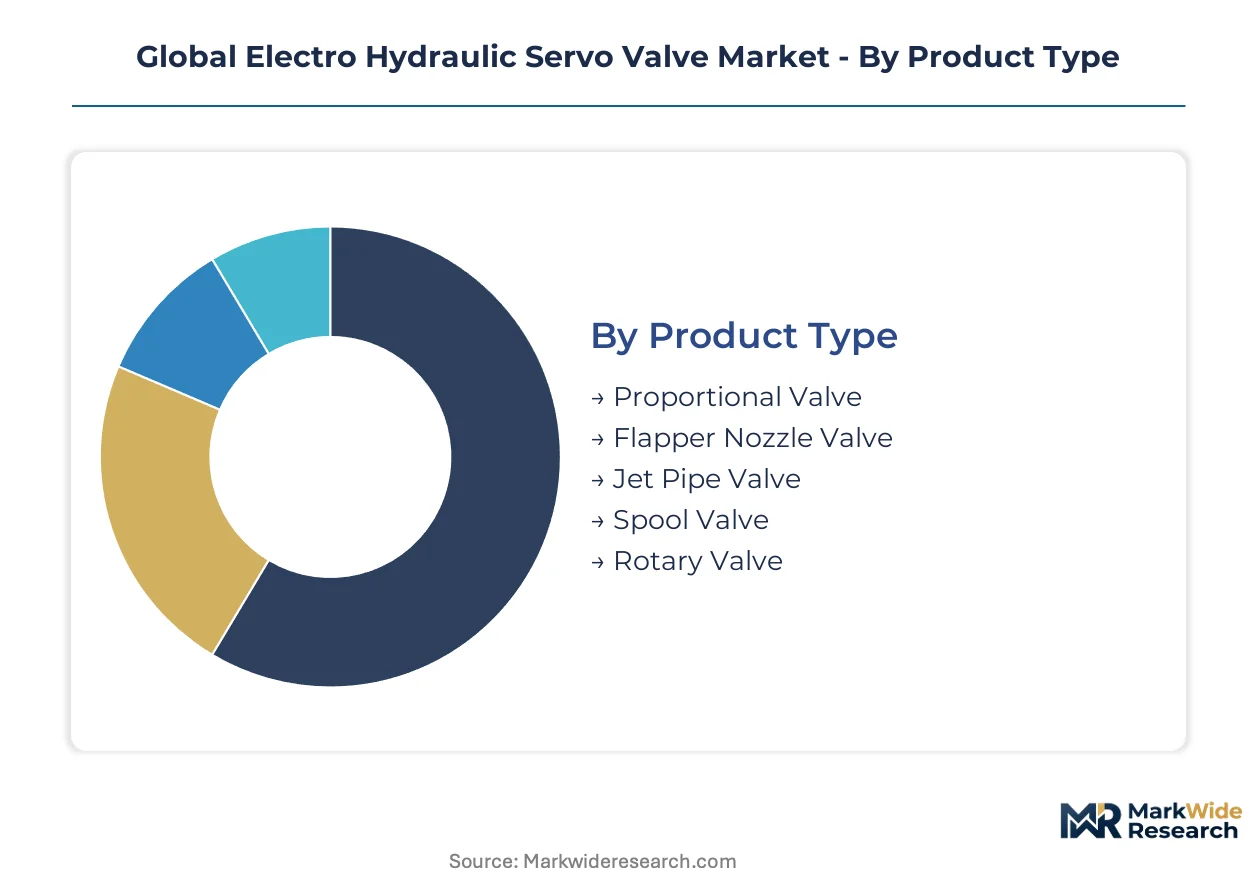
Servo valve procurement channels diverge sharply by specification intensity. FAA-certified aerospace applications route through specialized distribution, while construction machinery flows through broad industrial channels with lower technical pre-qualification.
Product Type:
Channel access depends on contamination tolerance and maintenance profile. Jet pipe architectures command premium distribution partnerships, while spool valves penetrate volume markets through general industrial supply.
- Jet Pipe Valves:Pilot-stage fluidic amplification delivers contamination tolerance above 200 ppm particulate loading. Demand clusters in aerospace flight control systems where fail-safe positioning justifies premium procurement through specialized channels. FAA certification requirements restrict supply base to heritage manufacturers with traceable material documentation.
- Spool Valves:Direct-acting spool configurations achieve simpler field serviceability with standard tooling. Construction machinery OEMs in Germany and Japan specify these through broad industrial distribution where price transparency dominates supplier selection. Lower filtration requirements reduce total cost of ownership in mobile equipment.
- Proportional Valves:Continuous flow modulation without discrete switching supports plastic injection molding and metal forming presses.
- Flapper Nozzle Valves:Torque motor-driven flapper deflection enables sub-millisecond response in semiconductor lithography positioning stages.
- Rotary Valve:Cylindrical spool rotation suits high-flow marine steering gear with redundant channel architectures.
Jet pipe valves dominate installed base in aerospace. Spool valves are where expansion concentrates in renewable energy and construction equipment.
Technology:
Cost tier separation between legacy analog architectures and integrated digital platforms reshapes supplier margins. Electronics integration depth determines whether vendors capture specification authority or retreat to component supply.
- Digital Valve:Embedded processors with fieldbus communication enable real-time diagnostics and predictive maintenance protocols. Wind turbine OEMs in Denmark and offshore platform operators in Norway now mandate digital interfaces at replacement cycles, displacing analog architectures in energy generation. The technology tier separates integrated platform vendors from firmware-dependent assemblers.
- Closed Loop:Feedback-controlled positioning achieves hysteresis below 0.5% for precision motion in aircraft flight surfaces. Japanese machine tool builders and German automotive press shops require MTBF documentation above 50,000 hours, routing procurement through direct supplier audits rather than distributor channels.
- Analog Valve:Voltage-current pilot stage actuation persists in legacy military platforms with long service life requirements.
- Open Loop:Uncompensated flow control satisfies cost-sensitive agricultural machinery where positioning accuracy tolerance exceeds 2%.
- Electro-Mechanical Valve:Direct electric actuation eliminates hydraulic fluid in sub-50 kW applications facing EPA spill prevention scrutiny.
Closed loop architectures anchor specification intensity in aerospace. Digital valve platforms are climbing the fastest in energy and industrial automation replacement cycles.
Application:
Customer type concentration varies by operational environment severity. Marine and aerospace applications route through reliability engineering teams, while construction machinery flows through fleet procurement.
- Aerospace:FAA and EASA certification mandates traceable material lots through three tiers of sourcing. Next-generation flight control platforms in the US and France are expanding specification intensity for precision hydraulic actuation. Airworthiness directives extend product development cycles and restrict supply base to qualified heritage manufacturers.
- Energy Generation:Offshore wind turbine pitch control specifications represent uncontracted demand in North Sea and East Asian installations. Extreme environment sealing requirements exceed standard industrial ratings, creating specification windows for specialized suppliers with superalloy expertise.
- Defense Systems:Military-grade specification tiers are rotating toward dual-use commercial platforms, broadening addressable volume.
- Construction Machinery:ISO 4406 Class 14/12/9 filtration requirements inflate total cost of ownership, favoring simpler spool architectures.
- Marine Equipment:Corrosion-resistant coatings and redundant channel designs satisfy classification society rules for commercial shipping.
Aerospace dominates specification intensity and margin capture. Energy generation is where technology substitution is accelerating most quickly.
End User:
Volume concentration versus margin capture splits across the procurement hierarchy. OEMs and Tier-1 suppliers control specification authority, while equipment manufacturers optimize installed base service costs.
- OEMs:Boeing, Airbus, and Lockheed Martin anchor demand for FAA-certified platforms with captive reliability engineering teams conducting direct supplier capability audits. These buyers mandate predictive maintenance API access and embedded sensor integration before contract award, consolidating specification authority at the platform integrator level.
- Green Energy Firms:Ørsted and Vestas specify extreme environment servo valves for offshore wind installations with 25-year service life requirements. Procurement teams prioritize outcome-based service contracts enabled by AI-integrated health monitoring, shifting supplier relationships from component supply to performance guarantees.
- Tier-1 Suppliers:Parker Hannifin and Bosch Rexroth channel manufacturing scale through integrated electronics assembly and captive foundry capacity.
- Equipment Manufacturers:Construction machinery builders optimize fleet standardization across multiple equipment categories.
- Vehicle Assemblers:Automotive press shop automation drives specification intensity in Stuttgart and Nagoya industrial clusters.
OEMs dominate specification authority and margin capture. Green energy firms are gaining the fastest in procurement volume as renewable energy buildout accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision servo valve assemblies to aerospace OEMs in France and the United States, establishing the Rhine-Main corridor as the dominant trade-flow corridor for high-specification hydraulic components.
Germany
Stuttgart and Munich industrial automation clusters drive specification intensity for high-response servo valves in automotive press shops. The EU F-Gas Regulation mandates refrigerant-compatible sealing material upgrades across Baden-Württemberg manufacturing facilities. Bosch Rexroth AG anchors captive foundry capacity and integrated electronics assembly in this region.
United States
Boeing and Lockheed Martin expand procurement of FAA-certified flight control actuation systems for next-generation platforms. FAA airworthiness directives mandate traceable material lots through three tiers of sourcing for aerospace-qualified valves. Wichita, Kansas and Seattle, Washington concentrate precision machining capacity for defense and commercial aviation supply chains.
China
State-owned energy and steel producers accelerate GB standard harmonization to align with international qualification benchmarks. The Ministry of Ecology and Environment enforces dual carbon goals that constrain hydraulic system emissions in heavy industry. Yangtze River Delta manufacturing bases in Shanghai and Jiangsu province concentrate domestic valve assembly capacity for infrastructure equipment.
Japan
Machine tool builders in Nagoya and Tokyo require MTBF documentation above 50,000 hours for closed-loop positioning systems. METI industrial standards shape procurement specifications for semiconductor lithography positioning stages. Japanese automotive press automation drives direct supplier capability audits bypassing traditional distributor channels.
Norway
Equinor and offshore platform operators mandate digital valve interfaces at replacement cycles for subsea hydraulic systems. The Norwegian Petroleum Safety Authority enforces extreme environment sealing requirements exceeding standard industrial ratings. Stavanger and Bergen engineering consultancies concentrate closed-loop hydraulic-electronic control expertise for North Sea energy installations.
Global Electro Hydraulic Servo Valve Market Competitive Landscape
Listed leaders compete with private specialists across certification authority and manufacturing scale. The vendor base concentrates around heritage aerospace suppliers with FAA traceability documentation and diversified industrial conglomerates with captive electronics integration. Three archetypes dominate: integrated platform vendors with firmware capabilities, component assemblers dependent on outsourced control modules, and specialized consultancies with systems integration expertise. Competitive moves center on electronics integration depth and geographic expansion through distribution hub density.
Within the integrated platform tier, Moog Inc. and Bosch Rexroth AG exemplify suppliers with heritage positioning in flight control actuation and captive manufacturing scale respectively. Parker Hannifin Corporation occupies a position among channel-dense conglomerates with distribution infrastructure spanning multiple countries. These three entities represent the competitive anchor points separating specification authority from component supply relationships.
| Leading Market Players |
|---|
| Moog Inc. |
| Bosch Rexroth AG |
| Parker Hannifin Corporation |
| Eaton Corporation plc |
| HAWE Hydraulik SE |
| YUKEN KOGYO Co. Ltd. |
| Honeywell International Inc. |
| Woodward Inc. |
| Duplomatic Motion Solutions S.p.A. |
| Others |
Supply & Pricing Matrix
Captive foundry utilization rates above 85% in Baden-Württemberg and Bavaria anchor price floors for aerospace-qualified servo valves, compressing margin flexibility for second-tier assemblers without backward integration into superalloy machining capacity. Scale concentration among German and Japanese heritage manufacturers amplifies specification authority at the OEM level, forcing price discipline through direct supplier audits rather than distributor-negotiated contracts.
Pricing Analysis
Three-generation pricing spreads separate embedded-processor digital platforms from legacy analog architectures and obsolescent open-loop designs. Pricing stratifies across FAA-certified aerospace tiers, ISO-compliant industrial grades, and uncertified mobile equipment levels, with certification documentation and traceable material lots commanding 40-60% premiums over functional equivalents. Cost compression in construction machinery spool valves is intensifying because Chinese assemblers are capturing volume through simplified maintenance profiles. Green energy firms and semiconductor fabricators exhibit lowest price sensitivity, prioritizing MTBF documentation and predictive maintenance API access over unit cost.
Supply Chain Analysis
Maraging steel and superalloy feedstock concentration in Germany, Japan, and the United States creates single-source vulnerability for high-performance torque motor laminations and jet pipe pilot stages. Valve assembly draws from precision machining clusters in Stuttgart, Nagoya, and Wichita, with electronics integration increasingly tethered to Taiwanese semiconductor foundries for embedded processor supply. Distribution runs through specialized aerospace channels for FAA-certified platforms and broad industrial supply for construction machinery, with direct OEM procurement gaining share in renewable energy and automotive press automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Boeing, Airbus, and offshore wind developers like Ørsted and Vestas has shifted specification authority from distributor sales engineers to captive reliability teams, compressing supplier margins through outcome-based contracting and predictive maintenance guarantees.
For Market Incumbents: Shield heritage positioning in FAA-certified flight control by accelerating firmware capabilities and embedded sensor integration ahead of electromechanical substitution below 50 kW. Deepen backward integration into superalloy machining capacity to defend margin structure against Chinese volume assemblers. Prioritize certification investment in EASA and China GB standard harmonization to maintain cross-border market access as qualification burdens tighten. For New Entrants and Emerging Players: Aftermarket service gaps in legacy analog valve installed bases present white-space entry points for predictive maintenance platform providers without captive manufacturing. Target offshore wind turbine pitch control specifications in North Sea and East Asian installations, where extreme environment sealing requirements exceed standard industrial ratings and heritage suppliers remain under-contracted. Pursue direct engagement with green energy reliability teams through outcome-based performance guarantees rather than component supply relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform vendors with captive electronics assembly and firmware capabilities over component assemblers dependent on outsourced control modules. Long-term viability across the projection horizon rests on AI-integrated valve health monitoring convergence and electromechanical-hybrid architectures. Monitor China GB standard harmonization progress as the inflection signal for state-owned energy producer procurement access and cross-border qualification burden intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Embedded processors with fieldbus communication displace analog architectures in Danish and Norwegian energy installations. |
| Backward Integration into Superalloy Supply | Captive maraging steel machining capacity insulates margin structure from raw material volatility in German aerospace clusters. |
| Predictive Maintenance Service Contracts | Machine learning convergence with pressure sensors enables outcome-based relationships with Ørsted and Vestas procurement teams. |
| China GB Standard Harmonization | Cross-border qualification alignment opens procurement access to state-owned steel and energy producers in Yangtze River Delta. |
| EASA Certification Investment | Traceable material lot documentation and environmental stress screening extend product development cycles but secure platform integrator relationships. |
Research Methodology
Operator-level perspectives from aerospace OEM procurement directors, wind turbine reliability engineers, hydraulic systems integrators, and Tier-1 supplier manufacturing heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through FAA airworthiness directive filings, EASA certification databases, SEC 10-K supply chain disclosures, and German mechanical engineering association (VDMA) production statistics. Bottom-up segment sizing triangulated against top-down macroeconomic indicators and industrial automation capex tracking.
Sensitivity analysis across multiple scenario assumptions informed the analytical framework, with volume and value outputs reflecting segmentation by valve architecture, electronics integration depth, certification tier, and end-use application intensity. CAGRs were derived through regression analysis of historical procurement patterns and forward projection of replacement cycle timing, regulatory compliance burden trajectories, and technology substitution rates in energy generation installations.
Forecasts assume regulatory continuity in FAA, EASA, and EU F-Gas regimes; material policy shifts in refrigerant compatibility mandates or China GB standard harmonization timelines would require re-modeling. Practitioners should keep alternative scenarios live as electromechanical substitution thresholds and offshore wind installation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Laser Processing Market