
 Global Bioelectronics Market | 2026-2036
Global Bioelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioelectronics Market Foresight
The EU Green Deal is consolidating demand for biocompatible materials and closed-loop manufacturing in European medical device supply chains. Medtronic plc leverages its vertically integrated neuromodulation platform to sustain R&D intensity across implantable bioelectronic portfolios. Abbott Laboratories anchors glucose monitoring ecosystems with electrochemical sensor architectures that dominate ambulatory care settings.
Bioelectronics encompasses the integration of biological systems with electronic devices at the molecular, cellular, or tissue level, typically operating through biocompatible electrodes, conductive polymers, or semiconductor interfaces that transduce biochemical signals into measurable electrical outputs for diagnostic or therapeutic intervention. Implantable devices command the deepest margin pools due to regulatory barriers and surgical workflow integration, while biosensors compete on cost curve steepness in point-of-care settings. Electrochemical technology leads volume deployment across glucose and cardiac monitoring applications, whereas semiconductor-based platforms are concentrating investment in next-generation neural interfaces.
FDA breakthrough device designation and EU MDR compliance timelines shape product development roadmaps and market access velocity for bioelectronics manufacturers seeking dual-territory approval. EMA's evolving stance on active implantable software updates is forcing firms to restructure post-market surveillance obligations across European member states. Stakeholders must monitor reimbursement coding decisions by CMS and Germany's Federal Joint Committee as these determine commercial scalability for novel bioelectronic therapeutic categories.
Market Dynamics
FDA breakthrough device designation is compressing commercialization timelines for neuromodulation systems while EU MDR compliance costs force portfolio rationalization across European active implantable manufacturers.
Growth Catalysts
- Medicare reimbursement maturation:CMS coding decisions for bioelectronic therapeutics are unlocking hospital procurement budgets across United States ambulatory surgical centers.
- Closed-loop manufacturing mandates:EU Green Deal biocompatibility requirements are consolidating demand for sustainable medical device supply chains in Germany and France.
- Glucose monitoring ecosystem expansion:Electrochemical sensor architectures are penetrating home-based chronic disease management workflows beyond traditional clinical settings.
Market Restraints
- Precious metal input volatility:Platinum and iridium price swings destabilize cost structures for cardiac implant electrode production.
- Single-source semiconductor dependence:Advanced neural interface chip fabrication concentrates in Taiwan foundries, exposing supply continuity risk.
- EMA software update friction:Evolving post-market surveillance obligations for active implantable devices extend regulatory validation cycles across European member states.
Strategic Opportunities
- Underpenetrated Indian cardiac intervention:CDSCO streamlined approval pathways for implantable devices are opening private hospital procurement in Mumbai and Delhi clusters.
- Peripheral nerve stimulation expansion:Chronic pain management applications outside spinal cord modulation represent unaddressed therapeutic white space.
- AI-enabled diagnostic convergence:Machine learning integration with electrochemical biosensors is creating predictive monitoring platforms for early disease detection.
Industry Challenges
- Biomaterials engineering talent scarcity:Specialized expertise in conductive polymer-tissue interface design commands premium compensation and extends R&D team assembly timelines.
- ISO 14155 clinical trial complexity:Multi-site investigational device exemption studies for implantable neuromodulation require coordinated regulatory submissions across FDA and notified body jurisdictions.
- Legacy hospital IT integration:Bioelectronic data streams face interoperability friction with existing electronic health record architectures in United States health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioelectronics Market |
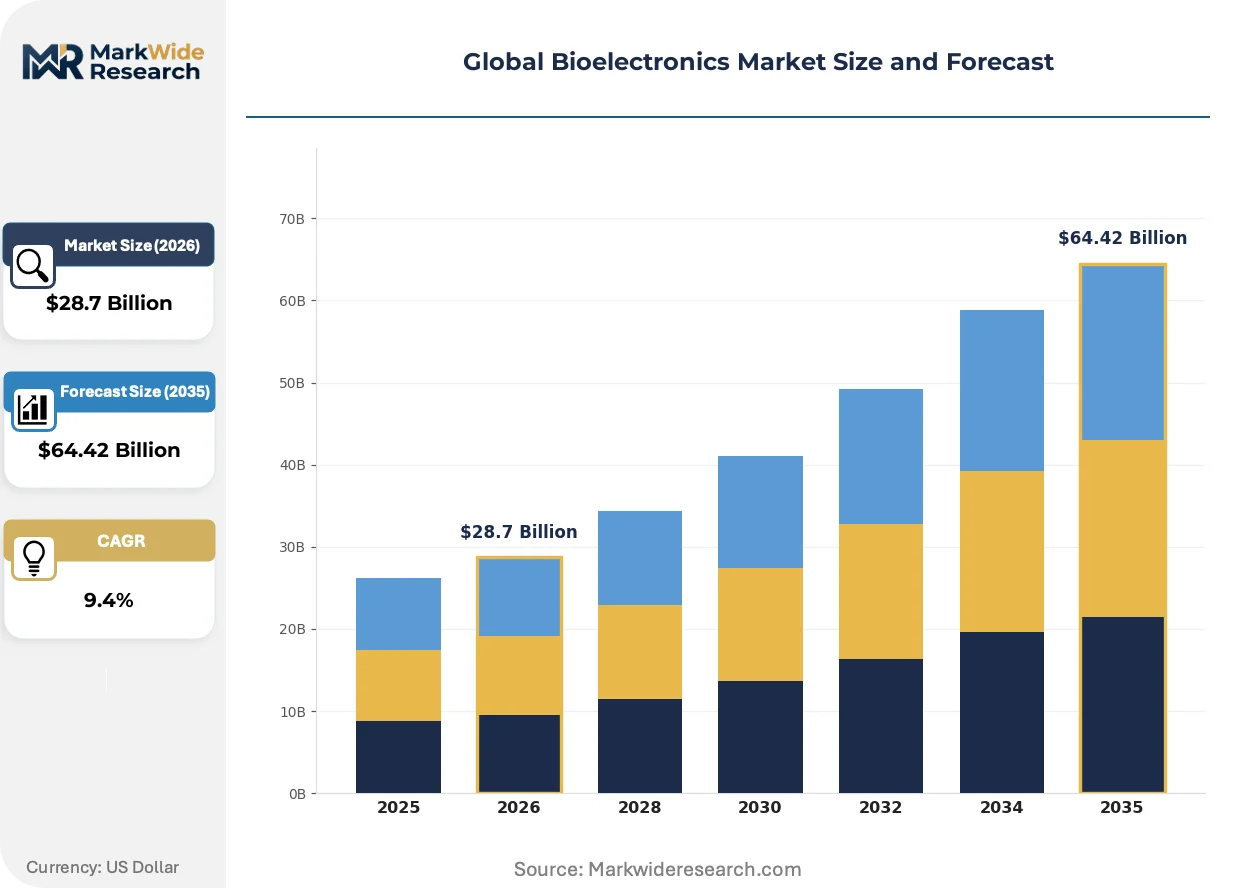
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Diagnostic Instruments, Therapeutic Equipment, Biosensors Technology: Electrochemical, Optical, Piezoelectric, Magnetic, Semiconductor Application: Neurological Monitoring, Glucose Monitoring, Cardiac Monitoring, Drug Delivery Systems, Tissue Engineering End User: Medical Research Institutes, Specialty Clinics, Biotechnology Firms, Rehabilitation Centers, Academic Laboratories |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Koninklijke Philips N.V., Siemens Healthineers AG, F. Hoffmann-La Roche Ltd., Bayer AG, Nova Biomedical Corporation, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioelectronics Market Shifts & Advancements
Semiconductor-based neural interfaces are overtaking electrochemical platforms in next-generation therapeutic applications, while regulatory sandboxes in major jurisdictions accelerate validation pathways for software-enabled active implants.
Organic electrochemical transistors are overtaking traditional metal-electrode interfaces in chronic neural recording applications. Academic medical centers in Boston and Zurich are piloting these polymer-semiconductor hybrids for multi-year implant stability. The technology is overtaking conventional materials by eliminating foreign-body response degradation that limits long-term signal fidelity.
EU MDR Article 120 transition deadlines are forcing manufacturers to restructure technical documentation and clinical evidence portfolios for legacy implantable devices. Notified body capacity constraints in Germany and Ireland are extending conformity assessment queues. Cardiac rhythm management manufacturers are responding by prioritizing high-margin neuromodulation submissions over defibrillator line extensions.
Hospital procurement committees are consolidating vendor relationships for implantable bioelectronics around full-lifecycle service agreements. Device manufacturers are displacing traditional distributor networks with direct field clinical specialist teams in United States integrated delivery networks. This concentration is most visible in Medicare Advantage–dominated markets where total cost-of-ownership contracting determines supplier selection.
Global Bioelectronics Market Segmentation
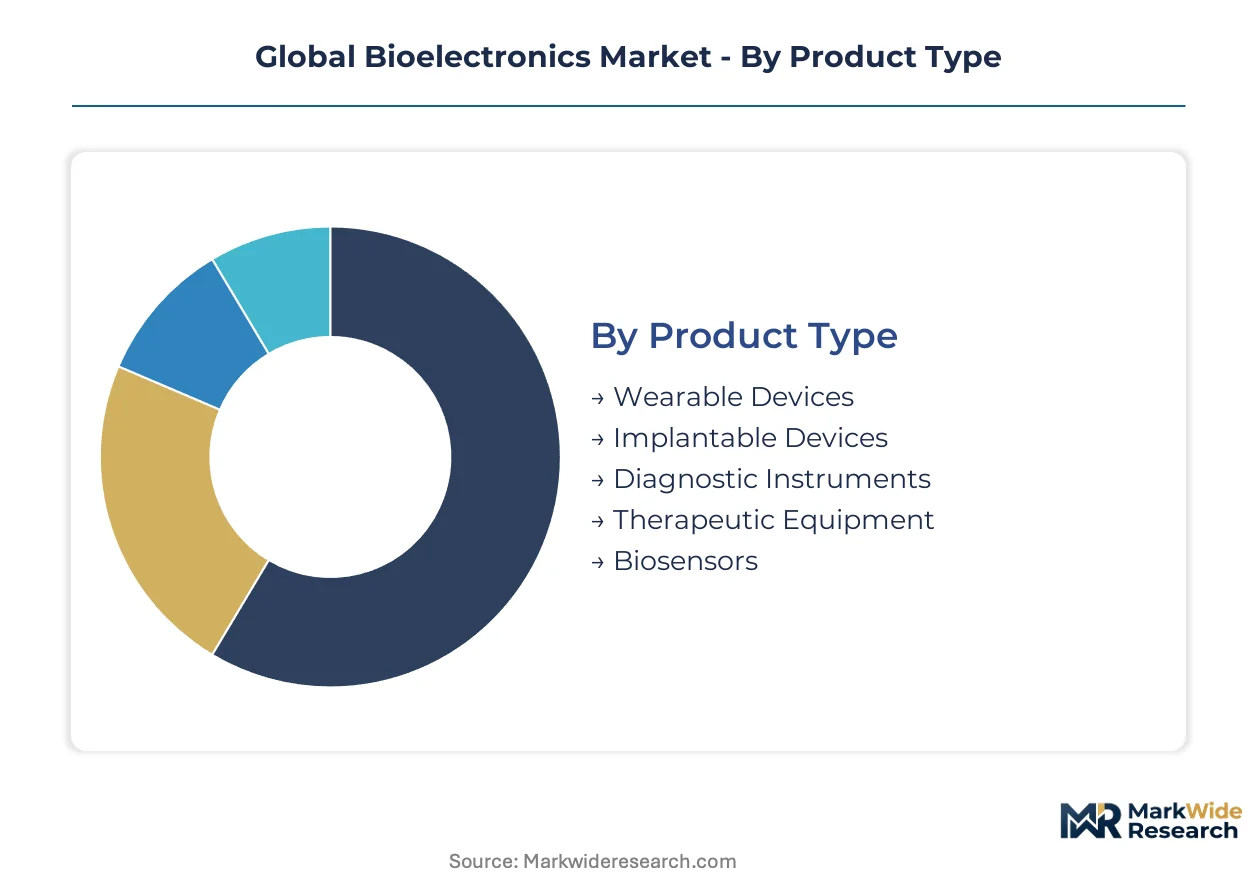
Bioelectronics markets fragment across device invasiveness, signal transduction physics, and care setting economics. Procurement committees weight total cost-of-ownership differently when evaluating ambulatory sensors versus surgical implants, creating distinct competitive arenas within each category.
Product Type:
Supply concentration in electrode materials and sterile manufacturing capacity shapes competitive dynamics across device categories.
- Implantable Devices:Deep surgical workflow integration and regulatory barriers protect margin pools for cardiac rhythm management and neuromodulation systems. German hospital procurement committees anchor European demand for these devices, prioritizing full-lifecycle service agreements over unit pricing.
- Wearable Devices:Electrochemical sensor architectures dominate glucose and cardiac ambulatory monitoring through skin-interfacing conductive polymers. United States Medicare Advantage contracting is consolidating vendor relationships around remote patient monitoring data integration.
- Diagnostic Instruments:Benchtop systems for clinical laboratory settings require FDA 510(k) or EU MDR conformity assessment before commercial deployment.
- Therapeutic Equipment:External neuromodulation and electrotherapy devices compete on reimbursement coding clarity across United States ambulatory surgical centers.
- Biosensors:Point-of-care and home-based formats face steeper cost curve pressure than implantable alternatives.
Today's leader: Implantable Devices. Tomorrow's challenger: Wearable Devices.
Technology:
Cost tier separation between mature electrochemical platforms and emerging semiconductor architectures determines R&D allocation across the industry.
- Electrochemical:Glucose oxidase and cardiac troponin assays leverage well-established fabrication methods with proven biocompatibility profiles. Abbott Laboratories anchors volume deployment through vertically integrated sensor production for ambulatory care settings.
- Semiconductor:Silicon-based neural interfaces and organic electrochemical transistors are gaining share in next-generation chronic recording applications. Academic medical centers in Boston and Zurich pilot polymer-semiconductor hybrids for multi-year implant stability.
- Optical:Spectroscopic methods for continuous glucose and oxygen saturation monitoring require specialized emitter-detector packaging.
- Piezoelectric:Mechanical energy harvesting and pressure sensing applications utilize ceramic and polymer transducer materials.
- Magnetic:Magnetoencephalography and magnetic nanoparticle-based diagnostics serve specialized neurological and oncology applications.
Electrochemical platforms anchor current revenue. Semiconductor architectures are climbing the fastest.
Application:
Volume concentration in chronic disease management workflows drives manufacturing scale economies for specific therapeutic indications.
- Glucose Monitoring:Electrochemical sensor ecosystems penetrate home-based diabetes management beyond traditional clinical settings. United States reimbursement maturation for continuous glucose monitors is unlocking ambulatory surgical center procurement budgets.
- Cardiac Monitoring:Implantable loop recorders and external event monitors command distinct margin structures based on invasiveness and diagnostic yield.
- Neurological Monitoring:Intracranial and cortical interfaces for epilepsy and movement disorders face extended regulatory validation cycles.
- Drug Delivery Systems:Closed-loop infusion pumps and iontophoretic patches require coordinated hardware-software regulatory submissions.
- Tissue Engineering:Bioelectronic scaffolds for regenerative applications remain predominantly preclinical with limited commercial scale.
Glucose Monitoring commands installed base leadership. Neurological Monitoring shows steepest expansion trajectory.
End User:
Customer type differentiation separates capital equipment purchasers from consumable-driven procurement workflows.
- Specialty Clinics:Cardiac electrophysiology and pain management practices concentrate demand for implantable device procedures. Direct field clinical specialist teams are displacing traditional distributor networks in United States integrated delivery networks.
- Medical Research Institutes:Preclinical and early-phase clinical trial demand for novel bioelectronic platforms concentrates in Boston, San Francisco, and Zurich metropolitan clusters.
- Biotechnology Firms:Drug-bioelectronic combination product developers require specialized contract manufacturing and regulatory consulting partnerships.
- Rehabilitation Centers:Functional electrical stimulation and neuroprosthetic applications serve post-stroke and spinal cord injury populations.
- Academic Laboratories:Basic research funding for organic electrochemical transistors and neural interface materials flows through NIH, NSF, and European Research Council grant mechanisms.
Specialty Clinics dominate commercial volume. Medical Research Institutes drive technology translation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioelectronics commercialization traces its industrial lineage to post-war German precision engineering and subsequent US semiconductor integration, with contemporary manufacturing gravity distributing across specialized clusters in North America, Europe, and Asia-Pacific.
United States
Medicare reimbursement maturation for continuous glucose monitors and neuromodulation systems unlocks hospital procurement budgets across ambulatory surgical centers. FDA breakthrough device designation compresses commercialization timelines for novel therapeutic categories. The Greater Boston and San Francisco Bay Area clusters concentrate venture funding for neural interface startups alongside established cardiac rhythm management operations.
Germany
Federal Joint Committee reimbursement decisions determine commercial scalability for implantable bioelectronic therapeutics across statutory health insurance networks. EU MDR compliance timelines and notified body capacity constraints in Berlin and Munich extend conformity assessment queues for active implantable manufacturers. The Baden-Württemberg and Bavaria industrial corridors anchor precision manufacturing for biocompatible electrode materials and sterile device production.
Japan
PMDA streamlined review pathways for software-enabled active implants accelerate post-market authorization for next-generation neuromodulation systems. METI funding mechanisms support domestic semiconductor-neural interface integration programs. The Kanto region surrounding Tokyo concentrates electrochemical sensor manufacturing for glucose monitoring exports across Asia-Pacific markets.
China
NMPA innovation fast-track channels for imported active implantable devices reduce regulatory lag for multinational cardiac rhythm management portfolios. National semiconductor self-sufficiency initiatives under MIIT direction target captive neural interface chip fabrication capacity. The Yangtze River Delta cluster around Shanghai hosts contract manufacturing operations for biocompatible polymer electrode assemblies serving domestic and export demand.
India
CDSCO streamlined approval pathways for implantable cardiac devices open private hospital procurement in Mumbai and Delhi metropolitan clusters. Production-linked incentive schemes under DGFT administration attract electrochemical sensor assembly operations for glucose monitoring devices. The Karnataka and Maharashtra technology corridors concentrate medical device engineering talent pools and contract research organizations supporting clinical trial execution.
Global Bioelectronics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory validation depth and surgical workflow integration intensity. The market structure concentrates around vertically integrated neuromodulation platforms and electrochemical sensor ecosystems, with mid-tier specialists competing on regional regulatory expertise. Three archetypes dominate: full-lifecycle service providers, component-specialist licensors, and regional contract manufacturers. Competitive moves center on direct field clinical specialist team deployment and backward integration into biocompatible electrode material production.
Within the integrated platform tier, Medtronic plc and Abbott Laboratories exemplify archetypal positioning through vertically structured neuromodulation and glucose monitoring portfolios. Boston Scientific Corporation occupies a specialist position in interventional cardiac and peripheral nerve stimulation segments. These entities anchor competitive dynamics through differentiated regulatory submission capabilities and direct hospital procurement relationships across United States integrated delivery networks and German statutory health insurance systems.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| F. Hoffmann-La Roche Ltd. |
| Bayer AG |
| Nova Biomedical Corporation |
| Broadcom Inc. |
| Others |
Supply & Pricing Matrix
Organic electrochemical transistor manufacturing transitions are simultaneously compressing per-unit electrode costs and consolidating biocompatible polymer supply around German and Swiss specialty chemical producers. This dual restructuring amplifies pricing power for implantable device manufacturers while squeezing margin pools for electrochemical sensor assemblers competing on volume scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated neuromodulation systems from MDR-compliant cardiac implants and unbranded biosensor consumables. Price differentiation hinges on regulatory certification tier and surgical workflow integration depth. Cost compression in the economy tier is intensifying because electrochemical glucose sensor commoditization concentrates procurement leverage among United States Medicare Advantage plans. Hospital procurement committees demonstrate lowest price sensitivity for implantable neuromodulation, while home-based glucose monitoring shows highest elasticity.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biocompatible polymer shipments is amplifying regional sourcing preferences among European implantable device manufacturers. Supply concentrates in Germany for precision electrode fabrication, Taiwan for advanced neural interface semiconductor foundry capacity, and China for electrochemical sensor assembly operations. Raw material dependencies span platinum-iridium alloys for cardiac electrodes, conductive polymers for neural interfaces, and glucose oxidase enzymes for biosensor assays. Single-source vulnerability in Taiwan semiconductor fabrication exposes neuromodulation chip supply continuity. Distribution runs through direct field clinical specialist teams for implantables and medical device distributors for consumable sensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Bioelectronics Market reads as a late-cycle quality story where hospital procurement committees are reallocating budgets toward premium-tier implantable systems with full-lifecycle service bundling.
For Market Incumbents: Acquire biocompatible electrode material production capabilities to secure supply continuity against Taiwan semiconductor foundry concentration and precious metal price volatility. Consolidate regulatory submission expertise across FDA breakthrough designation and EU MDR Article 120 compliance to extend conformity assessment queue priority. Deepen backward integration into conductive polymer manufacturing to defend margin pools from specialty chemical supplier pricing power. For New Entrants and Emerging Players: The premium-economy price-point gap in peripheral nerve stimulation devices creates entry space for mid-tier specialists with streamlined regulatory pathways. Target underpenetrated Indian private hospital clusters in Mumbai and Delhi where CDSCO streamlined approvals reduce market entry friction. Deploy AI-enabled diagnostic convergence as the primary go-to-market angle to differentiate from established electrochemical sensor incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with captive biocompatible material production and regional regulatory expertise. Long-term viability across the projection horizon favors platforms with vertically integrated neuromodulation portfolios and direct hospital procurement relationships. Monitor EMA software update guidance evolution as the critical inflection signal for active implantable device margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Compresses commercialization timelines for neuromodulation systems seeking accelerated review. |
| EU MDR Technical Documentation Restructuring | Extends conformity assessment capacity for legacy implantable device portfolios. |
| Direct Field Clinical Specialist Deployment | Displaces distributor networks in United States integrated delivery networks. |
| Biocompatible Polymer Backward Integration | Captures electrode material supply continuity against German specialty chemical concentration. |
| AI-Enabled Diagnostic Platform Development | Creates predictive monitoring differentiation beyond commodity electrochemical sensors. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors grounded the qualitative assessment. Secondary validation drew from FDA 510(k) and breakthrough device designation filings, EMA active implantable guidance documents, CMS Medicare reimbursement coding decisions, and EU MDR notified body capacity reports. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Output projections span volume and value estimates across device invasiveness tiers, signal transduction technologies, therapeutic applications, and end-user categories throughout the forecast period. CAGRs were derived from regression analysis against Medicare reimbursement maturation rates, EU Green Deal manufacturing compliance cost trajectories, and semiconductor foundry capacity expansion timelines. Industry-specific inputs incorporated platinum-iridium price volatility indices and notified body queue duration estimates.
Caveats apply where EMA software update enforcement intensity, Taiwan foundry supply disruption, or CMS reimbursement coding reversals could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Global Broadcast Switcher Market