
 Embedded Controllers Market | 2026-2036
Embedded Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Controllers Market Analysis
Direct semiconductor procurement by automotive OEMs is reconfiguring traditional tiered supply chains. Texas Instruments leverages its analog-digital integration to sustain long-term supply agreements with electrification programs. STMicroelectronics anchors European microcontroller supply through its vertically diffused manufacturing footprint in France and Italy. NXP Semiconductors dominates automotive-grade secure connectivity with its ASIL-certified portfolio spanning gateway and domain controllers.
An embedded controller integrates a processor core, memory, and programmable peripherals on a single die or package, typically operating at clock speeds from 16 MHz to 1 GHz with flash memory densities between 32 KB and 2 MB for deterministic real-time control. These devices execute closed-loop regulation, protocol translation, and sensor fusion for industrial machinery, vehicles, and consumer endpoints. Microcontrollers occupy the largest value pool across product categories due to their ubiquity in cost-sensitive volume applications, while embedded FPGAs capture premium margins in robotics and adaptive signal processing workloads. Automotive end users command the steepest growth trajectory as zonal architectures displace distributed ECU networks, though industrial automation sustains the most predictable replacement cycles.
The US FDA regulates embedded controllers in Class II and Class III medical devices through design control requirements under 21 CFR Part 820, while the EPA's emissions testing protocols mandate tamper-proof controller architectures for engine management. Europe's ECHA enforces REACH substance restrictions on semiconductor packaging materials, and CE marking under the Radio Equipment Directive governs wireless connectivity implementations. Stakeholders must monitor divergence between IEC 61508 safety integrity levels and ISO 26262 automotive grades as functional safety standards proliferate across adjacent end markets.
Market Dynamics
Zonal E/E architectures in automotive are collapsing distributed ECU counts and forcing embedded controller consolidation into domain and zone controllers, compressing unit volumes while elevating performance requirements per device.
Growth Catalysts
- ISO 26262 functional safety mandates:ASIL-D certification requirements for autonomous and electrified powertrain systems are mandating controller redesigns that favor certified embedded architectures with hardware redundancy and lock-step cores.
- Silicon carbide powertrains:Wide-bandgap semiconductor adoption in traction inverters demands faster switching control loops that only specialized automotive microcontrollers with sub-microsecond interrupt latency can execute reliably.
- Germany's automotive cluster:OEM and Tier-1 engineering centers in Stuttgart, Munich, and Wolfsburg concentrate procurement volumes for safety-rated controllers and anchor European demand formation.
Market Restraints
- 300mm wafer supply concentration:Advanced microcontroller fabrication depends on Taiwan and South Korea foundry capacity where automotive-qualified process nodes face allocation competition from consumer and AI accelerator demand.
- Legacy copper bond wire dependencies:Packaging material constraints under Europe's REACH substance restrictions complicate high-temperature automotive controller reliability qualification timelines.
- Functional safety certification costs:Third-party ISO 26262 and IEC 61508 assessment fees plus documentation burden create fixed cost barriers that disadvantage mid-volume embedded controller suppliers.
Strategic Opportunities
- India's automotive electronics localization:Production-linked incentive schemes for semiconductor assembly and testing are attracting controller packaging investments to serve domestic two-wheeler and passenger vehicle electrification programs.
- RISC-V open architecture cores:Royalty-free instruction set architectures enable custom controller designs with deterministic timing extensions that differentiate from ARM-licensed competitors in industrial robotics.
- Software-defined vehicle middleware:Hypervisor-enabled embedded controllers that partition safety-critical and infotainment workloads onto shared silicon create attach opportunities for virtualization-ready microcontroller families.
Industry Challenges
- Embedded systems cybersecurity certification:UN R155 and R156 vehicle type approval requirements mandate security management systems that most legacy controller suppliers lack in-house penetration testing expertise to implement.
- Multi-core software migration:Existing AUTOSAR Classic applications require substantial re-architecture to exploit parallel processing on dual-core lock-step microcontrollers without compromising deterministic real-time guarantees.
- Foundry process migration cadence:Automotive qualification cycles spanning three to five years conflict with foundry node retirement schedules, forcing controller vendors to absorb inventory risk for end-of-life process technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Controllers Market |
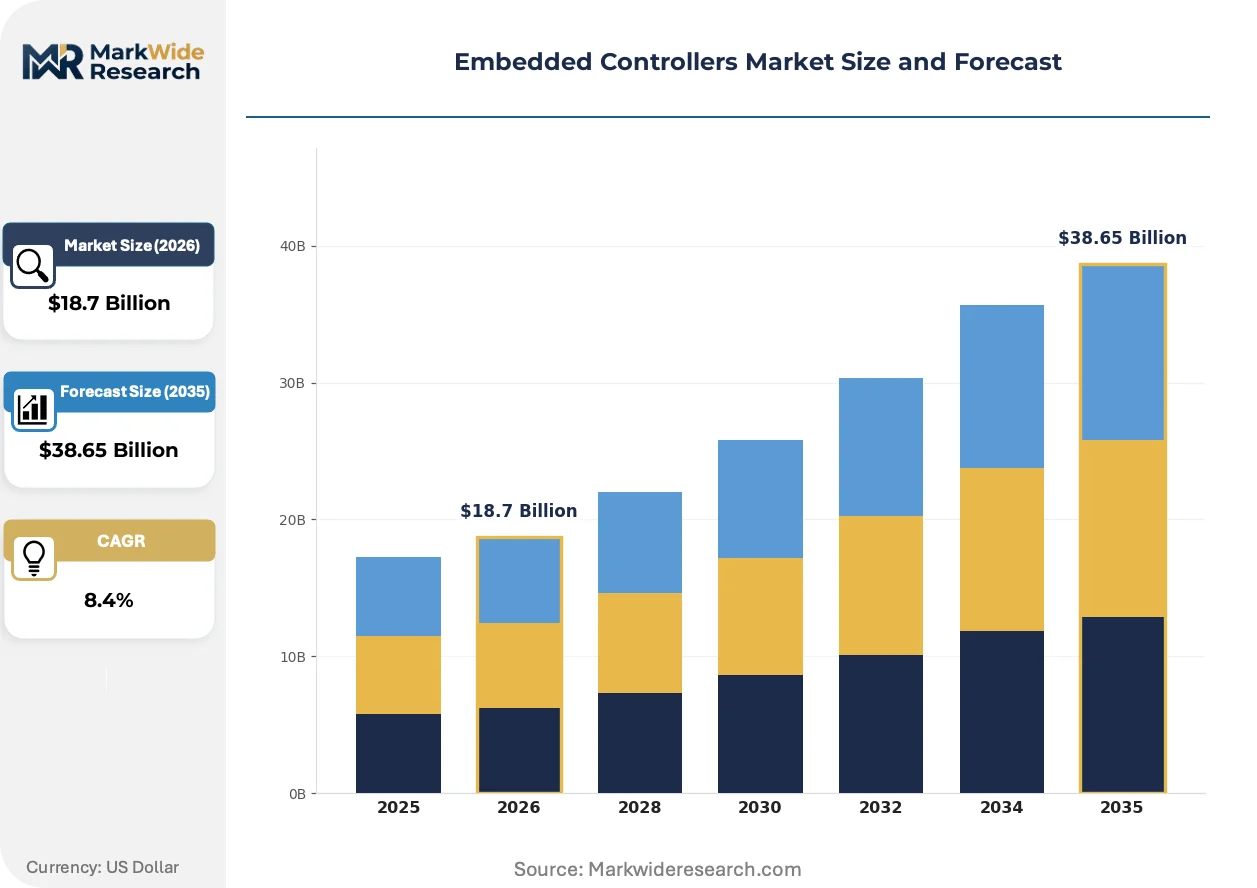
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
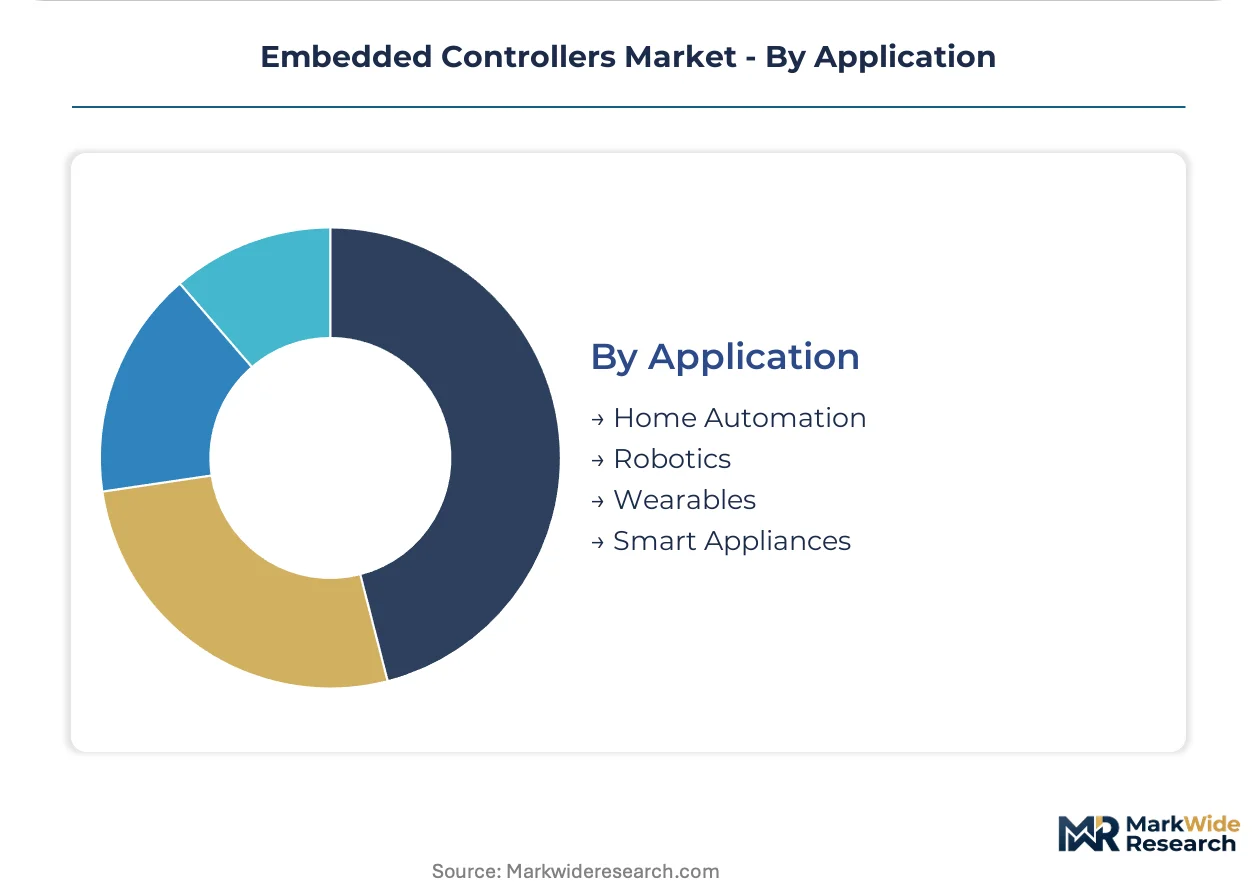
| Segmentation | Product Type: Microcontrollers, Digital Signal Processors, Embedded FPGAs, System on Chip End User: Automotive, Industrial Automation, Consumer Electronics, Medical Devices Connectivity: Bluetooth, Wi-Fi, Ethernet, Zigbee Application: Home Automation, Robotics, Wearables, Smart Appliances |
| Companies Covered | Texas Instruments, STMicroelectronics, Microchip Technology, NXP Semiconductors, Infineon Technologies, Renesas Electronics, Intel Corporation, Analog Devices, Advantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Controllers Market Emerging Trajectories
Hardware-software decoupling through virtualization layers is redefining embedded controller value capture, shifting margin pools from silicon toward software enablement stacks and development tool ecosystems.
Hypervisor technology is virtualizing embedded controller hardware into multiple isolated execution environments. Automotive OEMs in Germany and Japan are deploying these architectures in gateway and zone controller prototypes ahead of 2025 platform launches. This virtualization is compressing hardware SKU diversity while expanding software monetization opportunities through firmware update subscriptions.
Europe's Cyber Resilience Act imposes mandatory security update obligations and vulnerability disclosure requirements on connected device manufacturers. Embedded controller vendors must now maintain decade-long patch lifecycles for automotive and medical device deployments. Industrial automation suppliers in Germany face the steepest compliance burden as their installed base of legacy fieldbus controllers lacks over-the-air update capabilities.
Direct semiconductor procurement by automotive OEMs is displacing traditional Tier-1 module supplier intermediation. Ford, GM, and Volkswagen have established controller sourcing agreements that bypass established ECU integrators and specify silicon directly. This pattern concentrates most visibly in powertrain and battery management domains where OEMs seek to protect intellectual property around thermal and charging algorithms.
Embedded Controllers Market Segmentation
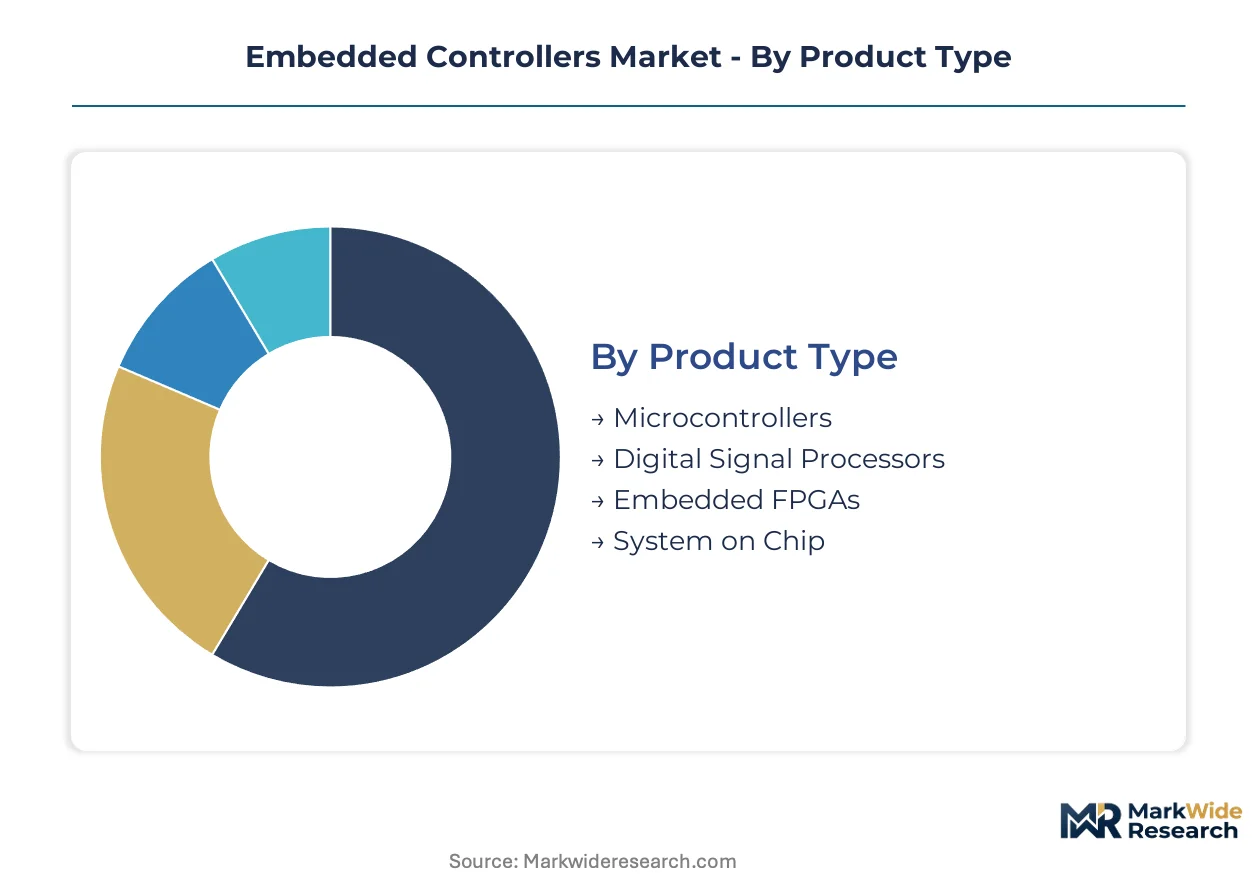
Embedded controllers serve radically different performance and cost requirements across automotive powertrains, industrial robotics, and consumer wearables. Segmentation reveals how microcontroller architectures, connectivity protocols, and safety certifications map to distinct procurement budgets and qualification timelines.
Product Type:
Use cases span deterministic motor control in Stuttgart automotive plants to adaptive signal processing in Shenzhen robotics clusters.
- Microcontrollers:These devices integrate processor cores with flash memory and programmable peripherals on single dies, typically operating between 16 MHz and 1 GHz with memory densities from 32 KB to 2 MB. Automotive powertrain and chassis domains in Germany concentrate procurement for ASIL-rated variants with lock-step cores and hardware redundancy. The dominant share belongs to Microcontrollers, while Embedded FPGAs is closing the gap fastest.
- Digital Signal Processors:Specialized architectures execute multiply-accumulate operations in single clock cycles for real-time audio and vibration analysis. Industrial automation lines in Japan deploy these for predictive maintenance algorithms requiring sub-microsecond latency guarantees.
- Embedded FPGAs:Reconfigurable logic fabrics enable post-deployment algorithm updates for computer vision and adaptive filtering workloads. Robotics OEMs in Germany and Japan pay premium margins for deterministic timing extensions unavailable in fixed-architecture alternatives.
- System on Chip:Heterogeneous integration combines application processors, neural accelerators, and safety islands for software-defined vehicle zone controllers. NXP and STMicroelectronics anchor European supply through vertically integrated manufacturing footprints.
Cost tiers separate commodity 8-bit microcontrollers from automotive-grade multi-core SoCs requiring ISO 26262 certification.
End User:
Procurement concentration varies sharply between safety-critical automotive programs and high-volume consumer electronics.
- Automotive:Zonal E/E architectures are collapsing distributed ECU counts and consolidating functionality into domain controllers with ASIL-D requirements. OEMs in Stuttgart, Munich, and Wolfsburg anchor European demand for certified embedded architectures.
- Industrial Automation:Predictable replacement cycles sustain mid-volume microcontroller demand for programmable logic controllers and motor drives. Germany's factory automation cluster maintains decade-long supplier relationships with deterministic real-time requirements.
- Consumer Electronics:Cost-sensitive volume applications prioritize die size optimization and packaging cost reduction over extended temperature ranges. White goods manufacturers in China specify 8-bit and 16-bit controllers for appliance motor control.
- Medical Devices:FDA design control requirements under 21 CFR Part 820 and IEC 62304 software lifecycle mandates extend qualification timelines. Class II and Class III device manufacturers specify controllers with documented failure modes and effects analysis.
Automotive commands the steepest growth trajectory, though Industrial Automation sustains the most predictable replacement cycles.
Connectivity:
Protocol selection trades power consumption against bandwidth and interoperability certification costs.
- Bluetooth:Low-energy variants dominate wearable and portable medical device implementations with sub-milliwatt idle power consumption. Audio accessory manufacturers in China specify Bluetooth 5.3 for LE Audio broadcast capabilities.
- Wi-Fi:High-throughput implementations serve video-enabled smart appliances and industrial gateways requiring cloud connectivity. CE marking under Europe's Radio Equipment Directive governs 2.4 GHz and 5 GHz band implementations.
- Ethernet:Time-sensitive networking extensions enable deterministic control loops for factory automation and automotive backbone networks. IEEE 802.1AS time synchronization is mandatory for autonomous vehicle sensor fusion architectures.
- Zigbee:Mesh networking protocols concentrate in home automation and building energy management with sub-100 millisecond latency tolerance. Thread protocol convergence is displacing standalone Zigbee implementations in North American smart home deployments.
Ethernet is expanding most quickly in automotive and industrial domains, while Bluetooth retains volume leadership in battery-powered endpoints.
Application:
Maturity curves separate established home automation markets from emerging robotics workloads.
- Home Automation:Lighting and climate control systems specify low-cost 8-bit microcontrollers with integrated RF transceivers. Matter protocol certification is forcing controller redesigns for interoperability across Amazon, Google, and Apple ecosystems.
- Robotics:Collaborative robot arms and autonomous mobile robots demand real-time kinematic control with sub-microsecond joint position feedback. Germany's automotive supplier cluster sources specialized controllers for welding and assembly line integration.
- Wearables:Health monitoring bands and smartwatches integrate sensor fusion hubs with Bluetooth Low Energy connectivity. FDA and CE marking requirements bifurcate designs between wellness devices and regulated medical monitors.
- Smart Appliances:Refrigerators and washing machines add connectivity for predictive maintenance and energy optimization algorithms. India's production-linked incentive schemes are attracting controller packaging investments for domestic appliance electrification programs.
Home Automation holds the largest installed base, though Robotics is gaining share fastest on automation labor substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's semiconductor logistics hub underwrites Europe's embedded controller trade flows, while Taiwan's Hsinchu Science Park rail links anchor Asia-Pacific wafer supply chains. Germany's automotive electrification programs and India's production-linked incentive schemes are redrawing procurement geography.
Germany
Stuttgart, Munich, and Wolfsburg anchor European demand for ASIL-D certified controllers in zonal E/E architectures. KBA vehicle type approval mandates ISO 26262 compliance for autonomous powertrain systems. Baden-Württemberg's supplier cluster concentrates engineering procurement for lock-step core microcontrollers.
United States
Detroit's electrification programs and Austin's semiconductor design centers drive microcontroller demand across powertrain and battery management domains. NHTSA cybersecurity guidelines under FMVSS and EPA emissions testing protocols mandate tamper-proof controller architectures. Michigan's automotive corridor sources directly from silicon vendors, bypassing traditional Tier-1 integrators.
China
Shenzhen's electronics manufacturing ecosystem and Shanghai's automotive R&D centers absorb volume microcontroller supply for domestic EV programs. MIIT mandates GB standards compliance for connected vehicle controllers under national cybersecurity regulations. The Yangtze River Delta concentrates packaging investments serving appliance motor control and industrial automation.
India
Chennai's two-wheeler electrification and Pune's passenger vehicle programs attract controller assembly investments under PLI scheme incentives. BIS certification requirements and DGFT import substitution policies favor domestic semiconductor packaging. Karnataka's electronics manufacturing clusters qualify suppliers for automotive-grade reliability standards.
Japan
Nagoya's industrial robotics manufacturers and Tokyo's automotive engineering centers sustain demand for deterministic real-time controllers. METI's semiconductor strategy targets domestic microcontroller production for critical infrastructure. Chubu's factory automation corridor specifies sub-microsecond latency processors for predictive maintenance systems.
Embedded Controllers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with process-specific differentiation. The vendor base organizes around three archetypes: diversified analog-digital conglomerates with captive fabrication, European vertically integrated microcontroller specialists, and Asia-Pacific fabless design houses with foundry partnerships. Competitive moves concentrate on backward integration into silicon carbide substrate supply and strategic partnerships for RISC-V core licensing.
Within the diversified semiconductor tier, Texas Instruments and STMicroelectronics exemplify archetypes with distinct geographic manufacturing footprints. NXP Semiconductors occupies a position representing automotive-grade secure connectivity specialization. These three anchors illustrate how European and US-based vendors leverage regional regulatory alignment—REACH substance compliance, FDA design controls, and KBA type approval—to sustain procurement relationships with safety-critical end markets.
| Leading Market Players |
|---|
| Texas Instruments |
| STMicroelectronics |
| Microchip Technology |
| NXP Semiconductors |
| Infineon Technologies |
| Renesas Electronics |
| Intel Corporation |
| Analog Devices |
| Advantech |
| Others |
Supply Flow & Price Mechanics
Taiwan's Hsinchu Science Park anchors wafer supply for automotive-qualified microcontroller nodes, where foundry allocation competition from AI accelerators compresses pricing power for embedded controller vendors serving European OEMs. Cost pass-through limitations at Tier-1 module suppliers intensify margin pressure upstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive microcontrollers from industrial-grade variants and commodity 8-bit controllers. Price differentiation rests on ISO 26262 certification grade and volume procurement scale, with Stuttgart OEMs commanding steepest discounts. Cost compression in economy tiers intensifies because Chinese appliance manufacturers prioritize die-size optimization. Consumer electronics buyers exhibit highest price sensitivity; medical device manufacturers accept premium positioning for documented failure mode analysis.
Supply Chain Analysis
TSMC, Samsung Foundry, and GlobalFoundries hold dominant capacity for automotive-qualified 40nm and 28nm process nodes feeding embedded controller production. Taiwan, South Korea, and Germany concentrate supply for silicon carbide substrates, copper bond wire packaging, and ASIL certification testing respectively. Single-source vulnerability concentrates in 300mm wafer supply where automotive process nodes face allocation competition. Distribution runs through authorized distributors serving Tier-1 module suppliers and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as zonal E/E architectures fragment demand across domain controller specialists, zone controller integrators, and legacy ECU consolidation plays. Software-defined vehicle middleware creates niche entry points for virtualization-ready controller families.
For Market Incumbents: Entrench position through captive silicon carbide substrate supply and lock-step core certification investments. Threat from RISC-V open architecture entrants demands defensive patent positioning around deterministic timing extensions. Backward integration into 300mm wafer capacity buffers foundry allocation risk.
For New Entrants and Emerging Players: Pursue India's production-linked incentive schemes for controller assembly and testing serving domestic two-wheeler electrification. White-space concentrates in software-defined vehicle hypervisor layers where virtualization-ready microcontroller families lack established suppliers. Go-to-market through direct OEM procurement relationships bypassing traditional Tier-1 intermediation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-grade secure connectivity specialists with ASIL-certified portfolios spanning gateway and domain controllers. Five-to-ten year viability hinges on software monetization through firmware update subscriptions. Signal to monitor: direct semiconductor procurement agreements by Detroit and Stuttgart OEMs displacing Tier-1 module supplier intermediation.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Powertrain Integration | Wide-bandgap substrate supply anchors traction inverter control loop performance. |
| ASIL-D Certification Investment | Hardware redundancy and lock-step cores unlock Stuttgart OEM procurement volumes. |
| RISC-V Core Licensing Partnership | Royalty-free architectures differentiate deterministic timing for industrial robotics. |
| Direct OEM Procurement Channel | Bypassing Tier-1 integrators captures powertrain and battery management specification control. |
| Hypervisor-Enabled Virtualization Stack | Safety-critical and infotainment workload partitioning creates software subscription attach. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, IHS Markit vehicle production databases, and ECHA REACH substance restriction updates. Semiconductor vendor executives, Tier-1 supplier procurement directors, and OEM platform engineering leads provided demand-side validation. Bottom-up unit shipment estimates triangulated against top-down value projections across product type and end-use segments.
Forecast inputs incorporate silicon carbide powertrain adoption curves, zonal E/E architecture migration timelines, and functional safety certification completion rates across the projection horizon. Segmentation dimensions span product architecture, ASIL grade tier, connectivity protocol, and regional production cluster. CAGRs derived from regression analysis of historical microcontroller ASP trajectories and foundry capacity expansion announcements.
Sensitivities concentrate around foundry node allocation shifts, REACH packaging material restriction enforcement, and ISO 26262 certification backlog accumulation. Forecasts embed assumptions regarding automotive electrification program commitments and industrial automation replacement cycle stability. Quarterly review of wafer utilization rates, KBA type approval volumes, and PLI scheme disbursement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market