
 Video Encoder and Decoder Market | 2026-2036
Video Encoder and Decoder Market Size, Share, and Industry Trends Forecast 2026-2036
Video Encoder and Decoder Market Analytics
Subscription-based software-defined encoding is pivoting how vendors monetize video infrastructure. Haivision leverages cloud-native architectures to serve broadcasters with elastic capacity. Motorola Solutions anchors public safety deployments with hardened hardware codecs. Harmonic competes through managed SaaS offerings that reduce customer capex burdens.
Video encoders and decoders are signal processing systems that compress raw video streams into bandwidth-efficient formats and reconstruct them for playback, typically handling resolutions from 720p to 8K at bitrates ranging from 2 Mbps to 100 Mbps depending on codec efficiency and quality targets. Their primary purpose is enabling storage, transmission, and real-time distribution of video across constrained networks. Hardware encoders still dominate live broadcasting and surveillance where latency below 50 milliseconds is mandatory, while software encoders are capturing share in streaming and video conferencing where flexibility outweighs raw throughput. H.265 leads technology adoption in premium broadcasting due to its compression efficiency, though AV1 is gaining traction among streaming platforms seeking royalty-free alternatives.
The Federal Communications Commission shapes terrestrial broadcast standards in the United States, while the International Telecommunication Union coordinates global codec interoperability through H-series recommendations. The European Union's Radio Equipment Directive mandates CE marking for video transmission hardware sold in member states, affecting market access timelines. Stakeholders must monitor codec patent pool dynamics and sovereign cloud mandates as these forces will determine which encoding architectures secure long-term platform commitments.
Market Dynamics
The migration from hardware-bound encoding appliances to software-defined, cloud-native architectures is compressing vendor margins while expanding addressable use cases beyond traditional broadcast into enterprise streaming and AI-powered video analytics pipelines.
Growth Catalysts
- AV1 Royalty-Free Adoption:Streaming platforms are deploying AV1 codecs to eliminate H.265 patent pool liabilities. The Alliance for Open Media specification reduces per-stream licensing costs for high-volume distributors.
- FCC Next-Gen TV Mandate:The Federal Communications Commission's ATSC 3.0 framework requires terrestrial broadcasters to support advanced encoding formats. Station groups are refreshing encoder fleets to comply with 2025 spectrum reallocation timelines.
- Hyperscale Cloud Infrastructure:Amazon Web Services, Microsoft Azure, and Google Cloud Platform are building dedicated media encoding silicon. Elastic capacity models let broadcasters burst processing during live events without capital deployment.
Market Restraints
- Codec Patent Pool Fragmentation:MPEG LA, Access Advance, and Velos Media maintain overlapping H.265 patent claims. License stacking creates legal uncertainty that slows procurement decisions at mid-tier streaming services.
- Hardware Encoder Supply Concentration:Taiwan-based semiconductor foundries fabricate the majority of broadcast-grade encoding ASICs. Geopolitical friction around Taiwan Strait shipping lanes introduces supply continuity risk.
- Legacy SDI Infrastructure Entrenchment:National broadcasters in Western Europe maintain substantial investments in Serial Digital Interface routing. Hybrid IP-SDI transition costs deter premature all-software encoding adoption.
Strategic Opportunities
- AI-Accelerated Per-Title Encoding:Machine learning models are integrating with encoding pipelines to optimize bitrate ladders frame-by-frame. Netflix and YouTube deployment of neural codecs is compressing file sizes without perceptual quality loss.
- EU Green Deal Compliance:The European Commission's data center energy efficiency directives favor software encoders running on renewable-powered cloud regions. Broadcasters can offset carbon reporting obligations through codec efficiency gains.
- Edge Computing Architectures:5G network slicing enables encoding at cellular base stations. Live sports producers are testing sub-100 millisecond contribution feeds from stadiums without satellite uplink dependency.
Industry Challenges
- Real-Time Encoding Talent Scarcity:Deep expertise in GPU kernel optimization for H.265 and AV1 is concentrated among semiconductor vendors and hyperscale engineering teams. Broadcast technology vendors face recruitment competition for video codec engineers.
- Multi-Codec Certification Complexity:Content delivery networks must validate playback compatibility across Smart TVs, mobile devices, and browsers. Quality assurance matrices expand exponentially with each new codec generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Encoder and Decoder Market |
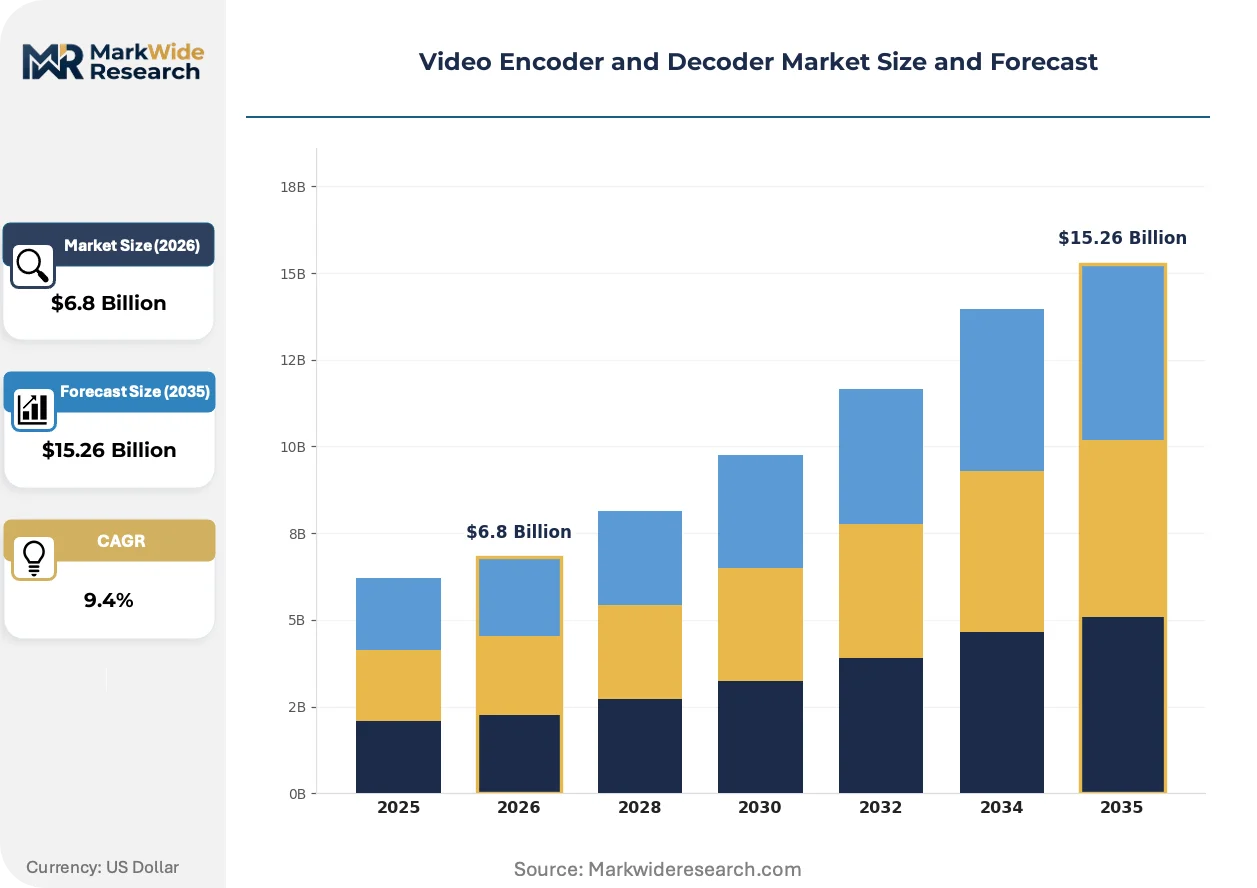
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Encoder, Software Encoder, Hardware Decoder, Software Decoder Technology: H.264, H.265, AV1, VP9, MPEG-2 Application: Broadcasting, Video Streaming, Video Conferencing, Surveillance, Video Editing End User: Media Companies, IT Enterprises, Security Providers, Content Creators |
| Companies Covered | Motorola Solutions, Haivision, Harmonic, Magewell, Teradek, Hikvision, Cisco, Blackmagic Design, VITEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Encoder and Decoder Market Evolving Landscape
Codec efficiency wars are forcing encoder vendors to optimize for divergent metrics: broadcasters prioritize deterministic latency while streaming platforms maximize compression ratios. The resulting product architecture splits are reshaping R&D allocation across the supplier base.
Neural network-based encoding is integrating into commercial encoder product lines. Bitmovin and AWS Elemental are deploying per-scene adaptive quantization that reduces bitrates by analyzing visual complexity in real time. Broadcasters adopting these tools are maintaining 4K quality at 40% lower bandwidth than fixed-profile H.265.
The European Union's Radio Equipment Directive is tightening electromagnetic compatibility requirements for video transmission hardware sold in member states. Manufacturers must obtain CE marking through notified body assessment, extending product launch timelines by four to six months. Professional encoder vendors are redesigning power supply architectures to meet updated conducted emissions limits.
Enterprise buyers are consolidating encoding procurement under centralized media operations teams. Previously siloed broadcast, corporate communications, and security video groups are standardizing on shared cloud encoding platforms. This organizational consolidation is visible most acutely among Fortune 500 companies with substantial internal video production volumes.
Video Encoder and Decoder Market Segmentation
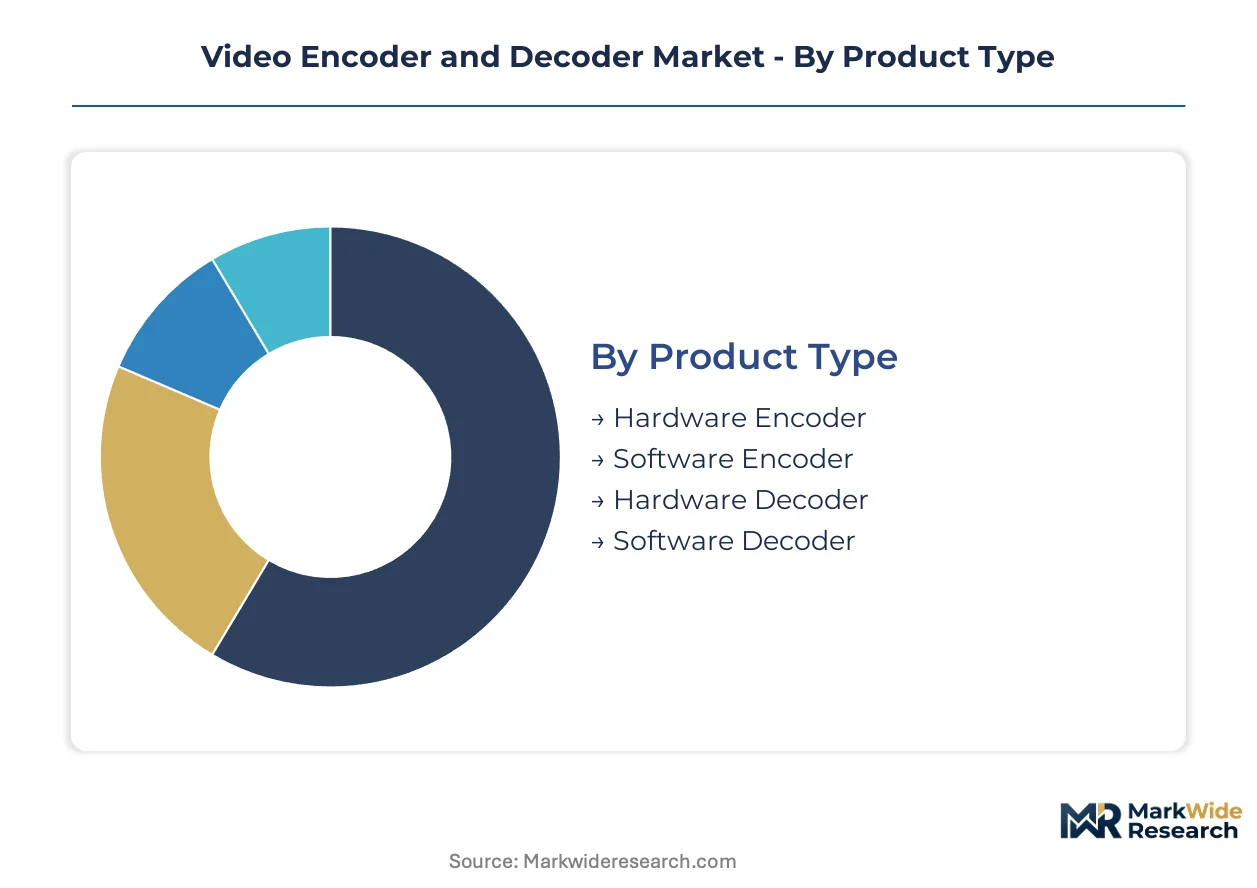
Video encoder and decoder procurement splits sharply between deterministic hardware appliances and elastic software deployments, with technology choices locking customers into decade-long infrastructure commitments. Understanding these segment boundaries reveals where vendor margins concentrate and which architectures will capture next-generation workloads.
Product Type:
Customization-to-standardization tension runs highest here, with bespoke hardware configurations dominating premium broadcast while off-the-shelf software licenses democratize access for mid-market streaming operators.
- Hardware Encoder:Dedicated ASIC-based appliances process uncompressed SDI feeds with sub-frame latency for live production trucks and national broadcast centers. Demand clusters with ABC, CBS, and NBC affiliate station groups refreshing ATSC 3.0 infrastructure across the United States.
- Software Encoder:Cloud-native encoding engines deploy on standard compute instances, enabling elastic scaling for peak streaming events without capital commitment. Netflix, Disney+, and Max utilize these for VOD libraries where latency tolerance exceeds 500 milliseconds.
- Hardware Decoder:Purpose-built playback devices integrate into professional monitoring chains and digital signage networks.
- Software Decoder:Browser-based and application-layer decoding solutions dominate consumer device compatibility matrices.
Leading the category by volume: Software Encoder. Expanding most quickly: Software Encoder.
Technology:
Codec selection follows a cost-tier logic, with royalty-bearing standards commanding premium positioning and open-source alternatives penetrating price-sensitive streaming tiers.
- H.265:Advanced compression reduces bitrates by 50% versus H.264 at equivalent quality, though patent pool licensing through MPEG LA and Access Advance adds per-stream costs. Premium broadcasters in Japan and South Korea mandate H.265 for 4K satellite distribution.
- AV1:Royalty-free specification from the Alliance for Open Media eliminates licensing friction for high-volume distributors. YouTube and Netflix deployment for mobile and low-bandwidth markets accelerates hardware decoder availability in smart TVs.
- H.264:Mature codec with universal device compatibility sustaining massive installed base in surveillance and legacy streaming.
- VP9:Google-developed open codec retains substantial presence in WebRTC video conferencing pipelines.
- MPEG-2:Legacy standard persists in terrestrial broadcast and cable headend infrastructure scheduled for phased replacement.
Volume leadership: H.264. Steepest expansion trajectory: AV1.
Application:
Application segmentation maps directly to customer technical requirements, with latency tolerance and quality thresholds determining hardware-versus-software procurement decisions.
- Broadcasting:Live production demands hardware-based encoding with guaranteed 50-millisecond latency for real-time switching and graphics insertion. Major sports leagues and election coverage networks in the United States maintain redundant encoder chains.
- Video Streaming:OTT platforms optimize for compression efficiency over latency, enabling software-based per-title encoding that adapts bitrate ladders to content complexity. Amazon Prime Video and Paramount+ deploy machine learning-enhanced encoding for catalog titles.
- Video Conferencing:Real-time communication platforms balance bandwidth adaptation with minimal latency for interactive sessions.
- Surveillance:Security operations prioritize multi-channel density and 24/7 reliability in hardened environmental conditions.
- Video Editing:Post-production workflows require intra-frame codecs supporting generation-loss-free concatenation and color grading.
Dominant by revenue: Broadcasting. Gaining share fastest: Video Streaming.
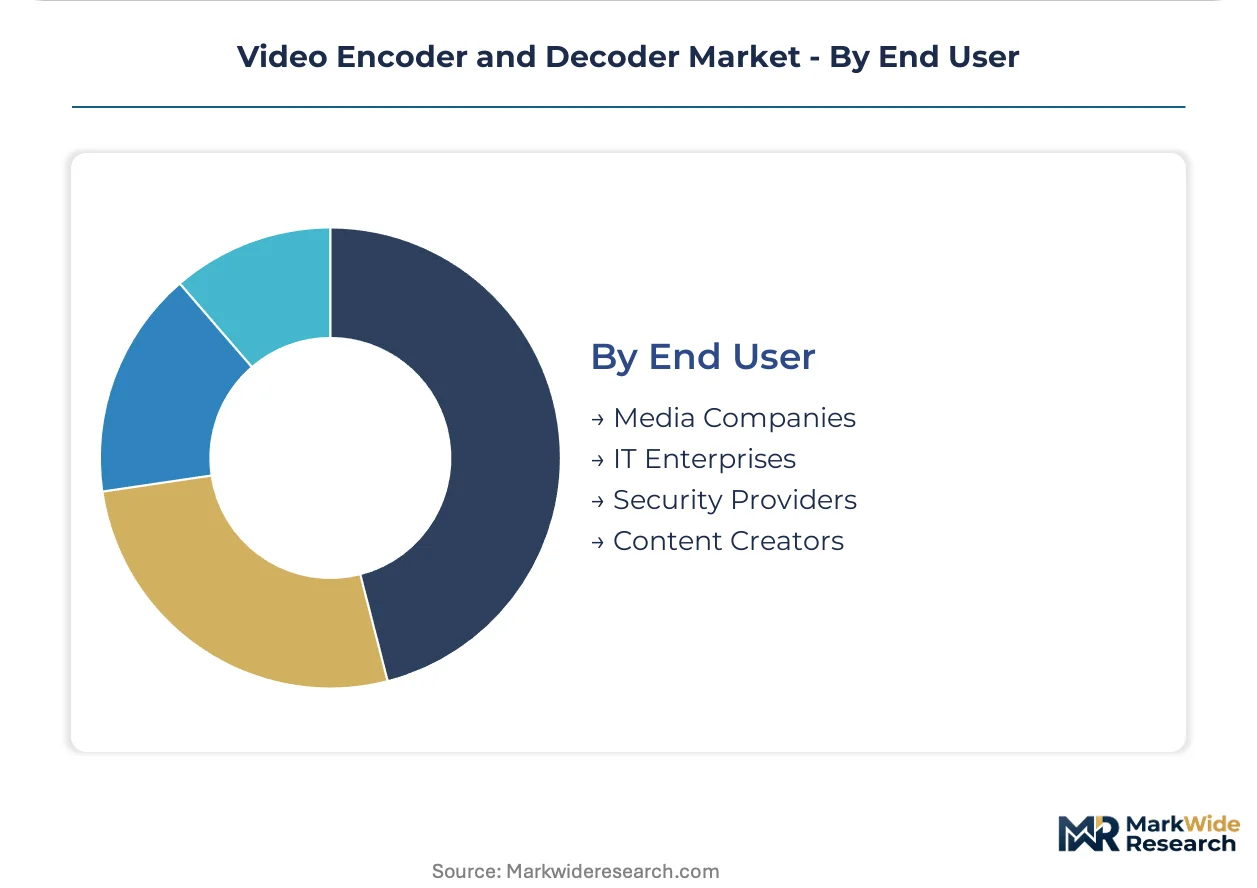
End User:
Customer-type segmentation reveals divergent procurement authority structures, with centralized media operations teams consolidating previously siloed encoding purchases.
- Media Companies:Traditional broadcasters and streaming pure-plays operate the largest encoding footprints, managing petabyte-scale libraries and live channel origination. Warner Bros. Discovery and Comcast NBCUniversal maintain dedicated encoding engineering teams.
- IT Enterprises:Fortune 500 corporations with substantial internal video production consolidate encoding under centralized media operations, standardizing on cloud platforms for executive communications and training.
- Security Providers:Video surveillance integrators specify encoder density and environmental hardening for municipal and commercial deployments.
- Content Creators:Individual producers and small studios leverage software-as-a-service encoding for social media and direct-to-consumer distribution.
Category volume leader: Media Companies. Climbing the fastest: IT Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of broadcast-grade encoding infrastructure, while Taiwan and South Korea supply the specialized ASICs powering live production workflows. China manufactures substantial volumes of surveillance-optimized codecs, creating a geographic split between design, fabrication, and deployment.
United States
Hyperscale cloud providers and national broadcasters drive infrastructure refresh cycles across the country. The Federal Communications Commission mandates ATSC 3.0 compliance for terrestrial stations by 2025. Los Angeles and New York anchor live production encoding clusters serving Hollywood studios and network headquarters.
Taiwan
Semiconductor foundries fabricate broadcast-grade encoding ASICs for global equipment vendors. The country's national communications regulator enforces electromagnetic compatibility standards for video transmission hardware. Hsinchu Science Park concentrates wafer production for 4K and 8K encoding silicon.
Germany
Public broadcasters ARD and ZDF deploy hardened encoders for national DVB-T2 distribution. The European Union's Radio Equipment Directive mandates CE marking for video transmission equipment sold across member states. Berlin and Munich host engineering centers developing H.265 optimization tools for satellite uplinks.
Japan
Broadcasters NHK and commercial networks lead 8K Super Hi-Vision encoding deployments. The Ministry of Internal Affairs and Communications coordinates spectrum allocation for next-generation terrestrial broadcasting. Tokyo's Odaiba district hosts testbed facilities for real-time neural codec integration.
South Korea
Telecom operators SK Telecom and KT deploy edge encoding for 5G live sports distribution. The Korea Communications Commission regulates over-the-top streaming quality standards. Seoul's Pangyo Techno Valley houses R&D labs optimizing AV1 hardware acceleration for mobile devices.
Video Encoder and Decoder Market Competitive Landscape
Top-tier vendors anchor broadcast infrastructure contracts, while mid-tier specialists capture streaming and surveillance niches. The supplier base stratifies across three tiers: hyperscale cloud platforms with captive silicon, established broadcast equipment houses with SDI heritage, and emerging software-native challengers. Strategic moves concentrate on cloud-native portfolio pivots and vertical integration into media processing silicon.
Within the broadcast equipment tier, Motorola Solutions and Haivision occupy positions reflecting divergent architectural bets. Motorola Solutions exemplifies hardened hardware specialization for public safety and government applications. Haivision represents cloud-native elasticity targeting broadcasters seeking operational flexibility. Harmonic anchors the managed services archetype, reducing customer capital burdens through subscription monetization models.
| Leading Market Players |
|---|
| Motorola Solutions |
| Haivision |
| Harmonic |
| Magewell |
| Teradek |
| Hikvision |
| Cisco |
| Blackmagic Design |
| VITEC |
| Others |
Value Network & Pricing Analysis
Performance-grade certification tiers separate broadcast-hardened appliances from commodity software licenses, creating divergent margin structures that map directly onto Taiwan-centric ASIC sourcing versus cloud-region compute arbitrage. Buyers of sub-50-millisecond hardware encoders absorb premium positioning tied to FCC ATSC 3.0 compliance, while streaming operators exploit elastic SaaS pricing unconstrained by foundry capacity queues.
Pricing Analysis
Margin tightening in hardware tiers reflects foundry allocation scarcity for 4K/8K encoding silicon. Three-tier pricing structure across premium, standard, and economy levels stratifies by latency guarantee and codec breadth, with broadcast-grade appliances commanding 3-4x premiums over surveillance-optimized units. Cost-down pressure on software encoders accelerates as hyperscale cloud providers internalize media processing silicon. IT enterprises show highest price sensitivity through centralized procurement committees, while public safety agencies prioritize deterministic performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries fabricating broadcast-grade encoding ASICs for global equipment vendors. Component sourcing draws from South Korean memory suppliers and Japanese precision analog semiconductor houses. Geopolitical friction around Taiwan Strait shipping lanes constitutes the primary structural risk, compounded by concentration in Hsinchu Science Park wafer production. Distribution runs through authorized broadcast equipment distributors and direct hyperscale cloud marketplaces, with logistics anchored in Los Angeles and Amsterdam media hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC ATSC 3.0 compliance deadlines erect a cost-of-compliance barrier that favors incumbents with certified encoder fleets and burdens challengers with 12-18 month certification timelines.
For Market Incumbents: To counter hyperscale cloud encroachment into broadcast workflows, incumbents should deepen backward integration into media processing silicon through foundry partnerships in Taiwan and South Korea. Certification investment in EU Radio Equipment Directive CE marking creates regional lock-in against software-native challengers lacking hardware heritage. For New Entrants and Emerging Players: Mid-tier streaming operators in Western Europe present the most penetrable buyer archetype, underserved by legacy broadcast vendors and priced out of hyperscale managed services. White-space capture demands AV1-optimized SaaS encoding with per-title machine learning, sold through channel partners possessing existing CDN relationships. Direct enterprise sales teams bypass entrenched broadcast procurement committees. For Investors and Strategic Acquirers: Re-rating potential sits with software-native encoding specialists possessing GPU kernel optimization talent, given AI-accelerated per-title encoding adoption by major streaming platforms. Long-term viability hinges on codec patent pool navigation capabilities. The signal to watch is Alliance for Open Media hardware decoder penetration rates in smart TV silicon, indicating AV1 tipping-point acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Elastic capacity models let broadcasters burst processing during live events without capital deployment. |
| AI-Accelerated Per-Title Encoding | Netflix and YouTube deployment of neural codecs compresses file sizes without perceptual quality loss. |
| Edge Computing Architecture Deployment | 5G network slicing enables sub-100 millisecond contribution feeds from stadiums without satellite uplink dependency. |
| Codec Patent Pool Diversification | AV1 royalty-free adoption eliminates H.265 licensing friction for high-volume distributors. |
| EU Green Deal Compliance Positioning | Software encoders running on renewable-powered cloud regions offset broadcaster carbon reporting obligations. |
Research Methodology
Multi-period observation of hyperscaler media encoding capex, broadcast station ATSC 3.0 refresh cycles, and streaming platform codec deployment schedules anchored the trend analysis, supplemented by interviews with broadcast engineering directors, cloud platform product managers, semiconductor foundry account executives, and CDN procurement leads. Secondary validation drew from FCC filing databases, SEC 10-K equipment vendor disclosures, hyperscaler infrastructure investment announcements, and patent pool royalty rate publications. Bottom-up encoder shipment modeling triangulated against top-down content delivery network bandwidth growth estimates.
Segment-weighting across hardware versus software deployment models, H.265 versus AV1 codec technology trajectories, and broadcasting versus streaming application splits informed the analytical framework throughout the projection horizon. CAGRs derived from S-curve adoption modeling for next-generation codecs, cross-referenced with foundry capacity expansion announcements and terrestrial broadcaster spectrum reallocation timelines. Forecast inputs incorporated AI-accelerated encoding efficiency gains and 5G edge computing infrastructure deployment curves.
Revisions become necessary when semiconductor foundry geopolitical disruptions, codec patent pool litigation outcomes, or sovereign cloud mandate implementations materialize outside baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Sound Reception System Market