
 Nanoelectromechanical Systems (NEMS) Market | 2026-2036
Nanoelectromechanical Systems (NEMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoelectromechanical Systems (NEMS) Market Foresight
Direct sales partnerships between foundries and end-equipment makers is tilting toward vertically integrated supply arrangements. Texas Instruments leverages captive fabrication capacity to control sensor-grade wafer output. Bruker Corporation anchors its position through R&D intensity in scanning probe instrumentation. Robert Bosch GmbH competes by extending MEMS manufacturing scale into nanoscale device production.
Nanoelectromechanical systems integrate mechanical and electrical functionality at sub-micron scales, typically operating with critical dimensions below 100 nanometers and resonant frequencies in the megahertz to gigahertz range for sensing, actuation, and signal processing applications. CMOS-compatible fabrication routes dominate commercial production due to foundry infrastructure reuse and lithography precision. Sensors lead product type revenue pools because environmental and inertial variants command premium pricing in automotive and aerospace qualification tiers. Biomedical Devices within the application dimension represents the fastest structural expansion as implantable and point-of-care platforms demand femtogram-scale mass resolution.
FDA governs nano-enabled diagnostic interfaces through evolving premarket notification pathways while ISO delivers dimensional metrology standards that calibrate cross-border equipment interoperability. EPA monitors nanomaterial environmental release thresholds from fabrication facilities, shaping site selection and waste handling compliance burdens. Stakeholders must monitor how semiconductor export controls and clean-energy manufacturing credits redistribute foundry access and customer qualification timelines.
Market Dynamics
Fabrication equipment scarcity at leading-edge nodes is compressing NEMS foundry capacity allocation timelines. Device makers now bid for 300mm wafer starts eighteen months ahead of tape-out, fundamentally altering how sensor fabless firms secure manufacturing slots.
Growth Catalysts
- NIH SBIR funding:The National Institutes of Health Small Business Innovation Research program accelerates point-of-care diagnostic prototypes through streamlined grant-to-procurement pathways.
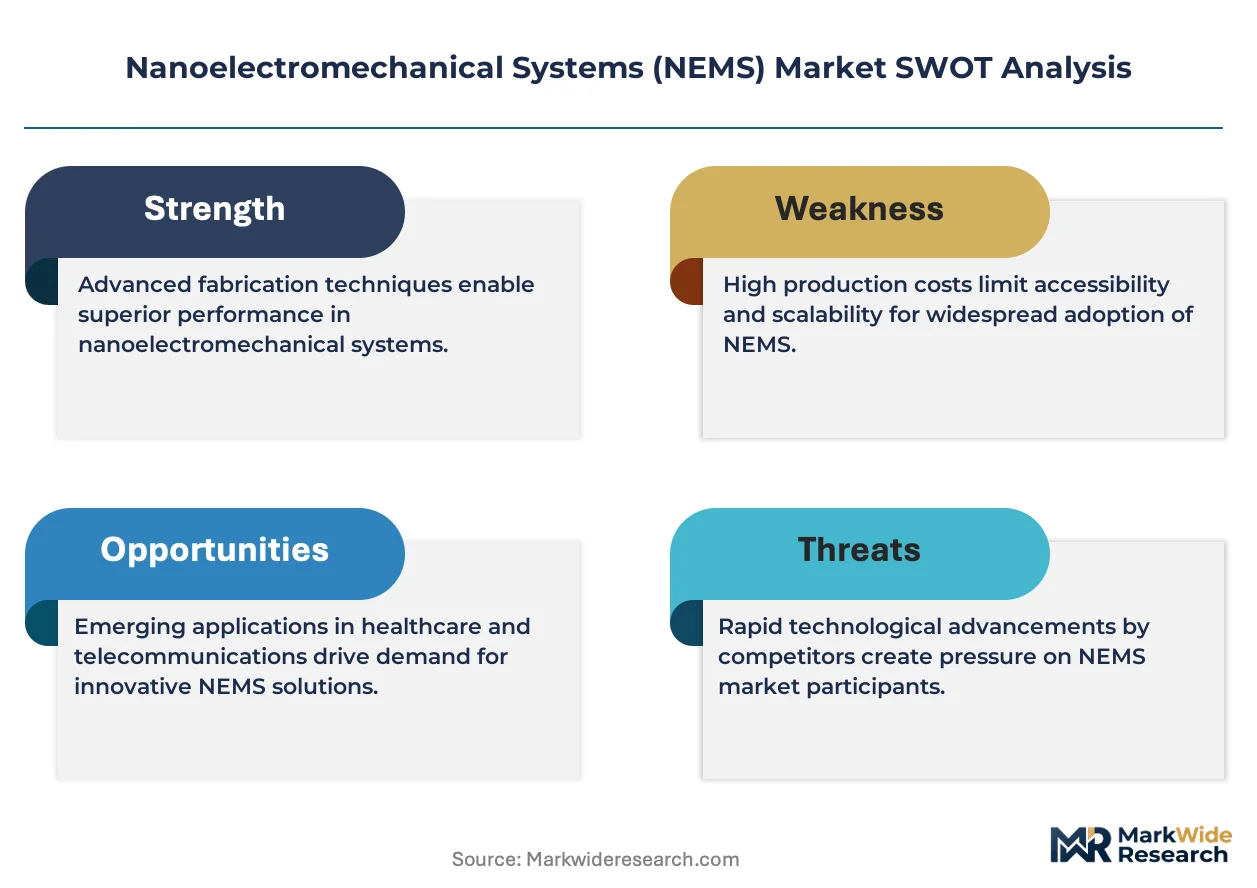
- CMOS-compatible resonator architectures:Piezoelectric aluminum nitride processes enable foundry reuse of existing 200mm lines, collapsing non-recurring engineering costs for environmental sensor startups.
- Germany:The KBA automotive certification framework now recognizes nano-scale inertial sensors for advanced driver-assistance systems, opening fleet procurement channels previously reserved to MEMS incumbents.
Market Restraints
- E-beam lithography tool concentration:ASML and JEOL equipment lead times now exceed fourteen months, throttling prototype throughput for sub-50nm critical dimension devices.
- Helium-3 supply fragility:Neutron detection applications face input cost volatility as Russian export quotas constrict isotope availability for NEMS-based radiation sensors.
- ISO 80000-1 dimensional traceability:Cross-border calibration disputes between national metrology institutes delay equipment qualification for aerospace tier-one suppliers.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor packaging attract NEMS module assembly investments targeting domestic medical device OEMs.
- Quantum sensing convergence:Integration of optomechanical resonators with superconducting qubit readout creates femtotesla magnetometry for unshielded biomagnetic imaging.
- Direct-to-foundry procurement platforms:Online wafer start marketplaces displace traditional distributor networks for sub-million-unit sensor programs.
Industry Challenges
- Multiphysics simulation expertise:Coupled electromechanical-thermal modeling talent scarcity extends design validation cycles for automotive qualification programs.
- ISO 10993 biocompatibility testing:Implantable NEMS face eighteen-to-twenty-four-month certification timelines as FDA reviewers build nano-specific toxicology precedents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoelectromechanical Systems (NEMS) Market |
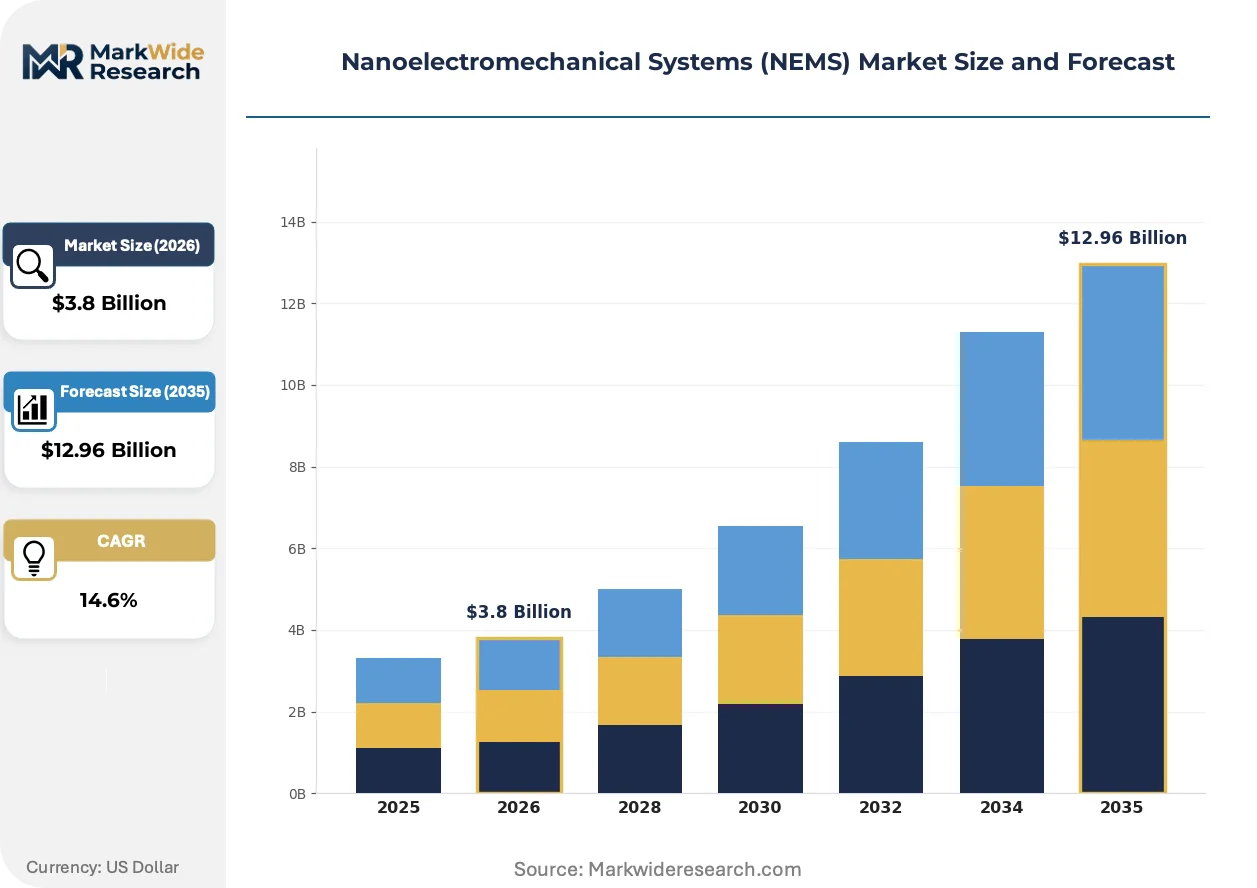
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microactuators, Nanodevices, Sensors, Transducers Application: Telecommunications, Biomedical Devices, Environmental Monitoring, Industrial Automation Technology: CMOS, MEMS, RF Technologies, Piezoelectric End User: Aerospace, Automotive, Consumer Electronics, Healthcare |
| Companies Covered | Texas Instruments Incorporated, Bruker Corporation, IBM Corporation, Nanosurf AG, Oxford Instruments plc, STMicroelectronics, Agilent Technologies Inc., Nanocyl SA, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoelectromechanical Systems (NEMS) Market Shifts & Advancements
Convergence between quantum measurement techniques and classical nanofabrication is dissolving historical boundaries between academic research tools and commercial sensor platforms. Device architectures once confined to physics laboratories now ship in volume for industrial process control.
Graphene-based resonant mass sensors are hybridizing electromechanical transduction with two-dimensional material surface functionalization. Pharmaceutical quality-control labs adopt these platforms for real-time bioprocess monitoring. The technology is hybridizing batch chromatography workflows into continuous manufacturing lines, compressing drug substance release timelines from weeks to hours.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of hydrophobic coatings used in NEMS humidity sensors. European environmental monitoring networks now specify fluorine-free alternatives in tender documents. German industrial sensor OEMs accelerate qualification of plasma-polymerized hexamethyldisiloxane barriers to maintain IP67-rated product lines.
Defense procurement offices now mandate domestic wafer provenance for strategic sensor categories, fragmenting previously global supply bases. Tier-one aerospace contractors respond by dual-sourcing identical designs from foundries in the United States and allied nations. This geographic unbundling is most visible in inertial measurement unit programs for satellite constellations, where supply assurance now outweighs unit cost minimization in source selection criteria.
Nanoelectromechanical Systems (NEMS) Market Segmentation
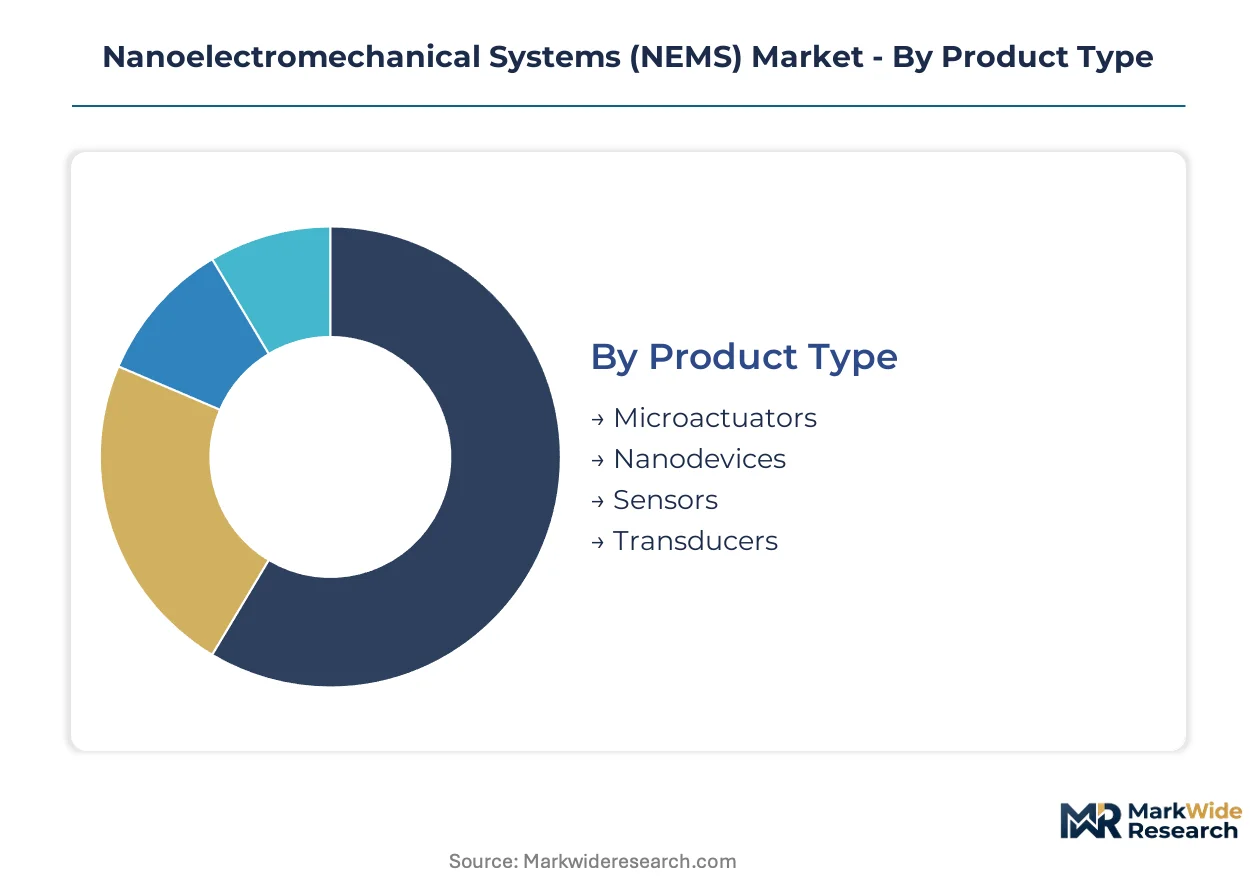
NEMS markets fragment across fabrication maturity, application risk tolerance, and end-user qualification tiers. Segment boundaries blur as CMOS foundries absorb nanoscale mechanical functions into unified process flows. Procurement patterns diverge sharply between automotive volume programs and biomedical premium validation cycles.
Product Type:
Mature MEMS-derived categories dominate current revenue pools while emerging nanodevice architectures reshape competitive positioning.
- Sensors:Environmental and inertial variants operate at megahertz-to-gigahertz resonant frequencies with sub-100nm critical dimensions. Automotive qualification tiers in Germany and the United States absorb the majority of volume, driven by KBA certification pathways for advanced driver-assistance systems.
- Nanodevices:Femtogram-scale mass resolution enables implantable diagnostics and point-of-care platforms. NIH SBIR funding channels accelerate FDA premarket notification timelines for domestic biomedical device manufacturers.
- Microactuators:Piezoelectric aluminum nitride processes leverage existing 200mm foundry infrastructure.
- Transducers:Signal conversion modules integrate with scanning probe instrumentation for industrial metrology.
Sensors handle the majority of throughput; nanodevices are climbing the fastest on share.
Application:
Application segmentation tracks regulatory intensity and reimbursement velocity across end-use verticals.
- Biomedical Devices:Implantable and point-of-care platforms demand ISO 10993 biocompatibility testing with eighteen-to-twenty-four-month FDA certification timelines. Federal nanotechnology initiatives and NIH funding direct procurement toward United States-based suppliers.
- Environmental Monitoring:REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of hydrophobic coatings. European tender networks now specify fluorine-free alternatives.
- Telecommunications:RF resonator architectures serve 5G infrastructure timing synchronization.
- Industrial Automation:Process control sensors compress drug substance release timelines from weeks to hours in pharmaceutical quality-control labs.
Biomedical Devices command premium pricing; Environmental Monitoring is gaining share fastest on regulatory tailwinds.
Technology:
Technology segmentation reflects foundry infrastructure reuse versus specialized fabrication requirements.
- CMOS:Compatible fabrication routes dominate commercial production through lithography precision and infrastructure reuse. Foundry capacity allocation timelines now require eighteen-month advance bidding for 300mm wafer starts.
- Piezoelectric:Aluminum nitride processes enable resonator architectures on existing 200mm lines, collapsing non-recurring engineering costs for environmental sensor startups.
- MEMS:Manufacturing scale extends into nanoscale device production through proven qualification frameworks.
- RF Technologies:High-frequency signal processing demands specialized substrate materials and e-beam lithography tooling.
CMOS captures the volume base; Piezoelectric shows the steepest expansion trajectory on cost accessibility.
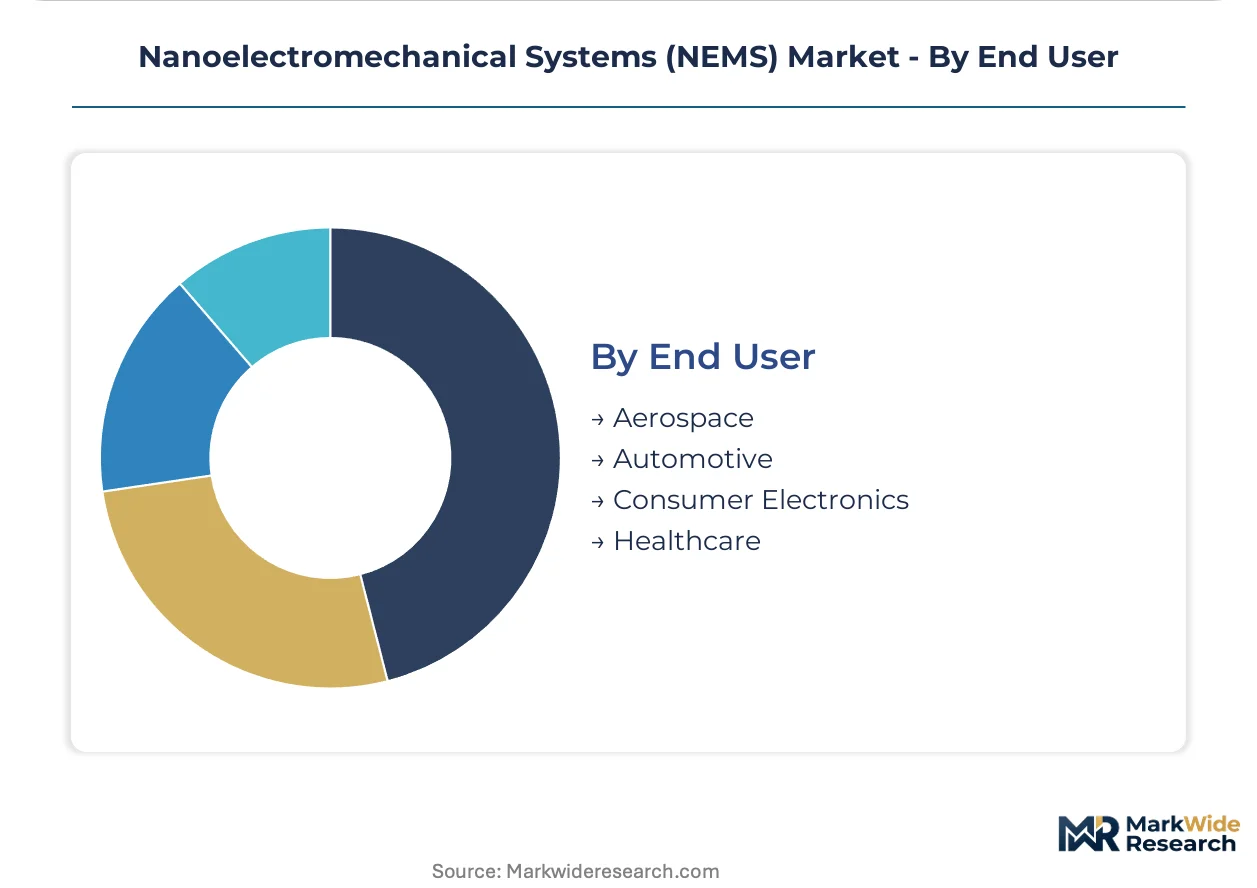
End User:
End-user segmentation separates qualification-intensive verticals from consumer-scale velocity.
- Automotive:Advanced driver-assistance systems certification opens fleet procurement channels previously reserved to MEMS incumbents. German KBA framework recognition accelerates nano-scale inertial sensor adoption.
- Healthcare:Implantable NEMS face extended toxicology precedent-building as FDA reviewers develop nano-specific evaluation standards. Point-of-care diagnostics concentrate demand in United States domestic supply chains.
- Aerospace:Defense procurement mandates domestic wafer provenance, fragmenting previously global supply bases.
- Consumer Electronics:Volume scale competes with automotive for foundry slot allocation.
Automotive absorbs the dominant share of qualified volume; Healthcare is expanding most quickly on diagnostic platform convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that of Germany by roughly 20-25 percent on qualified sensor volumes, reflecting NIH procurement preferences and KBA certification bottlenecks. This asymmetry reshapes where NEMS foundries allocate scarce 300mm wafer capacity. Domestic content requirements in defense and biomedical verticals further fragment regional procurement patterns.
United States
Federal nanotechnology initiatives and NIH SBIR funding channels concentrate point-of-care diagnostic demand in domestic supply chains. FDA premarket notification pathways for nano-scale medical devices compress development timelines for qualified suppliers. Boston-Cambridge and Silicon Valley clusters anchor biomedical NEMS prototyping, with foundry partnerships securing eighteen-month advance wafer allocations.
Germany
KBA automotive certification framework recognition opens fleet procurement channels for nano-scale inertial sensors previously reserved to MEMS incumbents. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force rapid reformulation of sensor coatings. Baden-Württemberg industrial sensor OEMs accelerate plasma-polymerized hexamethyldisiloxane barrier qualification to maintain IP67-rated product lines.
China
MIIT domestic substitution targets for semiconductor manufacturing equipment accelerate local NEMS fabrication infrastructure buildout. Dual carbon goals reshape foundry site selection toward renewable-powered industrial parks. Yangtze River Delta clusters concentrate CMOS-compatible resonator production for telecommunications timing synchronization modules.
Japan
METI funding for quantum sensing convergence drives optomechanical resonator integration with superconducting qubit readout platforms. JIS dimensional metrology standards calibrate cross-border equipment interoperability for aerospace tier-one suppliers. Nagoya-Tokyo industrial corridors host precision fabrication facilities serving femtotesla magnetometry applications.
India
PLI scheme production-linked incentives for semiconductor packaging attract NEMS module assembly investments targeting domestic medical device OEMs. BIS standards development for nano-enabled diagnostics lags FDA and EMA precedents by approximately 36 months. Karnataka and Telangana clusters concentrate foundry-adjacent packaging capacity for environmental monitoring sensor exports.
Nanoelectromechanical Systems (NEMS) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in captive wafer and instrumentation niches. Market structure tilts toward consolidated foundry access with fragmented fabless design competition. Three archetypes dominate: vertically integrated semiconductor houses with captive fabrication, precision instrumentation specialists with R&D-intensive positioning, and automotive-tier suppliers extending MEMS scale into nanoscale production. Competitive moves concentrate on foundry partnership exclusivity and dual-source qualification for defense-aerospace procurement.
Among diversified technology conglomerates, Texas Instruments Incorporated and IBM Corporation exemplify platform-scale positioning through captive supply chain control. STMicroelectronics occupies a position bridging automotive qualification frameworks with foundry-access leverage. Precision instrumentation specialists Bruker Corporation and Oxford Instruments plc represent the R&D-intensive archetype, anchoring scanning probe and metrology segments where dimensional traceability commands premium positioning. Robert Bosch GmbH exemplifies the automotive-tier extension model, leveraging proven MEMS manufacturing scale into nanoscale device production for advanced driver-assistance systems.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Bruker Corporation |
| IBM Corporation |
| Nanosurf AG |
| Oxford Instruments plc |
| STMicroelectronics |
| Agilent Technologies Inc. |
| Nanocyl SA |
| Robert Bosch GmbH |
| Others |
Supply & Pricing Matrix
ASML and JEOL e-beam lithography tool concentration in the Netherlands and Japan funnels margin pools toward qualified foundries with secured equipment allocations. Biomedical device OEMs absorbing femtogram-scale mass sensors face configured-to-order premiums that standard automotive sensor programs cannot command.
Pricing Analysis
Configured-to-order pricing for implantable diagnostics spreads 40-50 percent above standard environmental sensor SKUs. Three-tier pricing structure across automotive-qualified, industrial-grade, and economy variants anchors differentiation on KBA certification status and ISO 10993 biocompatibility completion. Cost compression in standard inertial sensor tiers is intensifying because CMOS-compatible piezoelectric processes collapse non-recurring engineering barriers for environmental startups. Automotive fleet procurement exhibits lowest price sensitivity; consumer electronics sensor buyers demand aggressive unit economics.
Supply Chain Analysis
Extended payment terms from United States biomedical OEMs now stretch to ninety days, forcing foundries to access supply-chain finance facilities for wafer start liquidity. Taiwan, South Korea, and the United States concentrate 300mm CMOS-compatible fabrication capacity. Helium-3 isotope feeds from Russian export quotas, aluminum nitride piezoelectric substrates, and specialized e-beam resist materials constitute critical input dependencies. Single-source vulnerability concentrates in sub-50nm lithography tooling. Distribution runs through direct-to-foundry procurement platforms displacing traditional distributor networks for sub-million-unit sensor programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration and recertification service contracts for implantable NEMS expand faster than hardware unit shipments as FDA nano-specific toxicology precedents lengthen replacement cycles. Recurring revenue from metrology validation services now captures margin pools that device sales alone cannot secure.
For Market Incumbents: Pre-empt emerging fabless competitors by locking exclusive 300mm wafer allocation agreements with Taiwan and South Korea foundries. Secure dual-source qualification for defense-aerospace procurement before domestic content mandates harden. Invest in ISO 10993 biocompatibility testing infrastructure to compress eighteen-to-twenty-four-month certification timelines for implantable platforms.
For New Entrants and Emerging Players: Point-of-care diagnostic modules for domestic Indian medical device OEMs represent the most penetrable entry point given PLI scheme packaging incentives and lagging BIS standards development. CMOS-compatible resonator architectures on existing 200mm lines enable cost-accessible environmental sensor production without leading-edge node competition. Direct-to-foundry procurement platforms provide go-to-market bypass of established distributor networks.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrumentation specialists with R&D-intensive positioning in scanning probe and dimensional metrology segments. Five-to-ten-year viability hinges on quantum sensing convergence capabilities and optomechanical resonator integration with superconducting qubit readout. Watch for FDA nano-specific guidance publication as inflection indicator for implantable NEMS reimbursement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Exclusivity | Locked 300mm wafer allocations secure capacity ahead of eighteen-month tape-out bidding cycles. |
| Dual-Source Qualification | Defense procurement mandates domestic wafer provenance fragment supply bases for aerospace tier-one contractors. |
| Biocompatibility Testing Infrastructure | ISO 10993 certification compression accelerates FDA premarket notification timelines for implantable platforms. |
| Quantum Sensing Convergence | Optomechanical resonator integration with superconducting qubit readout enables femtotesla magnetometry applications. |
| Direct-to-Foundry Procurement Platform | Online wafer start marketplaces displace distributor networks for sub-million-unit environmental sensor programs. |
Research Methodology
Cross-validation between primary interviews with foundry operations executives, biomedical device procurement managers, and automotive Tier 1 sensor qualification engineers anchors the qualitative findings. Secondary validation draws from FDA 510(k) premarket notification databases, NIH SBIR award records, KBA automotive certification registries, and ISO dimensional metrology standards documentation. Bottom-up segment sizing triangulates against top-down macroeconomic overlay models.
Calibration against historical CMOS foundry capacity utilization rates and biomedical device FDA clearance velocity patterns shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, application risk tolerance, technology maturity tier, and end-user qualification intensity. CAGRs derive from regression analysis of foundry equipment lead time trajectories and NIH funding channel expansion rates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, helium-3 isotope export quota enforcement, and federal nanotechnology initiative appropriations would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market