
 AI Computing Hardware Market | 2026-2036
AI Computing Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
AI Computing Hardware Market Outlook
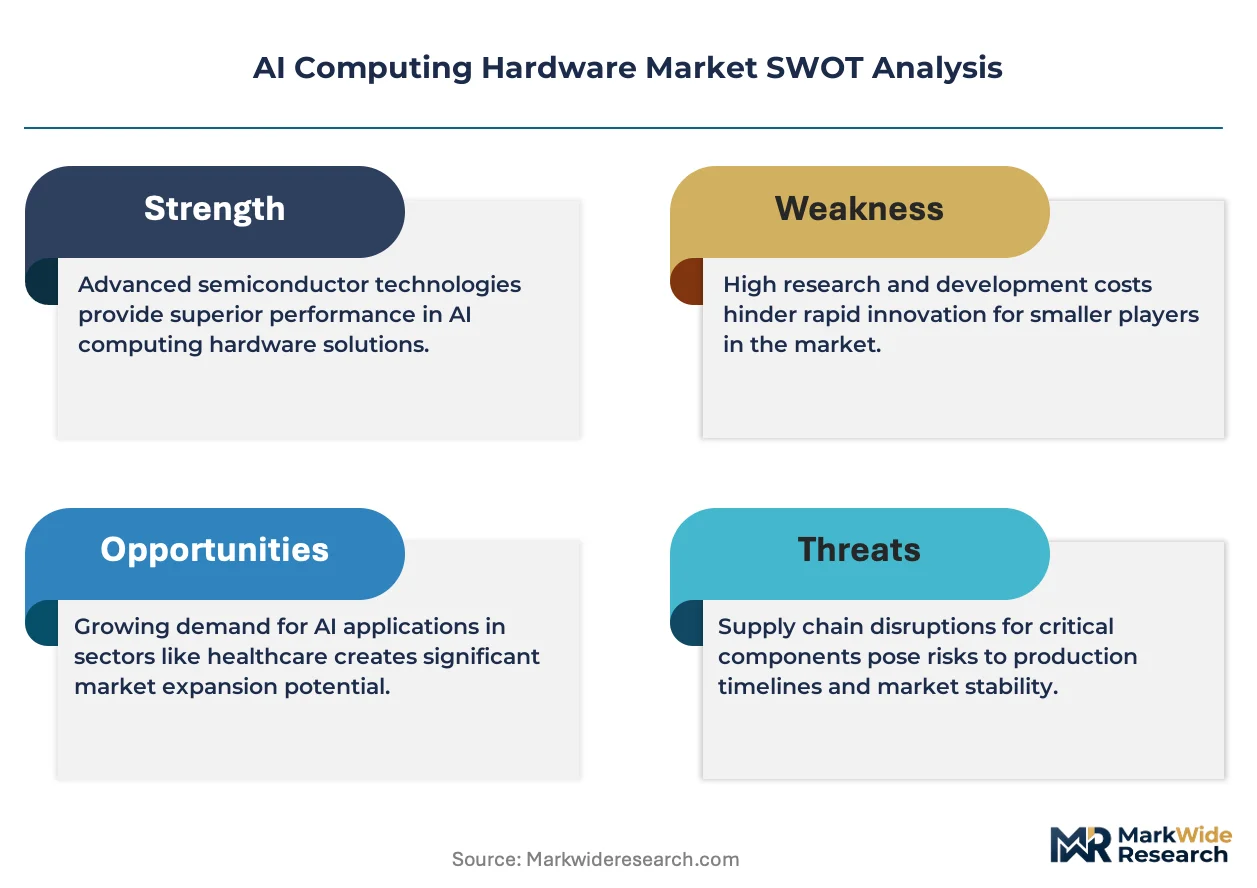
Modular server rack configurations with disaggregated GPU, memory, and networking components is realigning enterprise procurement patterns. NVIDIA Corporation leverages its CUDA software ecosystem to sustain attach rates across cloud and on-premise deployments. Intel Corporation competes through its Gaudi accelerator line and foundry ambitions. Advanced Micro Devices anchors its position via Instinct MI300 series traction in high-performance computing contracts.
AI computing hardware encompasses semiconductor devices and systems engineered to execute matrix-intensive workloads with specialized architectures such as tensor cores, high-bandwidth memory stacks, and chiplet-based packaging. These systems serve industrial and commercial purposes spanning autonomous training pipelines, real-time inference at edge nodes, and large-scale scientific simulation. GPUs dominate product type revenue due to their programmability across deep learning and data analytics applications, while ASICs capture efficiency-sensitive inference deployments in hyperscale facilities. Edge computing technology segments are expanding fastest as latency requirements harden for computer vision workloads in manufacturing and logistics.
The U.S. Department of Commerce export controls on advanced semiconductors, the EU AI Act risk-classification framework, and China's MIIT domestic substitution mandates are fragmenting supply chain access and redirecting capital toward regional fabrication ecosystems. Compliance with these overlapping regimes now shapes R&D location decisions, product feature segmentation, and customer eligibility screening. Stakeholders must monitor evolving cross-border licensing thresholds and align product roadmaps with jurisdiction-specific performance ceilings to preserve market access.
Market Dynamics
Hyperscale cloud operators are consolidating procurement power around GPU-heavy training clusters, while sovereign AI mandates in the European Union, Japan, and India fragment supply requirements and redirect capital toward regional fabrication ecosystems.
Growth Catalysts
- EU AI Act risk-classification framework:The EU AI Act mandates algorithmic transparency for high-risk applications, forcing enterprises to upgrade on-premise inference infrastructure and accelerating demand for compliant edge computing hardware.
- Autonomous vehicle training pipelines:Automotive OEMs in Germany, Japan, and the United States are scaling synthetic data generation and neural network training, driving procurement of high-memory GPU clusters for computer vision model development.
- Chiplet-based packaging:Advanced packaging technologies enable heterogeneous integration of logic and memory dies, reducing power consumption per training workload and lowering total cost of ownership for data center operators.
Market Restraints
- High-bandwidth memory supply concentration:HBM3 and HBM3e production concentrates among three Korean suppliers, creating input cost volatility and allocation constraints for accelerator card manufacturers.
- U.S. Department of Commerce export controls:Licensing thresholds on advanced semiconductors block shipment of highest-performance AI chips to specific end-markets, forcing product segmentation and feature limitation.
- Thermal density limitations:Rack-level power draw exceeding 100 kilowatts strains conventional air cooling, requiring liquid cooling retrofits that extend deployment timelines and raise facility capital requirements.
Strategic Opportunities
- India's domestic substitution mandates:The country's PLI scheme and MIIT-aligned import restrictions create captive demand for locally assembled training and inference systems, favoring joint ventures with domestic electronics manufacturers.
- Convergence of photonics and silicon:Co-packaged optical interconnects reduce data movement energy overhead, opening efficiency-sensitive deployments in hyperscale facilities where electrical signaling reaches physical limits.
- Saudi Arabia's sovereign compute buildout:NEOM and Riyadh data center zones require localized AI infrastructure for Arabic large language model training, creating demand for Arabic-optimized inference hardware.
Industry Challenges
- Compiler and kernel engineering talent scarcity:Optimization of tensor operations for novel accelerator architectures requires specialized expertise in CUDA alternatives and custom instruction sets, lengthening time-to-production for new hardware entrants.
- Multi-jurisdiction certification timelines:Simultaneous compliance with U.S. FCC electromagnetic interference standards, EU CE marking requirements, and China's GB certification protocols extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Computing Hardware Market |
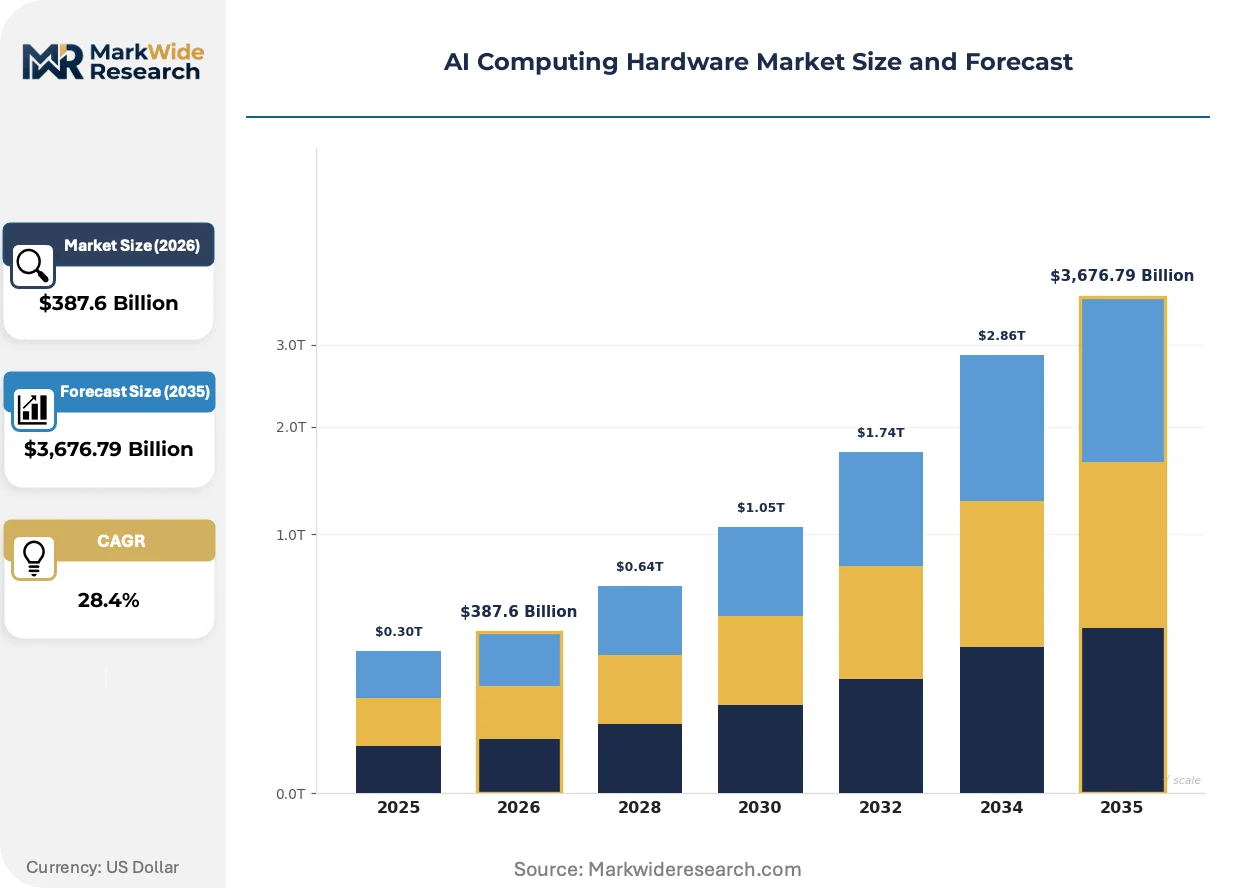
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $3,676.79 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPUs, TPUs, FPGAs, ASICs Technology: Cloud Computing, Edge Computing, Quantum Computing, Augmented Reality End User: Research Institutions, Enterprises, Startups, Government Agencies Application: Data Analytics, Deep Learning, Natural Language Processing, Computer Vision |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Advanced Micro Devices, Alphabet, IBM Corporation, Qualcomm Technologies, Apple, Huawei Technologies, AMD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Computing Hardware Market Strategic Shifts
Disaggregated server architectures and software-defined hardware allocation are compressing hardware refresh cycles while elevating the strategic importance of interconnect bandwidth and memory pooling technologies.
Chiplet-based packaging with 2.5D and 3D stacking is rewriting the cost-performance frontier for AI accelerators. Hyperscale operators in the United States and China are adopting these designs for training clusters exceeding 10,000 GPUs. The technology is rewriting procurement economics by enabling modular upgrades of memory and logic dies without full system replacement.
The EU AI Act's risk-tiered compliance obligations are reshaping hardware feature requirements. High-risk application deployers must maintain audit trails and explainability infrastructure, driving demand for on-chip telemetry and deterministic execution modes. European financial services and healthcare AI deployments are most affected, with hardware vendors adding secure enclave capabilities to satisfy conformity assessment procedures.
Buyers are consolidating procurement around long-term framework agreements with cloud operators rather than owning depreciating capital assets. Enterprise IT departments in manufacturing and logistics are shifting from on-premise GPU ownership to reserved instance contracts with guaranteed capacity. This pattern is most visible in Germany and Japan, where facility constraints and carbon accounting rules favor outsourced compute over data center construction.
AI Computing Hardware Market Segmentation
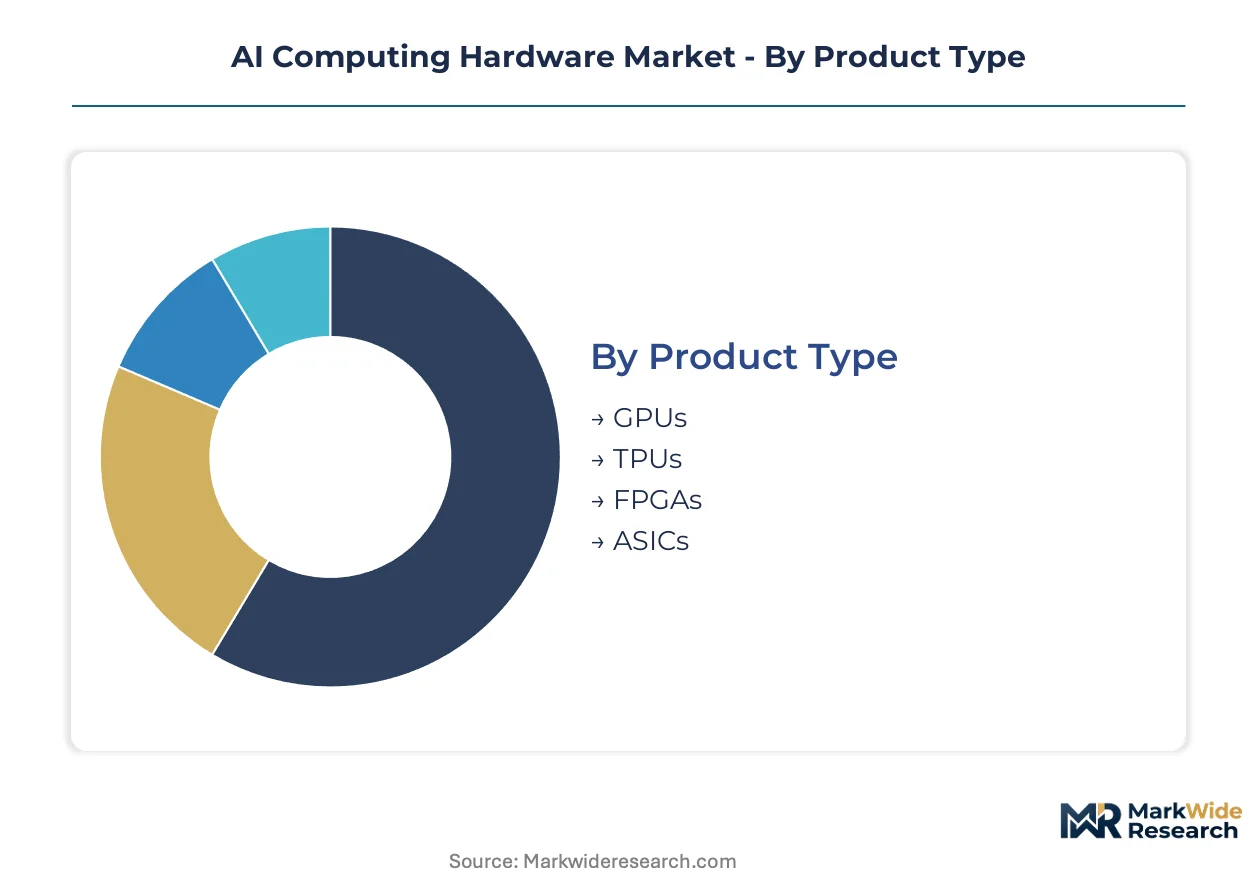
Segmentation in AI computing hardware reveals how architectural choices cascade through deployment economics. Product type and technology selections determine whether workloads run in centralized training clusters or distributed edge nodes.
Product Type:
Integration depth varies sharply: GPUs and TPUs dominate standalone data center deployments, while ASICs and FPGAs embed directly into application-specific systems.
- GPUs:Tensor core architectures with high-bandwidth memory stacks enable programmable acceleration across diverse neural network topologies. Hyperscale cloud operators in the United States and China concentrate procurement around NVIDIA and AMD data center cards for training workloads exceeding 10,000 units. Thermal density above 100 kilowatts per rack drives liquid cooling retrofits and extends facility deployment timelines.
- ASICs:Custom silicon designs optimize inference throughput per watt for fixed workloads such as recommendation engines and transformer-based language models. Google's TPU v5p deployments in Mountain View and Taiwan facility zones demonstrate the cost efficiency achievable at hyperscale volume. U.S. Department of Commerce export controls force product segmentation and feature limitation for certain destination markets.
- TPUs:Google's proprietary accelerator line serves internal cloud services and select enterprise customers through Google Cloud Platform.
- FPGAs:Reconfigurable logic fabrics from Xilinx and Intel adapt to evolving algorithm requirements in low-latency financial and telecommunications applications.
GPUs lead volumes today; ASICs are gaining share fastest in hyperscale inference.
Technology:
Cost tier separation distinguishes capital-intensive centralized infrastructure from operational-expense-optimized distributed deployments.
- Cloud Computing:Hyperscale data centers aggregate GPU clusters with pooled memory and networking resources, delivering training capacity through reserved instance contracts. Amazon Web Services, Microsoft Azure, and Google Cloud Platform compete on interconnect bandwidth and availability zone coverage.
- Edge Computing:Low-latency inference nodes deploy within manufacturing facilities, autonomous vehicles, and retail locations to process computer vision streams without round-trip data center transit. EU AI Act risk-classification requirements for high-risk applications accelerate compliant edge hardware procurement in Germany and France.
- Quantum Computing:IBM, Google, and IonQ systems target optimization and simulation workloads beyond classical computational reach.
- Augmented Reality:Head-mounted displays and spatial computing devices integrate specialized inference silicon for real-time scene understanding and gesture recognition.
Cloud Computing commands the largest capital allocation; Edge Computing shows the steepest expansion trajectory.
End User:
Application maturity separates established enterprise adopters from experimental research deployments.
- Enterprises:Fortune 500 technology, financial services, and healthcare organizations procure hybrid infrastructure combining on-premise GPU clusters with cloud burst capacity. Germany's automotive OEMs and Japan's electronics manufacturers lead private training cluster buildouts for proprietary model development.
- Government Agencies:National laboratories and defense departments fund exascale system procurement with domestic content requirements. India's PLI scheme and domestic substitution mandates redirect capital toward locally assembled systems.
- Research Institutions:Universities and national science foundations access federally subsidized supercomputing allocations.
- Startups:Venture-backed companies rely predominantly on cloud credits and spot instance pricing for model training.
Enterprises dominate current procurement volumes; Government Agencies are expanding fastest through sovereign AI initiatives.
Application:
Compute intensity varies by algorithm class, with generative workloads demanding distinct memory and interconnect configurations.
- Deep Learning:Multi-layer neural network training requires dense GPU clustering with high-bandwidth interconnects between accelerators. Saudi Arabia's NEOM data center zones and Riyadh facilities procure localized infrastructure for Arabic large language model development.
- Natural Language Processing:Transformer architectures with billions of parameters drive demand for high-memory GPU configurations and specialized inference chips. China's MIIT domestic substitution mandates redirect supply chain access toward local fabrication ecosystems.
- Computer Vision:Convolutional and vision transformer models serve autonomous vehicle perception, medical imaging, and quality inspection systems.
- Data Analytics:Traditional machine learning and statistical workloads run on commodity infrastructure with accelerator augmentation.
Deep Learning absorbs the largest hardware allocation; Natural Language Processing is climbing the fastest as generative AI scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The AI computing hardware industry traces its modern scale to Silicon Valley's GPU-centric data center buildouts during the 2010s deep learning revolution. That foundation now fragments across competing national technology strategies. Sovereign compute mandates and export control regimes redirect capital flows toward regional fabrication ecosystems.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center zones consolidate procurement around GPU-heavy training clusters exceeding 10,000 units. The U.S. Department of Commerce export controls on advanced semiconductors block shipment of highest-performance AI chips to specific end-markets. Austin, Texas and Phoenix, Arizona host emerging domestic packaging and assembly facilities as supply chain localization accelerates.
China
Domestic cloud providers and national laboratories scale synthetic data generation pipelines for computer vision and large language model development. MIIT domestic substitution mandates redirect capital toward local fabrication ecosystems and restrict import of foreign training hardware. The Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate domestic accelerator design houses and advanced packaging facilities.
Germany
Automotive OEMs in Stuttgart and Munich scale neural network training for autonomous vehicle perception systems. The EU AI Act risk-classification framework forces enterprises to upgrade on-premise inference infrastructure with algorithmic transparency capabilities. Frankfurt's data center zone attracts GPU cluster deployments serving financial services AI workloads under strict conformity assessment procedures.
Japan
Electronics manufacturers and robotics developers procure high-memory configurations for industrial automation and quality inspection systems. METI funding programs support domestic semiconductor packaging capacity expansion to reduce reliance on Korean HBM suppliers. The Kansai region around Osaka hosts advanced substrate manufacturing for chiplet-based AI accelerators.
Saudi Arabia
NEOM and Riyadh data center zones require localized AI infrastructure for Arabic large language model training and sovereign compute independence. The country's national technology investment fund directs capital toward domestic assembly of training and inference systems. The Kingdom's western region hosts specialized facilities for Arabic-optimized inference hardware deployment.
AI Computing Hardware Market Competitive Environment
The competitive structure tilts toward integrated hardware-software ecosystems with high switching costs. Three to five vertically integrated specialists control the premium accelerator tier, while a fragmented base of regional assemblers serves sovereign compute mandates. Dominant archetypes include CUDA-ecosystem incumbents, foundry-integrated challengers, and government-backed domestic champions. Competitive moves concentrate on strategic partnerships with cloud operators and geographic licensing carve-outs to preserve market access under export controls.
Among U.S.-based semiconductor designers, NVIDIA Corporation, Intel Corporation, and Advanced Micro Devices occupy distinct positioning vectors. NVIDIA Corporation exemplifies the software-ecosystem incumbent archetype through its CUDA platform attach rates. Intel Corporation represents the foundry-integrated challenger pursuing vertical control over accelerator design and manufacturing. Advanced Micro Devices anchors the high-performance computing specialist tier through its data center GPU traction. Each occupies a differentiated lane within hyperscale procurement frameworks.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Advanced Micro Devices |
| Alphabet |
| IBM Corporation |
| Qualcomm Technologies |
| Apple |
| Huawei Technologies |
| AMD |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud operators in the United States and China consolidate procurement around GPU-heavy training clusters exceeding 10,000 units, anchoring contract-based long-term offtake agreements with volume-scaled pricing tiers. This buyer concentration forces hardware vendors into framework negotiations where interconnect bandwidth and memory pooling capabilities determine premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NVIDIA's H100-class configurations from AMD's MI300 series and domestic Chinese alternatives. Price differentiation hinges on CUDA ecosystem attach rates and high-bandwidth memory stack density. Cost compression in the standard tier intensifies as Gaudi accelerators and custom ASICs erode GPU incumbency. Startups and research institutions exhibit highest price sensitivity; sovereign cloud operators in Saudi Arabia and India demonstrate lowest.
Supply Chain Analysis
Specialized packaging engineers in Taiwan, South Korea, and Japan constrain advanced substrate capacity for chiplet-based AI accelerators. The supply chain draws from HBM3 memory stacks, CoWoS interposers, and EUV photoresist chemicals. Single-source vulnerability concentrates in Korean HBM suppliers SK Hynix and Samsung. Distribution runs through direct hyperscale procurement teams rather than traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework compounds hardware demand by mandating on-premise inference infrastructure with algorithmic transparency capabilities. This regulatory milestone redirects enterprise procurement toward compliant edge computing deployments.
For Market Incumbents:Lock in CUDA ecosystem dominance through compiler toolchain investments that raise switching costs for cloud operators evaluating AMD or Intel alternatives. Add secure enclave capabilities to satisfy EU AI Act conformity assessment procedures. Foundry-integrated challengers threaten margin compression in the standard tier.
For New Entrants and Emerging Players:Domestic assemblers in India and Saudi Arabia represent the most penetrable channel partner type for joint ventures meeting PLI scheme and sovereign compute mandates. Target Arabic-optimized inference hardware for NEOM data center zones. License RISC-V or custom instruction set architectures to bypass CUDA dependency.
For Investors and Strategic Acquirers:Hyperscale cloud operators are the most active acquirer in this space, snapping up chiplet packaging specialists and optical interconnect startups. Long-term viability favors vertically integrated players controlling both accelerator design and advanced substrate manufacturing. Watch for U.S. Department of Commerce licensing threshold adjustments as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-packaged Optical Interconnect Integration | Reduces data movement energy overhead in hyperscale facilities where electrical signaling reaches physical limits. |
| Secure Enclave Hardware Development | Satisfies EU AI Act conformity assessment procedures for high-risk financial services and healthcare AI deployments. |
| Domestic Packaging Joint Venture | Aligns with India's PLI scheme and Saudi Arabia's sovereign compute buildout for localized assembly requirements. |
| Liquid Cooling Infrastructure Partnership | Addresses thermal density limitations exceeding 100 kilowatts per rack in GPU-heavy training clusters. |
| Compiler Toolchain Acquisition | Accelerates time-to-production for novel accelerator architectures facing CUDA ecosystem lock-in. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center procurement officers, semiconductor packaging engineers, cloud platform architects, and regulatory compliance leads with secondary validation against SEC hyperscaler capex disclosures, foundry utilization reports, and EU AI Act implementation guidance. Bottom-up cluster deployment counts and top-down wafer supply estimates were triangulated.
Comparable-period anchoring tied projection models to historical GPU shipment trajectories and cloud infrastructure investment cycles across the analysis window. Segmentation dimensions included product type, deployment technology, end-user archetype, and application intensity. CAGRs were derived from accelerator attach rate assumptions and sovereign AI capital allocation patterns, with inputs from HBM supply constraints and export control licensing thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to U.S. Department of Commerce licensing adjustments, EU AI Act enforcement granularity, and Korean HBM supplier allocation decisions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Global Embedded Systems Market