
 Embedded Computing Systems Market | 2026-2036
Embedded Computing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Computing Systems Market Foresight
The EU Cyber Resilience Act is pivoting compliance costs upward for any supplier targeting European automotive or medical device accounts. Intel Corporation leverages its foundry-scale manufacturing to sustain pricing power across high-reliability system-on-chip designs. NXP Semiconductors anchors its position through deep automotive safety processor portfolios that dominate functional safety segments. Texas Instruments competes by controlling analog-digital integration at the board level, a capability that extends its reach into industrial automation sockets.
Embedded computing systems integrate microprocessors, memory subsystems, and dedicated I/O interfaces onto single-board or module-level architectures, typically operating within constrained thermal envelopes and real-time deterministic response windows. Their primary purpose is to execute dedicated control, signal processing, or communication tasks within larger electromechanical systems without requiring general-purpose computing resources. Microcontrollers retain the largest volume share across automotive body electronics and industrial motor controllers, while system on chips captures expanding margin pools in ADAS and infotainment clusters where integration density reduces bill-of-material complexity. Field programmable gate arrays occupy a specialized niche in medical imaging and aerospace prototyping where reconfigurable logic outperforms fixed-function silicon.
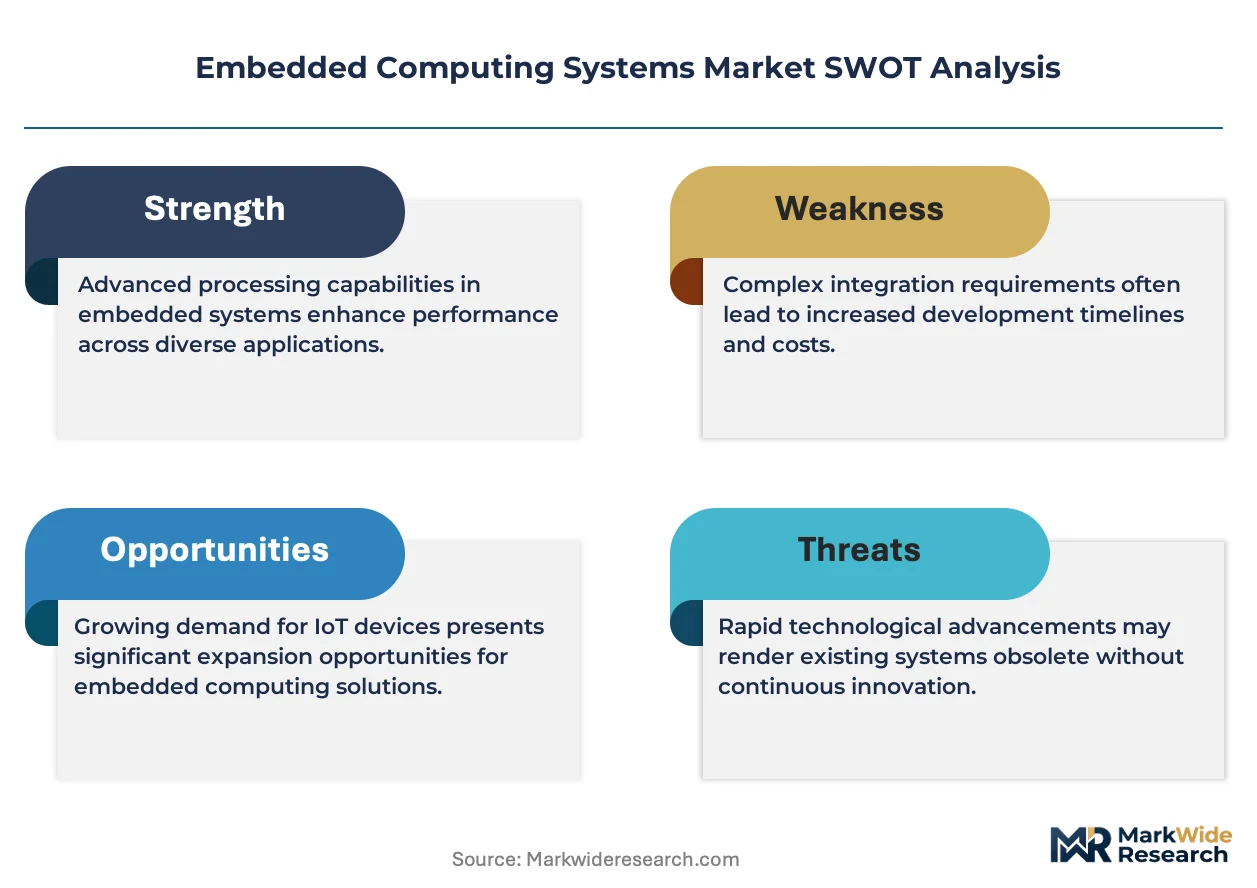
The FDA enforces software validation protocols under 21 CFR Part 820 for embedded controllers deployed in medical devices, while the EPA's emissions testing requirements drive automotive OEMs toward certified embedded powertrain control units. ISO 26262 functional safety standards and the EU Cyber Resilience Act collectively raise the engineering barrier for new entrants, privileging incumbents with established certification track records. Stakeholders must weigh whether to absorb compliance costs in-house or cede market access to certified subsystem suppliers.
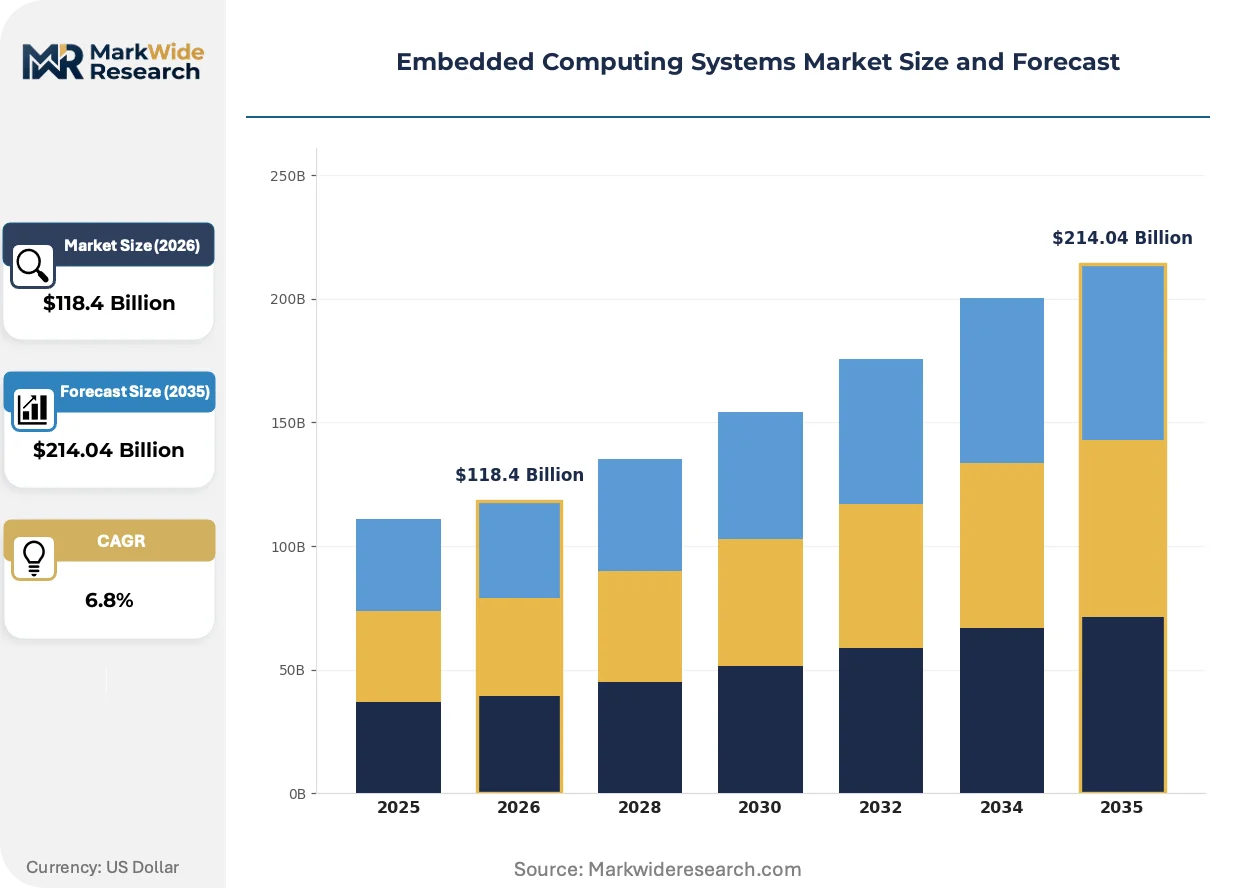
Market Dynamics
Automotive electrification and functional safety mandates are compressing development cycles while fragmenting supplier tiers, forcing embedded computing vendors to absorb certification costs or cede socket access to certified subsystem integrators.
Growth Catalysts
- ISO 26262 functional safety standards:Automotive OEMs in Germany and Japan now mandate ASIL-D certified processors for brake-by-wire and steer-by-wire systems, expanding addressable silicon content per vehicle.
- Edge AI inference workloads:Factory automation lines in the United States are deploying vision-guided robotics requiring deterministic latency below 10 milliseconds, pulling GPU-NPU hybrid architectures into industrial controllers.
- EU Cyber Resilience Act:Network-connected medical devices and automotive ECUs sold into Europe must demonstrate vulnerability management processes, creating certified supplier scarcity that benefits incumbents with established security engineering teams.
Market Restraints
- Advanced node wafer costs:Sub-7nm mask sets and EUV lithography cycles inflate NRE charges for automotive-grade SoCs, squeezing mid-tier MCU suppliers without foundry-scale purchasing power.
- Concentrated advanced packaging capacity:Taiwan-based OSATs control the majority of fan-out wafer-level packaging for high-density automotive modules, exposing supply continuity to single-geo concentration risk.
- Legacy 8-inch fab depreciation:Analog-mixed signal microcontrollers for body electronics face input cost pressure as foundries accelerate 12-inch transitions, stranding 110nm-180nm process commitments.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing are attracting embedded module assembly investments to serve domestic textile and pharmaceutical machinery OEMs.
- RISC-V open ISA adoption:Aerospace prototyping and academic research clusters in Switzerland and Germany are licensing royalty-free cores, eroding ARM's historical dominance in safety-critical segments.
- Digital twin integration:Automotive Tier-1s in Japan are contracting embedded suppliers for hardware-in-the-loop simulation environments that compress validation cycles before physical prototyping.
Industry Challenges
- Functional safety engineering scarcity:ASIL-certified firmware architects command premium compensation in Stuttgart, Detroit, and Nagoya, constraining supplier scaling velocity.
- Multi-standard compliance stacking:Medical device embedded controllers must simultaneously satisfy FDA 21 CFR Part 820 software validation and EU MDR cybersecurity annexes, extending certification timelines.
- Heterogeneous integration complexity:ADAS domain controllers require thermal co-design across discrete GPUs, safety MCUs, and power management ICs, fragmenting traditional single-silicon procurement relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Computing Systems Market |
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $214.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Digital Signal Processors, Field Programmable Gate Arrays, System on Chips Application: Automotive, Consumer Electronics, Industrial Automation, Medical Devices Connectivity: Ethernet, Wi-Fi, Bluetooth, Zigbee End User: OEMs, System Integrators, Research Institutions, Telecom Companies |
| Companies Covered | Intel Corporation, NXP Semiconductors, Texas Instruments, Renesas Electronics Corporation, STMicroelectronics, Infineon Technologies AG, Qualcomm Incorporated, Microchip Technology, Advantech Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Computing Systems Market Shifts & Advancements
Deterministic edge computing architectures are fragmenting traditional microcontroller categories as automotive and industrial buyers prioritize latency guarantees over raw throughput metrics.
Arm Cortex-R82 and emerging RISC-V real-time cores are overtaking legacy 32-bit automotive MCUs in powertrain domain controllers. Tier-1 suppliers in Germany and Japan are qualifying these architectures for motor control and battery management systems. This transition is overtaking established supplier relationships as OEMs requalify software stacks around new ISA ecosystems.
The EU Cyber Resilience Act mandates automated vulnerability disclosure and patch delivery for network-connected embedded devices. Medical device manufacturers must redesign OTA update architectures to satisfy EMA-aligned cybersecurity expectations. European automotive ECU suppliers are absorbing the steepest compliance engineering costs, accelerating consolidation toward subsystem vendors with dedicated security operations centers.
Subscription-based firmware licensing is displacing perpetual silicon-plus-software bundles in industrial automation procurement. German machine builders are contracting embedded runtime licenses through automation distributors rather than direct semiconductor purchasing. This model shift concentrates margin capture with platform vendors possessing cloud-connected device management infrastructure.
Embedded Computing Systems Market Segmentation
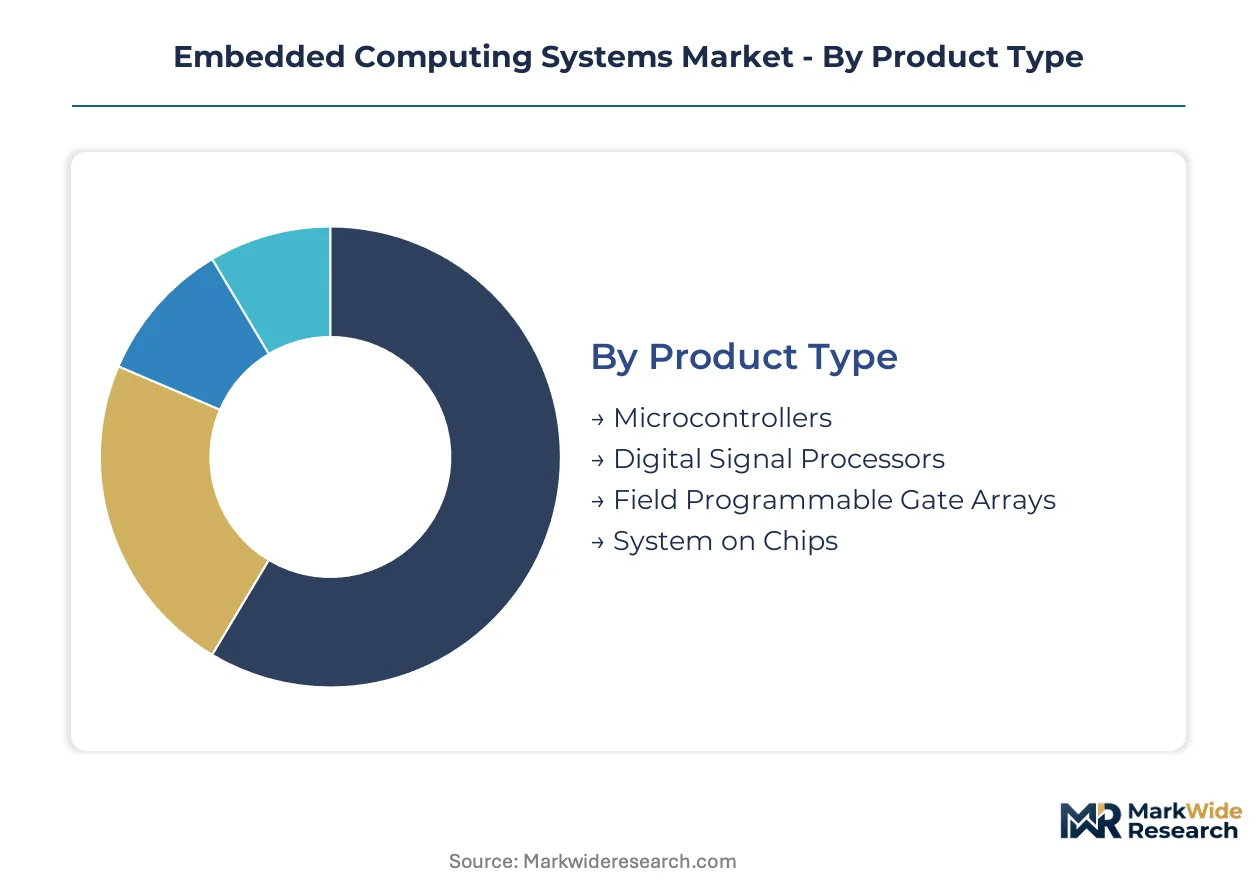
Embedded computing systems fragment across multiple technical and commercial dimensions. Product architecture determines thermal envelope and real-time capability. Application context dictates certification burden and margin structure.
Product Type:
Volume concentration sits with legacy 8-bit and 32-bit microcontrollers. Premium expansion concentrates in heterogeneous SoCs integrating safety islands and AI accelerators.
- Microcontrollers:These integrate CPU core, volatile and non-volatile memory, and programmable I/O peripherals onto monolithic dies. Automotive body electronics in Germany and Japan consume the highest unit volumes, driven by centralized zonal E/E architectures replacing distributed ECUs.
- System on Chips:SoCs combine application processors, GPU clusters, dedicated neural processing units, and functional safety cores on single substrates. ADAS domain controllers in Stuttgart and Detroit pull these devices, constrained by ISO 26262 ASIL-D certification timelines and sub-7nm wafer allocation.
- Digital Signal Processors:Optimized arithmetic units execute multiply-accumulate operations for real-time filtering and transform calculations. Motor control inverters and active noise cancellation systems.
- Field Programmable Gate Arrays:Reconfigurable logic arrays enable hardware-level algorithm customization without mask set costs. Medical imaging equipment prototyping in Swiss research clusters.
Mature deployment sits with Microcontrollers. Newer deployment is concentrated in System on Chips.
Application:
Automotive electrification is concentrating silicon content fastest. Medical device certification timelines extend procurement cycles and favor incumbent suppliers.
- Automotive:Powertrain electrification and chassis-by-wire systems are expanding semiconductor value per vehicle. Battery management systems and inverter controls in Germany, Japan, and the United States absorb the highest microcontroller and SoC volumes.
- Industrial Automation:Vision-guided robotics and deterministic motion controllers require sub-10 millisecond latency guarantees. Factory floors in the United States are deploying GPU-NPU hybrid architectures at the edge.
- Medical Devices:Implantable cardioverter-defibrillators and infusion pumps must satisfy FDA 21 CFR Part 820 software validation protocols. EU MDR cybersecurity annexes add compliance layering.
- Consumer Electronics:Smart home hubs and wearable devices prioritize cost-optimized connectivity integration over functional safety certification.
Procurement scale clusters with Automotive. Certification complexity peaks with Medical Devices.
Connectivity:
Wired deterministic protocols dominate safety-critical sockets. Wireless integration is expanding fastest in building automation and asset tracking.
- Ethernet:Time-sensitive networking extensions deliver sub-microsecond synchronization for industrial motion control. Automotive backbone networks in Germany are migrating to multi-gigabit Ethernet from legacy CAN-FD.
- Wi-Fi:Wi-Fi 6 and emerging Wi-Fi 7 standards support high-throughput medical imaging transmission and over-the-air firmware updates. Hospital networks in the United States.
- Bluetooth:Low-energy variants enable short-range pairing for wearable health monitors and hearing aids.
- Zigbee:Mesh networking protocols optimize for ultra-low power consumption in building automation sensors and smart lighting controllers.
Established sockets favor Ethernet. Wireless expansion is climbing the fastest in facility management and remote patient monitoring.
End User:
Direct OEM procurement is consolidating around certified subsystem suppliers. Research institutions are driving early RISC-V qualification for safety-critical applications.
- OEMs:Automotive and medical device manufacturers are internalizing embedded controller specification while outsourcing physical manufacturing to certified foundry partners. German and Japanese OEMs dominate silicon procurement volume.
- System Integrators:Industrial automation specialists bundle embedded modules with mechanical subsystems and application software. German machine builders are shifting toward subscription-based firmware licensing.
- Research Institutions:Academic and government laboratories in Switzerland and Germany are qualifying open-source RISC-V cores for aerospace prototyping.
- Telecom Companies:Base station and edge computing infrastructure vendors require extended temperature range operation and hardware security module integration.
Volume procurement concentrates with OEMs. Architectural experimentation sits with Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Penang, Shenzhen, and Dresden concentrate embedded module assembly capacity through tax abatement schemes and duty-free component import regimes. These zones anchor regional supply networks for automotive and industrial automation OEMs.
United States
Detroit automotive OEMs and Austin semiconductor design clusters drive microcontroller procurement for powertrain electrification. The EPA enforces emissions testing protocols that mandate certified embedded powertrain control units. Factory floors in Michigan and Ohio deploy vision-guided robotics requiring sub-10 millisecond deterministic latency.
Germany
Stuttgart and Munich anchor battery management system development for electric vehicle platforms. The KBA enforces type approval standards that incorporate ISO 26262 functional safety mandates. Industrial automation OEMs in Baden-Württemberg contract embedded suppliers for hardware-in-the-loop simulation environments.
Japan
Nagoya and Tokyo metropolitan areas concentrate steer-by-wire and brake-by-wire system qualification. METI promotes domestic semiconductor production through subsidies for 12-inch fab capacity expansion. Tier-1 suppliers in Aichi Prefecture requalify software stacks around Arm Cortex-R82 and emerging RISC-V real-time cores.
China
Shenzhen and Shanghai special economic zones host embedded module assembly for consumer electronics and automotive applications. MIIT enforces GB standards for network-connected device security that parallel EU Cyber Resilience Act requirements. Yangtze River Delta foundries accelerate 12-inch transitions that strand 110nm-180nm legacy process commitments.
India
Bengaluru and Pune industrial corridors attract embedded controller investments under the PLI scheme for electronics manufacturing. The CEA regulates power electronics standards for grid-connected industrial equipment. Textile and pharmaceutical machinery OEMs in Gujarat and Maharashtra source locally assembled embedded modules.
Embedded Computing Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-intensive automotive and medical device sockets. The vendor base stratifies into three tiers: foundry-scale integrated device manufacturers, fabless safety processor architects, and industrial automation module integrators. Strategic moves concentrate on M&A for ASIL-certified firmware teams and strategic partnerships for advanced packaging capacity.
Within the integrated device manufacturer tier, Intel Corporation, NXP Semiconductors, and Texas Instruments occupy positions defined by manufacturing scale and analog-digital integration depth. These entities exemplify archetypes spanning foundry-scale production, automotive safety processor portfolios, and board-level mixed-signal control. Their competitive positioning reflects certification track records under FDA, EPA, and EU regulatory frameworks rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Intel Corporation |
| NXP Semiconductors |
| Texas Instruments |
| Renesas Electronics Corporation |
| STMicroelectronics |
| Infineon Technologies AG |
| Qualcomm Incorporated |
| Microchip Technology |
| Advantech Co. Ltd. |
| Others |
Supply & Pricing Matrix
EUV lithography cycle costs for sub-7nm automotive-grade SoCs cascade through three distinct pricing tiers, with ASIL-D certified processors commanding premium positioning against uncertified commodity microcontrollers.
Pricing Analysis
Short lead-time premiums for automotive-grade silicon separate expedited procurement contracts from standard quarterly allocation agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 certification grade and foundry-scale purchasing power. Cost compression in mid-tier MCU segments is intensifying because 12-inch fab transitions strand 110nm-180nm legacy process commitments. Industrial automation OEMs in Germany exhibit the highest price sensitivity due to subscription-based firmware licensing displacement, while medical device manufacturers absorb premium pricing for FDA-validated supply security.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese automotive OEMs require qualified secondary suppliers for every critical embedded controller socket, fragmenting procurement relationships across redundant vendor pools. Taiwan, South Korea, and the United States anchor advanced node wafer fabrication and fan-out wafer-level packaging capacity. Raw material dependencies span high-purity silicon wafers, rare earth elements for power management ICs, and specialized epoxy molding compounds. Single-source vulnerability concentrates in Taiwan-based OSATs controlling advanced packaging for high-density automotive modules. Distribution runs through certified subsystem integrators rather than direct semiconductor procurement for Tier-1 automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded computing market sits in a processor architecture transition phase, with Arm Cortex-R82 and RISC-V real-time cores displacing legacy 32-bit automotive MCUs across powertrain domain controllers.
For Market Incumbents: Cement ASIL-certified firmware engineering capabilities through targeted acquisition of Stuttgart, Detroit, and Nagoya talent pools before compensation premiums escalate further. Expand captive advanced packaging capacity in Germany and Japan to reduce Taiwan OSAT concentration exposure. ISO 26262 certification track records constitute the critical defensive moat against RISC-V ecosystem challengers. For New Entrants and Emerging Players: Open-source RISC-V core licensing offers a technology-first wedge into aerospace prototyping and academic research clusters in Switzerland and Germany where ARM royalty structures face scrutiny. White-space concentration sits with India industrial automation under PLI scheme incentives, particularly textile and pharmaceutical machinery OEMs in Gujarat and Maharashtra. Channel partnership with German automation distributors enables subscription-based firmware revenue capture without direct OEM sales infrastructure. For Investors and Strategic Acquirers: METI subsidy announcements for 12-inch domestic fab expansion are the leading indicator that Japanese embedded controller supply security is becoming a sovereign priority with acquisition premium implications. Five-to-ten year viability hinges on functional safety engineering scarcity resolution rather than raw manufacturing scale. Target acquisition archetype: mid-tier MCU suppliers with established automotive qualification records but lacking foundry-scale purchasing power. Watch for EU Cyber Resilience Act enforcement actions as the inflection signal for certified supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Opens brake-by-wire and steer-by-wire procurement channels at Stuttgart and Nagoya OEMs. |
| RISC-V Core Licensing Program | Erodes ARM royalty dominance in Swiss aerospace and German academic safety-critical research clusters. |
| Advanced Packaging Capacity Expansion | Reduces Taiwan OSAT concentration risk for automotive domain controller supply continuity. |
| Subscription Firmware Platform Launch | Captures recurring revenue from German machine builders shifting from perpetual silicon bundles. |
| Hardware-in-the-Loop Simulation Partnership | Compresses validation cycles for Japanese Tier-1s requalifying software stacks around new ISA ecosystems. |
Research Methodology
Multi-period observation of automotive microcontroller procurement volumes, industrial automation capex cycles, and medical device FDA submission rates anchored the trend analysis, supplemented by interviews with embedded systems architects, Tier-1 supplier procurement directors, semiconductor foundry account managers, and functional safety certification auditors. Secondary validation drew from SEC semiconductor filings, EPA emissions testing protocol documentation, EU Cyber Resilience Act implementation guidance, and ISO 26262 certification registry data. Bottom-up product-level shipment estimates triangulated against top-down OEM production forecasts.
Segment-weighting across product architecture, application context, connectivity protocol, and end-user procurement model structured the analytical framework across the analysis window. Automotive electrification content-per-vehicle trajectories, industrial edge AI inference workload penetration rates, and medical device cybersecurity compliance layering informed category-specific growth assumptions. CAGRs were derived from fitted trend extrapolation with regulatory inflection adjustments.
Several conditions sit outside the modeled scope, including sovereign subsidy program cancellations, foundry fire or earthquake disruption scenarios, and abrupt ISA ecosystem abandonment by major OEMs. Forecasts reflect stated assumptions regarding ISO 26262 certification timeline stability and EU Cyber Resilience Act enforcement intensity. Deviation in Taiwan Strait logistics continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Hi-Fi System Market