
 Electronic-Nose Market | 2026-2036
Electronic-Nose Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic-Nose Market Intelligence
Modular sensor arrays bundled with cloud analytics platforms is realigning buyer choice toward subscription-based configurations. Aryballe Technologies leverages silicon photonics integration to sustain technology leadership in compact form factors. Alpha MOS anchors European demand through specialized olfaction measurement systems for food and beverage clients. Owlstone Medical competes in clinical breath analysis by extending its FAIMS platform into disease screening workflows.
An electronic-nose instrument detects volatile organic compounds through an array of chemical sensors coupled with pattern recognition algorithms, typically achieving detection thresholds in parts-per-billion ranges for industrial quality assurance. Gas sensors occupy the dominant technology position due to mature manufacturing and broad compatibility with humidity-variable environments. Portable configurations represent the fastest-growing product category as field-deployable units replace laboratory-bound systems in environmental monitoring and agricultural inspection routines.
FDA oversight of diagnostic breath analysis devices and ISO 17025 accreditation requirements for analytical laboratories are tightening performance documentation standards across healthcare and industrial segments. REACH chemical registration rules in Europe restrict certain sensor coating materials, pushing manufacturers toward biocompatible polymer alternatives. Stakeholders must monitor evolving regulatory recognition of electronic-nose data as admissible evidence in food safety litigation and customs inspection protocols.
Market Dynamics
Modular sensor arrays paired with cloud analytics platforms are restructuring buyer-supplier relationships toward recurring-revenue configurations, forcing hardware manufacturers to build software capabilities or partner with analytics providers.
Growth Catalysts
- ISO 17025 laboratory accreditation:Analytical laboratories in Germany and France pursue electronic-nose systems to meet tightening performance documentation standards for food safety testing and customs inspection protocols.
- Non-destructive food quality testing:Food and beverage manufacturers deploy portable electronic-nose units to replace destructive sampling methods, reducing waste while accelerating batch release decisions.
- Silicon photonics integration:Miniaturization of optical sensor components enables compact form factors suitable for point-of-care clinical breath analysis and field agricultural inspection.
Market Restraints
- Specialized polymer coating supply:REACH chemical registration restrictions in Europe limit availability of certain sensor coating materials, forcing reformulation cycles and qualification delays.
- Humidity-variable environment calibration:Gas sensors require extensive recalibration protocols for high-moisture industrial settings, elevating total cost of ownership relative to alternative detection methods.
- Pattern recognition algorithm development:Shortage of data scientists with olfaction signal processing expertise constrains customization velocity for niche industrial applications.
Strategic Opportunities
- Disease screening workflow integration:Clinical breath analysis platforms can extend into early-stage metabolic disorder detection, leveraging existing FAIMS infrastructure for non-invasive patient monitoring.
- Environmental monitoring field deployment:Portable configurations penetrate agricultural inspection routines in Spain and Italy, replacing laboratory-bound systems for soil health and crop maturity assessment.
- Subscription-based analytics bundling:Sensor hardware vendors capture recurring revenue through cloud-based pattern recognition services, shifting buyer relationships from capital expenditure to operational expenditure models.
Industry Challenges
- FDA diagnostic device clearance timelines:Breath analysis manufacturers face extended validation periods for disease-screening claims, compressing competitive windows and elevating regulatory compliance costs.
- Legacy quality control system integration:Food manufacturers struggle to interface electronic-nose data streams with existing manufacturing execution systems, requiring custom middleware development.
- Cross-sensor standardization delays:Absence of universal volatile organic compound reference libraries forces buyers to build proprietary training datasets, slowing deployment across multiple production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic-Nose Market |
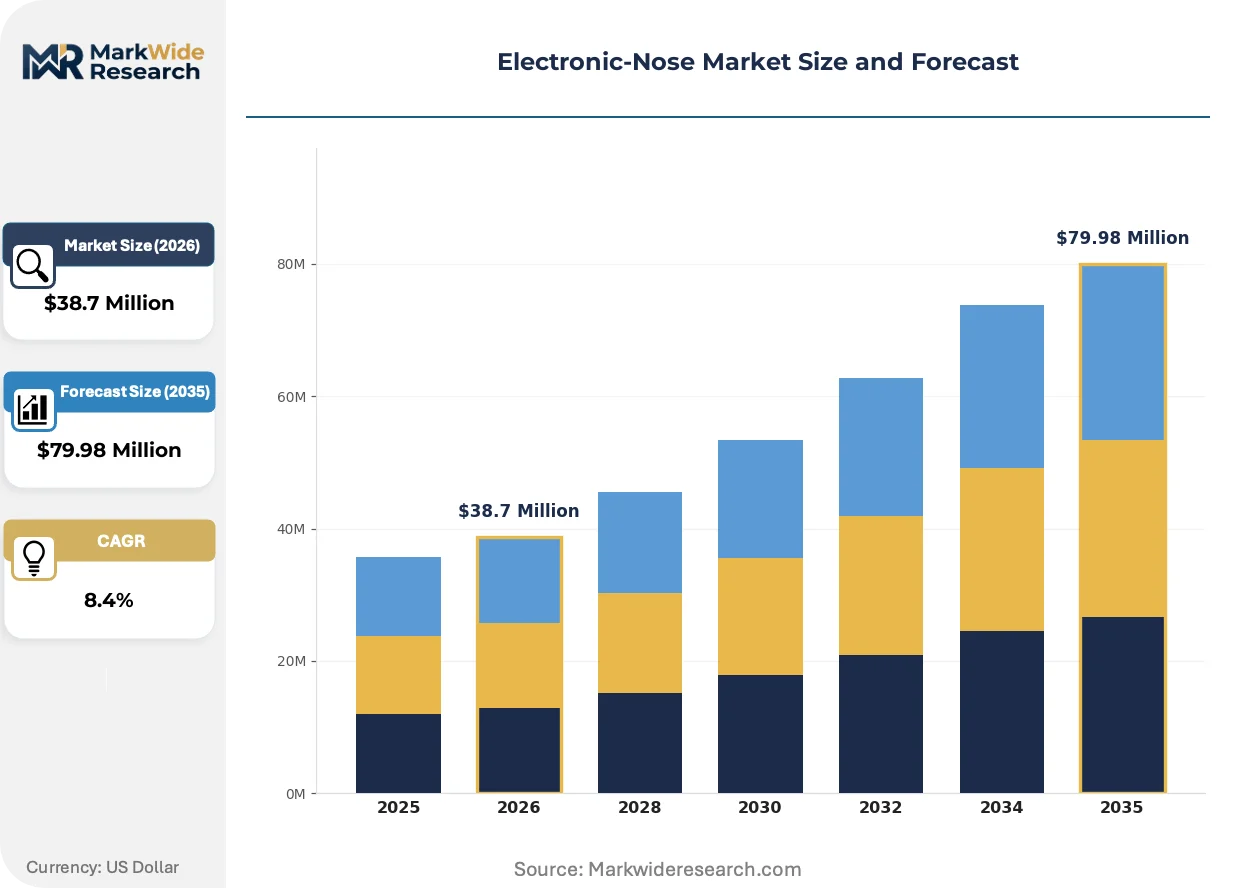
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $79.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Integrated, Micro Technology: Gas Sensors, Chemical Sensors, Optical Sensors, Biosensors Application: Food Quality Control, Environmental Monitoring, Medical Diagnostics, Homeland Security End User: Agriculture, Healthcare, Industrial, Research Institutes |
| Companies Covered | Aryballe Technologies, WAGEM Monitoring Systems, Alpha MOS, Electronic Sensor Technology, Odotech, Owlstone Medical, Cyranose, Envirosuite, Airsense Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic-Nose Market Strategic Shifts & Innovations
Three intersecting developments are compressing product development cycles and redrawing competitive boundaries: silicon photonics miniaturization, tightening multi-jurisdiction regulatory documentation requirements, and the unbundling of hardware from analytics services.
Silicon photonics is rewriting the economics of compact electronic-nose manufacturing. Optical sensor arrays integrated onto semiconductor substrates achieve parts-per-billion detection thresholds previously requiring benchtop laboratory instruments. Medical device manufacturers in Switzerland and diagnostic startups in South Korea are adopting these chip-scale platforms for point-of-care deployment. The technology is compressing the price-performance gap between portable field units and centralized laboratory systems.
REACH chemical registration enforcement is tightening material specifications across European manufacturing. ECHA restrictions on certain hydrophobic sensor coatings push manufacturers toward biocompatible polymer alternatives, triggering reformulation qualification cycles. Food safety testing laboratories in Germany and environmental monitoring agencies in France face elevated procurement documentation burdens as they validate substitute materials for humidity-variable deployment.
Buyers are fragmenting their vendor relationships across hardware and software layers. Agricultural cooperatives in Spain and wine producers in Italy procure sensor arrays from instrumentation specialists while subscribing to cloud analytics platforms from separate software vendors. This unbundling compresses hardware margins while elevating the strategic importance of proprietary training datasets and pattern recognition accuracy guarantees.
Electronic-Nose Market Segmentation
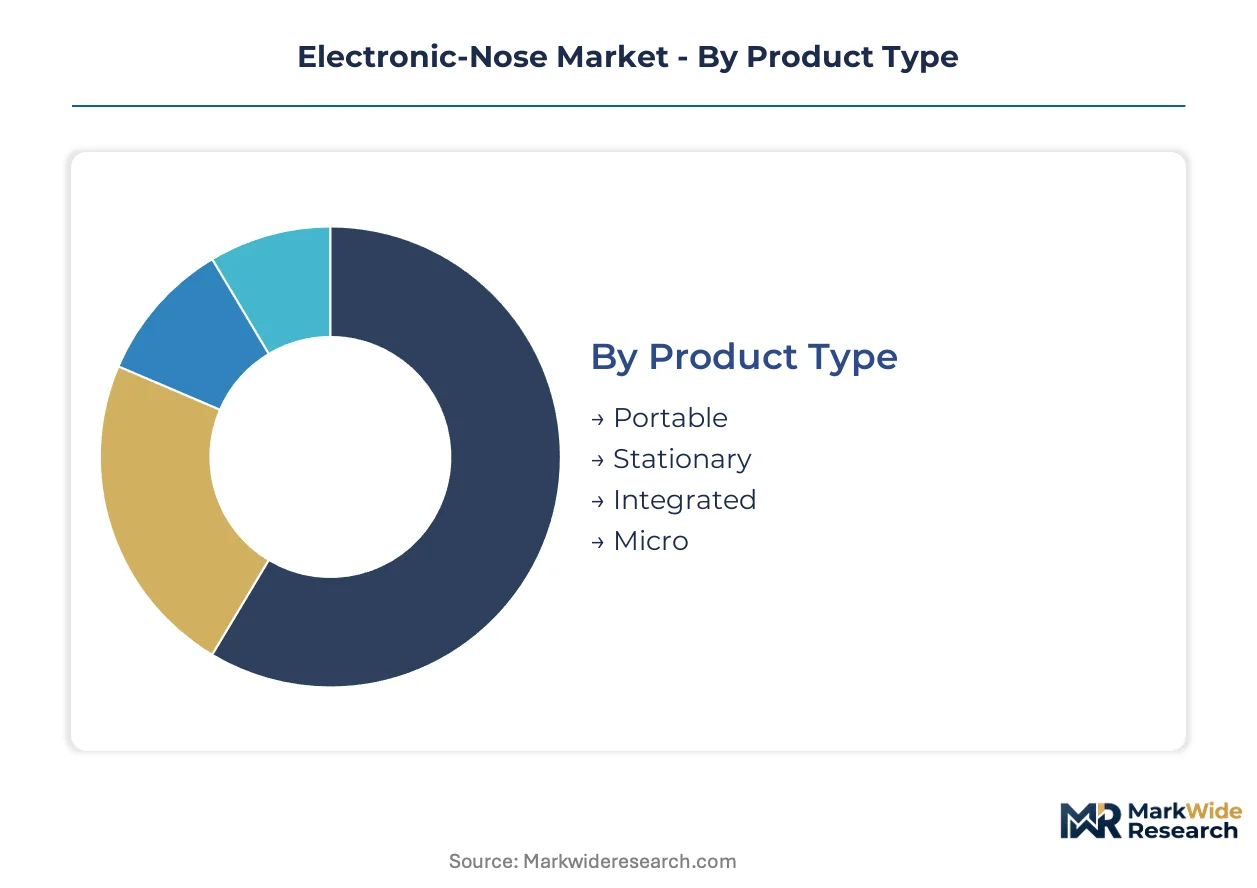
Segmentation in the electronic-nose market reveals how hardware form factors, sensor technologies, and end-use requirements create distinct procurement patterns. Buyers prioritize detection sensitivity thresholds, environmental robustness, and integration complexity differently across food safety, clinical screening, and industrial quality control workflows.
Product Type:
Supply concentration in portable manufacturing clusters favors contract electronics assemblers with humidity-testing capabilities, while stationary systems remain captive to specialized analytical instrument vendors with calibration infrastructure.
- Portable:Battery-powered units with MEMS sensor arrays achieve field-deployable detection thresholds previously requiring laboratory confinement. Demand concentrates in Spanish agricultural cooperatives and Italian wine producers replacing laboratory-bound systems with vineyard-side maturity assessment tools.
- Stationary:Benchtop configurations integrate multi-channel reference libraries and automated sampling systems for high-throughput industrial quality control. German food manufacturers anchor procurement volumes as ISO 17025 accreditation requirements tighten performance documentation standards for batch release decisions.
- Integrated:Embedded sensor modules designed for incorporation into larger manufacturing execution systems.
- Micro:Chip-scale implementations leveraging silicon photonics for point-of-care clinical deployment.
Today's leader: Stationary. Tomorrow's challenger: Portable.
Technology:
Cost tier differentiation separates mature manufacturing processes from emerging semiconductor integration approaches, with gas sensors commanding volume production economies and optical sensors capturing premium positioning through miniaturization.
- Gas Sensors:Metal oxide semiconductor and conducting polymer arrays dominate commercial installations due to mature foundry processes and broad humidity-range operability. French environmental monitoring agencies and German industrial automation clusters sustain procurement volumes despite recalibration-intensive maintenance protocols.
- Optical Sensors:Silicon photonics integration achieves parts-per-billion sensitivity on semiconductor substrates, compressing form factors for wearable clinical applications. Swiss medical device manufacturers and South Korean diagnostic startups drive adoption for point-of-care breath analysis workflows.
- Chemical Sensors:Electrochemical detection cells with specialized polymer coatings for targeted volatile compound identification.
- Biosensors:Enzyme-functionalized or antibody-coated interfaces for biological marker detection in medical screening.
Gas sensors retain volume leadership. Optical sensors gain share fastest through clinical miniaturization.
Application:
Application concentration tracks regulatory enforcement intensity, with food safety documentation requirements and clinical diagnostic clearance timelines creating divergent vendor qualification barriers.
- Food Quality Control:Non-destructive batch screening for spoilage detection, ripeness assessment, and authenticity verification replaces destructive sampling methods. German and French analytical laboratories anchor demand as EFSA documentation standards and customs inspection protocols elevate sensor traceability requirements.
- Medical Diagnostics:Breath-based metabolic disorder screening leverages FAIMS and optical detection platforms for non-invasive patient monitoring. FDA clearance timelines compress competitive windows for disease-claim validation, favoring vendors with existing clinical trial infrastructure.
- Environmental Monitoring:Soil health assessment and emissions tracking in agricultural and industrial settings.
- Homeland Security:Explosive and chemical warfare agent detection for border screening and facility protection.
Food quality control commands current procurement volumes. Medical diagnostics represents the steepest expansion trajectory pending regulatory recognition.
End User:
Customer type fragmentation separates price-sensitive agricultural cooperatives from specification-driven healthcare systems, with research institutes occupying an intermediate position on customization tolerance.
- Healthcare:Hospital systems and diagnostic service providers prioritize FDA-cleared platforms with validated clinical workflows. Procurement concentrates in Swiss and South Korean healthcare networks pursuing point-of-care metabolic screening integration.
- Industrial:Food manufacturers and chemical processors require robust humidity-variable operation with manufacturing execution system connectivity. German industrial automation clusters sustain demand despite legacy system integration challenges.
- Agriculture:Cooperatives and individual producers seeking field-deployable crop and soil assessment tools.
- Research Institutes:Academic and government laboratories developing proprietary training datasets and application-specific algorithms.
Healthcare captures premium pricing. Industrial end users drive volume scale through multi-site standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronic-nose technology originated in European analytical chemistry laboratories during the late 1980s, with France and Germany pioneering the sensor array architectures that underpin modern commercial systems. Industrial automation clusters in these founding markets continue to anchor precision instrumentation development.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg sustain demand for stationary electronic-nose systems integrated into manufacturing execution systems. ISO 17025 accreditation requirements enforced by DAkkS tighten performance documentation standards for food safety testing laboratories. Stuttgart-based precision instrumentation vendors supply calibration infrastructure to analytical laboratories serving customs inspection protocols.
France
Environmental monitoring agencies in the Île-de-France region deploy gas sensor arrays for emissions tracking and soil health assessment. ECHA REACH restrictions on hydrophobic sensor coatings push manufacturers toward biocompatible polymer alternatives. Lyon and Grenoble host specialized olfaction measurement system development for food and beverage quality control applications.
Switzerland
Medical device manufacturers in the Basel-Zurich corridor adopt silicon photonics platforms for point-of-care clinical breath analysis. Swissmedic oversight of diagnostic device clearance creates premium-tier procurement patterns favoring validated clinical workflows. Geneva-based diagnostic startups leverage semiconductor integration for wearable metabolic screening applications.
South Korea
Diagnostic startups in Seoul and Daejeon extend FAIMS platforms into disease screening workflows for non-invasive patient monitoring. MFDS clearance timelines compress competitive windows for breath-based metabolic disorder claims. Suwon-Gyeonggi semiconductor fabrication clusters enable chip-scale optical sensor manufacturing for compact form factors.
Spain
Agricultural cooperatives in Catalonia and Andalusia replace laboratory-bound systems with portable electronic-nose units for vineyard-side crop maturity assessment. Non-destructive testing methods reduce waste while accelerating batch release decisions for wine producers. Barcelona-based environmental monitoring firms deploy field-deployable units for soil health inspection routines.
Electronic-Nose Market Key Industry Players
The competitive structure tilts toward technology-specialist archetypes with differentiated sensor platform expertise. Vendor relationships fragment across hardware instrumentation and cloud analytics layers, compressing margins for pure-play manufacturers while elevating recurring-revenue software providers. Two strategic archetypes dominate: silicon photonics integrators pursuing clinical miniaturization, and established analytical instrument vendors defending food safety testing positions. Competitive moves concentrate on strategic partnerships with analytics platforms and technology licensing for sensor array customization.
Within the technology-specialist tier, Aryballe Technologies exemplifies silicon photonics integration for compact form factors, while Alpha MOS occupies a position representing specialized olfaction measurement systems for European food and beverage clients. Owlstone Medical sits within the clinical breath analysis segment, extending FAIMS platform infrastructure into disease screening workflows.
| Leading Market Players |
|---|
| Aryballe Technologies |
| WAGEM Monitoring Systems |
| Alpha MOS |
| Electronic Sensor Technology |
| Odotech |
| Owlstone Medical |
| Cyranose |
| Envirosuite |
| Airsense Analytics |
| Others |
Cost & Logistics Intelligence
Silicon photonics wafer costs cascade through three distinct hardware tiers, with semiconductor-grade substrates commanding premium positioning for point-of-care clinical devices while MEMS-based gas sensor arrays occupy standard-economy positioning for agricultural field deployment.
Pricing Analysis
Subscription-SaaS bundling with cloud analytics platforms now dominates buyer relationships, compressing upfront hardware margins while elevating recurring revenue streams. Price differentiation rests on ISO 17025 certification tier and after-sales calibration service bundling. Cost compression in standard-tier portable units is intensifying because agricultural cooperatives in Spain and Italy prioritize field-deployable detection over laboratory-grade sensitivity. Healthcare systems in Switzerland exhibit lowest price sensitivity, accepting premium positioning for FDA-cleared clinical workflows.
Supply Chain Analysis
Refurbishment flows for gas sensor arrays create secondary market circulation, with recalibrated units penetrating price-sensitive agricultural segments. Manufacturing concentrates in Germany, South Korea, and Switzerland. Production draws from specialized polymer coating suppliers, MEMS foundries, and semiconductor photonics fabrication clusters. Single-source vulnerability sits with REACH-restricted hydrophobic coating materials. Distribution runs through analytical instrument vendors with embedded calibration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in clinical breath analysis, where silicon photonics miniaturization enables premium-tier positioning against commoditized gas sensor competition.
For Market Incumbents: Extend cloud analytics capabilities through partnership or in-house development to capture recurring revenue streams, as hardware margins compress under unbundling pressure. Defend food safety testing positions by deepening calibration infrastructure investment in Germany and France, where ISO 17025 documentation requirements tighten vendor qualification barriers. Backward integration into silicon photonics wafer sourcing reduces exposure to semiconductor foundry capacity constraints. For New Entrants and Emerging Players: Begin with portable configurations for agricultural cooperatives in Spain and Italy, where laboratory-bound system replacement creates immediate white-space opportunity. Target vineyard-side crop maturity assessment as the most penetrable application, leveraging non-destructive testing demand from wine producers. Pursue direct sales to agricultural cooperatives rather than analytical instrument channel intermediaries to accelerate price-competitive positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where hardware vendors lack software capabilities or analytics partnerships to sustain recurring revenue models. Long-term viability favors vendors with validated clinical trial infrastructure and FDA clearance pathways for metabolic disorder screening claims. Target acquisition archetype: silicon photonics specialists with point-of-care device development expertise. Monitor MFDS and FDA diagnostic device clearance timelines as inflection indicators for competitive window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Platform Integration | Enables chip-scale optical sensors for wearable clinical breath analysis in Swiss healthcare networks. |
| Cloud Analytics Partnership | Captures recurring revenue through pattern recognition services for food safety testing laboratories. |
| ISO 17025 Certification Investment | Qualifies vendors for DAkkS-accredited analytical laboratory procurement in German industrial clusters. |
| FAIMS Infrastructure Extension | Supports disease screening workflow integration for non-invasive metabolic disorder detection. |
| Biocompatible Polymer Reformulation | Addresses ECHA REACH restrictions on hydrophobic sensor coatings in European manufacturing. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with sensor technology R&D directors, food safety laboratory managers, clinical diagnostic procurement officers, and agricultural cooperative equipment buyers with secondary validation against FDA 510(k) filings, ECHA REACH registration databases, ISO 17025 accreditation records, and customs inspection protocol documentation. Bottom-up demand modeling triangulated against top-down market sizing across sensor technology tiers.
Comparable historical periods anchored the projection horizon, with growth trajectories derived from technology adoption curves in adjacent point-of-care diagnostic segments. Segmentation dimensions spanned hardware form factor, sensor technology type, application workflow, and end-user procurement sophistication. Forecast inputs incorporated silicon photonics cost reduction curves, REACH regulatory enforcement timelines, and cloud analytics subscription attach rates.
Several conditions sit outside the modeled scope, including unforeseen FDA diagnostic device reclassification, abrupt ECHA polymer coating prohibitions, and breakthrough non-sensor detection technologies. Forecasts reflect documented assumptions on regulatory clearance pacing and agricultural cooperative capital expenditure cycles. Practitioners should monitor MFDS and Swissmedic clearance announcements, REACH authorization list updates, and agricultural subsidy program shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market