
 Hi-Fi System Market | 2026-2036
Hi-Fi System Market Size, Share, and Industry Trends Forecast 2026-2036
Hi-Fi System Market Analysis
Subscription-based high-resolution streaming integration is hardening into a core revenue layer for manufacturers. Harman International Industries leverages its automotive and consumer audio verticals to sustain R&D intensity across multiple price tiers. Bowers & Wilkins anchors its premium positioning through British engineering heritage and controlled distribution. Sony Corporation dominates streaming codec development, extending its influence over how digital audio reaches end users.
A Hi-Fi System comprises precision-engineered audio reproduction equipment designed to deliver frequency response accuracy, low total harmonic distortion, and high signal-to-noise ratios for faithful sound reproduction in residential and professional environments. Speakers and amplifiers occupy the largest margin pools, while streaming-enabled wireless systems represent the fastest-expanding technology dimension. Audiophile and home user segments show divergent purchasing patterns, with the former prioritizing component separability and the latter favoring integrated ecosystem compatibility.
FCC equipment authorization governs wireless transmission protocols in the United States, while CE marking and RoHS compliance govern electromagnetic compatibility and hazardous substance restrictions across Europe. Ecodesign regulations from the EU progressively tighten standby power limits, forcing hardware redesigns that ripple through global product lines. Stakeholders must monitor whether regional certification divergence accelerates platform fragmentation or consolidates around unified streaming standards.
Market Dynamics
Streaming protocol standardization is compressing hardware differentiation cycles, forcing manufacturers to redesign amplifier and speaker architectures around wireless codec compatibility rather than analog performance metrics.
Growth Catalysts
- EU Ecodesign standby power mandates:Tighter limits on idle consumption are accelerating semiconductor upgrades in power management circuits, creating replacement demand across installed bases.
- Home theater renovation activity:Residential construction in Germany and Japan is incorporating pre-wired acoustic infrastructure, embedding high-fidelity equipment specifications into architectural standards.
- MQA and FLAC codec proliferation:Lossless streaming format support is absorbing into receiver firmware, expanding addressable demand among catalog collectors seeking bit-perfect reproduction.
Market Restraints
- Rare earth magnet supply concentration:Neodymium procurement depends on Chinese processing capacity, exposing driver manufacturers to export quota volatility and price spikes.
- FCC equipment authorization timelines:Wireless certification delays in the United States extend product launch windows by four to six months, compressing revenue recognition periods.
- Soundbar substitution:Integrated television audio solutions are capturing marginal home theater buyers who previously considered discrete component systems.
Strategic Opportunities
- Indian metropolitan household formation:Mumbai and Bangalore are exhibiting rising discretionary spending on residential entertainment infrastructure among technology sector professionals.
- Bi-amplified active speaker convergence:DSP-controlled crossover networks combined with Class D amplification are collapsing traditional component stack requirements into single-enclosure solutions.
- Japan's METI energy efficiency labeling:Top-runner appliance standards are creating premium positioning for compliant products in retail channels.
Industry Challenges
- Acoustic engineering talent scarcity:Transducer design expertise concentrates among aging specialists in Denmark and Germany, constraining R&D expansion at mid-tier manufacturers.
- Multi-protocol wireless integration:Simultaneous certification for WiSA, AirPlay, and proprietary mesh networks fragments firmware development resources and extends validation cycles.
- RoHS substance compliance recertification:Expanded restricted substance lists in the European Union force bill-of-materials revisions that disrupt supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hi-Fi System Market |
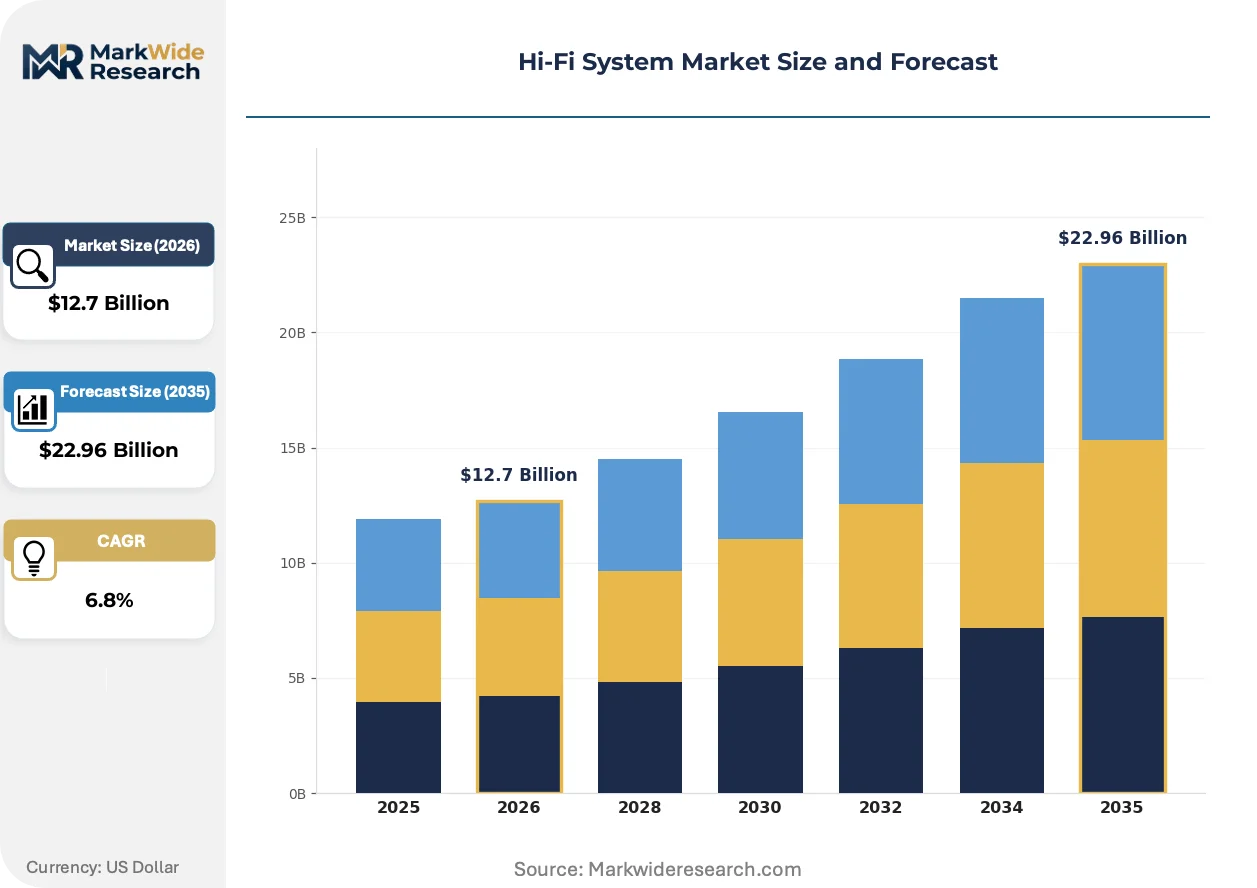
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Speakers, Amplifiers, Turntables, CD Players Technology: Wireless, Bluetooth, Wired, Streaming End User: Home Users, Audiophiles, Commercial Spaces, Studios Distribution Channel: Online Retailers, Specialty Stores, Electronics Outlets, Others |
| Companies Covered | Harman International Industries, LG Electronics Inc., Bose Corporation, Bowers & Wilkins, Samsung Electronics Co., Ltd., Sony Corporation, Panasonic Corporation, KEF International, Yamaha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hi-Fi System Market Emerging Trajectories
Codec sovereignty battles between streaming platforms are reshaping hardware firmware roadmaps, with manufacturers forced to support multiple lossless formats simultaneously rather than optimizing for single-ecosystem performance.
Gallium nitride (GaN) power semiconductors are absorbing into Class D amplifier output stages, enabling higher switching frequencies with reduced thermal mass. Audiophile buyers in Japan and Germany are adopting GaN-based integrated amplifiers at accelerating rates. This technology is absorbing the physical volume previously occupied by linear power supplies and heat sinks, permitting compact chassis designs without wattage compromise.
CE marking electromagnetic compatibility standards are tightening radiated emission limits for wireless audio transmitters, forcing shielding redesigns in streaming DAC architectures. Manufacturers serving European distribution channels must retest existing product lines against updated EN 55032 limits. High-end networked players with internal switch-mode supplies face the most significant compliance burden, driving modular external power supply adoption.
Direct-to-consumer channel expansion is displacing traditional hi-fi dealer networks, with manufacturers building proprietary e-commerce infrastructure and virtual demonstration capabilities. Specialist retailers in the United States and United Kingdom are consolidating or pivoting toward installation services to retain relevance. Germany retains stronger brick-and-mortar loyalty, though even Munich and Hamburg markets show declining foot traffic for standalone audio showrooms.
Hi-Fi System Market Segmentation
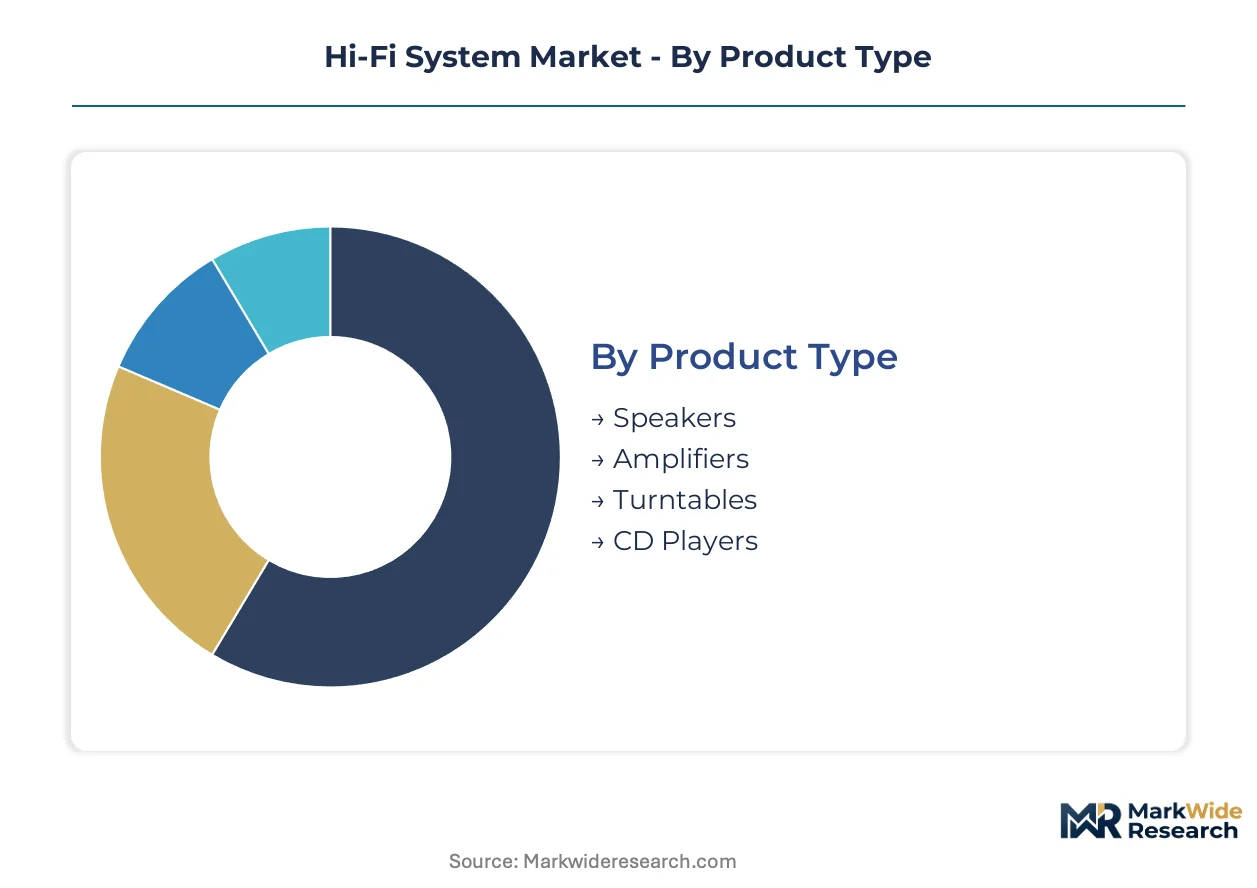
Hi-fi system segmentation reveals divergent hardware requirements between integrated lifestyle products and discrete component architectures. Manufacturers must calibrate R&D allocation across standalone equipment serving purist listeners versus embedded solutions targeting seamless smart home integration.
Product Type:
Standalone loudspeakers and amplifiers command premium positioning through acoustic engineering differentiation, while embedded source components face compression from streaming substitution.
- Speakers:Electromechanical transducers converting electrical signals to acoustic output, spanning passive radiator designs to active DSP-controlled systems. Demand concentrates in Germany and Japan where residential construction specifications increasingly mandate pre-wired acoustic infrastructure. Driver manufacturers face neodymium supply volatility from Chinese processing concentration.
- Amplifiers:Signal amplification electronics ranging from Class A/B linear designs to GaN-enabled Class D switching architectures. Audiophile buyers in Japan adopt GaN-based integrated amplifiers at accelerating rates as thermal mass requirements shrink. Power semiconductor upgrades accelerate from EU Ecodesign standby power mandates.
- Turntables:Analog vinyl reproduction equipment with belt-drive and direct-drive motor configurations.
- CD Players:Optical disc transport mechanisms with digital-to-analog conversion stages.
Speakers lead volumes today; amplifiers are gaining share fastest through active speaker convergence.
Technology:
Wireless transmission protocols are collapsing traditional cable infrastructure requirements, though wired connections retain latency-critical professional applications.
- Wireless:Radio-frequency audio transmission encompassing proprietary mesh networks and standards-based protocols. FCC equipment authorization timelines in the United States extend product launch windows by four to six months. Multi-protocol certification for WiSA, AirPlay, and proprietary systems fragments firmware development resources.
- Bluetooth:Short-range wireless codec transmission with widespread mobile device compatibility. CE marking electromagnetic compatibility standards tighten radiated emission limits, forcing shielding redesigns in streaming DAC architectures.
- Wired:Physical cable connections via analog RCA, balanced XLR, or digital SPDIF interfaces.
- Streaming:Network-based audio delivery with lossless codec support.
Wireless leads volumes today; streaming is climbing the fastest as subscription-based high-resolution integration hardens into core revenue layers.
End User:
Purchasing patterns diverge sharply between specification-focused enthusiasts and convenience-oriented residential buyers.
- Home Users:Residential consumers prioritizing ecosystem compatibility and minimal installation complexity. Soundbar substitution captures marginal buyers who previously considered discrete component systems. Mumbai and Bangalore metropolitan households exhibit rising discretionary spending on residential entertainment infrastructure.
- Audiophiles:Discerning listeners demanding component separability, bit-perfect reproduction, and upgrade paths. Catalog collectors drive MQA and FLAC codec proliferation into receiver firmware. Transducer design expertise concentrates among aging specialists in Denmark and Germany.
- Commercial Spaces:Hospitality and retail venues requiring distributed audio coverage.
- Studios:Professional monitoring environments demanding flat frequency response and precise imaging.
Home users lead volumes today; audiophiles sustain the steepest margin expansion trajectory.
Distribution Channel:
Channel structure is displacing toward direct manufacturer engagement as specialist retail consolidation accelerates.
- Online Retailers:E-commerce platforms enabling manufacturer-direct sales with virtual demonstration capabilities. Direct-to-consumer expansion displaces traditional dealer networks in the United States and United Kingdom. Proprietary infrastructure investments reduce intermediary margin capture.
- Specialty Stores:Dedicated audio showrooms with listening room facilities and installation services. Munich and Hamburg markets show declining foot traffic despite stronger German brick-and-mortar loyalty. Retailers pivot toward installation services to retain relevance.
- Electronics Outlets:Generalist consumer electronics retailers with limited acoustic demonstration capabilities.
- Others:Direct contract sales and custom integration channels.
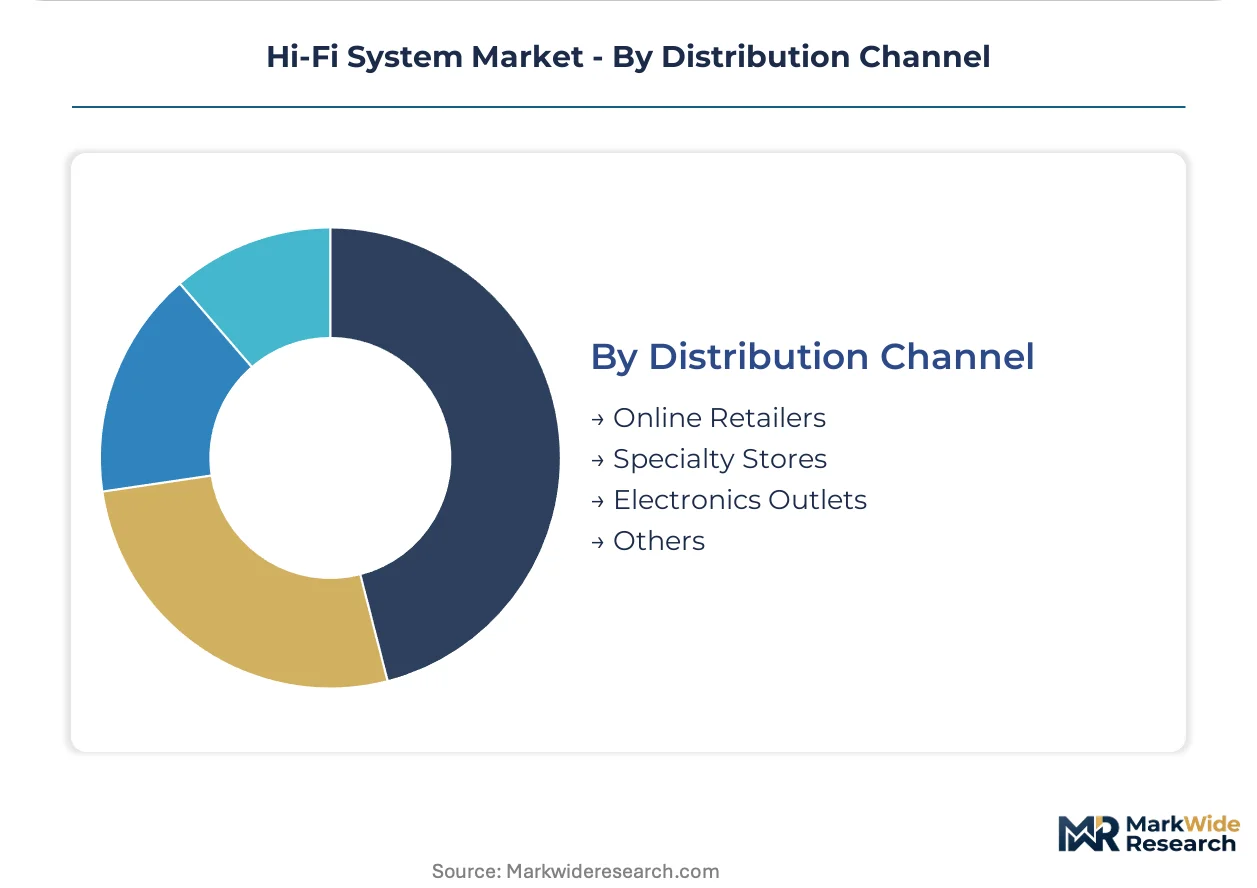
Online retailers lead volumes today; specialty stores are contracting fastest amid consolidation pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sustains denser specialty retail infrastructure than the United States, while Japan exhibits stronger consumer loyalty toward domestic amplifier manufacturers. Demand concentrates where residential construction specifications embed acoustic infrastructure and where streaming codec adoption accelerates fastest.
Germany
Home theater renovation activity and pre-wired acoustic infrastructure specifications drive equipment specifications into building codes. The EU Ecodesign Directive mandates progressively tighter standby power limits, forcing semiconductor upgrades in power management circuits. Munich and Hamburg retain stronger brick-and-mortar audio showroom loyalty despite declining foot traffic.
United States
Subscription-based high-resolution streaming integration hardens into core revenue layers for manufacturers serving residential consumers. FCC equipment authorization timelines extend wireless product launch windows by four to six months, compressing revenue recognition periods. Direct-to-consumer channel expansion displaces traditional hi-fi dealer networks across coastal metropolitan markets.
Japan
Audiophile buyers adopt gallium nitride-based integrated amplifiers at accelerating rates as thermal mass requirements shrink. METI energy efficiency labeling under top-runner appliance standards creates premium positioning for compliant products in retail channels. The Kanto region surrounding Tokyo anchors domestic manufacturing concentration for precision transducer components.
India
Metropolitan household formation among technology sector professionals in Mumbai and Bangalore drives discretionary spending on residential entertainment infrastructure. BIS certification requirements for electronic goods create compliance barriers for imported equipment. Western India manufacturing clusters near Pune are absorbing contract assembly demand from audio equipment brands.
United Kingdom
British engineering heritage anchors premium positioning for loudspeaker manufacturers serving catalog collectors seeking bit-perfect reproduction. CE marking electromagnetic compatibility standards tighten radiated emission limits for wireless audio transmitters, forcing shielding redesigns. London and Southeast England concentrate specialist retail consolidation pressures as dealers pivot toward installation services.
Hi-Fi System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated lifestyle products consolidating around consumer electronics conglomerates while discrete component architectures sustain fragmentation among heritage audio houses. The vendor base organizes into three strategic archetypes: diversified technology conglomerates with audio verticals, pure-play acoustic engineering specialists, and contract manufacturers serving private-label distribution. Competitive positioning hardens through direct-to-consumer channel infrastructure investments and multi-protocol wireless certification capabilities.
Among diversified technology conglomerates, Harman International Industries and Sony Corporation occupy positions spanning automotive and consumer audio verticals, while Bowers & Wilkins exemplifies the heritage specialist archetype anchored in controlled distribution and engineering pedigree. These three entities represent contrasting strategic postures: vertical integration across multiple price tiers, dominance in streaming codec development and hardware firmware roadmaps, and premium positioning through British manufacturing heritage respectively.
| Leading Market Players |
|---|
| Harman International Industries |
| LG Electronics Inc. |
| Bose Corporation |
| Bowers & Wilkins |
| Samsung Electronics Co., Ltd. |
| Sony Corporation |
| Panasonic Corporation |
| KEF International |
| Yamaha Corporation |
| Others |
Supply Flow & Price Mechanics
GaN semiconductor adoption in Class D amplifier output stages is compressing thermal management costs while concentrating procurement leverage among Japanese and German power electronics suppliers. This technology transition simultaneously reduces chassis material requirements and elevates dependency on specialized foundry capacity, reshaping cost economics across integrated and discrete product tiers.
Pricing Analysis
Capacity additions in China's neodymium processing facilities are reshaping price floors for driver magnet assemblies, though export quota volatility sustains premium tier premiums. Three-tier pricing structure across premium, standard, and economy levels separates audiophile-grade component separability from mass-market ecosystem compatibility. Cost compression in entry-level wireless systems is intensifying because soundbar substitution captures marginal home theater buyers. Home users exhibit highest price sensitivity, while catalog collectors in Japan and Germany demonstrate inelastic demand for bit-perfect reproduction capabilities.
Supply Chain Analysis
Direct-to-consumer channels handle hyperscale buyer demand for streaming-enabled systems, displacing traditional dealer inventory holding. Manufacturing concentration spans China for driver assembly, Japan for precision transducer components, and Germany for acoustic engineering validation. Neodymium magnets, GaN semiconductors, and DSP chipsets constitute critical input dependencies. Single-source vulnerability in Chinese rare earth processing exposes driver manufacturers to export restriction shocks. Distribution runs through manufacturer-owned e-commerce infrastructure and consolidated specialist retailers pivoting toward installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign standby power mandates impose stricter compliance costs on European-serving manufacturers than Asian competitors, creating arbitrage potential for production relocation or certification tier differentiation.
For Market Incumbents: Extend GaN amplifier platform architectures across multiple price tiers to amortize R&D across volume segments while soundbar substitution threatens discrete component demand. Deepen backward integration into DSP firmware development to defend margin position against streaming protocol fragmentation. Prioritize METI top-runner compliance in Japan to secure premium retail positioning. For New Entrants and Emerging Players: Direct-to-consumer virtual demonstration platforms unlock penetration of Mumbai and Bangalore metropolitan households where specialist retail infrastructure remains underdeveloped. Target active speaker convergence segments where traditional component stack requirements collapse into single-enclosure solutions. Pursue white-label contract assembly relationships with Western India manufacturing clusters near Pune to circumvent BIS certification barriers. For Investors and Strategic Acquirers: Roll-up economics work for heritage acoustic engineering specialists because transducer design expertise concentrates among aging specialists in Denmark and Germany with limited succession planning. Long-term viability hinges on captive R&D retention through generational transition. Monitor FCC equipment authorization timeline compression as inflection indicator for wireless product launch velocity and revenue recognition efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Amplifier Platform Expansion | Enables compact chassis designs without wattage compromise for Japanese audiophile buyers. |
| Multi-Protocol Wireless Certification | Simultaneous WiSA, AirPlay, and proprietary mesh support fragments firmware development resources. |
| Direct-to-Consumer Channel Buildout | Proprietary e-commerce infrastructure reduces intermediary margin capture in United States coastal markets. |
| EU Ecodesign Compliance Investment | Tighter standby power limits force semiconductor upgrades in power management circuits. |
| Indian Manufacturing Footprint Establishment | Pune-area contract assembly absorbs demand while BIS certification creates import barriers. |
Methodological Framework
Bottom-up residential entertainment infrastructure modeling reconciled against top-down semiconductor and transducer supply tracking forms the analytical core. Primary interviews with acoustic engineering directors, streaming platform codec developers, specialty retail buyers, and residential construction specification consultants combined with secondary validation against FCC equipment authorization databases, EU Ecodesign directive implementation reports, METI top-runner appliance standard filings, and BIS electronic goods certification records. Top-down trade flow analysis and bottom-up manufacturer shipment triangulation ensure cross-verification.
Historical trendline analysis of wireless protocol adoption rates and active speaker penetration patterns informs projection parameters across the analysis window. Segmentation dimensions encompass product architecture type, wireless transmission protocol, end-user sophistication tier, and distribution channel structure. CAGRs derive from regression analysis of replacement cycle compression and codec proliferation trajectories, incorporating EU standby power mandate compliance costs and GaN semiconductor price elasticity assumptions.
Rare earth export quota shocks, FCC certification timeline extensions, and streaming platform codec sovereignty battles are the dominant revision risks. Forecasts reflect documented assumptions regarding residential construction specification embedding rates and wireless standard consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Cognitive Systems Spending Market