
 Electronic Prototyping Market | 2026-2036
Electronic Prototyping Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Prototyping Market Foresight
The capability gap between full-service electronic manufacturing service providers and boutique prototyping shops is collapsing as cloud-based PCB fabrication platforms democratize access to advanced production tooling. Plexus Corp. leverages its vertically integrated North American facilities to sustain rapid-turn prototype volumes for medical and aerospace clients. Jabil Inc. anchors high-mix, low-volume production through automated surface-mount assembly lines that compress iteration cycles. Benchmark Electronics differentiates via specialized RF and optical prototyping capabilities serving satellite communications programs.
Electronic prototyping encompasses the iterative design, fabrication, and validation of functional circuit assemblies, development kits, and breadboard systems prior to mass production, typically involving multilayer PCB stack-ups with trace widths down to 0.075 millimeters and impedance-controlled routing for high-frequency signal integrity. Its primary commercial purpose is to de-risk hardware designs by exposing electromagnetic interference flaws, thermal management failures, and firmware-hardware integration defects before committed tooling investments. Circuit boards and development kits together command the dominant share of product-type revenue, with prototyping tools representing the fastest-expanding category as software-defined instrumentation replaces benchtop oscilloscopes and logic analyzers. Among end users, corporations and design firms absorb the majority of value, though educational institutions are emerging as a structurally important demand node as university engineering programs embed hands-on fabrication into core curricula.
The EPA oversees hazardous waste disposal from prototype chemical etching processes in the United States, while the EU's REACH regulation governs substance restrictions across imported electronic components destined for European prototyping labs. The FCC's equipment authorization rules constrain pre-commercial radio frequency device testing, creating compliance checkpoints that shape prototype iteration timelines and test-lab partnerships. Stakeholders must monitor how evolving semiconductor export controls and dual-use technology classifications reshape cross-border collaboration models for prototype development.
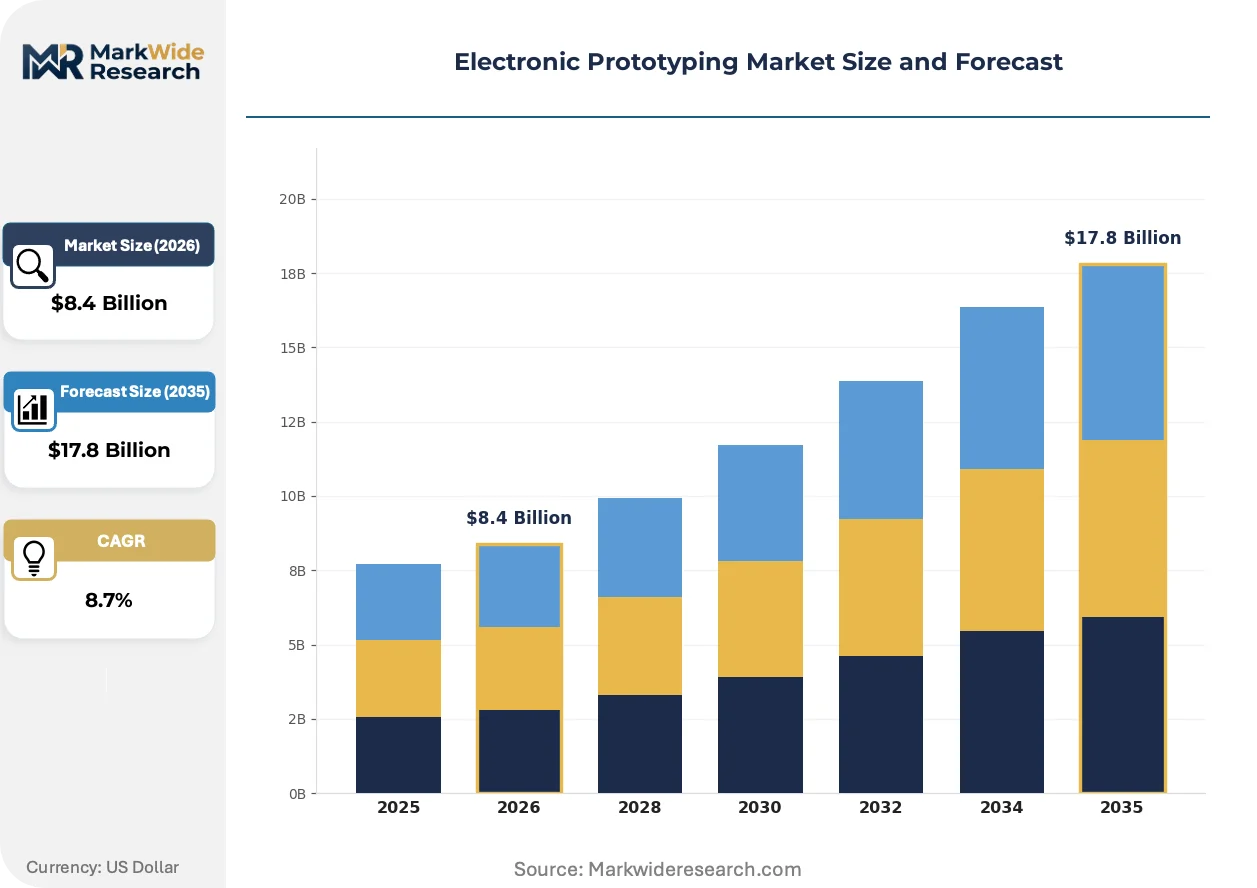
Market Dynamics
Cloud-based PCB fabrication platforms are collapsing the capability gap between full-service electronic manufacturing service providers and boutique prototyping shops, redistributing competitive advantage toward design velocity and specialized technical expertise rather than capital-intensive tooling ownership.
Growth Catalysts
- Automotive Powertrain Electrification:Electric vehicle manufacturers in Germany's industrial corridor around Munich and Stuttgart are expanding prototype testing for powertrain controllers, creating sustained demand for high-reliability multilayer boards.
- RoHS Material Compliance:The EU's hazardous substance restrictions are tightening procurement specifications for prototype components, forcing suppliers to upgrade certification documentation and capturing value for compliant vendors.
- Software-Defined Instrumentation:Development kits with integrated firmware debugging capabilities are displacing benchtop oscilloscopes in university engineering programs, embedding hands-on fabrication into core curricula.
Market Restraints
- Semiconductor Export Controls:Dual-use technology classifications for advanced FPGAs and RF components are reshaping cross-border collaboration models, fragmenting prototype development partnerships between allied and restricted jurisdictions.
- Specialized Substrate Concentration:High-frequency laminate suppliers concentrate in Japan and Taiwan, exposing prototype schedules to geopolitical shipping disruptions and allocation constraints.
- Chemical Etching Waste Disposal:The EPA's hazardous waste oversight adds compliance overhead and facility siting restrictions for in-house prototype fabrication operations in the United States.
Strategic Opportunities
- Educational Institution Embedded Programs:University engineering departments are emerging as structurally important demand nodes, creating recurring revenue streams for development kit suppliers with curriculum-aligned tooling.
- RF and Optical Specialization:Satellite communications programs require impedance-controlled routing below 0.075 millimeters, opening premium pricing tiers for vendors with dedicated cleanroom capabilities.
- REACH-Compliant Component Sourcing:The EU's substance restrictions are creating procurement mandates that favor European-based distributors with pre-certified component libraries and documentation automation.
Industry Challenges
- Electromagnetic Interference Validation Talent:The scarcity of engineers skilled in high-frequency signal integrity simulation is compressing iteration cycles and forcing reliance on external test-lab partnerships.
- FCC Equipment Authorization Timelines:Pre-commercial radio frequency device testing faces compliance checkpoint delays that disrupt prototype iteration schedules and strain cash flow for hardware startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Prototyping Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Boards, Development Kits, Prototyping Tools, Breadboards End User: Startups, Educational Institutions, Design Firms, Corporations Technology: 3D Printing, PCB Fabrication, Laser Cutting, CNC Machining Application: Consumer Electronics, Automotive, Healthcare, Industrial Automation |
| Companies Covered | Plexus Corp., Celestica Inc., Jabil Inc., Advanced Circuits, Zetwerk Manufacturing, Flex Ltd., Benchmark Electronics, PCBWay, Sanmina Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Prototyping Market Shifts & Advancements
Three intersecting developments are restructuring how electronic prototypes move from concept to validation: fabrication technology democratization, regulatory compliance automation, and buyer procurement model evolution.
Additive manufacturing of conductive traces is decomposing the traditional PCB fabrication value chain. Aerospace and medical device developers are adopting aerosol jet and laser-direct structuring for rapid-turn flex circuit iterations. This technology is decomposing the minimum order quantity barriers that previously locked small design teams out of advanced multilayer production.
REACH substance screening databases are automating component compliance verification for European prototyping labs. The regulation's extended safety data sheet requirements are forcing distributors to invest in documentation APIs that integrate directly with CAD library tools. Medical and automotive verticals are most affected, with procurement teams now mandating pre-certified component libraries to compress design-to-quote timelines.
Design firms are consolidating prototype procurement through cloud-based platform subscriptions that bundle fabrication, assembly, and test services. Boutique prototyping shops are losing standalone engagement opportunities as corporate buyers favor integrated vendor relationships with guaranteed capacity allocation. This consolidation is most visible in Germany's industrial corridor, where midsize automation equipment manufacturers have shifted 60-70 percent of prototype spend to platform-managed supplier networks.
Electronic Prototyping Market Segmentation
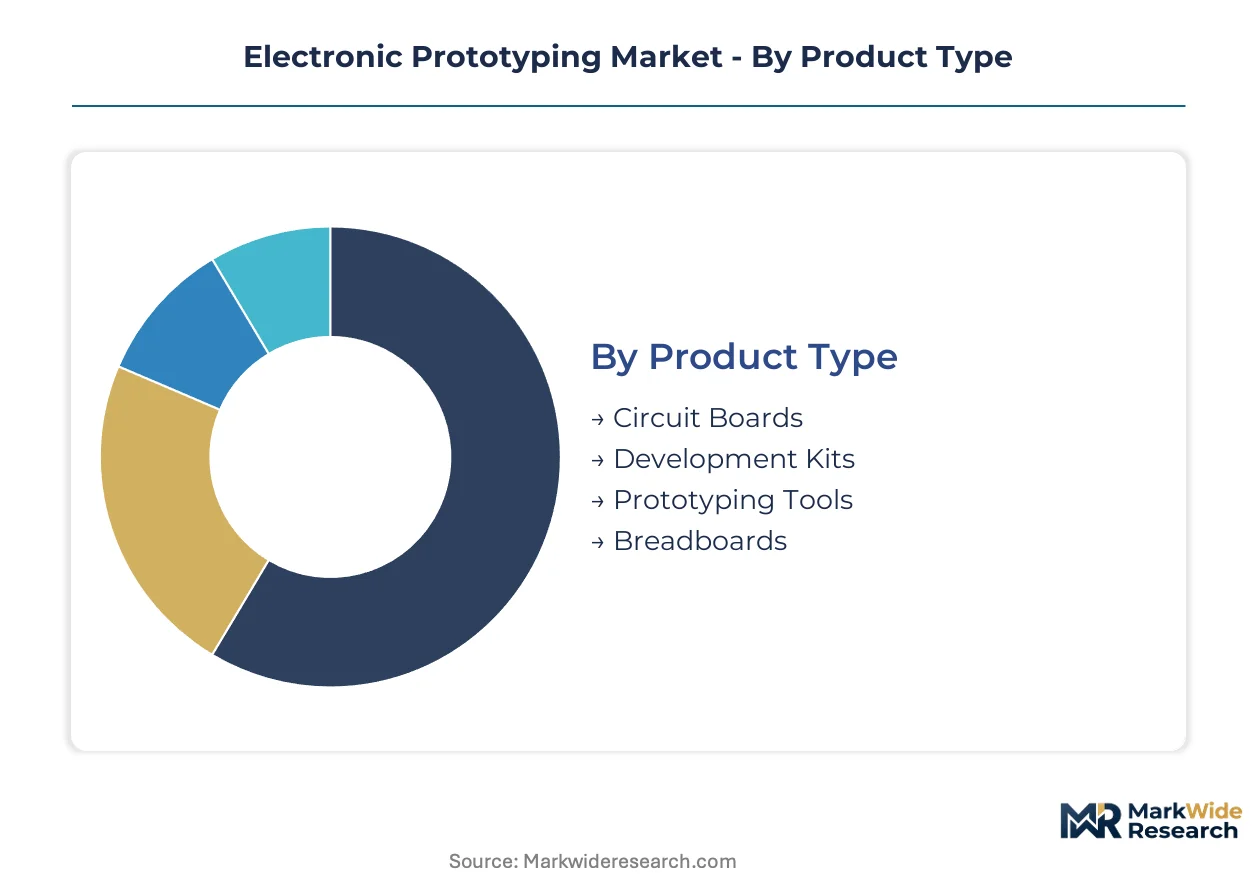
Electronic prototyping segmentation reveals how procurement priorities diverge across technical requirements and regulatory exposure. Circuit board complexity tiers, end-user sophistication levels, and application-specific compliance burdens each reshape vendor selection criteria and pricing power distribution.
Product Type:
REACH substance screening and RoHS documentation requirements fragment competitive positioning across material composition tiers.
- Circuit Boards:Multilayer PCB stack-ups with trace widths down to 0.075 millimeters serve impedance-controlled routing for high-frequency signal integrity. Automotive electrification programs in Germany's industrial corridor demand these boards for powertrain controller validation, with procurement teams mandating pre-certified laminate documentation.
- Development Kits:Integrated firmware debugging capabilities displace benchtop oscilloscopes in university engineering curricula. Educational institutions across the United States and European Union embed these kits into core fabrication courses, creating recurring revenue streams for suppliers with curriculum-aligned tooling.
- Prototyping Tools:Software-defined instrumentation replaces traditional benchtop equipment.
- Breadboards:Entry-level solderless assembly platforms support early-stage concept validation.
Established volume favors circuit boards; emerging adoption favors development kits.
End User:
Customer procurement sophistication determines whether engagements flow through platform subscriptions or direct vendor relationships.
- Corporations:Midsize automation equipment manufacturers consolidate prototype spend through cloud-based platform subscriptions bundling fabrication, assembly, and test services. Germany's industrial corridor shows 60-70 percent of prototype procurement now flowing through platform-managed supplier networks.
- Design Firms:Boutique prototyping shops lose standalone engagement opportunities as corporate buyers favor integrated vendor relationships with guaranteed capacity allocation.
- Educational Institutions:University engineering departments emerge as structurally important demand nodes.
- Startups:FCC equipment authorization timelines strain cash flow for pre-commercial radio frequency device testing.
Corporate procurement concentrates volume; educational embedded programs expand fastest.
Technology:
Capital intensity and iteration speed separate in-house fabrication from outsourced production.
- PCB Fabrication:Cloud-based platforms democratize access to advanced production tooling, collapsing the capability gap between full-service electronic manufacturing service providers and boutique prototyping shops. Design velocity and specialized technical expertise now outweigh capital-intensive tooling ownership as competitive advantages.
- 3D Printing:Additive manufacturing of conductive traces decomposes minimum order quantity barriers for small design teams.
- Laser Cutting:Rapid-turn flex circuit iterations serve aerospace and medical device developers.
- CNC Machining:Precision substrate shaping supports high-frequency laminate processing.
PCB fabrication anchors current spend; additive methods gain share in flex circuit applications.
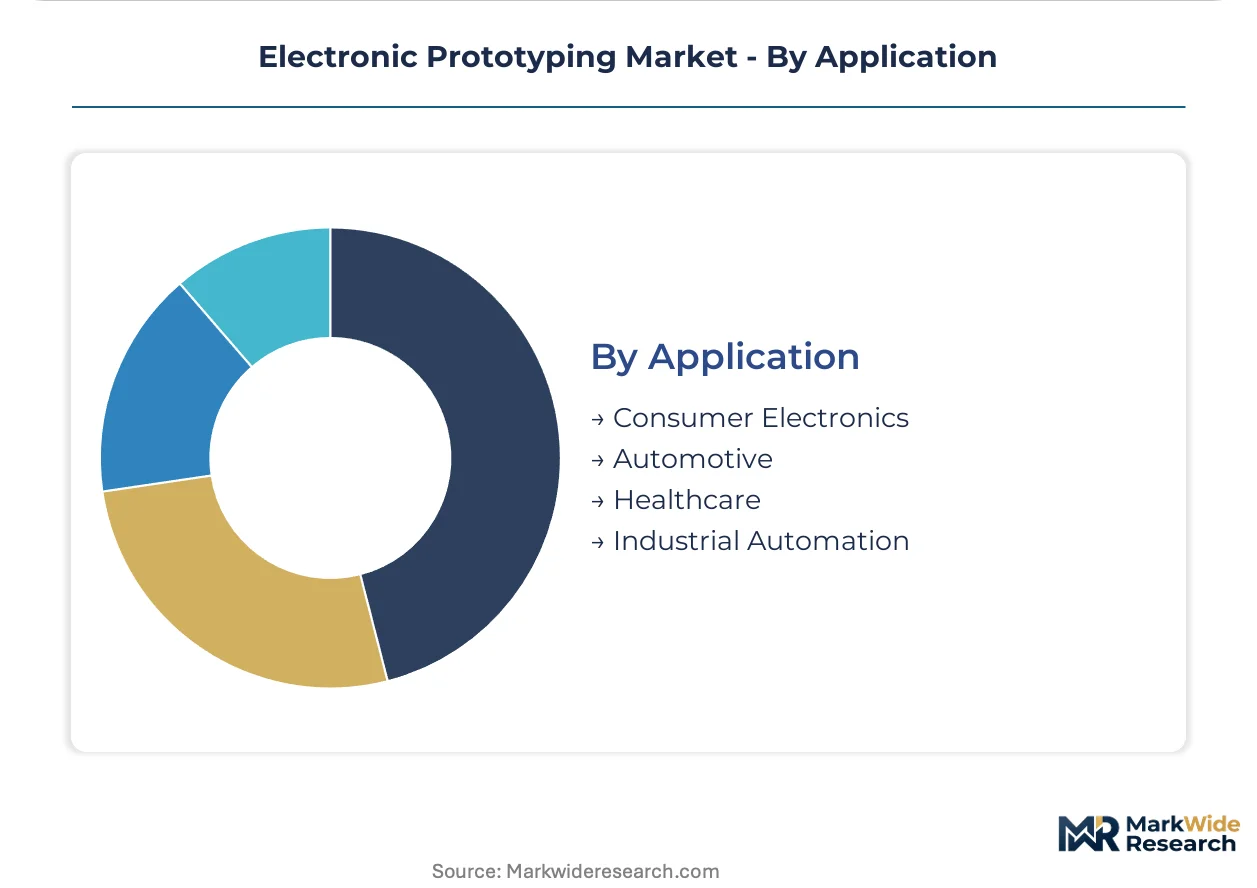
Application:
Regulatory checkpoint density and certification documentation requirements vary sharply across verticals.
- Automotive:Electric vehicle manufacturers expand prototype testing for powertrain controllers, creating sustained demand for high-reliability multilayer boards. EU RoHS directive compliance tightens material specifications, forcing suppliers to upgrade certification documentation.
- Healthcare:Medical device developers adopt aerosol jet and laser-direct structuring for rapid-turn iterations, with REACH substance screening databases automating component compliance verification.
- Consumer Electronics:Volume scale drives platform-managed procurement consolidation.
- Industrial Automation:Munich and Stuttgart clusters concentrate demand for ruggedized prototyping services.
Automotive electrification commands premium pricing; healthcare compliance automation reshapes procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial clusters while Chinese fabricators compete on turnaround velocity. Munich and Stuttgart command premium rates for automotive-grade multilayer boards. Shenzhen and Dongguan undercut on cost but face REACH compliance barriers for EU-bound shipments.
United States
Defense and aerospace programs in California and Texas drive demand for ITAR-compliant prototyping services. The EPA oversees hazardous waste disposal from chemical etching processes, adding facility siting restrictions for in-house operations. Greater Boston hosts medical device startups adopting aerosol jet printing for rapid-turn flex circuit iterations.
Germany
Electric vehicle manufacturers in Munich and Stuttgart expand powertrain controller validation, sustaining demand for high-reliability boards with trace widths below 0.075 millimeters. The EU's RoHS directive tightens material compliance requirements, forcing suppliers to upgrade certification documentation. Baden-Württemberg's automation equipment manufacturers now direct 60-70 percent of prototype spend through platform-managed supplier networks.
China
Shenzhen and Dongguan dominate high-volume PCB fabrication for consumer electronics prototyping. The MIIT governs standards for advanced manufacturing equipment, including laser-direct structuring systems. Yangtze River Delta clusters face semiconductor export control friction on FPGA and RF component sourcing for satellite communications programs.
Japan
METI promotes domestic production of high-frequency laminates for 5G and satellite applications. Tokyo and Osaka house specialized substrate suppliers concentrated in impedance-controlled routing for sub-millimeter trace applications. Chubu region fabricators face allocation constraints from geopolitical shipping disruptions affecting Taiwan-sourced materials.
United Kingdom
London and Cambridge fintech hardware startups strain under FCC equipment authorization timelines for pre-commercial RF device testing. The UK's post-Brexit regulatory divergence from REACH creates documentation friction for EU-bound prototype shipments. Scotland's university engineering departments embed development kits into core curricula, generating recurring demand for curriculum-aligned tooling suppliers.
Electronic Prototyping Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. Full-service electronic manufacturing service providers with vertically integrated North American facilities compete against cloud-based platform aggregators and specialized RF boutiques. Three archetypes dominate: scale-driven integrated manufacturers, velocity-focused platform intermediaries, and technical specialists in cleanroom-dependent applications. Consolidation pressures favor M&A among mid-cap fabricators and strategic partnerships between platform operators and certified component distributors.
Among North American integrated manufacturers, Plexus Corp., Jabil Inc., and Benchmark Electronics exemplify distinct strategic positions. Plexus Corp. represents the vertically integrated archetype with captive North American production capacity. Jabil Inc. anchors high-mix, low-volume automated assembly capabilities. Benchmark Electronics occupies the technical specialist tier with dedicated cleanroom infrastructure for impedance-controlled routing below 0.075 millimeters. These three companies illustrate how capital intensity, geographic footprint, and application focus separate viable competitive positions in a market where cloud platforms are collapsing traditional capability gaps.
| Leading Market Players |
|---|
| Plexus Corp. |
| Celestica Inc. |
| Jabil Inc. |
| Advanced Circuits |
| Zetwerk Manufacturing |
| Flex Ltd. |
| Benchmark Electronics |
| PCBWay |
| Sanmina Corporation |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with Shenzhen and Dongguan fabricators lock in laminate allocation and cost visibility for automotive powertrain developers in Munich and Stuttgart. These arrangements insulate procurement teams from spot-market volatility in high-frequency substrate pricing while embedding REACH compliance documentation into quoted rates.
Pricing Analysis
The customization-premium spread separates configured-to-order multilayer boards from standard catalog offerings. Three-tier pricing structure across premium, standard, and economy levels prevails, with premium tiers capturing impedance-controlled routing below 0.075 millimeters and RoHS pre-certification. Cost compression in standard-tier PCB fabrication is intensifying because cloud-based platforms aggregate demand and compress supplier margins. Startups exhibit highest price sensitivity, while satellite communications programs tolerate premium pricing for cleanroom-dependent RF prototyping.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for laminate shipments from Taiwan and Japan. Supply concentrates in China, Taiwan, and Japan, with high-frequency laminates drawing from specialized substrate suppliers in Chubu and Tokyo-Osaka clusters. Single-source vulnerability runs through Taiwan-sourced materials subject to geopolitical shipping disruptions. Distribution runs through platform-managed supplier networks for midsize automation equipment manufacturers and direct vendor relationships for aerospace and medical device developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic prototyping functions as a defensive-moat market where regulatory entrenchment in REACH and RoHS compliance documentation creates sticky supplier relationships. Switching costs escalate for buyers who have integrated pre-certified component libraries into CAD workflows.
For Market Incumbents: Secure curriculum-aligned development kit partnerships with university engineering departments to capture recurring revenue streams. Defend against cloud-based platform disintermediation by investing in captive cleanroom capabilities for sub-0.075 millimeter impedance-controlled routing. Capacity addition in Baden-Württemberg reinforces proximity to Stuttgart automotive clusters.
For New Entrants and Emerging Players: Differentiate on RF and optical specialization for satellite communications programs, where technical barriers protect pricing power. Target educational institutions as the most penetrable segment, embedding software-defined instrumentation into core fabrication courses. Go-to-market through curriculum development partnerships rather than transactional component sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform operators with subscription-based procurement consolidation. Long-term viability over a multi-year horizon favors technical specialists with cleanroom infrastructure over commodity fabricators facing margin compression. Acquisition target archetype: mid-cap RF boutiques with ITAR-compliant facilities. Watch semiconductor export control expansion as the inflection indicator for cross-border collaboration model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Component Library Expansion | Pre-certified documentation APIs integrate with Siemens and Autodesk CAD tools, compressing design-to-quote timelines for automotive procurement teams. |
| Cloud Platform Subscription Consolidation | Guaranteed capacity allocation contracts capture 60-70 percent of prototype spend from Baden-Württemberg automation equipment manufacturers. |
| Cleanroom RF Specialization Investment | Impedance-controlled routing below 0.075 millimeters opens premium pricing tiers for satellite communications programs with limited vendor alternatives. |
| Educational Institution Embedded Programs | Curriculum-aligned development kit partnerships generate recurring revenue streams as university engineering departments expand hands-on fabrication requirements. |
| Additive Manufacturing Capability Addition | Aerosol jet and laser-direct structuring systems decompose minimum order quantity barriers for medical device and aerospace rapid-turn flex circuit iterations. |
Research Methodology
Cross-validation between primary interviews with PCB fabrication plant managers, automotive electronics procurement leads, university engineering department heads, and RF test-lab directors and secondary sources anchors the qualitative findings. SEC 10-K filings from electronic manufacturing service providers, ECHA REACH substance databases, FCC equipment authorization records, and IHS Markit automotive production data provide quantitative grounding. Bottom-up demand aggregation across end-user segments triangulates with top-down market sizing from trade flow analysis.
Sensitivity analysis around semiconductor export control scenarios and laminate supply disruption probabilities shapes the analytical framework. Modeled segmentation spans product type complexity tiers, end-user procurement sophistication levels, application-specific regulatory checkpoint density, and geographic production cluster concentration. CAGRs derive from fitted growth curves adjusted for technology substitution effects and compliance cost trajectories. Key inputs include cloud platform adoption rates in German industrial corridors and educational institution embedded program expansion.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment and stable REACH enforcement would require recalibration. Forecasts reflect documented assumptions regarding laminate supplier geographic concentration and platform subscription penetration curves. Semiconductor export control escalation, EPA hazardous waste disposal rule tightening, or cloud platform market consolidation could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
System on Module (Som) Market