
 Middle East and Africa Electric Drives Market | 2026-2036
Middle East and Africa Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electric Drives Market Outlook
Automation engineering talent shortages across the Gulf states are reorganizing how system integrators and end-users deploy electric drive infrastructure. ABB leverages its regional service footprint to anchor large oil and gas retrofit programs. Siemens competes through localized manufacturing partnerships that sustain shorter lead times for variable frequency drive shipments.
An electric drive comprises a motor paired with power electronics that modulate speed, torque, and rotational direction through controlled voltage and frequency adjustment, typically operating between 0.5 kW and 20 MW depending on industrial load requirements. Variable Frequency Drive technology dominates new installations across conveyor systems and pump applications where energy recovery justifies capital expenditure. Servo Control segments serve precision manufacturing and automotive assembly lines where positioning accuracy below 0.1 degrees remains critical. AC Motors constitute the mature volume base, while Servo Motors capture expanding margin pools in automated material handling.
Saudi Standards, Metrology and Quality Organization (SASO) efficiency mandates and UAE's Emirates Authority for Standardization and Metrology (ESMA) industrial equipment codes are tightening minimum performance thresholds for motor-drive systems imported into Gulf markets. South Africa's National Regulator for Compulsory Specifications (NRCS) applies parallel energy efficiency labeling that shapes procurement criteria for mining and mineral processing operators. Stakeholders must weigh regional certification divergence against platform standardization strategies as compliance costs compound across multi-country project portfolios.
Market Dynamics
The Gulf Cooperation Council's industrial energy efficiency mandates are compressing payback periods for electric drive retrofits while simultaneously tightening compliance windows for petrochemical operators.
Growth Catalysts
- SASO Efficiency Mandates:Saudi Arabia's tightening motor performance standards are forcing wholesale replacement of legacy fixed-speed systems across Jubail's industrial corridor.
- Upstream Optimization:Oil and gas operators across the Eastern Province are deploying variable frequency drives to cut pumping energy intensity at brownfield extraction sites.
- AC Motor Volume Base:The mature installed base of induction motors creates predictable replacement demand as efficiency tiers ratchet upward.
Market Restraints
- Copper and Rare Earth Input Volatility:Permanent magnet servo motors face cost pressure from neodymium supply concentration in Chinese processing facilities.
- Technical Talent Scarcity:Automation engineering skill gaps across the Gulf states extend commissioning timelines and inflate system integrator rates.
- Regulatory Divergence:Parallel SASO, ESMA, and NRCS certification requirements fragment platform standardization for multi-country project portfolios.
Strategic Opportunities
- South African Mining Retrofit:NRCS energy labeling is reshaping procurement criteria for mineral processing operators with concentrated fixed-speed motor bases.
- Servo-Conveyor Convergence:Automated material handling in automotive assembly is creating margin expansion for precision positioning systems below 0.1 degrees accuracy.
- Midstream Pipeline Electrification:UAE pump station operators are piloting integrated drive-motor packages for remote desert infrastructure.
Industry Challenges
- Commissioning Engineering Bottlenecks:Scarce field service capacity across Yanbu's petrochemical cluster delays startup schedules for complex multi-drive installations.
- Legacy Control Integration:Brownfield sites with 1980s-era SCADA architectures face protocol translation complexity when adding modern Ethernet-capable drives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electric Drives Market |
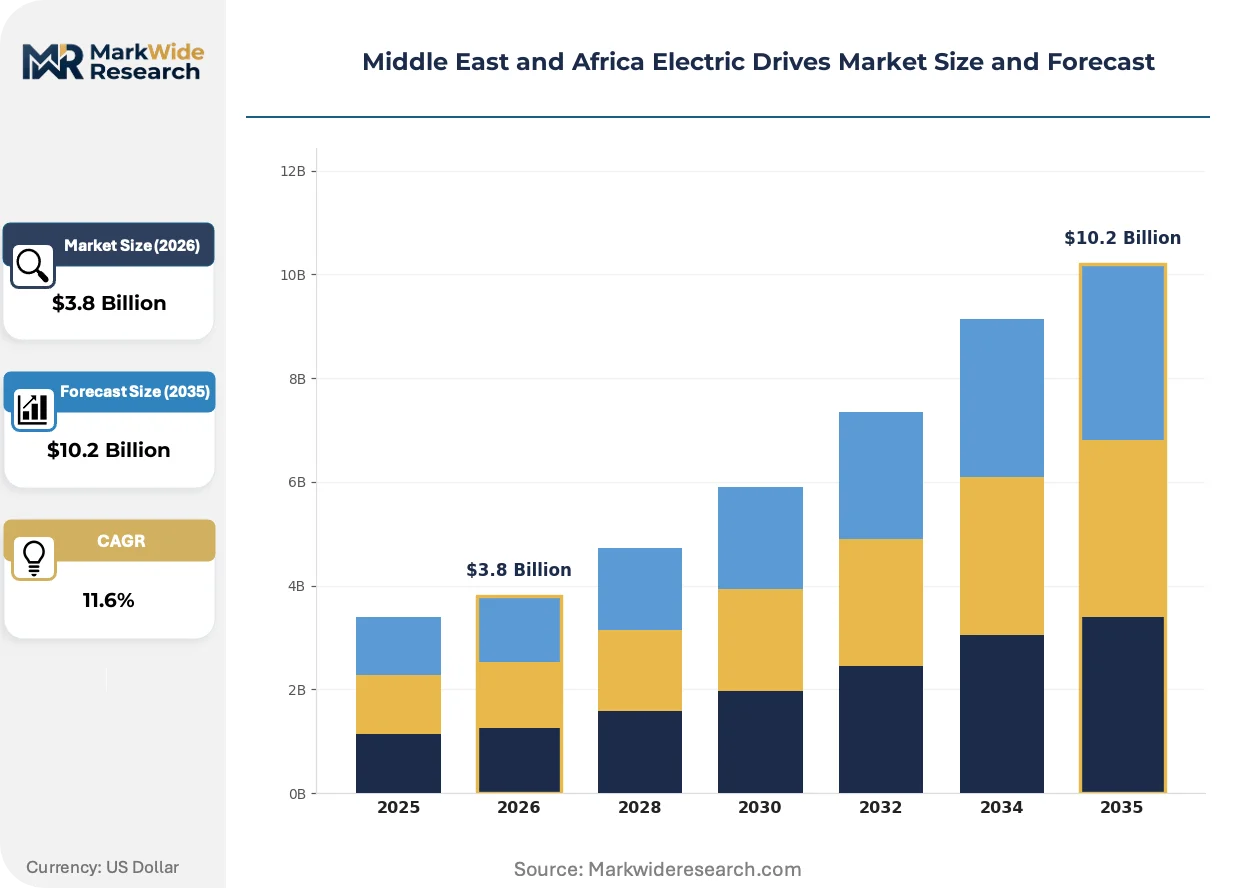
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors End User: Manufacturing, Oil & Gas, Automotive, Renewable Energy Technology: Variable Frequency Drive, Direct Torque Control, Servo Control, Dynamic Braking Application: Conveyor Systems, Pumps, Compressors, Fans |
| Companies Covered | ABB, Siemens, Schneider Electric, Danfoss, Mitsubishi Electric, Rockwell Automation, Fuji Electric, Eaton, WEG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electric Drives Market Strategic Shifts
Digital twin integration and edge analytics are reshaping how electric drive systems are specified, commissioned, and maintained across Middle Eastern industrial corridors.
Silicon carbide power semiconductors are fragmenting traditional insulated-gate bipolar transistor architectures in variable frequency drives above 100 kW. Saudi Aramco's upstream operators are piloting these converters for subsea pump applications where switching losses determine thermal management costs. The technology is fragmenting vendor roadmaps as incumbents face capex-intensive fab transitions.
ESMA's industrial equipment efficiency codes are compressing import windows for non-compliant motor-drive systems into the UAE. The regulation forces distributors to clear legacy inventory ahead of enforcement phases. Petrochemical EPCs are responding by pre-qualifying only tier-one suppliers with established Gulf certification histories.
Service contract unbundling is separating hardware procurement from commissioning and lifecycle maintenance across the Eastern Province. End-users are negotiating drive purchases directly with manufacturers while outsourcing startup to specialized system integrators. This pattern is most visible in Yanbu's downstream complexes where project finance structures favor capital-light operational expenditure models.
Middle East and Africa Electric Drives Market Segmentation
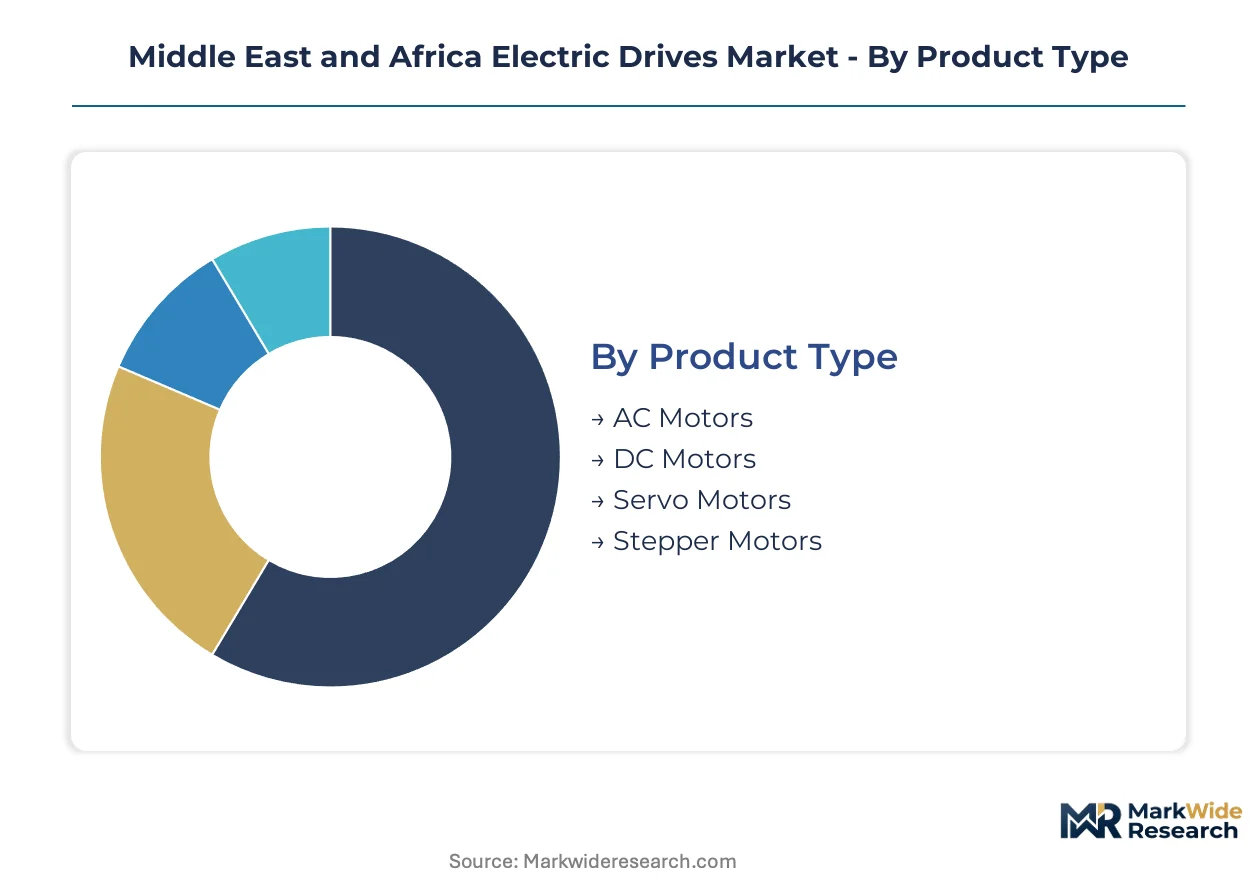
Segmentation of the Middle East and Africa Electric Drives Market reveals distinct procurement patterns across regulatory jurisdictions. SASO efficiency mandates in Saudi Arabia and ESMA codes in the UAE reshape demand concentration within each product and technology category.
Product Type:
SASO motor efficiency tiers and ESMA import windows differentiate procurement volumes across motor architectures in Saudi Arabia and the UAE.
- AC Motors:Induction motor designs dominate retrofit cycles across Jubail's petrochemical corridor as fixed-speed replacement demand concentrates here. Saudi Aramco upstream operators specify these for pump applications where efficiency tier upgrades justify capital deployment against compressed payback periods.
- Servo Motors:Permanent magnet synchronous designs capture precision positioning demand in UAE automotive assembly lines where accuracy below 0.1 degrees remains critical. Neodymium supply concentration through Chinese processing facilities constrains cost structures for Gulf distributors.
- DC Motors:Brushed and brushless architectures persist in legacy mining equipment across South Africa's platinum belt.
- Stepper Motors:Hybrid stepper configurations serve discrete positioning tasks in packaging machinery installations.
Established volume favors AC Motors; emerging adoption favors Servo Motors.
End User:
Customer type determines specification complexity and service contract structures across the Eastern Province and UAE industrial zones.
- Oil & Gas:Upstream operators across Saudi Arabia's Eastern Province deploy variable frequency drives for artificial lift and subsea pump optimization. Brownfield extraction sites generate concentrated retrofit demand as energy intensity targets tighten.
- Manufacturing:Automated material handling in UAE free zones drives servo control adoption for conveyor precision. Procurement teams negotiate unbundled contracts separating hardware from commissioning services.
- Automotive:Assembly line electrification in Dubai's industrial parks specifies integrated drive-motor packages.
- Renewable Energy:Solar tracking systems in Morocco's Noor complex utilize stepper motor arrays.
Procurement scale concentrates in Oil & Gas; specification complexity climbs fastest in Manufacturing.
Technology:
Power semiconductor evolution fragments vendor roadmaps as silicon carbide displaces insulated-gate bipolar transistor architectures above 100 kW.
- Variable Frequency Drive:Voltage-source inverter topologies modulate motor speed through pulse-width modulation across Saudi pump stations. Switching loss reduction determines thermal management costs in desert installations.
- Servo Control:Closed-loop position feedback systems enable precision below 0.1 degrees in UAE automotive conveyor applications. Commissioning engineering bottlenecks extend startup timelines for multi-axis configurations.
- Direct Torque Control:Flux estimation algorithms reduce torque ripple in mining hoist drives.
- Dynamic Braking:Resistive dissipation modules manage regenerative energy in crane and elevator systems.
Deployment breadth favors Variable Frequency Drive; positioning accuracy requirements favor Servo Control.
Application:
Load characteristics determine drive sizing from 0.5 kW through 20 MW across industrial infrastructure.
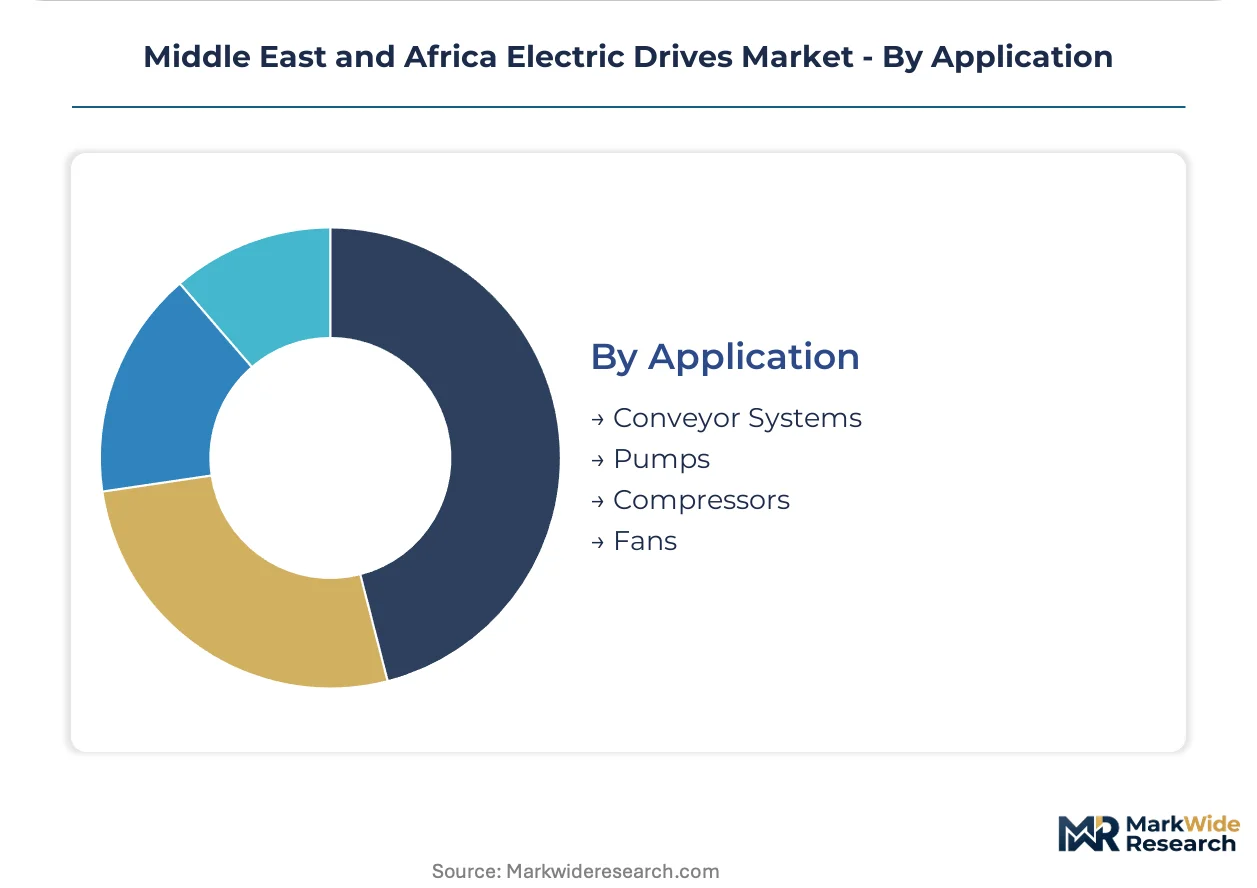
- Pumps:Centrifugal and positive displacement configurations dominate upstream and midstream oil and gas operations. Saudi Aramco pilots silicon carbide converters for subsea applications where thermal management costs constrain conventional designs.
- Conveyor Systems:Belt and roller configurations in UAE logistics hubs specify servo drives for precision indexing. Material handling automation creates margin expansion for positioning systems.
- Compressors:Dynamic and positive displacement types serve petrochemical process gas duties.
- Fans:Axial and centrifugal designs ventilate underground mining operations.
Energy recovery economics favor Pumps; precision throughput requirements favor Conveyor Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO efficiency mandates anchor Saudi Arabia's regulatory framework for industrial motor systems. The Gulf Cooperation Council's divergent certification requirements fragment procurement strategies across multi-country project portfolios.
Saudi Arabia
Upstream oil and gas operators deploy variable frequency drives for artificial lift optimization across brownfield extraction sites. SASO motor efficiency tiers force wholesale replacement of legacy fixed-speed systems. Jubail and Yanbu industrial corridors concentrate downstream petrochemical retrofit demand.
United Arab Emirates
ESMA industrial equipment codes compress import windows for non-compliant motor-drive systems. Petrochemical EPCs pre-qualify tier-one suppliers with established Gulf certification histories. Dubai's logistics hubs specify servo drives for automated material handling precision.
South Africa
NRCS energy efficiency labeling reshapes procurement criteria for mining and mineral processing operators. The country's national industrial regulator applies parallel standards to motor-drive systems. Platinum belt operations face concentrated fixed-speed motor replacement cycles.
Egypt
Suez Canal industrial zones generate demand for pump and compressor electrification. The country's national standards body aligns equipment import requirements with regional efficiency benchmarks. Cairo-Alexandria corridor manufacturing clusters pilot integrated drive-motor packages.
Morocco
Noor solar complex tracking systems utilize stepper motor arrays for precision positioning. The country's renewable energy agency drives industrial electrification standards adoption. Casablanca-Settat region automotive suppliers specify servo control for assembly line automation.
Middle East and Africa Electric Drives Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa Electric Drives Market. European industrial conglomerates anchor premium-tier positioning through regional service footprints. Asian electrical equipment specialists compete on manufacturing scale and shorter lead times. Strategic moves concentrate on localized production partnerships and unbundled service contract structures.
Within the integrated industrial systems tier, ABB and Siemens represent contrasting geographic anchoring strategies. ABB leverages its regional service infrastructure to anchor large oil and gas retrofit programs. Siemens competes through localized manufacturing partnerships that sustain shorter lead times for variable frequency drive shipments. Schneider Electric occupies a position bridging premium-tier system integration with mid-market volume deployment.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Danfoss |
| Mitsubishi Electric |
| Rockwell Automation |
| Fuji Electric |
| Eaton |
| WEG |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide power semiconductor substitution for insulated-gate bipolar transistors is fragmenting vendor cost structures while redrawing procurement geography toward East Asian wafer fabrication capacity. This technology transition simultaneously elevates upfront converter pricing for end-users and compresses margins for legacy IGBT-dependent suppliers across Gulf industrial corridors.
Pricing Analysis
Variable frequency drive pricing spreads 15-25% between European tier-one suppliers and Asian volume manufacturers across Saudi Arabia and UAE procurement channels. Three-tier pricing structure across premium, standard, and economy levels segments by certification tier and commissioning service bundling. Price erosion runs through standard-tier AC motor drives as Chinese manufacturers expand Middle East distribution partnerships. State-owned oil and gas operators exhibit lowest price sensitivity due to energy recovery payback justification, while South African mining procurement teams prioritize upfront capital minimization.
Supply Chain Analysis
Container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for power electronics modules and rare earth magnet materials. Manufacturing concentration rests on China for neodymium processing, Germany for precision servo components, and Japan for advanced silicon carbide substrates. Permanent magnet servo motors face single-source vulnerability through Chinese rare earth supply concentration. Distribution runs through authorized distributor networks with regional stocking points in Dubai Jebel Ali and Johannesburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Electric Drives Market sits in early-cycle expansion as SASO and ESMA efficiency mandates force wholesale replacement of installed fixed-speed motor bases ahead of compliance deadlines.
For Market Incumbents: Secure commissioning engineering capacity through specialized system integrator partnerships to overcome talent scarcity bottlenecks delaying Yanbu petrochemical startups. Anchor position by pre-qualifying for tier-one EPC supplier lists before ESMA enforcement phases clear legacy distributor inventory. Deepen backward integration into silicon carbide module sourcing to offset Chinese substrate supply concentration.
For New Entrants and Emerging Players: Aftermarket service unbundling presents white-space opportunity where ABB and Siemens retain bundled hardware-commissioning structures. Target South African mining retrofit demand where NRCS energy labeling reshapes procurement criteria for fixed-speed replacement. Penetrate through outcome-based energy savings contracts that transfer efficiency risk from capital-constrained operators.
For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated specialists with Gulf certification histories. Long-term viability centers on platform standardization strategies that amortize compliance costs across multi-country project portfolios. Watch silicon carbide adoption rates in Saudi Aramco upstream pilots as inflection signal for technology roadmap winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Partnership | Siemens' UAE assembly operations compress variable frequency drive lead times for ESMA-compliant shipments. |
| Service Contract Unbundling | Yanbu petrochemical operators now separate hardware procurement from specialized commissioning outsourcing. |
| Silicon Carbide Converter Pilot | Saudi Aramco subsea pump trials validate next-generation thermal management for desert installations. |
| Certification Pre-Qualification | Petrochemical EPCs now filter supplier lists to tier-one vendors with established SASO compliance histories. |
| System Integrator Acquisition | Automation engineering scarcity is forcing drive manufacturers to acquire commissioning capability in-house. |
Study Parameters
Desk research of trade customs data, SASO technical regulation filings, and EPC contractor procurement disclosures preceded structured interviews with plant engineers, aftermarket service directors, and petrochemical project procurement leads. Primary fieldwork across Jubail and Yanbu industrial corridors captured brownfield retrofit specification patterns. Secondary validation drew from Gulf Cooperation Council energy efficiency program documentation, NRCS equipment registry data, and silicon carbide semiconductor supply chain disclosures. Bottom-up unit economics triangulated against top-down regulatory mandate penetration assumptions.
Variance decomposition across product type, end-user vertical, power rating tier, and regional regulatory jurisdiction shaped the analytical framework. Modeled segmentation spanned motor architecture, control technology, and application load characteristics throughout the forecast period. CAGRs derived from replacement cycle timing against efficiency tier ratchet schedules, with scenario weighting for copper and rare earth input cost trajectories. Forecast inputs incorporated commissioning engineering capacity constraints and distributor inventory clearance patterns ahead of ESMA enforcement windows.
Underlying assumptions cover regulatory compliance timeline adherence, rare earth supply continuity, and Gulf state industrial capital allocation priorities, with deviation risk concentrated in neodymium price volatility and automation talent migration patterns. Recalibration cycles align with material shifts in SASO efficiency tier implementation schedules and silicon carbide manufacturing scale-up milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Contactors Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
GCC Ceiling Fan Market