
 Motor Control IC Market | 2026-2036
Motor Control IC Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Control IC Market Outlook
Modular motor control IC platforms that bundle gate drivers, microcontrollers, and power stages into configurable stacks is rebalancing how OEMs evaluate total cost of ownership against discrete component flexibility. Infineon Technologies leverages its SiC and GaN power portfolio to anchor high-voltage traction applications across European automotive programs. Texas Instruments competes through extensive analog integration that reduces external BOM count for mid-tier industrial drives. STMicroelectronics specializes in sensorless control algorithms that trim encoder costs from consumer appliance motors.
A motor control IC is a semiconductor device that governs the speed, torque, or position of electric motors through pulse-width modulation, closed-loop feedback, or vector commutation, typically integrating analog front-ends, digital signal processors, and power output stages in die areas ranging from a few square millimeters to multi-chip modules. Its primary purpose is to convert electrical energy into precisely governed mechanical motion while minimizing switching losses and electromagnetic interference. Digital ICs with embedded ARM cores are capturing margin pools as firmware-defined control replaces fixed-function analog alternatives. Field-oriented control technology leads in performance-critical robotics and servo positioning where dynamic response requirements exceed what scalar PWM methods deliver. Power ICs remain the volume backbone across consumer appliance and HVAC compressor applications where cost sensitivity dominates design priorities.
The US EPA and NHTSA coordinate motor efficiency and electrification standards that determine which control architectures qualify for automotive and appliance compliance programs. China's MIIT enforces GB motor efficiency tiers that force IC suppliers to certify new products against progressively stricter loss metrics. The EU Ecodesign Directive and F-Gas Regulation indirectly shape motor control IC demand by mandating compressor efficiency upgrades in refrigeration and heat pump systems. Stakeholders must monitor how regional efficiency mandates diverge in stringency and test methodology, as compliance fragmentation will determine which integrated control platforms achieve multi-region scale.
Market Dynamics
Field-oriented control architectures are displacing scalar PWM methods across high-performance motor applications, compressing development timelines for robotics and electric vehicle powertrain programs while elevating firmware-defined control platforms over fixed-function analog alternatives.
Growth Catalysts
- China's GB motor efficiency standards:MIIT certification tiers force IC suppliers to redesign power stages for progressively stricter loss metrics, accelerating replacement cycles in industrial drives and appliance compressors.
- GaN power integration:Wide-bandgap semiconductors slash switching losses in high-frequency inverter stages, enabling compact motor drives for drone propulsion and surgical tool applications.
- Germany's industrial automation corridor:Munich-Stuttgart manufacturing density concentrates demand for precision servo control in automotive assembly and machine tool retrofit programs.
Market Restraints
- Silicon carbide substrate costs:SiC wafer prices remain elevated versus silicon alternatives, constraining adoption in cost-sensitive appliance and HVAC compressor segments.
- Foundry concentration in Taiwan:Advanced BCD process capacity for integrated gate drivers concentrates at TSMC and UMC, exposing supply continuity risks during geopolitical disruptions.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for automotive traction inverters extends development cycles by 18-24 months versus industrial-grade equivalents.
Strategic Opportunities
- India's PLI scheme for electric mobility:Production-linked incentives for domestic EV manufacturing create captive demand for localized motor control IC sourcing and joint development partnerships.
- Sensorless control algorithm advances:Elimination of optical encoders from consumer appliance motors opens margin expansion in washing machine and refrigerator compressor platforms.
- EU F-Gas Regulation phase-down:Refrigerant transition mandates drive compressor efficiency upgrades, requiring adaptive control ICs that optimize variable-speed operation across refrigerant property ranges.
Industry Challenges
- Mixed-signal design talent scarcity:Expertise spanning analog power stages, digital signal processing, and thermal management concentrates at established IDMs, constraining fabless entrants.
- Legacy industrial fieldbus integration:EtherCAT and PROFINET protocol stacks demand specialized communication peripherals that fragment firmware development resources across customer-specific implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Control IC Market |
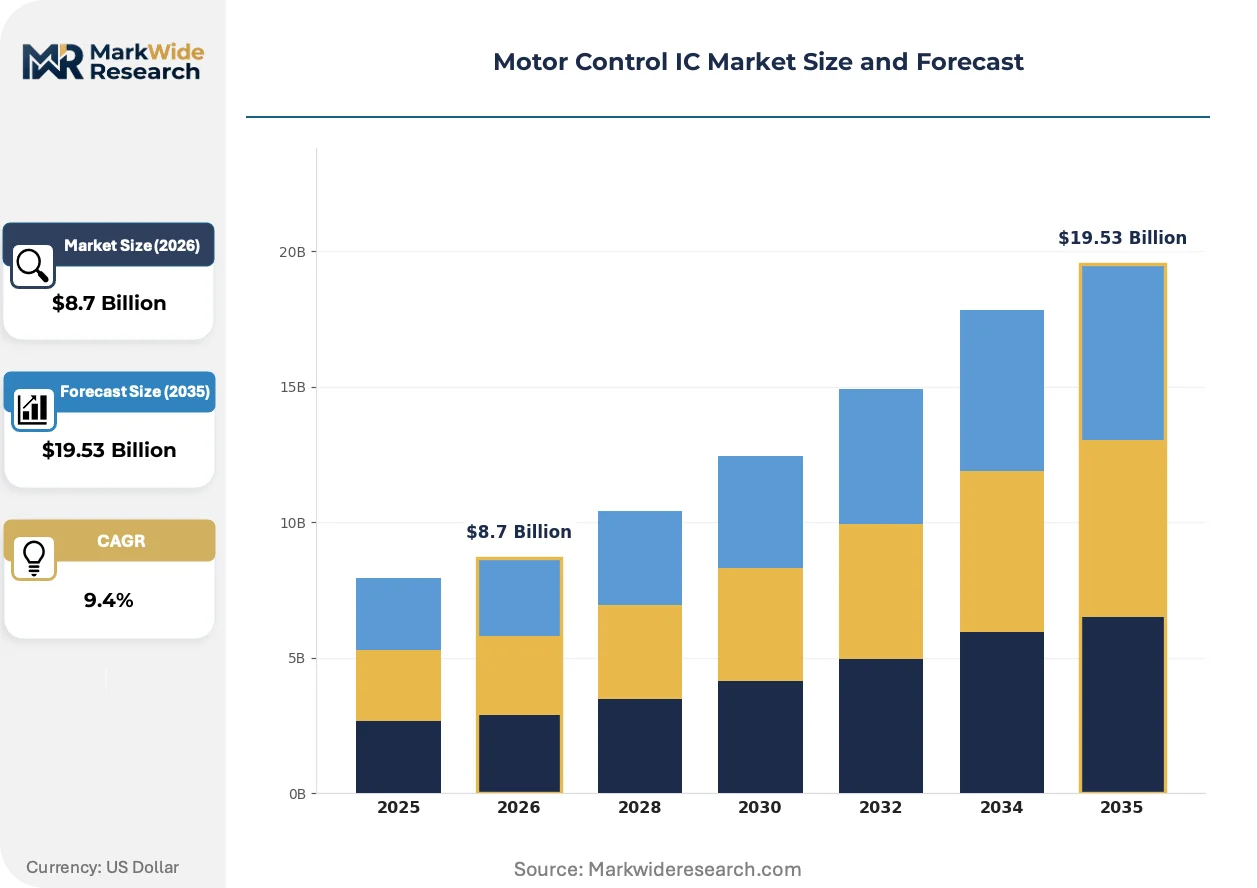
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear ICs, Digital ICs, Power ICs, Integrated Circuits Technology: Analog Control, PWM Control, Sensorless Control, Field-Oriented Control End User: Automotive, Consumer Electronics, Industrial Automation, Robotics Application: Electric Motors, DC Motors, Stepper Motors, Servo Motors |
| Companies Covered | NXP Semiconductors, Microchip Technology, Texas Instruments, Renesas Electronics, Analog Devices, Infineon Technologies, ON Semiconductor, Maxim Integrated, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Control IC Market Strategic Shifts
Embedded ARM cores with hardware acceleration for trigonometric operations are redefining control loop performance benchmarks, compressing the gap between discrete DSP solutions and fully integrated SoC architectures across servo and traction applications.
Adaptive flux-weakening algorithms are automating field-weakening parameter tuning that previously required manual calibration by motor specialists. Tier-one automotive suppliers deploy these self-tuning blocks in electric axle programs to reduce variant-specific engineering overhead. The technology is automating the transition from application-specific motor control departments toward platform-standardized firmware libraries that scale across vehicle classes.
The EU Ecodesign Directive's expanding scope to fractional horsepower motors mandates minimum efficiency indices for pumps and fans, forcing IC suppliers to embed loss-optimized commutation modes. Compressor OEMs in Italy and Poland redesign control boards to meet the 2026 tier requirements. Heat pump manufacturers accelerate procurement of variable-speed drives that modulate output rather than cycling on-off, prioritizing ICs with integrated power factor correction.
Consolidated purchasing by white goods multinationals is compressing supplier negotiation cycles from annual to quarterly frameworks, with technical scorecards weighing firmware ecosystem maturity alongside unit pricing. Mid-tier industrial drive vendors respond by unbundling hardware from software licensing, offering subscription-based algorithm updates. This behavioral shift is most pronounced in China's appliance manufacturing belt, where美的 and海尔 procurement teams centralize motor control IC qualification across compressor, washing machine, and air handler product lines.
Motor Control IC Market Segmentation
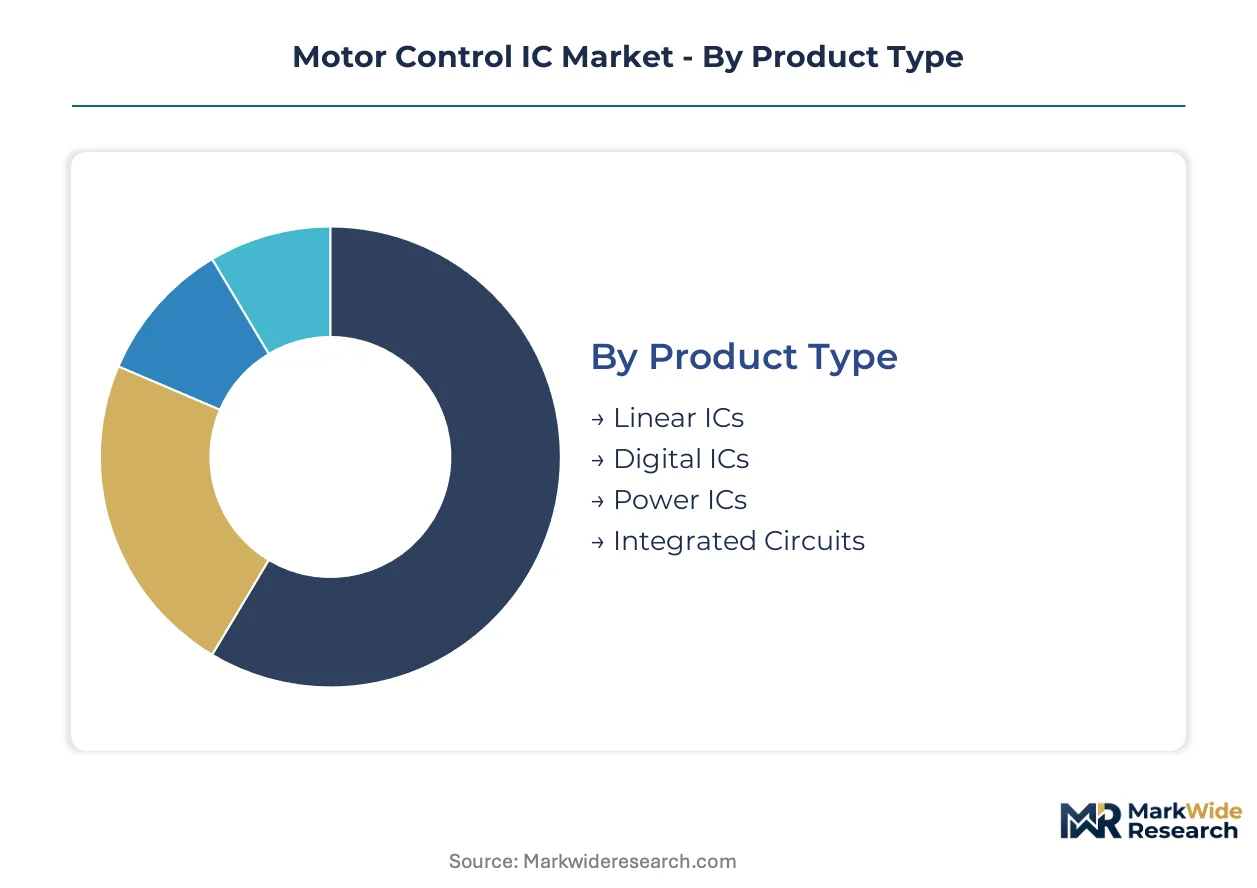
Motor control IC segmentation reveals how certification burdens, performance thresholds, and integration levels partition procurement budgets across automotive traction, industrial servo, and appliance compressor programs. Understanding these fault lines exposes where firmware-defined architectures displace legacy analog alternatives.
Product Type:
Linear ICs demand minimal functional safety documentation for appliance timer circuits, while Digital ICs with embedded ARM cores trigger ISO 26262 ASIL-D timelines for automotive traction inverters. Power ICs face divergent GB efficiency tiers in China versus EPA standby power rules in the US. Integrated Circuits must satisfy REACH substance restrictions for European industrial drives.
- Linear ICs:These devices regulate motor speed through continuous voltage adjustment without digital processing, using operational amplifiers and voltage regulators in die geometries optimized for low electromagnetic interference. Demand concentrates in white goods manufacturing clusters around Qingdao and Ningbo, where washing machine timer circuits and refrigerator damper controls prioritize cost over precision. China's GB motor efficiency standards force incremental redesigns to minimize standby losses.
- Digital ICs:Embedded ARM Cortex-M cores execute field-oriented control algorithms with hardware-accelerated trigonometric operations, enabling sub-millisecond current loop response for servo positioning. Procurement is accelerating across Germany's Munich-Stuttgart automation corridor, where automotive assembly robots and machine tool retrofits demand firmware-tunable parameters. ISO 26262 ASIL-D qualification extends development cycles by 18-24 months versus industrial equivalents.
- Power ICs:Monolithic integration of gate drivers and power MOSFETs in BCD processes targets HVAC compressor and appliance motor volumes.
- Integrated Circuits:Multi-chip modules stacking microcontrollers, pre-drivers, and power stages serve compact drone propulsion and surgical tool applications.
Power ICs sit at the top of the volume ranking, with Digital ICs climbing the fastest.
Technology:
Cost tiers separate scalar PWM methods for commodity appliances from sensorless vector control for mid-tier industrial drives, with field-oriented architectures commanding premium positioning in robotics and EV powertrains.
- Analog Control:Fixed-function op-amp networks generate trapezoidal commutation sequences without software intervention, limiting flexibility but eliminating firmware validation costs. Demand persists in India's cost-sensitive appliance manufacturing under the PLI scheme for electric mobility, where basic fan and pump controls dominate. The technology faces displacement as digital alternatives achieve price parity at equivalent performance points.
- Sensorless Control:Back-EMF estimation algorithms eliminate optical encoders and Hall sensors from consumer appliance motors, trimming bill-of-material costs while maintaining adequate speed regulation. Washing machine and refrigerator compressor platforms in China's manufacturing belt accelerate adoption as美的 and海尔 centralize procurement qualification. Advanced flux-weakening blocks now automate parameter tuning previously requiring motor specialist calibration.
- PWM Control:Scalar pulse-width modulation varies duty cycle to control average voltage applied to motor windings in cost-optimized drives.
- Field-Oriented Control:Vector commutation decouples torque and flux components for dynamic response exceeding scalar methods in servo positioning.
PWM Control retains the largest installed base, though Sensorless Control is gaining share fastest as encoder elimination spreads beyond appliances into pumps and fans.
End User:
Application maturity varies sharply: automotive traction inverters require multi-year qualification cycles, while consumer electronics demands quarterly price renegotiation and rapid firmware iteration.
- Automotive:Traction inverter ICs integrate isolated gate drivers, current sensing, and ASIL-D diagnostic logic for electric axle programs across European and Chinese OEM platforms. NHTSA coordinates with EPA on electrification standards that determine control architecture eligibility for compliance credits. GaN power integration enables compact 800V bus designs, though SiC substrate costs constrain mainstream adoption.
- Industrial Automation:Servo drives for machine tools and packaging equipment demand EtherCAT and PROFINET protocol stacks that fragment firmware development resources. Germany's industrial corridor concentrates precision control procurement, with Munich-Stuttgart manufacturing density driving multi-axis coordination requirements. Legacy fieldbus integration remains a persistent engineering burden.
- Consumer Electronics:White goods multinationals compress supplier negotiation cycles from annual to quarterly frameworks, prioritizing firmware ecosystem maturity alongside unit pricing.
- Robotics:Collaborative and mobile robot joints require compact, high-torque-density motor drives with safety-rated torque limiting.
Industrial Automation leads in average selling price, with Automotive expanding most quickly as EV powertrain programs multiply platform variants.
Application:
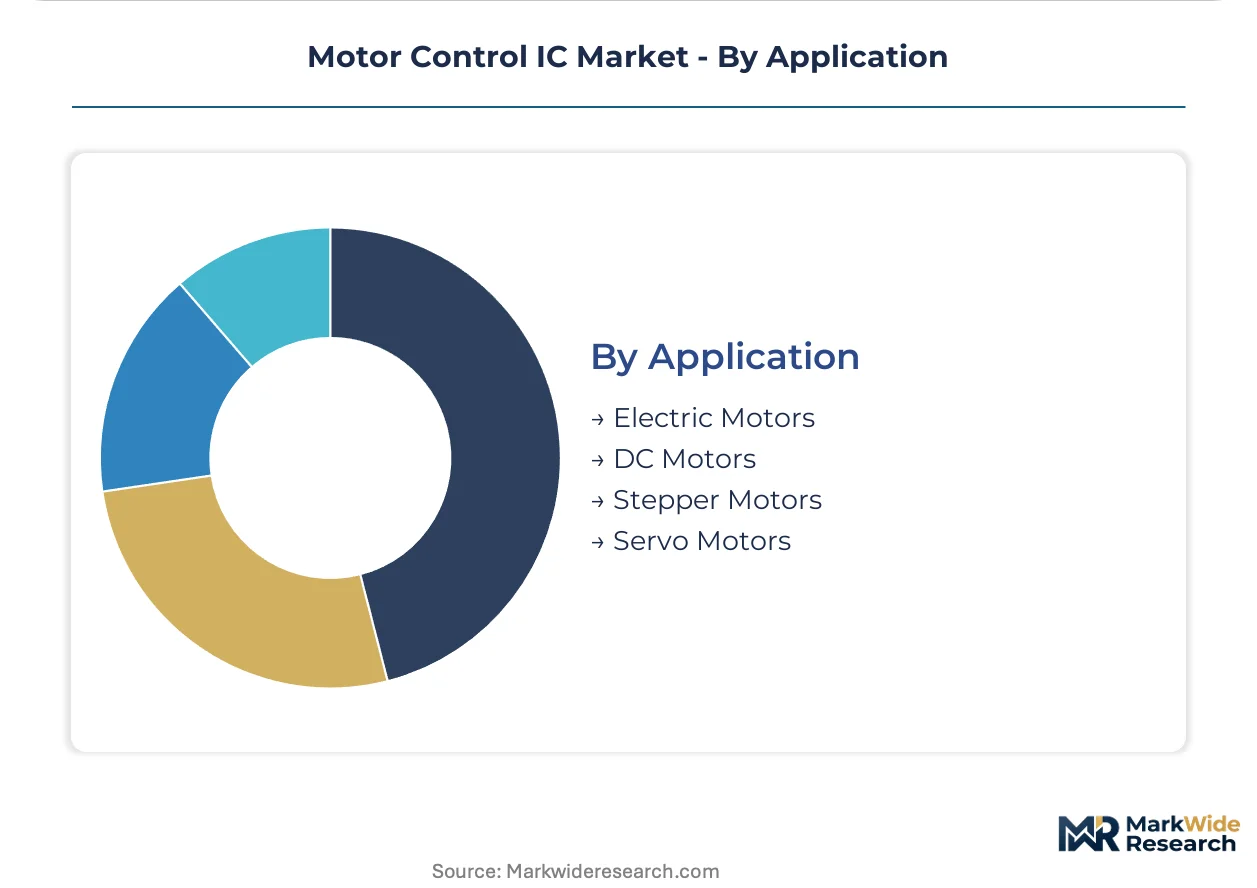
Supply concentration for high-volume DC motor controllers in cordless power tools diverges from fragmented demand for precision servo motors in semiconductor manufacturing equipment.
- Electric Motors:Broad category encompassing induction and synchronous machines in pumps, fans, and compressors subject to EU Ecodesign Directive efficiency mandates. Italy and Poland-based compressor OEMs redesign control boards to meet tier requirements, prioritizing ICs with integrated power factor correction. Variable-speed drives modulate output rather than cycling on-off.
- Servo Motors:Permanent magnet synchronous machines with high-resolution feedback enable sub-arcminute positioning accuracy for CNC machine tools and robotic arms. Demand concentrates in precision manufacturing clusters where dynamic response requirements exceed induction motor capabilities. Field-oriented control technology leads performance-critical applications.
- DC Motors:Brushed and brushless permanent magnet designs power automotive auxiliary systems and battery-operated tools.
- Stepper Motors:Open-loop position control without feedback suits 3D printers, textile machinery, and laboratory automation.
Electric Motors dominate unit volumes, with Servo Motors showing the steepest expansion trajectory as robotics and precision manufacturing accelerate replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The motor control IC industry traces its commercial roots to German industrial automation engineering and American automotive electronics manufacturing, with subsequent scaling across East Asian semiconductor fabrication corridors. Today procurement patterns concentrate in three continental manufacturing belts.
Germany
Precision servo drives for automotive assembly robots and machine tool retrofits dominate procurement across Bavaria and Baden-Württemberg. The KBA coordinates with EU Ecodesign Directive implementation timelines that determine compressor control board redesign cycles. Munich-Stuttgart manufacturing density drives multi-axis coordination requirements for EtherCAT-enabled servo systems.
China
MIIT dual carbon goals and GB motor efficiency tiers force IC suppliers to certify power stages against progressively stricter loss metrics. Qingdao and Ningbo appliance manufacturing clusters accelerate replacement cycles for washing machine timer circuits and refrigerator damper controls.美的 and海尔 procurement teams centralize motor control IC qualification across compressor and air handler product lines.
United States
EPA standby power rules and NHTSA electrification standards determine which control architectures qualify for automotive compliance credits. Detroit-area automotive suppliers and Austin semiconductor design houses anchor traction inverter development programs. GaN power integration enables compact 800V bus designs for electric axle platforms.
India
PLI scheme production-linked incentives for domestic EV manufacturing create captive demand for localized motor control IC sourcing. Basic fan and pump controls dominate cost-sensitive appliance manufacturing under analog control architectures. Gujarat and Maharashtra industrial corridors attract joint development partnerships for electric two-wheeler powertrains.
Japan
METI energy efficiency standards and JIS certification requirements shape industrial drive procurement specifications. Nagoya-area automotive suppliers and Tokyo precision equipment manufacturers demand sensorless vector control for high-torque-density applications. Robotics OEMs prioritize compact motor drives with safety-rated torque limiting for collaborative robot joints.
Motor Control IC Market Competitive Environment
The competitive structure tilts toward integrated device manufacturers with captive fabrication capacity and deep analog-digital mixed-signal expertise. Market concentration reflects high barriers to entry spanning functional safety certification, BCD process access, and firmware ecosystem maturity. Two strategic archetypes dominate: diversified semiconductor conglomerates with automotive qualification track records, and specialized motor control houses with vertical integration into power stage design. Competitive moves center on strategic partnerships for GaN and SiC supply security, plus portfolio diversification into sensorless algorithm IP.
Among European-anchored IDMs, Infineon Technologies and STMicroelectronics exemplify the diversified conglomerate archetype with automotive traction qualifications. Texas Instruments represents the analog integration specialist position with extensive BOM reduction capabilities for mid-tier industrial drives. NXP Semiconductors occupies a hybrid position bridging automotive functional safety and industrial communication protocol stacks.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Microchip Technology |
| Texas Instruments |
| Renesas Electronics |
| Analog Devices |
| Infineon Technologies |
| ON Semiconductor |
| Maxim Integrated |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
IDM conglomerates with captive fabrication capacity anchor supply-side discipline, translating process-node advantages into pricing power across automotive traction and industrial servo tiers while compressing margins for fabless competitors dependent on foundry spot pricing.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-grade, and appliance-grade certification levels stratifies procurement budgets, with ISO 26262 ASIL-D qualification commanding substantial premiums over industrial equivalents. Price differentiation hinges on functional safety documentation depth and GB efficiency tier compliance in China. Cost compression in consumer appliance segments intensifies as white goods multinationals consolidate purchasing power. Appliance OEMs in China's manufacturing belt exhibit highest price sensitivity, while German automotive suppliers prioritize firmware ecosystem maturity over unit economics.
Supply Chain Analysis
India's PLI scheme domestic-content mandates and China's MIIT localization requirements are reshaping sourcing patterns for electric mobility programs, forcing tier-one suppliers to qualify secondary foundry partners outside Taiwan. Advanced BCD process capacity for integrated gate drivers concentrates in Taiwan, South Korea, and the United States. Silicon carbide substrates, gallium nitride epitaxy, and 300mm silicon wafers constitute critical input dependencies. Single-source vulnerability at TSMC and UMC for automotive-grade BCD nodes exposes continuity risks during geopolitical disruptions. Distribution runs through authorized distributors serving tier-one automotive suppliers and direct OEM contracts for appliance compressor volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Motor Control IC Market reads as a late-cycle quality story as EV powertrain programs shift procurement toward ASIL-D qualified platforms with embedded ARM cores and sensorless algorithm IP.
For Market Incumbents: Hedge against fabless encroachment by securing captive supply of silicon carbide substrates through long-term offtake agreements with substrate manufacturers, while accelerating sensorless control algorithm patent filings to defend margin position against algorithm-licensing competitors. Reinforce firmware ecosystem stickiness through quarterly update cadences that match美的 and海尔 procurement cycles. For New Entrants and Emerging Players: Enter via India's PLI scheme electric two-wheeler powertrain corridor, where localized joint development partnerships face lower qualification barriers than German automotive programs. Target sensorless control modules for washing machine and refrigerator compressor platforms in China's appliance manufacturing belt, where encoder elimination creates white-space demand. Pursue white-label firmware licensing to mid-tier industrial drive vendors unbundling hardware from software. For Investors and Strategic Acquirers: Valuations sit cheapest among mixed-signal design houses with sensorless algorithm IP and existing GB efficiency tier certifications. Long-term viability favors acquisition targets with demonstrated automotive functional safety track records and established relationships with Germany's Munich-Stuttgart automation corridor. Monitor ASIL-D qualification timeline compression as the inflection signal indicating competitive moat erosion for incumbent IDMs.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Stage Integration | Enables compact 800V traction inverters for European EV platforms while slashing switching losses. |
| Sensorless Algorithm Patent Portfolio | Captures margin pools from encoder elimination across China's appliance manufacturing belt. |
| ASIL-D Certification Investment | Qualifies platforms for NHTSA electrification compliance credits in Detroit-area automotive programs. |
| India PLI Joint Development Partnership | Localizes sourcing for Gujarat and Maharashtra electric two-wheeler powertrain corridors. |
| Foundry Diversification Program | Mitigates TSMC concentration risk by qualifying secondary BCD capacity at UMC and domestic alternatives. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IC design engineers, automotive platform procurement managers, appliance OEM sourcing directors, and industrial drive firmware architects with secondary validation against SEC 10-K filings, MIIT certification databases, EU Ecodesign Directive implementation records, and semiconductor trade flow data. Bottom-up bill-of-material modeling across traction inverter and servo drive platforms triangulated against top-down OEM procurement budget allocations.
Historical reference periods spanning the pre-pandemic baseline through recent supply disruption quarters anchored the forecast window, with CAGRs derived from segment-level growth rate reconciliation across product type, technology, end user, and application dimensions. Modeled variables included ARM core penetration rates, GaN power stage adoption curves, ASIL-D qualification timelines, and GB efficiency tier compliance deadlines. Industry-specific inputs captured foundry capacity expansion announcements, PLI scheme disbursement schedules, and F-Gas Regulation phase-down milestones.
Inputs from automotive tier-one suppliers and white goods multinationals were available through the study window; gaps in fabless startup financial disclosures and privately held foundry utilization rates introduce uncertainty bands around sensorless control and emerging technology segments. Forecasts reflect documented assumptions regarding MIIT enforcement consistency and Taiwan semiconductor policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Isolated Interface Chip Market