
 Over the Air Engine Control Module Market | 2026-2036
Over the Air Engine Control Module Market Size, Share, and Industry Trends Forecast 2026-2036
Over the Air Engine Control Module Market Analytics
German automotive electronics manufacturing is consolidating as tier-one suppliers scale OTA validation facilities across Bavaria and Baden-Württemberg. Robert Bosch GmbH leverages its embedded software heritage to anchor cloud-to-vehicle firmware pipelines for European OEMs. Continental AG sustains R&D intensity in secure boot architectures and differential update protocols. NXP Semiconductors dominates automotive-grade secure element supply for ECU authentication chains.
Over the Air Engine Control Module systems enable wireless reprogramming of engine control unit firmware without physical workshop access, typically transmitting encrypted binary packages through cellular or Wi-Fi channels with rollback safeguards. These modules serve the primary commercial purpose of reducing recall costs and enabling continuous emissions compliance across distributed vehicle fleets. The technology dimension shows firmware updates generating the deepest margin pools due to recurring software licensing structures, while remote diagnostics expands fastest among fleet operators seeking predictive failure detection. Application segmentation reveals predictive maintenance commanding premium pricing as uptime guarantees become contractually embedded in fleet service agreements.
The UNECE WP.29 cybersecurity regulation shapes OTA system architecture by mandating intrusion detection and secure update verification for type-approved vehicles in Europe. The EPA and NHTSA in the United States enforce emissions compliance and software disclosure requirements that drive OEM investment in traceable OTA audit trails. Stakeholders must monitor evolving type-approval reciprocity between regulatory regimes as cross-border software update deployment becomes standard operating procedure.
Market Dynamics
Commercial fleet operators now mandate continuous emissions compliance across distributed vehicle pools, forcing OEMs to architect cloud-native firmware pipelines that eliminate physical service bay bottlenecks. UNECE WP.29 cybersecurity mandates tighten software traceability requirements, compressing update verification timelines and reshaping supplier qualification protocols.
Growth Catalysts
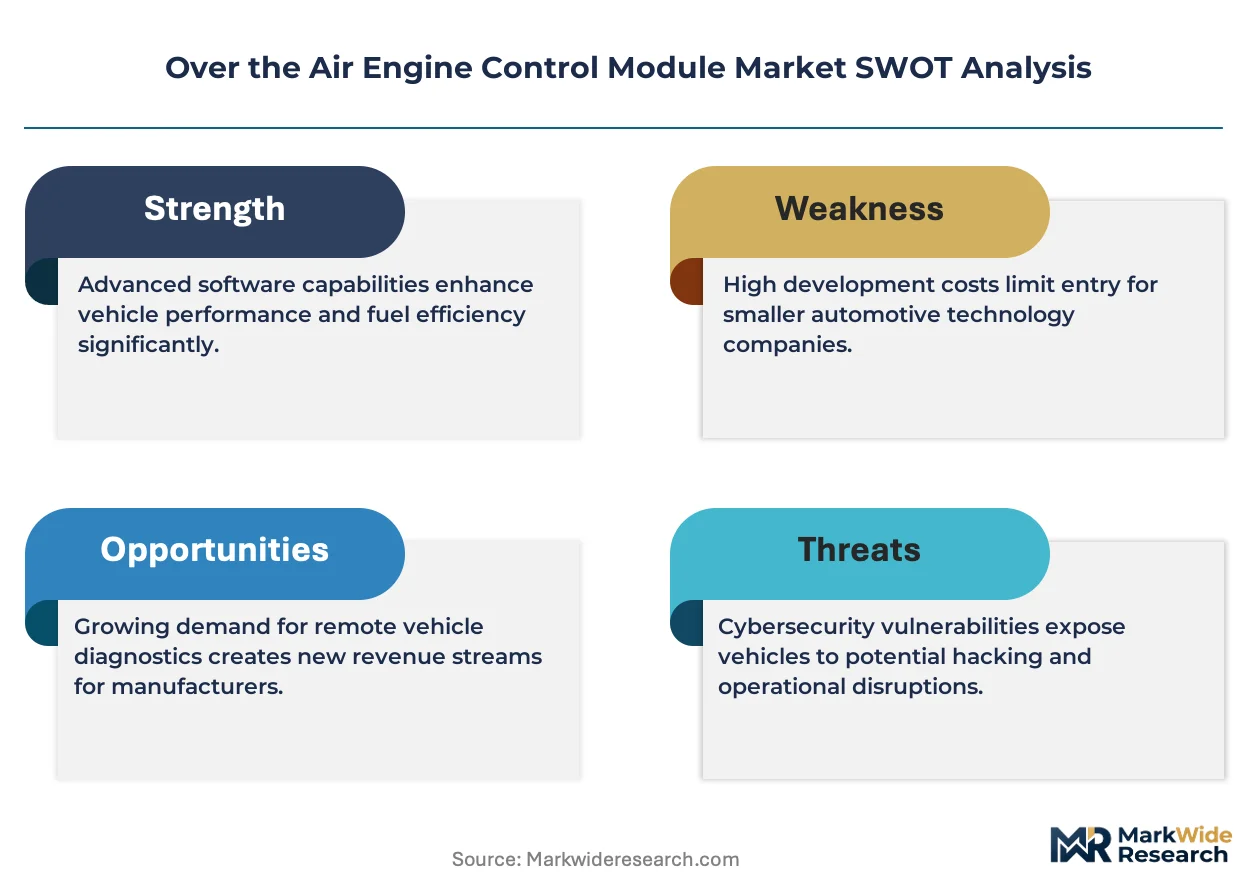
- UNECE WP.29 Regulation:Mandates intrusion detection and secure update verification for type-approved vehicles in Europe, compelling OEMs to fund OTA infrastructure investments that lock in recurring software licensing revenue streams.
- Commercial Fleet Operators:Demand predictive failure detection and uptime guarantees embedded in service contracts, converting maintenance from reactive cost centers to contracted performance outcomes.
- Differential Update Protocols:Enable transmission of compressed binary deltas rather than full firmware images, reducing cellular data consumption and expanding viable deployment to bandwidth-constrained markets.
Market Restraints
- Automotive-Grade Secure Element Supply:Concentration among specialty semiconductor foundries creates authentication chain bottlenecks, with qualification cycles extending component lead times.
- Legacy ECU Hardware Architectures:Pre-2020 engine control units lack sufficient onboard memory and processing headroom to support modern cryptographic verification routines, fragmenting addressable vehicle populations.
- Cross-Border Type-Approval Reciprocity Gaps:Divergent software disclosure requirements between EPA and NHTSA jurisdictions force redundant certification expenditures that inflate per-market deployment costs.
Strategic Opportunities
- India Commercial Vehicle Segment:BS-VI emissions enforcement and PLI scheme incentives for automotive electronics create first-mover advantage for OTA platforms targeting domestic truck and bus manufacturers.
- Edge-to-Cloud AI Convergence:Integration of onboard inference engines with centralized fleet analytics enables predictive calibration adjustments that anticipate component degradation before fault codes trigger.
- Subscription-Based Diagnostics:Remote monitoring services bundled with firmware updates transform one-time hardware sales into recurring revenue relationships with fleet management companies.
Industry Challenges
- Embedded Cryptography Talent Scarcity:Shortage of engineers proficient in automotive secure boot architectures and side-channel attack mitigation extends development timelines for tier-one suppliers.
- Multi-Generational ECU Integration:Heterogeneous vehicle fleets mixing legacy and modern control modules complicate rollback safeguard design and expand testing matrix complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over the Air Engine Control Module Market |
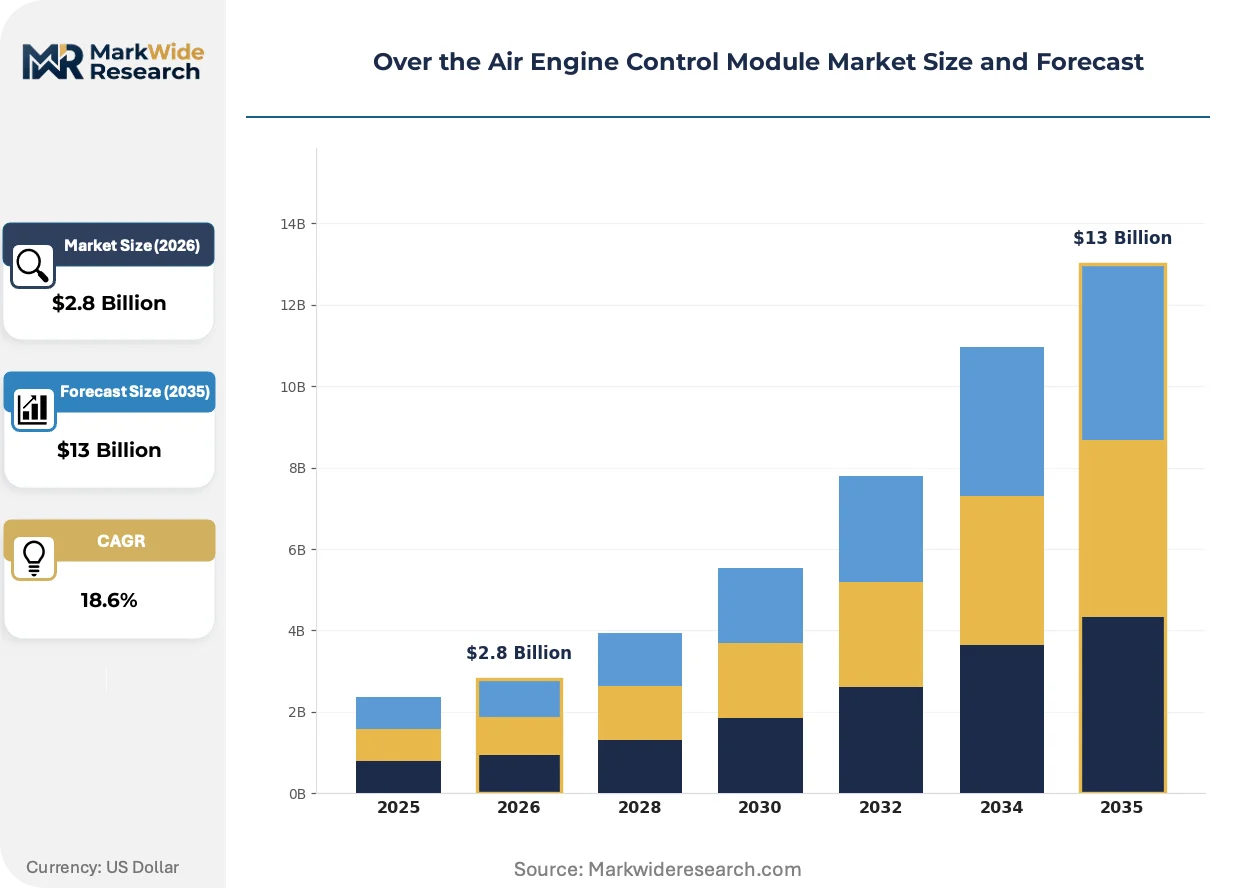
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Remote Diagnostics, ECU Calibration, Firmware Updates, Performance Monitoring Application: Fleet Management, Vehicle Tracking, Predictive Maintenance, Software Management End User: OEMs, Aftermarket Providers, Automotive Developers, Service Centers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Applications |
| Companies Covered | Red Bend Software (Harman), NXP Semiconductors, Visteon Corporation, Delphi Technologies, Robert Bosch GmbH, Continental AG, Denso Corporation, Aptiv PLC, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over the Air Engine Control Module Market Evolving Landscape
Firmware architectures are converging with cloud-native development practices, compressing release cycles from annual model-year updates to continuous deployment pipelines. Three forces dominate this transformation.
Automotive-grade hardware security modules are integrating directly into engine control unit substrate designs, embedding tamper-resistant key storage and cryptographic acceleration at the silicon level. Tier-one suppliers in Germany and Japan are qualifying these modules for powertrain applications where thermal cycling and vibration tolerance requirements exceed consumer electronics standards. This integration is compressing supplier margins on discrete secure elements while shifting value capture to system-level firmware platform vendors.
EPA emissions compliance audit trails now mandate cryptographic proof of software version integrity for recalled vehicles, extending OTA system requirements beyond European UNECE jurisdictions. The industrial consequence is mandatory investment in blockchain-anchored update logs that create immutable deployment records for regulatory subpoena. Heavy-duty diesel applications face the most severe compliance burden, with California Air Resources Board enforcement actions driving OEM prioritization of traceable update infrastructure.
Fleet procurement departments are consolidating vendor relationships around integrated platform providers capable of delivering firmware, diagnostics, and predictive analytics through unified service contracts. Traditional discrete component distributors lose share to direct OEM-cloud relationships that eliminate intermediary markup. This consolidation is most visible in North American long-haul trucking, where megafleet operators with ten-thousand-plus vehicle counts command custom API access and dedicated support tiers unavailable to smaller competitors.
Over the Air Engine Control Module Market Segmentation
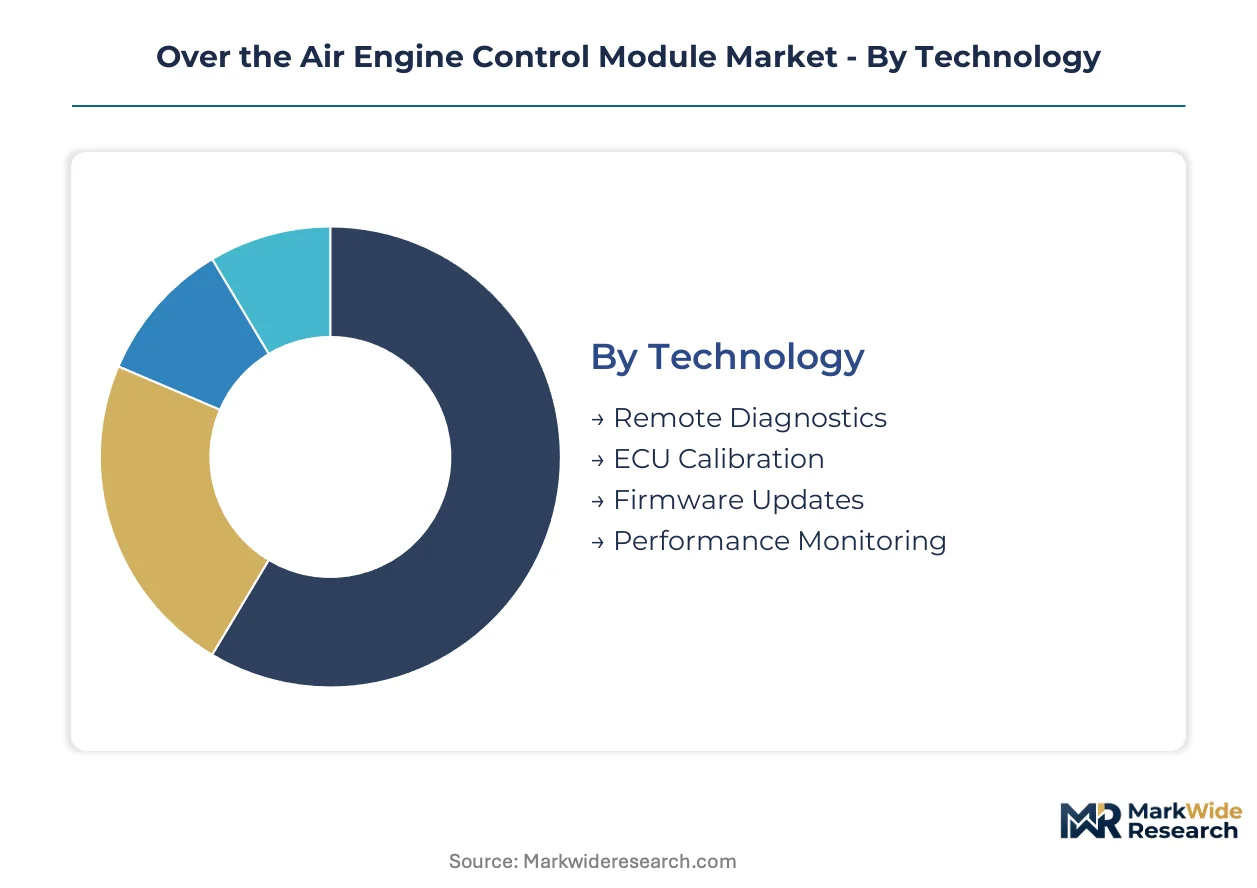
OTA engine control module segmentation reveals how technology choices, application priorities, and deployment architectures determine procurement patterns across automotive value chains. Each category reflects distinct buyer capabilities, compliance burdens, and margin structures that reshape supplier qualification requirements.
Technology:
Commercial buyers differentiate by whether they prioritize one-time hardware integration or recurring software revenue streams.
- Firmware Updates:Encrypted binary packages transmitted via cellular or Wi-Fi channels enable wireless ECU reprogramming without workshop access. Fleet operators in Germany contract for continuous emissions compliance updates, converting regulatory pressure into predictable licensing revenue for platform vendors.
- Remote Diagnostics:Predictive failure detection algorithms analyze real-time engine telemetry to anticipate component degradation before fault codes trigger. North American long-haul trucking megafleets embed uptime guarantees in service contracts, making this the fastest-expanding technology segment among commercial vehicle operators.
- ECU Calibration:Dynamic parameter adjustment for powertrain optimization under varying load conditions.
- Performance Monitoring:Real-time telemetry aggregation for fuel efficiency benchmarking and driver behavior scoring.
Firmware Updates leads volumes today; Remote Diagnostics is gaining share fastest.
Application:
End-use concentration varies by whether buyers operate captive fleets or serve distributed vehicle populations.
- Predictive Maintenance:Machine learning models trained on historical failure patterns enable component replacement scheduling before breakdown occurs. Premium pricing commands contractual uptime guarantees from European commercial fleet operators, embedding maintenance outcomes directly into service-level agreements.
- Fleet Management:Centralized oversight of distributed vehicle pools for route optimization and asset utilization tracking.
- Vehicle Tracking:Geolocation and geofencing capabilities for theft recovery and operational compliance.
- Software Management:Version control and rollback orchestration across heterogeneous ECU hardware generations.
Fleet Management anchors current deployment scale; Predictive Maintenance shows the steepest expansion trajectory.
End User:
Procurement authority concentrates differently depending on whether buyers control manufacturing specifications or post-warranty service relationships.
- OEMs:Original equipment manufacturers architect cloud-native firmware pipelines to eliminate physical service bay bottlenecks during recall campaigns. German automotive groups integrate OTA platforms into next-generation powertrain architectures, locking in recurring software licensing structures across vehicle lifecycles.
- Aftermarket Providers:Independent service networks seeking retrofit capabilities for legacy vehicle populations.
- Automotive Developers:Engineering houses building embedded software stacks for tier-one supplier integration.
- Service Centers:Workshop networks requiring diagnostic tool compatibility with manufacturer-certified update protocols.
OEMs dominate procurement volumes currently; Aftermarket Providers are climbing the fastest as retrofit demand intensifies.
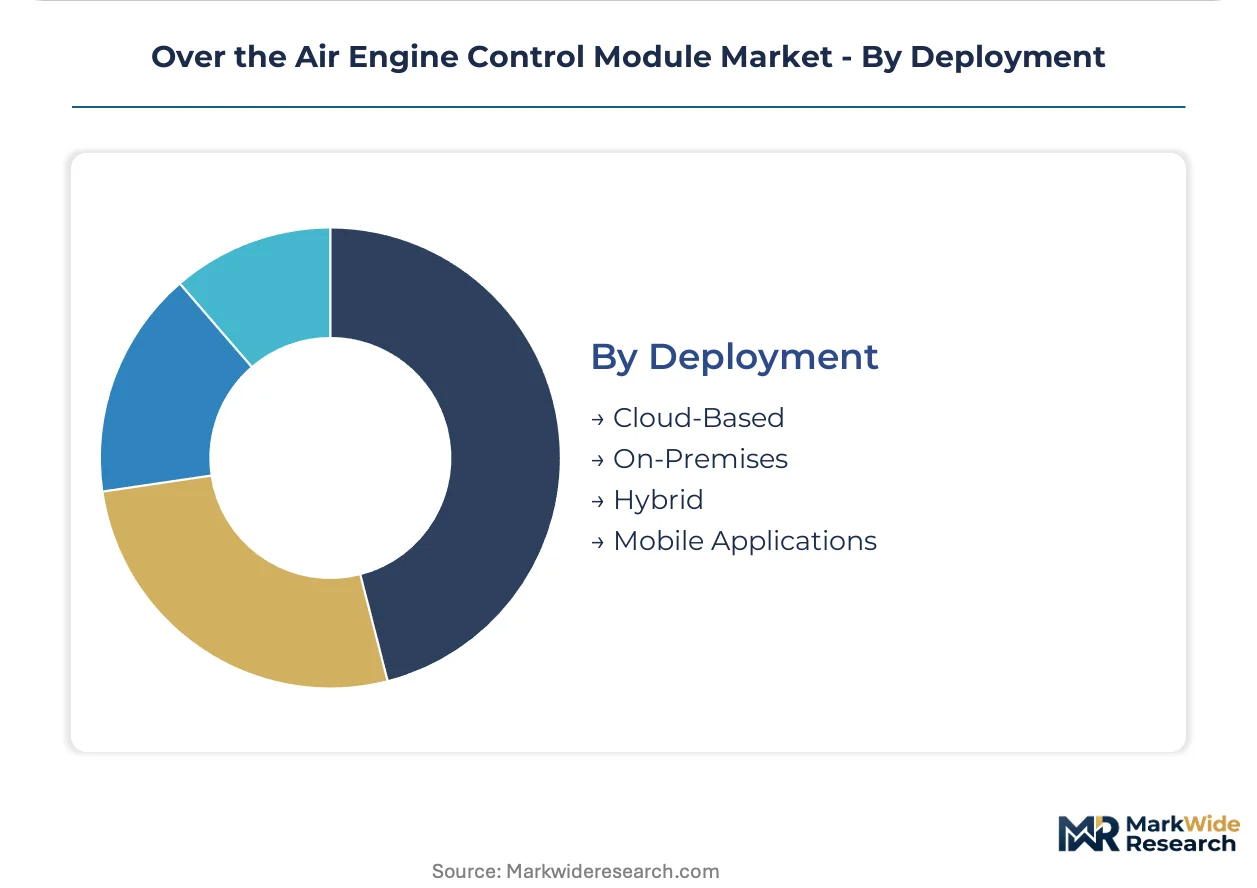
Deployment:
Infrastructure investment thresholds separate buyers with existing cloud operations from those requiring turnkey solutions.
- Cloud-Based:Scalable compute resources hosting firmware repositories, differential update generation, and deployment orchestration. Tier-one suppliers in Bavaria and Baden-Württemberg validate cloud-to-vehicle pipelines for European OEMs, compressing release cycles from annual model-year updates to continuous deployment.
- Hybrid:Edge caching combined with centralized analytics for bandwidth-constrained operational environments.
- On-Premises:Air-gapped infrastructure for defense and critical infrastructure fleets with stringent data sovereignty requirements.
- Mobile Applications:Smartphone-based interfaces for driver-facing diagnostic access and simplified update initiation.
Cloud-Based deployment leads adoption today; Hybrid architectures are expanding most quickly among mid-size fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive electronics manufacturing concentrates more OTA validation infrastructure than any other single country, while United States commercial fleet operators deploy remote diagnostics at faster adoption velocities than European counterparts.
Germany
Bavarian and Baden-Württemberg industrial clusters host tier-one supplier OTA validation facilities serving European OEM powertrain architectures. UNECE WP.29 cybersecurity mandates from the KBA national type-approval authority compress software traceability timelines for vehicles sold across EU member states. Stuttgart-based engineering centers validate differential update protocols for heavy-duty diesel compliance with California Air Resources Board reciprocity requirements.
United States
North American long-haul trucking megafleets with ten-thousand-plus vehicle counts command custom API access for predictive maintenance platforms. EPA emissions compliance audit trails now mandate cryptographic proof of software version integrity for recalled vehicles, extending beyond European regulatory jurisdictions. Michigan-based automotive electronics corridors anchor cloud-to-vehicle firmware pipeline development for domestic OEM recall cost reduction.
China
Domestic commercial vehicle manufacturers accelerate OTA platform integration under MIIT automotive software standards and dual carbon goals for fleet emissions monitoring. GB standards for vehicle network security create compliance baselines for encrypted binary package transmission. Yangtze River Delta electronics manufacturing clusters supply automotive-grade secure elements for ECU authentication chains serving both domestic OEMs and export markets.
India
BS-VI emissions enforcement and PLI scheme incentives for automotive electronics create first-mover positioning for OTA platforms targeting domestic truck and bus manufacturers. The CEA and national automotive regulators align type-approval processes with UNECE frameworks for software update traceability. Tamil Nadu and Maharashtra industrial corridors concentrate tier-one supplier engineering operations for commercial vehicle powertrain calibration.
Japan
METI industrial policy prioritizes edge-to-cloud AI convergence for predictive calibration adjustments in commercial vehicle applications. JIS standards for automotive cybersecurity harmonize with ISO 21434 to enable differential update protocol deployment across domestic and export vehicle populations. Nagoya-area automotive electronics clusters integrate hardware security modules directly into engine control unit substrate designs for thermal cycling tolerance.
Over the Air Engine Control Module Market Competitive Landscape
German producers anchor one tier of secure boot architecture development; United States and Japanese specialists hold differentiated positions in cellular modem integration and edge AI inference engines. The vendor base stratifies across three tiers: integrated platform providers capturing direct OEM-cloud relationships, semiconductor specialists supplying authentication chain components, and software platform vendors monetizing recurring licensing structures. Two competitive moves dominate: tier-one suppliers expanding OTA validation facility footprints across automotive manufacturing corridors, and semiconductor foundries extending automotive qualification cycles for secure element supply.
Within the integrated platform tier, Robert Bosch GmbH and Continental AG exemplify German engineering heritage applied to cloud-to-vehicle firmware pipelines. NXP Semiconductors occupies a position representing specialty semiconductor concentration in automotive-grade secure element supply chains. These three entities anchor distinct competitive vectors: Bosch exemplifies embedded software heritage monetization, Continental represents secure boot architecture R&D intensity, and NXP sits within authentication chain component supply.
| Leading Market Players |
|---|
| Red Bend Software (Harman) |
| NXP Semiconductors |
| Visteon Corporation |
| Delphi Technologies |
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Aptiv PLC |
| Qualcomm Technologies |
| Others |
Value Network & Pricing Analysis
Fleet procurement consolidation around unified platform providers strips margin from discrete component distributors and compresses intermediary markups across European and North American markets. This buyer-side concentration forces tier-one suppliers to absorb qualification cost burdens while defending recurring software licensing structures.
Pricing Analysis
Distributor margins face systematic compression as direct OEM-cloud relationships displace traditional automotive electronics channels. Subscription-based firmware licensing dominates revenue architecture, with three-tier pricing structure across premium, standard, and economy levels differentiating by update frequency and diagnostic depth. Price differentiation hinges on UNECE WP.29 certification grade and volume scale commitments. Cost compression in standard-tier hardware is intensifying due to automotive-grade secure element supply bottlenecks. Aftermarket retrofit providers exhibit highest price sensitivity; megafleet operators with dedicated API access show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German OEMs mandate multi-supplier qualification for secure boot architectures across Bavarian and Baden-Württemberg engineering centers. Geographic supply concentration centers on Germany, China, and Japan for hardware security module substrate integration. Raw material dependencies include automotive-grade silicon wafers, tamper-resistant key storage components, and cellular modem chipsets. Single-source vulnerability in specialty semiconductor foundry capacity creates authentication chain bottlenecks. Distribution runs through tier-one supplier direct relationships with OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Over the Air Engine Control Module market represents a late-cycle quality story where fleet procurement departments now mandate cryptographic audit trail specifications that exceed baseline regulatory requirements. This demand-shift toward premium compliance infrastructure rewards suppliers with pre-qualified secure boot architectures.
For Market Incumbents: To counter embedded cryptography talent scarcity, tier-one suppliers should expand captive training pipelines for automotive secure boot engineers in Stuttgart and Munich engineering corridors. Backward integration into hardware security module substrate designs locks in thermal cycling tolerance capabilities that commodity secure element vendors cannot match. Qualification facility expansion across Tamil Nadu and Maharashtra industrial corridors defends margin position against emerging platform competitors. For New Entrants and Emerging Players: Cloud-native firmware pipeline development offers the most penetrable entry vector for aftermarket retrofit providers serving legacy ECU populations in India and Southeast Asia. White-space concentration sits with BS-VI compliance-driven truck and bus manufacturers seeking first-mover OTA partnerships. Direct API integration with fleet management software vendors bypasses entrenched tier-one supplier relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor specialists holding automotive-grade secure element qualification cycles that extend 18-24 months beyond consumer electronics standards. Long-term viability favors platform vendors with recurring software licensing structures anchored to emissions compliance mandates. Watch for EPA-NHTSA regulatory reciprocity agreements as inflection signal for cross-border deployment cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Boot Architecture Investment | UNECE WP.29 mandates lock in recurring qualification revenue for pre-certified suppliers. |
| Differential Update Protocol Development | Compressed binary deltas reduce cellular data costs for bandwidth-constrained fleet operators. |
| Edge-to-Cloud AI Integration | Predictive calibration adjustments anticipate component degradation before fault codes trigger. |
| Hardware Security Module Substrate Integration | Thermal cycling tolerance requirements exceed consumer electronics standards in powertrain applications. |
| Subscription Diagnostics Bundling | Remote monitoring services transform one-time hardware sales into recurring revenue relationships. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution channel heads, and fleet management technology directors grounded qualitative findings in operational realities. Secondary validation drew from UNECE WP.29 regulatory filings, EPA emissions compliance databases, automotive production registries, and tier-one supplier R&D expenditure disclosures. Bottom-up and top-down triangulation cross-checked segment-level demand assumptions against aggregate market sizing.
Bottom-up modeling anchored volume projections to disclosed fleet operator deployment timelines and OEM platform integration schedules across the analysis window. Segmentation dimensions included technology type, application priority, end-user procurement authority, and deployment architecture. CAGRs were derived from slope analysis of disclosed licensing revenue trajectories and hardware shipment patterns. Forecast inputs incorporated differential update protocol adoption curves and secure element supply capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for legacy ECU retrofit compatibility would alter the outlook for aftermarket provider addressable populations. Forecasts reflect assumptions regarding UNECE-EPA regulatory reciprocity progression and semiconductor foundry capacity expansion timelines. Deviation in embedded cryptography talent pipeline development would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Automotive Human Interface System Market