
 On-Board Fuse Box Market | 2026-2036
On-Board Fuse Box Market Size, Share, and Industry Trends Forecast 2026-2036
On-Board Fuse Box Market Analytics
Multi-source procurement is expanding as automakers diversify fuse box suppliers beyond captive electronics divisions. Littelfuse leverages its vertical integration in semiconductor protection to sustain pricing power across EV platforms. Eaton Corporation anchors its position through R&D intensity in high-voltage architectures for commercial vehicles. Robert Bosch competes by controlling distribution channels that reach both OEM and aftermarket segments simultaneously.
An on-board fuse box is a centralized electrical distribution unit housing multiple fuse elements, typically rated between 5A and 80A, that protects vehicle circuits from overcurrent conditions through calibrated metal strip melting. It serves as the primary safeguard for wire harnesses, electronic control modules, and power distribution networks across internal combustion, hybrid, and battery-electric vehicles. Smart fuse boxes with solid-state switching and real-time diagnostics represent the fastest-growing product category, displacing standard fuse boxes in premium electric vehicle segments where software-defined protection enables predictive maintenance. Passenger cars retain the largest volume share, though electric vehicles generate disproportionate margin pools due to higher voltage ratings and integrated thermal management requirements.
The US NHTSA and FMVSS standards mandate specific overcurrent protection performance for vehicle safety systems, while China's MIIT enforces GB/T standards that accelerate adoption of integrated fuse technologies in new energy vehicles. Europe's REACH and RoHS frameworks restrict hazardous substances in fuse box housings and conductor materials, compelling suppliers to reformulate polymer compositions and plating chemistries. Stakeholders must monitor how regional divergence in voltage standards and recycling mandates reshapes product development priorities across manufacturing footprints.
Market Dynamics
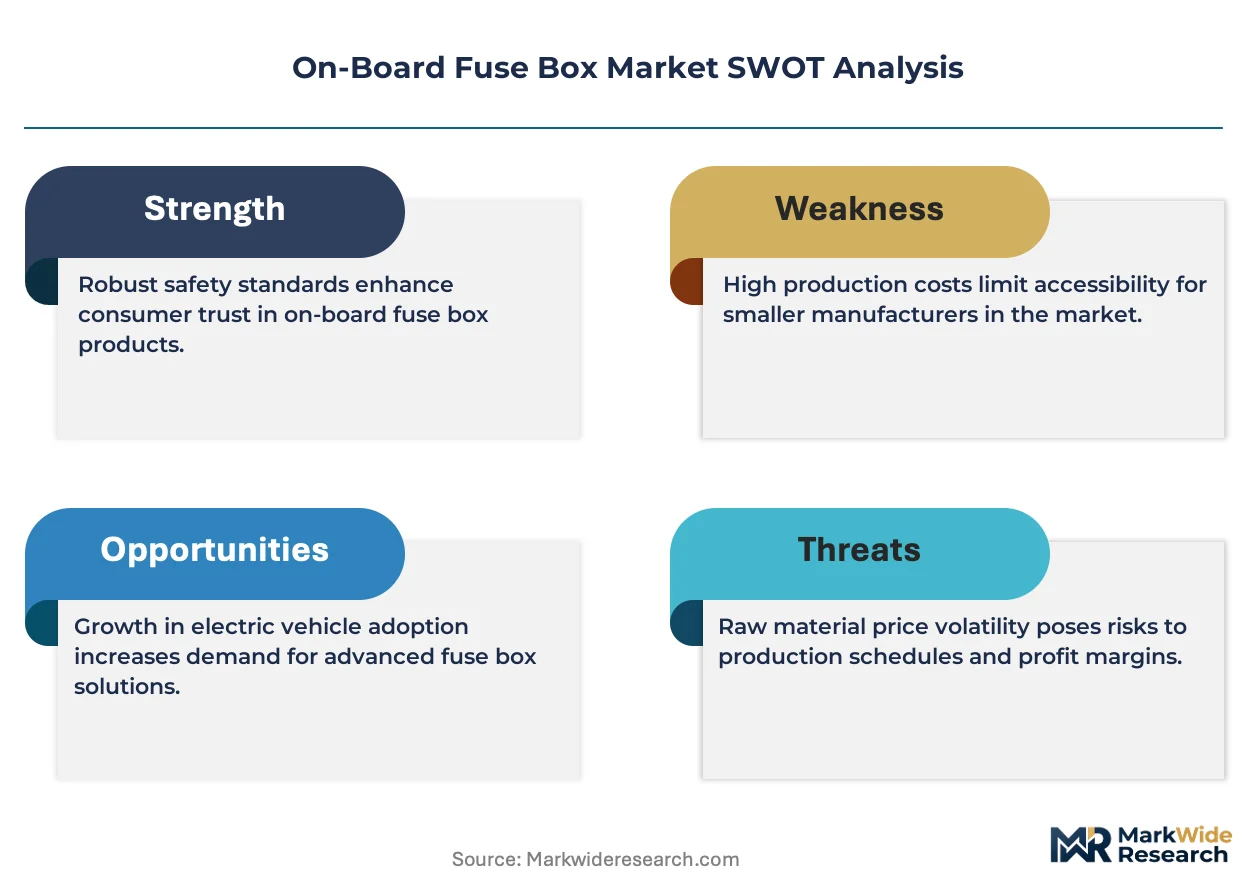
Vehicle electrification is collapsing the distinction between power distribution and active circuit management, forcing fuse boxes to absorb semiconductor-based switching functions that were historically separate from protection hardware.
Growth Catalysts
- MIIT's GB/T standards for new energy vehicles:China's mandatory circuit protection requirements for battery-electric platforms are accelerating procurement of integrated fuse technologies with real-time thermal monitoring capabilities.
- Wire harness protection intensity:Higher voltage architectures in commercial electric vehicles demand fuse boxes with expanded current ratings and arc-quenching materials that withstand repeated fault conditions.
- Germany's automotive manufacturing corridor:Concentrated OEM engineering centers in Stuttgart and Munich are driving specification upgrades that cascade through European supply chains.
Market Restraints
- Copper and silver price volatility:Conductor materials constitute a significant share of fuse element production costs, exposing margins to commodity exchange fluctuations without effective hedging instruments at tier-two suppliers.
- Polymer formulation constraints:REACH and RoHS substance restrictions on halogenated flame retardants and specific plating chemistries are forcing housing redesigns that extend qualification timelines.
- Solid-state circuit breaker substitution:Semiconductor-based protection devices in premium electric vehicle segments are absorbing functions previously exclusive to electromechanical fuse boxes.
Strategic Opportunities
- Commercial vehicle electrification:Fleet operators in North America are specifying smart fuse boxes with predictive maintenance interfaces to minimize downtime in heavy-duty electric trucks.
- Software-defined protection convergence:Integration of fuse boxes with vehicle domain controllers enables over-the-air threshold adjustment and fault logging that differentiates aftermarket service offerings.
- India's PLI scheme for auto components:Domestic manufacturing incentives are attracting fuse box assembly investments to serve both local OEMs and export markets in Southeast Asia.
Industry Challenges
- High-voltage safety certification timelines:UL and IEC testing protocols for arc containment and touch-safe designs require 18-24 month validation cycles that lag behind platform development schedules.
- Power electronics integration complexity:Fuse box engineers must coordinate thermal and electromagnetic compatibility with silicon carbide inverters and onboard chargers without established design precedents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Board Fuse Box Market |
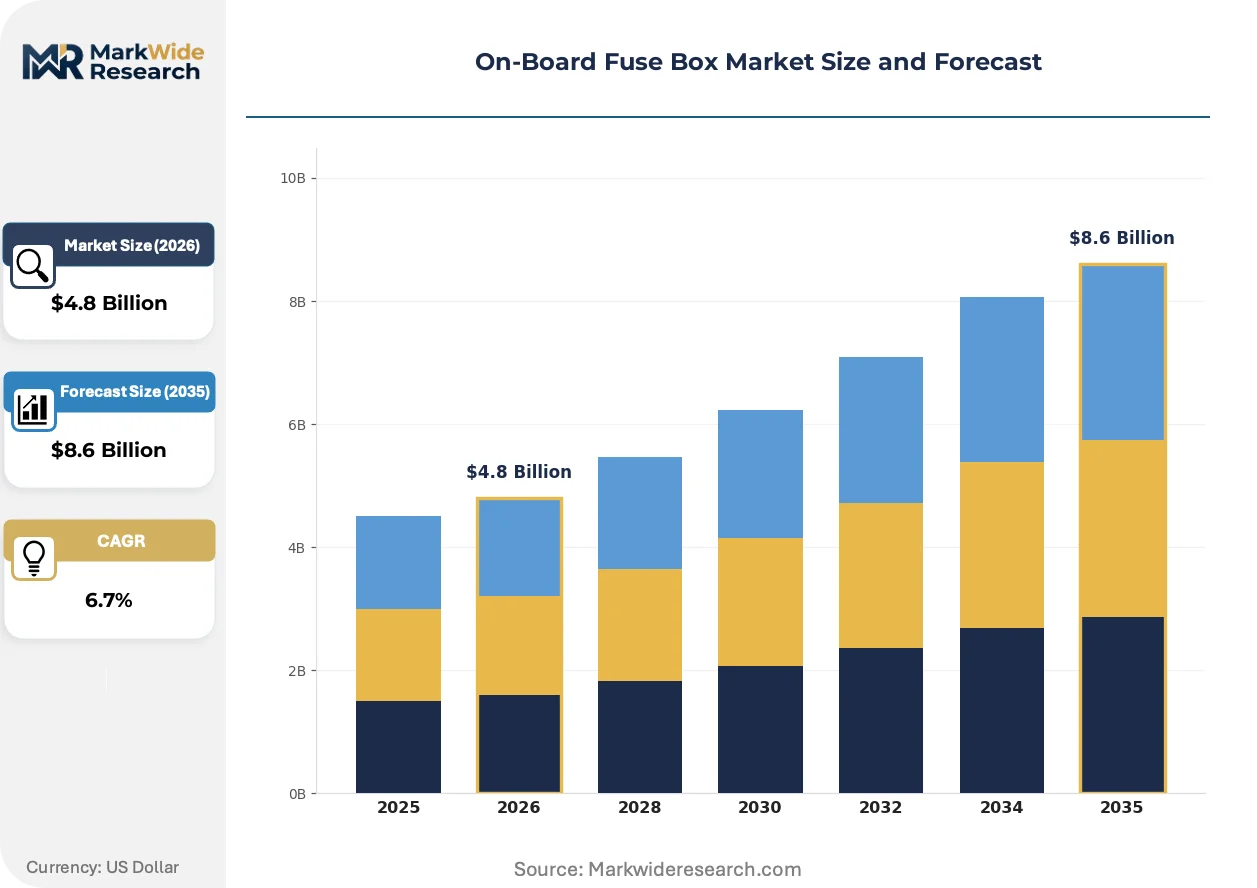
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fuse Box, Smart Fuse Box, Modular Fuse Box, Custom Fuse Box Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Technology: Automated, Manual, Hybrid, Integrated Customer Type: OEMs, Aftermarket Suppliers, Distributors, Service Centers |
| Companies Covered | Littelfuse, Eaton Corporation, Mersen, Robert Bosch, Continental AG, Denso, BorgWarner, HELLA, Apolo Industrial Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Board Fuse Box Market Evolving Landscape
Intelligent protection architectures are redistributing decision-making from centralized body control modules to distributed nodes embedded within the fuse box itself, compressing response times and enabling predictive intervention.
Solid-state switching technology is decentralizing circuit protection authority across vehicle electrical domains. These semiconductor-based devices eliminate mechanical wear and enable millisecond-level fault isolation. Premium electric vehicle manufacturers are adopting them for high-current paths previously served by blade fuses. The shift is decentralizing thermal management responsibility from separate control modules into the protection hardware itself.
China's MIIT enforcement of GB/T standards for new energy vehicles is mandating integrated arc detection and isolation capabilities that exceed legacy fuse performance. Domestic suppliers are reformulating fuse element alloys and housing geometries to achieve compliance. The regulation is compressing product lifecycles as OEMs refresh electrical architectures to meet phased implementation deadlines.
Fleet procurement officers are unbundling fuse box specification from captive electronics divisions and issuing standalone technical requirements to specialized suppliers. This behavior is fragmenting historical single-source relationships and exposing fuse box manufacturers to direct commercial negotiation. The pattern is most visible in North American commercial vehicle electrification programs where fleet operators retain engineering authority over electrical system architecture.
On-Board Fuse Box Market Segmentation
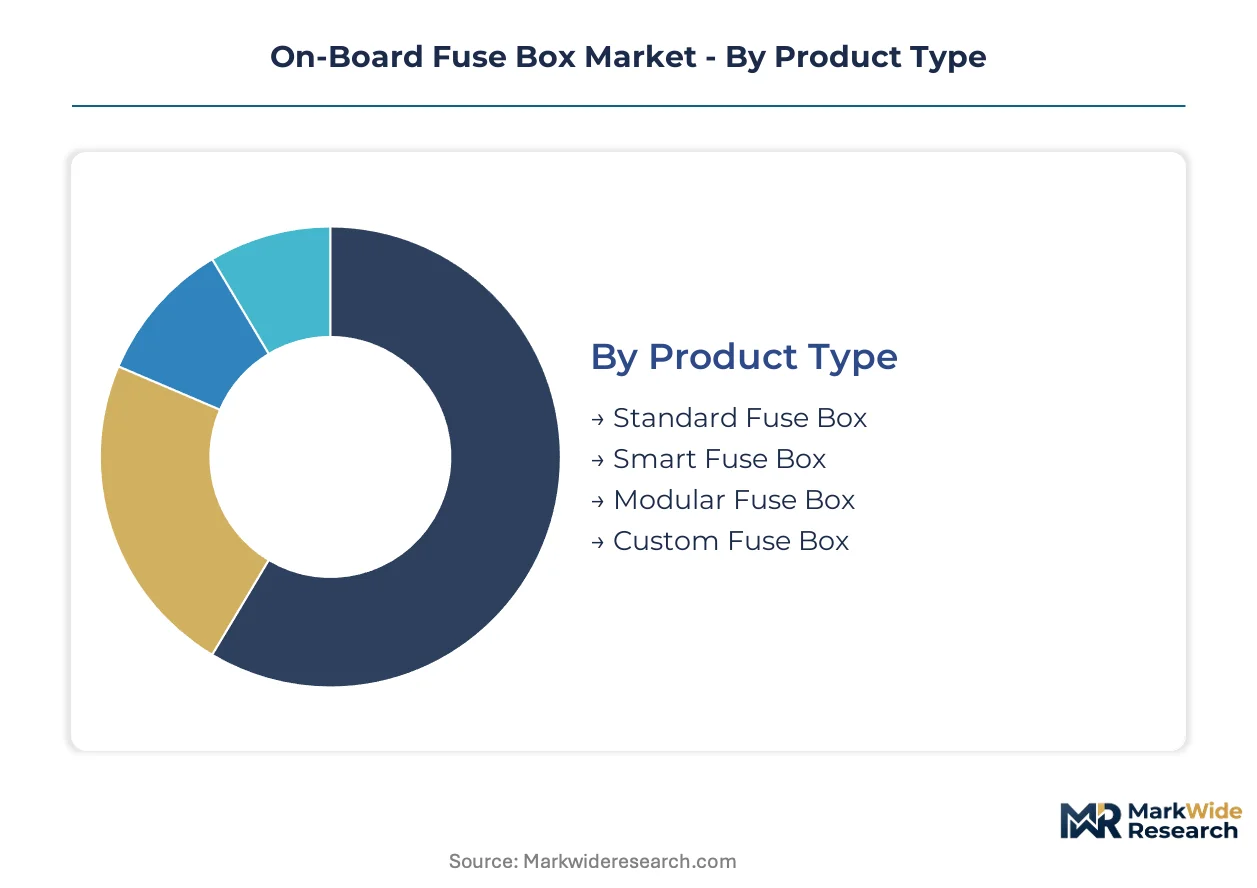
Fuse box segmentation reveals how capital allocation and technical requirements diverge across vehicle electrification pathways. Product architecture choices directly determine semiconductor content, thermal management complexity, and software integration depth.
Product Type:
Smart fuse boxes demand the heaviest upfront capital commitment due to embedded power semiconductors, real-time diagnostic firmware, and domain controller interfaces that standard architectures lack.
- Smart Fuse Box:Solid-state switching replaces mechanical fuse elements with silicon-based protection circuits enabling millisecond fault isolation and predictive maintenance telemetry. Demand concentrates in Germany's premium electric vehicle platforms where Stuttgart and Munich engineering centers specify integrated thermal monitoring for 800V architectures.
- Standard Fuse Box:Conventional blade and cartridge fuse configurations with passive thermal protection serve cost-sensitive internal combustion vehicle programs. Procurement remains anchored in China's mass-market passenger car segment where GB/T compliance pressures are accelerating refresh cycles without full smart architecture migration.
- Modular Fuse Box:Scalable housing designs accommodate varying circuit counts through standardized connector blocks.
- Custom Fuse Box:Application-specific geometries for commercial vehicle chassis with non-standard wire harness routing.
Most installed capacity flows through Standard Fuse Box. Expansion is steepest in Smart Fuse Box.
Vehicle Type:
Commercial vehicle electrification programs absorb disproportionate engineering resources per unit due to extended validation cycles and fleet-specific predictive maintenance requirements.
- Electric Vehicles:High-voltage fuse boxes must isolate faults across battery packs, inverters, and fast-charging circuits while managing thermal runaway containment. North American heavy-duty truck fleets specify smart variants with telematics integration to minimize roadside downtime.
- Passenger Cars:Volume concentration in compact and mid-size segments sustains procurement of standard architectures despite electrification tailwinds. China's new energy vehicle quotas are compressing the transition timeline as domestic OEMs rebalance portfolios.
- Commercial Vehicles:Bus and truck applications require expanded current ratings and arc-quenching materials.
- Motorcycles:Two-wheeler electrification in Southeast Asia drives demand for miniaturized waterproof housings.
Passenger Cars dominate unit shipments. Electric Vehicles command the highest value per installation.
Technology:
Integrated architectures concentrate R&D spending where semiconductor protection merges with power distribution functions previously handled by separate control modules.
- Integrated:Fuse boxes absorb switching and monitoring functions from standalone body control modules through embedded microcontrollers and CAN-FD communication stacks. European OEMs are mandating these configurations for software-defined vehicle platforms.
- Automated:Self-resetting solid-state devices eliminate service visits for nuisance trips in fleet applications.
- Manual:Traditional replaceable fuse elements persist in aftermarket replacement cycles.
- Hybrid:Combinations of electromechanical and semiconductor protection serve transitional architectures.
Manual technology retains the largest replacement part footprint. Integrated configurations are climbing the fastest.
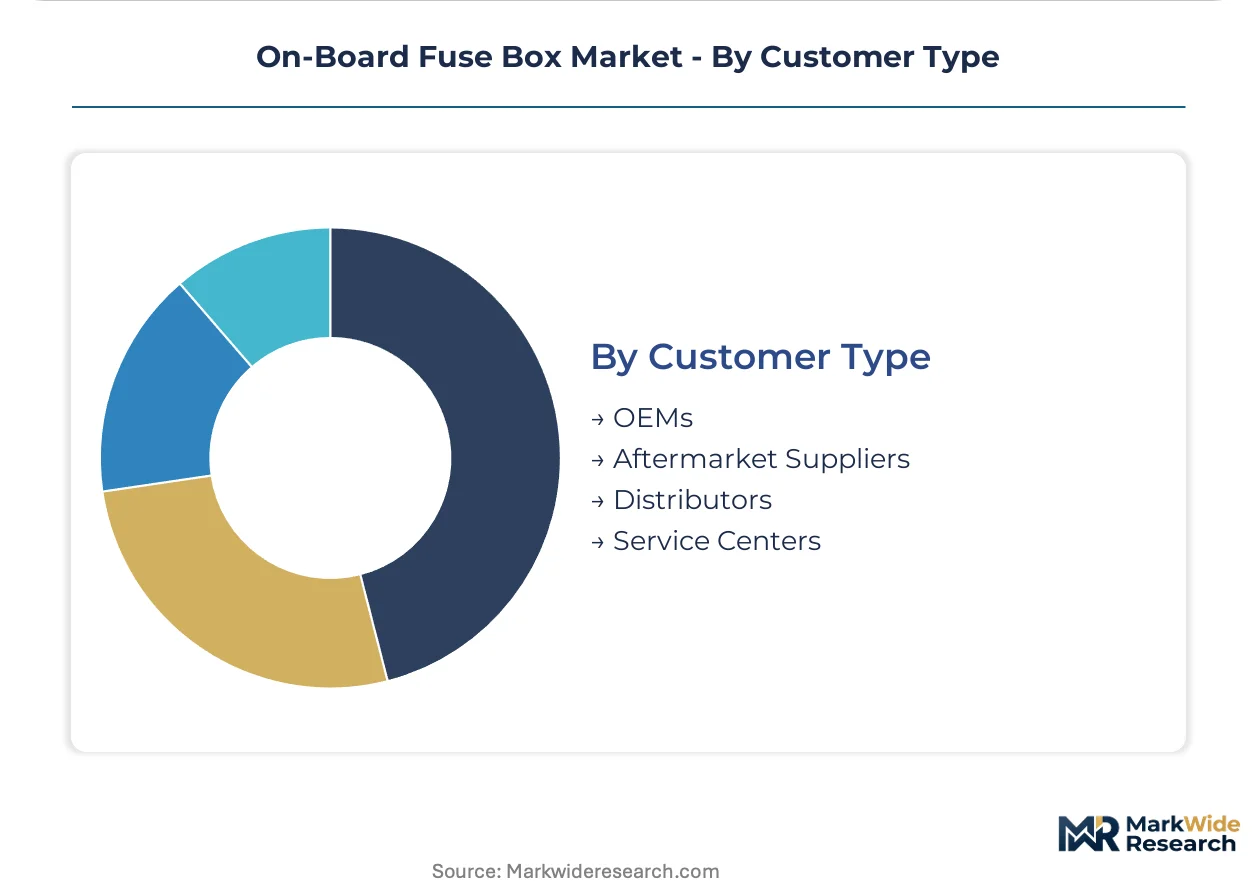
Customer Type:
OEM direct procurement requires the most intensive qualification investment due to platform-specific validation and multi-year supply agreements.
- OEMs:Original equipment manufacturers specify fuse boxes during electrical architecture definition, locking in designs years before production. Tier 1 suppliers compete through early-stage engineering engagement with Stuttgart, Munich, and Shanghai engineering centers.
- Aftermarket Suppliers:Independent distributors stock replacement fuse boxes for legacy vehicle parc maintenance.
- Distributors:Wholesale channels aggregate demand from smaller repair networks.
- Service Centers:Dealer and independent repair facilities source direct replacements for warranty repairs.
OEMs control the specification pipeline. Aftermarket Suppliers capture replacement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping fuse box manufacturing footprints as suppliers migrate assembly capacity toward jurisdictions with streamlined high-voltage safety certification pathways. Cost-of-compliance gaps between testing regimes are accelerating investment decisions across three continents.
United States
Commercial vehicle electrification programs in Michigan and Ohio are absorbing expanded fuse box procurement as heavy-duty truck fleets specify predictive maintenance interfaces. NHTSA's FMVSS overcurrent protection mandates for vehicle safety systems lock in design requirements years ahead of production. Detroit's automotive engineering corridor anchors specification development for North American OEM platforms.
Germany
Stuttgart and Munich engineering centers are driving 800V architecture upgrades that cascade through European supply chains for premium electric vehicle segments. REACH substance restrictions on halogenated flame retardants are compelling housing reformulations that extend qualification timelines. Baden-Württemberg's Tier 1 supplier concentration sustains fuse box innovation for software-defined vehicle platforms.
China
MIIT's GB/T standards for new energy vehicles are mandating integrated arc detection capabilities that exceed legacy fuse performance across battery-electric platforms. Dual carbon goals are tightening circuit protection requirements and compressing product refresh cycles. Shanghai and Shenzhen manufacturing clusters are attracting domestic fuse box assembly investments to serve local OEMs and Southeast Asian export markets.
Japan
METI's industrial policy frameworks are channeling semiconductor protection expertise toward automotive fuse box applications as vehicle electrification intensifies. JIS standards alignment with IEC protocols is reducing requalification burdens for suppliers serving multiple export destinations. Nagoya's automotive component ecosystem is coordinating thermal management integration with silicon carbide power electronics.
India
PLI scheme incentives for auto components are attracting fuse box manufacturing investments to Maharashtra and Tamil Nadu to serve domestic OEMs and regional export markets. BIS certification requirements for automotive electrical components are establishing baseline quality thresholds for local production. Chennai's automotive manufacturing corridor is consolidating assembly capacity for two-wheeler electrification programs across Southeast Asia.
On-Board Fuse Box Market Competitive Landscape
Established producers occupy the standard fuse box tier; emerging entrants pursue solid-state switching architectures and predictive maintenance interfaces. The market structure reflects moderate consolidation around diversified electrical component conglomerates with captive automotive relationships. Three archetypes dominate: semiconductor-integrated specialists, distribution-channel controllers, and vertically integrated protection device manufacturers. Competitive moves concentrate on strategic partnerships for high-voltage architecture co-development and geographic expansion into PLI-subsidized manufacturing jurisdictions.
Among North American-based diversified industrial suppliers, Eaton Corporation exemplifies the R&D-intensive archetype for commercial vehicle electrification. Littelfuse anchors the semiconductor-integrated tier through backward integration into protection device manufacturing. Robert Bosch occupies a position spanning both OEM specification control and aftermarket channel reach simultaneously. These three entities represent distinct competitive vectors: technology licensing intensity, upstream control over conductor materials, and dual-channel distribution architecture.
| Leading Market Players |
|---|
| Littelfuse |
| Eaton Corporation |
| Mersen |
| Robert Bosch |
| Continental AG |
| Denso |
| BorgWarner |
| HELLA |
| Apolo Industrial Corporation |
| Others |
Value Network & Pricing Analysis
Backward integration into semiconductor protection devices anchors pricing power for fuse box manufacturers serving premium electric vehicle platforms. Suppliers with captive production of silicon-based switching elements command margin premiums that outsourced competitors cannot match, particularly as China's MIIT tightens GB/T certification requirements for arc detection capabilities.
Pricing Analysis
Distributor margins compress standard fuse box economics while direct-to-OEM channels preserve pricing power for smart architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with UL and IEC testing tiers commanding substantial premiums over baseline BIS thresholds. Cost compression in standard blade fuse tiers intensifies because China's mass-market passenger segment prioritizes procurement scale over thermal monitoring features. Fleet operators in North American commercial vehicle programs demonstrate lowest price sensitivity due to predictive maintenance value capture, while Southeast Asian two-wheeler OEMs exhibit acute cost consciousness.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Munich engineering centers, while aftermarket distributors aggregate fragmented replacement volume. Manufacturing concentrates in China, Germany, and Mexico, with Shanghai and Shenzhen clusters serving domestic new energy vehicle production and export markets. Silver and copper conductor materials, engineering-grade polymer housings, and silicon carbide semiconductors constitute critical input dependencies. Single-source vulnerability in semiconductor switching elements threatens supply continuity as automotive power electronics demand surges. Distribution runs through Tier 1 supplier networks that coordinate qualification timelines with OEM platform development cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in on-board fuse boxes rests on semiconductor content substitution and software-defined protection tiering that commands premium positioning against legacy electromechanical alternatives.
For Market Incumbents: Anticipate solid-state circuit breaker substitution by accelerating R&D allocation to predictive maintenance interfaces and over-the-air threshold adjustment capabilities. Defensive consolidation through backward integration into fuse element alloy production mitigates copper and silver price volatility exposure. Certification investment in China's evolving GB/T standards preserves specification access as MIIT phases arc detection mandates. For New Entrants and Emerging Players: Launch via India's PLI-subsidized manufacturing corridors to capture Southeast Asian two-wheeler electrification demand with miniaturized waterproof housings. Target commercial vehicle fleet procurement officers in North America who unbundle fuse box specification from captive electronics divisions. White-space concentration in smart fuse box retrofit programs for existing heavy-duty truck parc offers immediate revenue traction absent lengthy OEM qualification cycles. For Investors and Strategic Acquirers: Roll-up economics work for semiconductor-integrated specialists because automotive electrification is collapsing the distinction between power distribution and active circuit management, creating captive supplier value. Long-term viability hinges on software-defined vehicle platform penetration rates. Watch for inflection in 800V architecture adoption across European premium segments as the signal for smart fuse box demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Protection Integration | Embedded silicon switching enables millisecond fault isolation for 800V architectures specified by Stuttgart engineering centers. |
| GB/T Certification Pre-Positioning | Early compliance with China's arc detection mandates secures specification lock-in during OEM electrical architecture refreshes. |
| Predictive Maintenance Interface Development | Telematics integration targets North American fleet operators minimizing roadside downtime in heavy-duty electric trucks. |
| PLI Manufacturing Footprint Expansion | India's subsidy scheme attracts assembly capacity to serve domestic OEMs and Southeast Asian two-wheeler electrification. |
| Solid-State Architecture Migration | Self-resetting protection devices eliminate service visits and differentiate premium tier offerings from blade fuse alternatives. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor protection device manufacturers grounded qualitative findings. Secondary validation drew from NHTSA FMVSS filings, MIIT GB/T standard publications, REACH substance restriction updates, vehicle production databases, and IHS Markit registration data. Bottom-up unit demand modeling triangulated against top-down market value estimates derived from disclosed Tier 1 supplier revenue allocations.
Bottom-up segmentation analysis modeled fuse box demand across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGR derivation rested on electric vehicle penetration assumptions, voltage architecture upgrade timelines, and semiconductor cost-down curves throughout the projection horizon. Industry-specific inputs included OEM platform development schedules, high-voltage safety certification cycle durations, and fleet operator predictive maintenance adoption patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt copper price spikes or accelerated solid-state circuit breaker substitution in premium segments. Forecasts reflect assumptions regarding China's dual carbon goal implementation pace, European REACH substance restriction enforcement timelines, and commercial vehicle electrification subsidy durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market