
 Automotive Digital Key Market | 2026-2036
Automotive Digital Key Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Key Market Intelligence
Multi-source semiconductor procurement is consolidating as tier-1 suppliers reduce dependency on single foundry relationships. Infineon Technologies anchors European secure element production for NFC and UWB modules. NXP Semiconductors dominates automotive-grade connectivity silicon with broad OEM qualification. Apple Inc. leverages its ecosystem control to push proprietary digital key protocols into vehicle partnerships.
An automotive digital key is a credential-based access system using Bluetooth Low Energy, near-field communication, or ultra-wideband radios to authenticate users and authorize vehicle entry and engine start without physical metal blades. The technology relies on tamper-resistant secure elements, standardized by the Car Connectivity Consortium, to prevent relay attacks and unauthorized duplication. Smartphone-based deployment leads volume as OEMs embed factory-installed digital key capability into flagship trims, while ultra-wideband adoption grows fastest due to centimeter-precision spatial awareness that prevents relay theft. NFC maintains residual share in entry-level segments where hardware cost constraints persist, though margin pools concentrate in integrated solutions combining multiple radio protocols with cloud-based key provisioning.
The UNECE WP.29 cybersecurity regulation mandates type-approved digital key systems meet ISO/SAE 21434 threat-management standards, compelling suppliers to redesign legacy architectures. The EU AI Act and GDPR impose data-localization requirements on biometric driver identification tied to digital key activation. The FCC in the United States governs UWB spectrum allocation, directly shaping which radio technologies achieve mass-market feasibility. Stakeholders must monitor regulatory divergence between European mandatory cybersecurity certification and voluntary North American guidelines, as this fragmentation will determine which technology portfolios require redundant engineering investment.
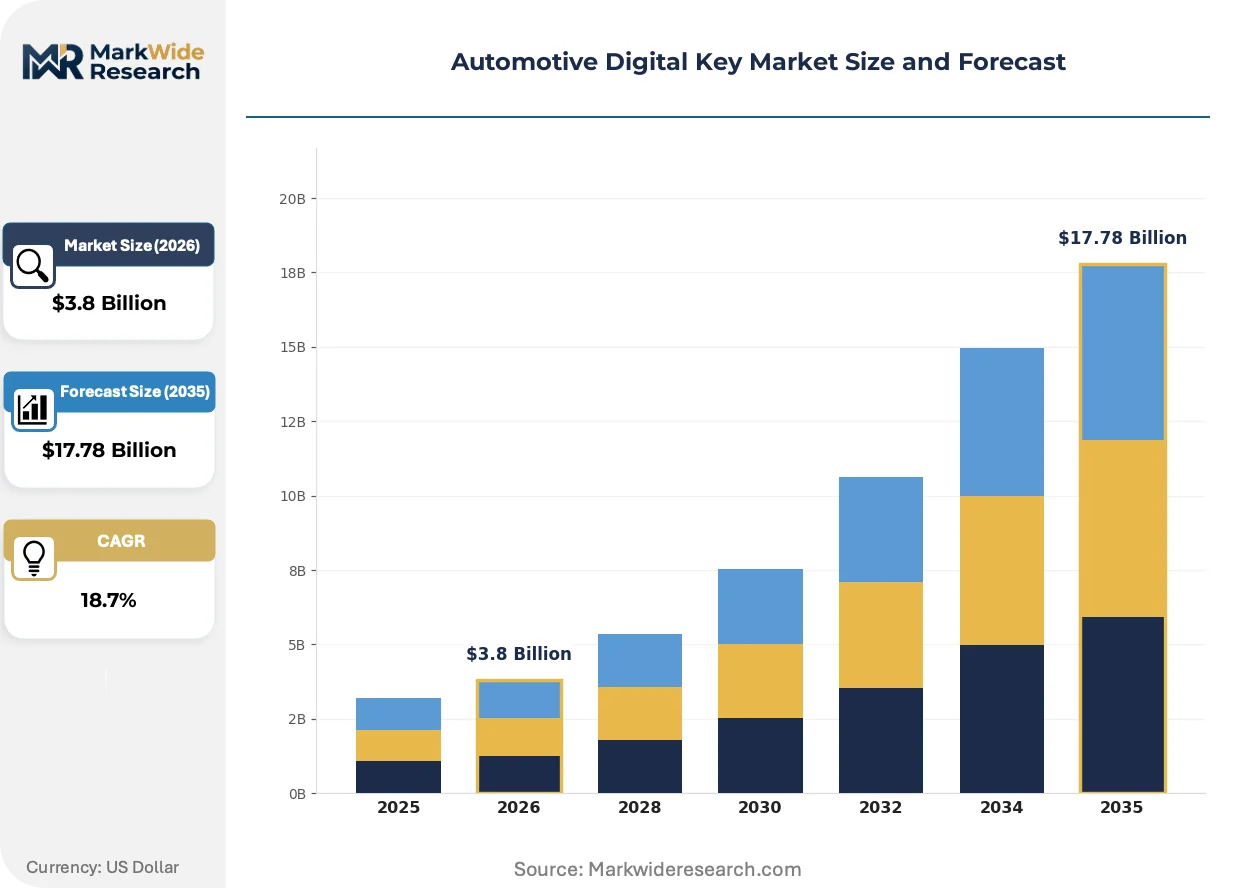
Market Dynamics
Ultra-wideband precision positioning is compressing the technology stack, forcing NFC-dominant architectures toward multi-protocol integration as relay-attack resistance becomes a non-negotiable design parameter for OEM qualification programs.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:ISO/SAE 21434 threat-management certification now gates type approval, compelling suppliers to engineer secure-element hardening into every digital key module.
- Smartphone ecosystem penetration:Factory-installed digital key capability spreads through flagship passenger vehicle trims as OEMs embed Bluetooth Low Energy and UWB radios at the point of manufacture.
- German production clustering:Munich and Hanover anchor Continental and BMW engineering centers, concentrating secure-access R&D investment and accelerating regional supplier qualification cycles.
Market Restraints
- Secure element supply concentration:European foundry capacity for automotive-grade tamper-resistant silicon remains tight, exposing procurement timelines to single-source qualification bottlenecks.
- UWB spectrum fragmentation:FCC allocation rules in the United States diverge from European spectrum planning, forcing redundant radio engineering for cross-regional vehicle platforms.
- NFC residual lock-in:Entry-level vehicle segments retain legacy near-field hardware due to bill-of-materials constraints, slowing full-stack protocol migration.
Strategic Opportunities
- Cloud-based key provisioning:Subscription-managed credential lifecycle services open recurring revenue streams beyond one-time hardware sales.
- Biometric-activated ignition:GDPR-compliant driver identification tied to digital key activation creates differentiation in luxury fleet specifications.
- Multi-fleet shared mobility:Car-sharing operators in urban Germany deploy smartphone-based access to eliminate physical handoff friction and reduce key management overhead.
Industry Challenges
- Embedded systems security engineering:Talent scarcity in automotive cryptography and side-channel attack mitigation extends product development timelines.
- Car Connectivity Consortium certification backlog:Standardized interoperability testing queues create launch-window risk for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Key Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphone-Based, Key Fob, Embedded, Wearable Technology: Bluetooth, NFC, Ultra-Wideband, QR Code End User: OEMs, Fleet Operators, Dealerships, Consumers Installation: Factory-Installed, Aftermarket, Integrated Solution, Standalone System |
| Companies Covered | DENSO Corp., Giesecke+Devrient GmbH, Apple Inc., Infineon Technologies, KPIT Technologies, Bayerische Motoren Werke AG, Ford Motor Co., NXP Semiconductors, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Key Market Strategic Shifts & Innovations
Radio protocol convergence and biometric integration are compressing the hardware-software boundary, shifting value capture toward credential-management platforms and away from discrete component supply.
Ultra-wideband spatial awareness is rewriting competitive positioning in vehicle access systems. The technology enables centimeter-precision distance bounding that neutralizes relay theft attacks. Luxury OEMs in Germany and the United States are adopting UWB as a standard fitment, collapsing the premium that NFC-only solutions once commanded.
The EU AI Act imposes data-localization requirements on biometric driver identification systems tied to digital key activation. Automotive suppliers must architect edge-computing inference to keep facial or fingerprint templates within vehicle-domain storage. This regulatory friction most affects German OEMs exporting into multiple European privacy jurisdictions, forcing modular compliance architectures.
Fleet procurement now favors integrated secure-access platforms over discrete radio modules. Car-sharing operators and corporate fleet managers negotiate multi-year credential lifecycle contracts that bundle hardware, cloud provisioning, and insurance-aligned security warranties. This bundling dynamic is most advanced in German urban mobility markets, where shared-vehicle density justifies platform-level supplier consolidation.
Automotive Digital Key Market Segmentation
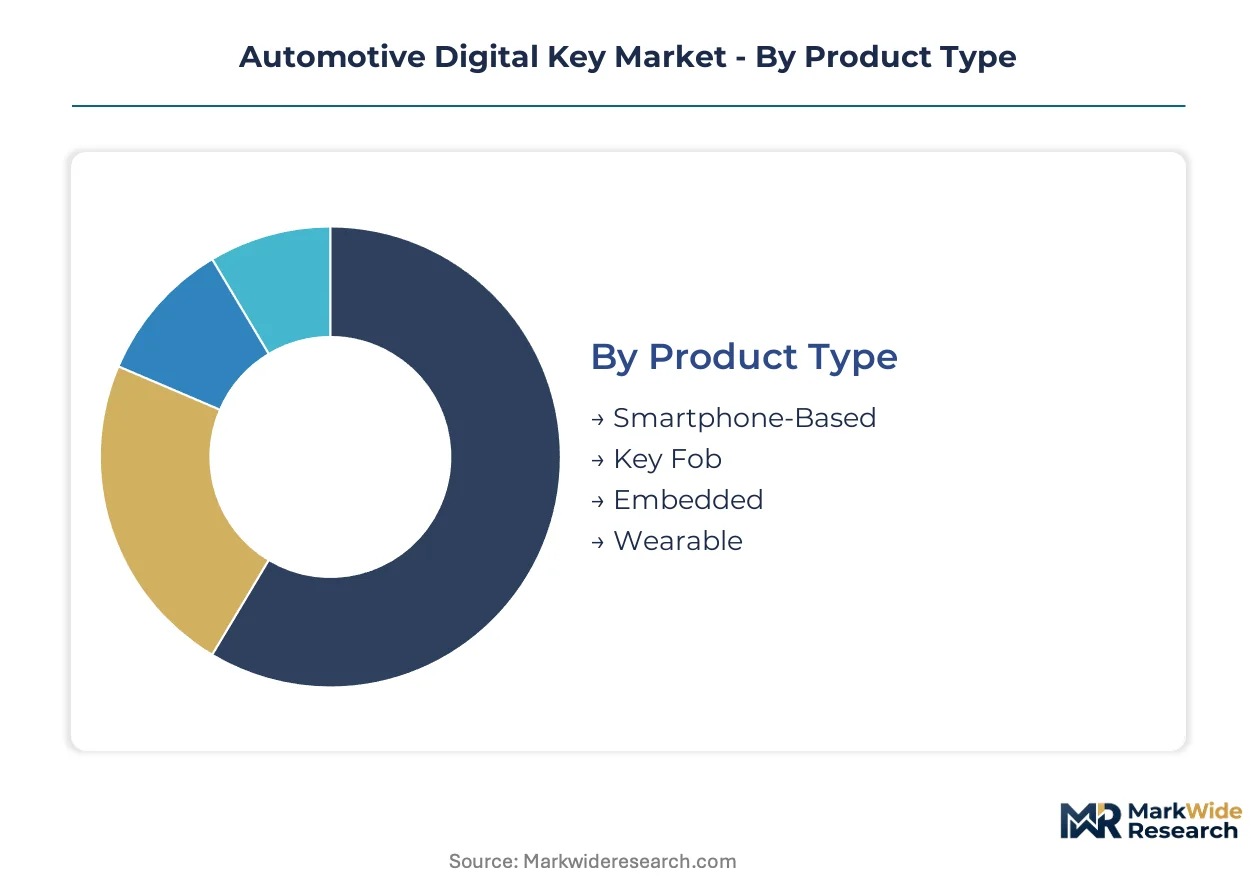
Segmentation in the automotive digital key market exposes divergent capital requirements across hardware, software, and service layers. Radio protocol integration demands heavy upfront R&D investment, while cloud-based provisioning shifts margin capture toward recurring service models. Understanding these capital-intensity gradients helps suppliers allocate engineering resources and identify partnership opportunities.
Product Type:
Capital intensity peaks in segments requiring secure-element manufacturing and multi-protocol radio integration, where semiconductor tooling and certification costs dominate unit economics.
- Smartphone-Based:Credentials reside in secure elements within iOS or Android devices, leveraging BLE, NFC, or UWB radios already present in consumer hardware. Luxury OEMs in Germany and the United States factory-install this capability as standard equipment, driven by consumer expectation for seamless device integration and elimination of physical key carry.
- Key Fob:Dedicated hardware units incorporate tamper-resistant silicon and single or dual-protocol radios in a battery-powered form factor. Fleet operators in German urban car-sharing networks specify these for rental pools where smartphone penetration among users remains inconsistent, though unit volumes are compressing as smartphone-based alternatives expand.
- Embedded:Biometric readers or touchpad interfaces built into vehicle B-pillars or center consoles require custom automotive-grade hardware with extended temperature tolerance.
- Wearable:Smartwatch or fitness band implementations rely on companion device tethering and reduced-security profiles for secondary access scenarios.
Most installed capacity flows through Smartphone-Based. Expansion is steepest in Embedded as biometric ignition integration spreads through premium vehicle lines.
Technology:
Application context determines technology selection, with theft-risk exposure and precision requirements dictating radio protocol choice across vehicle price tiers and use cases.
- Bluetooth:BLE 5.0 and later implementations provide meter-level proximity detection with minimal hardware cost and mature smartphone ecosystem support. Entry-level vehicle trims in cost-sensitive markets retain this technology where relay-attack vulnerability remains acceptable to OEMs prioritizing bill-of-materials reduction over security hardening.
- NFC:Near-field communication enables passive, battery-free operation with centimeter-range precision suitable for card-type credentials. The technology persists in rental fleet key cards and backup entry methods where smartphone battery failure scenarios must be accommodated.
- Ultra-Wideband:IEEE 802.15.4z-based distance bounding delivers centimeter-precision spatial awareness that cryptographically prevents relay attacks. German luxury OEMs and their tier-1 suppliers anchor UWB adoption, with BMW and Continental engineering clusters driving regional qualification cycles for this protocol.
- QR Code:Optical credential display requires only smartphone screen and vehicle camera, offering zero incremental hardware cost at the expense of security robustness.
Technology mix tilts toward multi-protocol stacks combining UWB precision with NFC fallback. QR Code deployment concentrates in temporary access scenarios rather than primary owner authentication.
End User:
Customer type shapes procurement modality, with volume scale and credential lifecycle complexity determining whether one-time hardware sales or managed service contracts dominate revenue capture.
- OEMs:Vehicle manufacturers specify digital key architecture during platform development, locking in secure-element suppliers and radio module vendors for multi-year production runs. German OEMs export platforms across European privacy jurisdictions, forcing modular compliance architectures under GDPR and EU AI Act data-localization mandates.
- Fleet Operators:Car-sharing and corporate fleet managers procure credential lifecycle as a managed service, bundling hardware installation, cloud provisioning, and insurance-aligned security warranties. Urban German mobility providers deploy smartphone-based access to eliminate physical handoff friction and reduce key management overhead across dispersed vehicle pools.
- Dealerships:Franchise networks require temporary credential issuance systems for service loaners and test drive fleets.
- Consumers:Individual purchasers access digital key capability through OEM mobile applications or aftermarket retrofit kits.
OEMs command the largest absolute procurement volumes. Fleet Operators are climbing the fastest as shared mobility platform economics justify supplier consolidation around integrated secure-access solutions.
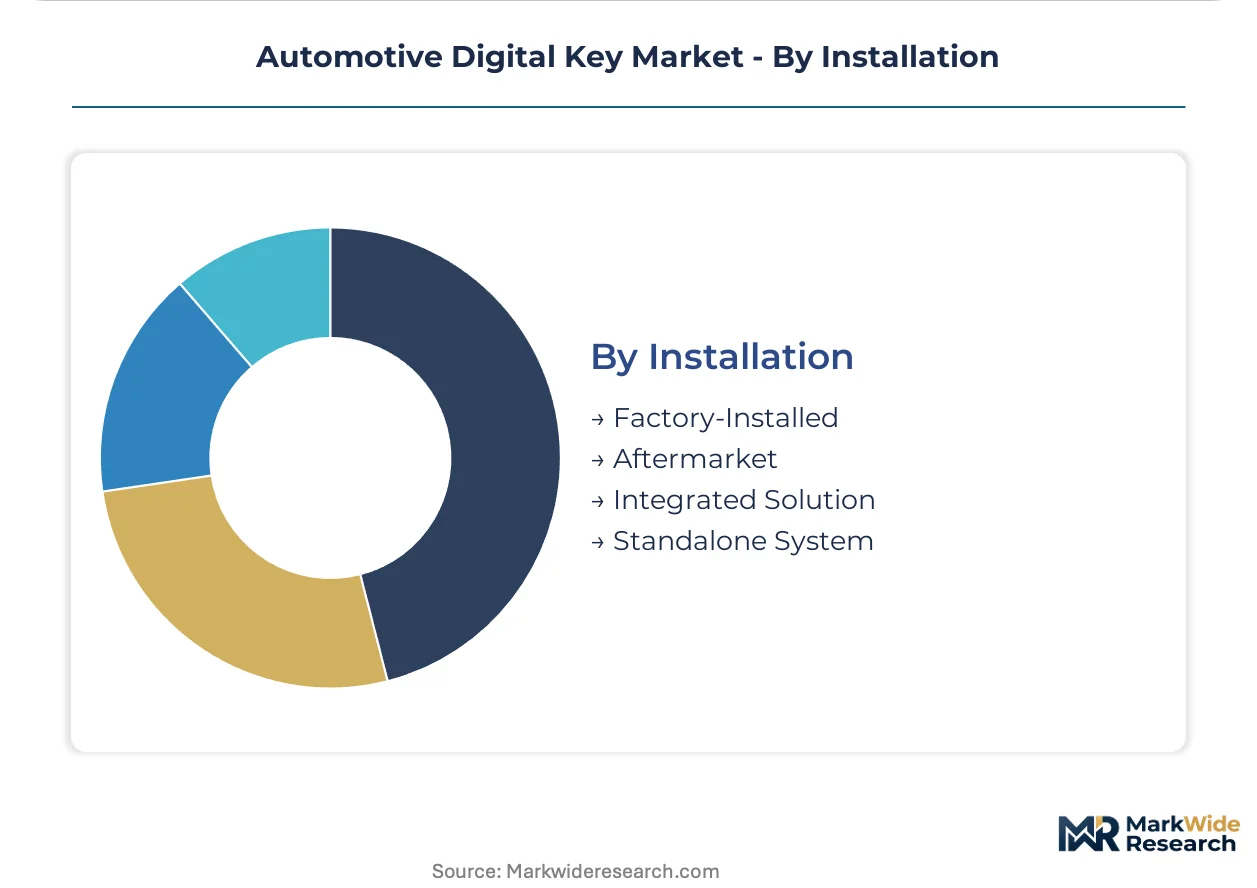
Installation:
Supply concentration and margin distribution vary sharply between factory-embedded and post-sale deployment channels, with integration depth determining aftermarket viability.
- Factory-Installed:Digital key hardware embedded at vehicle assembly enables full antenna integration, secure-element provisioning, and warranty-aligned security architecture. German production clusters around Munich and Hanover concentrate engineering investment and accelerate supplier qualification cycles for this channel.
- Aftermarket:Retrofit modules face antenna placement constraints and secure-element trust establishment challenges in vehicles not designed for digital key architecture. FCC UWB spectrum allocation rules in the United States and divergent European planning force redundant radio engineering for cross-regional aftermarket compatibility.
- Integrated Solution:Bundled hardware-software-service offerings combine vehicle-side modules with cloud credential management platforms.
- Standalone System:Discrete components without cloud connectivity serve isolated access scenarios with limited security requirements.
Factory-Installed captures the dominant share of secure-element volume. Integrated Solution is gaining share fastest as fleet procurement shifts toward platform-level supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Hanover anchor Continental and BMW engineering clusters, concentrating secure-access R&D investment and accelerating regional supplier qualification cycles for digital key deployment across multiple continents.
United States
Luxury passenger vehicle fleets in Detroit and Silicon Valley drive smartphone-based entry adoption. FCC UWB spectrum allocation rules shape radio technology feasibility for mass-market platforms. Michigan and California production corridors concentrate OEM engineering centers and tier-1 supplier partnerships.
Germany
BMW and Continental anchor production clusters around Munich and Hanover, concentrating secure-access R&D investment. UNECE WP.29 cybersecurity regulations and the EU AI Act mandate standardized secure access protocols with data-localization requirements. Bavaria and Lower Saxony engineering centers accelerate regional supplier qualification cycles for UWB module deployment.
China
Domestic EV manufacturers expand digital key integration across premium vehicle lines. MIIT and GB standards govern automotive cybersecurity certification for connected vehicle systems. Yangtze River Delta production bases concentrate semiconductor packaging and secure-element manufacturing capacity.
Japan
Automotive OEMs integrate multi-protocol digital key architectures into flagship export platforms. METI guidelines influence connected vehicle security standards and data governance frameworks. Kanto region engineering centers coordinate tier-1 supplier development for Asian market specifications.
South Korea
Domestic smartphone ecosystem penetration accelerates BLE and UWB radio adoption in vehicle access systems. MFDS and national cybersecurity frameworks shape biometric data handling requirements for driver identification systems. Seoul Capital Area technology corridors concentrate semiconductor design and automotive electronics integration.
Automotive Digital Key Market Key Industry Players
Global majors compete with regional champions across secure-element manufacturing and radio module integration, producing a tiered structure where semiconductor foundries, tier-1 automotive suppliers, and smartphone ecosystem operators occupy distinct value-capture positions. Market consolidation concentrates around multi-protocol stack providers capable of UWB-NFC-BLE integration. Three archetypes dominate: semiconductor secure-element specialists, automotive tier-1 system integrators, and consumer electronics platform operators. Capacity expansion in European foundries and strategic partnerships between OEMs and smartphone vendors represent the primary competitive moves reshaping supplier relationships.
Among semiconductor specialists, Infineon Technologies and NXP Semiconductors exemplify the secure-element manufacturing archetype, anchoring European automotive-grade silicon production. Continental AG occupies a position within the tier-1 system integrator tier, leveraging German production clustering to accelerate qualification cycles for multi-protocol digital key modules.
| Leading Market Players |
|---|
| DENSO Corp. |
| Giesecke+Devrient GmbH |
| Apple Inc. |
| Infineon Technologies |
| KPIT Technologies |
| Bayerische Motoren Werke AG |
| Ford Motor Co. |
| NXP Semiconductors |
| Continental AG |
| Others |
Cost & Logistics Intelligence
German luxury OEM procurement concentration anchors pricing power toward multi-year platform contracts with UWB-NFC-BLE stack suppliers, compressing spot-market margins for discrete component vendors. Subscription-managed credential lifecycle services are displacing one-time hardware transactions as fleet operators negotiate bundled security warranties.
Pricing Analysis
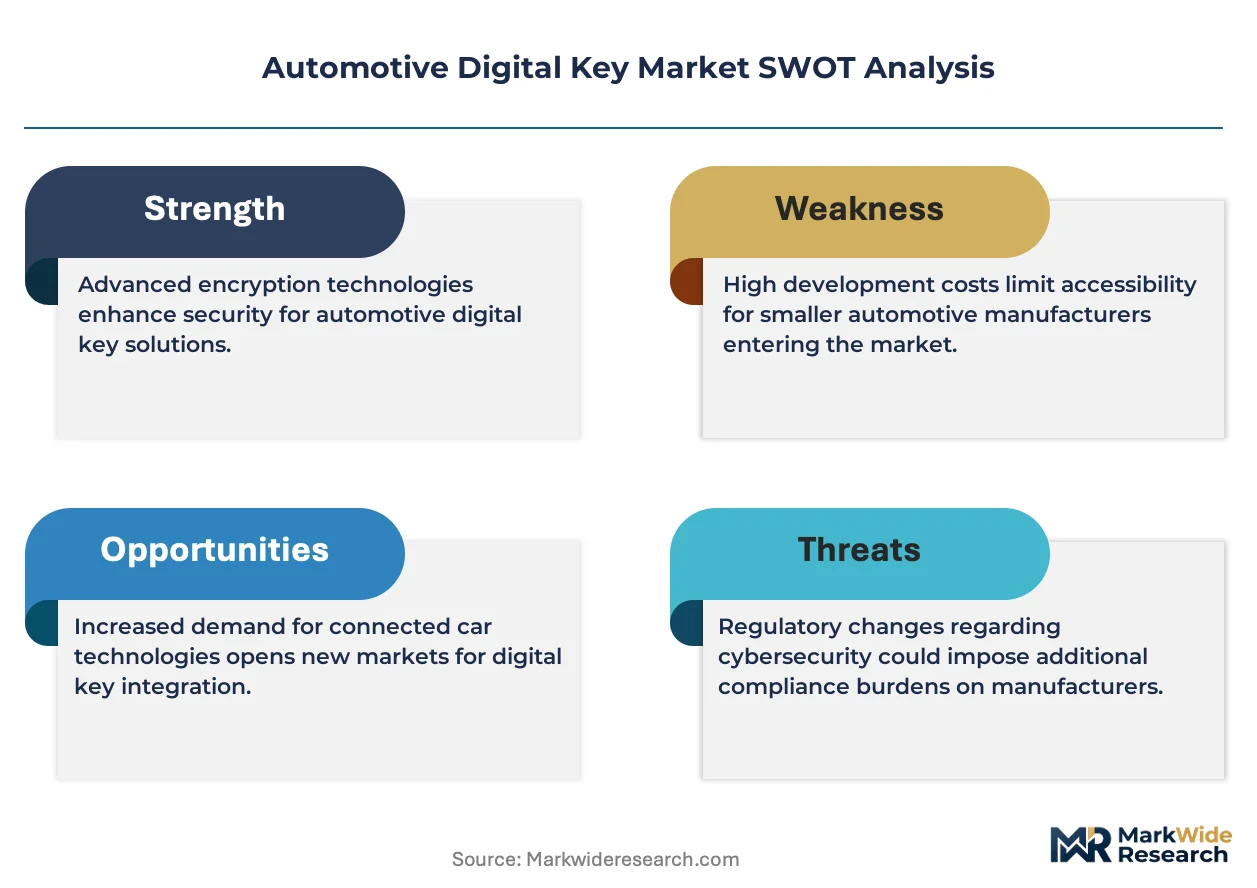
Secure-element foundry cost pass-through dominates module pricing as automotive-grade silicon qualification timelines stretch procurement cycles. Pricing stratifies across CCC-certified premium stacks, OEM-qualified standard modules, and entry-level BLE-only economy tiers. Cost compression in NFC-dominant architectures is intensifying because UWB precision positioning collapses the premium that single-protocol solutions once commanded. Fleet operators exhibit highest price sensitivity due to volume scale, while luxury OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with European foundry capacity for automotive-grade tamper-resistant silicon, exposing tier-1 procurement timelines to Infineon and NXP qualification bottlenecks. Secure-element manufacturing concentrates in Germany, Taiwan, and South Korea, while UWB radio module assembly draws from Chinese and Malaysian electronics corridors. Raw material dependencies include silicon wafers, rare-earth magnets for antenna arrays, and automotive-grade epoxy resins. Tariff exposure on Chinese-sourced connectivity silicon threatens cross-regional platform economics. Distribution runs through direct OEM supply agreements and tier-1 system integrator channels rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UNECE WP.29 cybersecurity mandates in Europe impose stricter certification costs than FCC-guided voluntary frameworks in the United States, creating arbitrage opportunities for suppliers with modular compliance architectures. German production clustering accelerates European qualification cycles while North American market entry demands redundant engineering investment.
For Market Incumbents: Acquire UWB-NFC protocol integration capabilities to neutralize relay-attack vulnerability as a competitive differentiator. Secure-element hardening expertise and CCC certification backlog management constitute critical defensive assets against emerging semiconductor specialists. Backward integration into European foundry partnerships reduces single-source exposure. Capacity addition in Lower Saxony engineering corridors reinforces proximity to BMW and Continental platform engineering centers. For New Entrants and Emerging Players: Begin with aftermarket retrofit modules for entry-level vehicle segments where factory-installed digital key penetration remains incomplete. Urban German car-sharing operators present the most penetrable fleet procurement channel, with credential lifecycle services offering recurring revenue entry. A direct-to-fleet go-to-market angle bypasses OEM qualification barriers while building installation and provisioning capabilities. For Investors and Strategic Acquirers: Automotive tier-1 system integrators are the most active acquirers in this space, consolidating multi-protocol stack providers to capture platform-level supplier relationships. Long-term viability hinges on cloud-based credential management recurring revenue attachment rates rather than hardware unit economics. Target acquisition archetypes include secure-element fabless designers with OEM qualification and UWB distance-bounding IP portfolios. The signal to watch is CCC certification queue length as a leading indicator of launch-window risk and supplier capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Radio Stack Integration | UWB-NFC-BLE convergence meets UNECE WP.29 relay-attack resistance mandates for OEM qualification. |
| Cloud Credential Lifecycle Platform | Subscription provisioning services capture recurring revenue from German car-sharing fleet operators. |
| European Foundry Partnership | Secure-element capacity anchoring reduces Infineon and NXP single-source procurement bottlenecks. |
| CCC Certification Acceleration | Standardized interoperability testing investment compresses launch-window risk for new platform introductions. |
| GDPR-Compliant Biometric Edge Computing | EU AI Act data-localization requirements drive vehicle-domain inference architecture differentiation. |
Research Approach
Bottom-up fleet operator and OEM procurement modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core of this study. Primary interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers combined with secondary validation against UNECE WP.29 regulatory filings, FCC spectrum allocation records, CCC interoperability standards, and vehicle production databases. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices map radio protocol adoption rates to secure-element demand across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion across the projection horizon. Forecast inputs include UWB module bill-of-materials trajectories and biometric ignition integration penetration curves through premium vehicle lines.
Caveats apply where UWB spectrum fragmentation between FCC and European planning authorities, or secure-element supply concentration disruptions, could materially shift the outlook. Forecasts reflect documented assumptions about regulatory harmonization timelines and OEM platform standardization decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Europe Automotive EPS Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market