
 EPS Motors Market | 2026-2036
EPS Motors Market Size, Share, and Industry Trends Forecast 2026-2036
EPS Motors Market Insights
Multi-source procurement for permanent-magnet subassemblies is expanding as Tier-1 suppliers diversify rare-earth exposure beyond single-country dependence. Bosch leverages in-house magnet recycling capabilities to stabilize feedstock costs. JTEKT anchors its competitive stance through dedicated steering-system integration labs in Japan and Europe. Nidec dominates high-volume brushless DC production for compact vehicle platforms.
An EPS motor is an electromechanical actuator that converts electrical energy into controlled rotational torque for power-assisted steering, typically operating at 12-42 volts with peak efficiencies above 90 percent to reduce parasitic engine load. DC brushless technology leads unit shipments due to superior thermal tolerance and reduced maintenance intervals in rack-assist configurations. Servo motor architectures are gaining traction in steer-by-wire prototypes where redundant torque feedback is critical. AC induction variants occupy a mature niche within commercial vehicle hydraulic-retrofit programs.
NHTSA safety standards, EPA corporate average fuel economy rules, and EU REACH restrictions on rare-earth processing collectively shape motor design trajectories and material qualification pathways. OEMs must certify electromagnetic compatibility under ECE R10 and demonstrate functional safety to ISO 26262 ASIL-D for steering-column integration. Stakeholders should monitor magnet-recycling economics and regional subsidy shifts for rare-earth independence before committing to captive smelter investments.
Market Dynamics
Permanent-magnet supply concentration in China is forcing Tier-1 suppliers to reconfigure sourcing strategies and accelerate alternative magnet chemistry development for brushless EPS architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:Stringent fleet efficiency targets compel OEMs to replace hydraulic power steering with electric assist, directly stimulating DC brushless motor procurement across light-duty vehicle programs.
- Rare-earth magnet recycling infrastructure:Emerging pyrometallurgical and hydrometallurgical recovery capabilities in Germany and Japan are reducing virgin neodymium dependence and stabilizing feedstock cost volatility for motor manufacturers.
- Steer-by-wire development programs:Redundant torque-feedback servo architectures are creating incremental motor demand for prototype validation fleets in premium passenger vehicle segments.
Market Restraints
- Neodymium-dysprosium price volatility:Concentrated rare-earth mining and processing in China's Inner Mongolia region exposes motor producers to abrupt input cost spikes and export quota disruptions.
- ISO 26262 ASIL-D certification timelines:Functional safety validation for steering-column integration demands 18-24 month qualification cycles, compressing product launch windows and elevating engineering overhead.
- AC induction motor legacy installed base:Mature hydraulic-retrofit programs in commercial vehicle fleets delay full electrification transitions and cap near-term brushless unit volume expansion.
Strategic Opportunities
- India PLI scheme for automotive components:Production-linked incentives for advanced driver-assistance systems and electric powertrains are attracting motor assembly investments targeting domestic OEM procurement and export hubs.
- Ferrite-assisted hybrid magnet topologies:Converging ferrite and reduced-rare-earth formulations are expanding into compact vehicle platforms where torque-density requirements are moderating.
- Direct-to-OEM component supply contracts:Bypassing traditional Tier-1 steering system integrators through dedicated motor supply agreements is capturing margin previously absorbed by intermediate assemblers.
Industry Challenges
- Electromagnetic compatibility engineering talent scarcity:ECE R10 certification expertise resides with a limited pool of specialists in Germany and Japan, constraining validation throughput for new market entrants.
- Multi-source magnet qualification complexity:Qualifying alternative rare-earth suppliers in Vietnam and Australia demands redundant metallurgical testing and traceability documentation that extends procurement cycles.
- Legacy vehicle electrical architecture integration:Retrofitting 12-volt brushless EPS into aging platform designs requires custom controller firmware that fragments production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPS Motors Market |
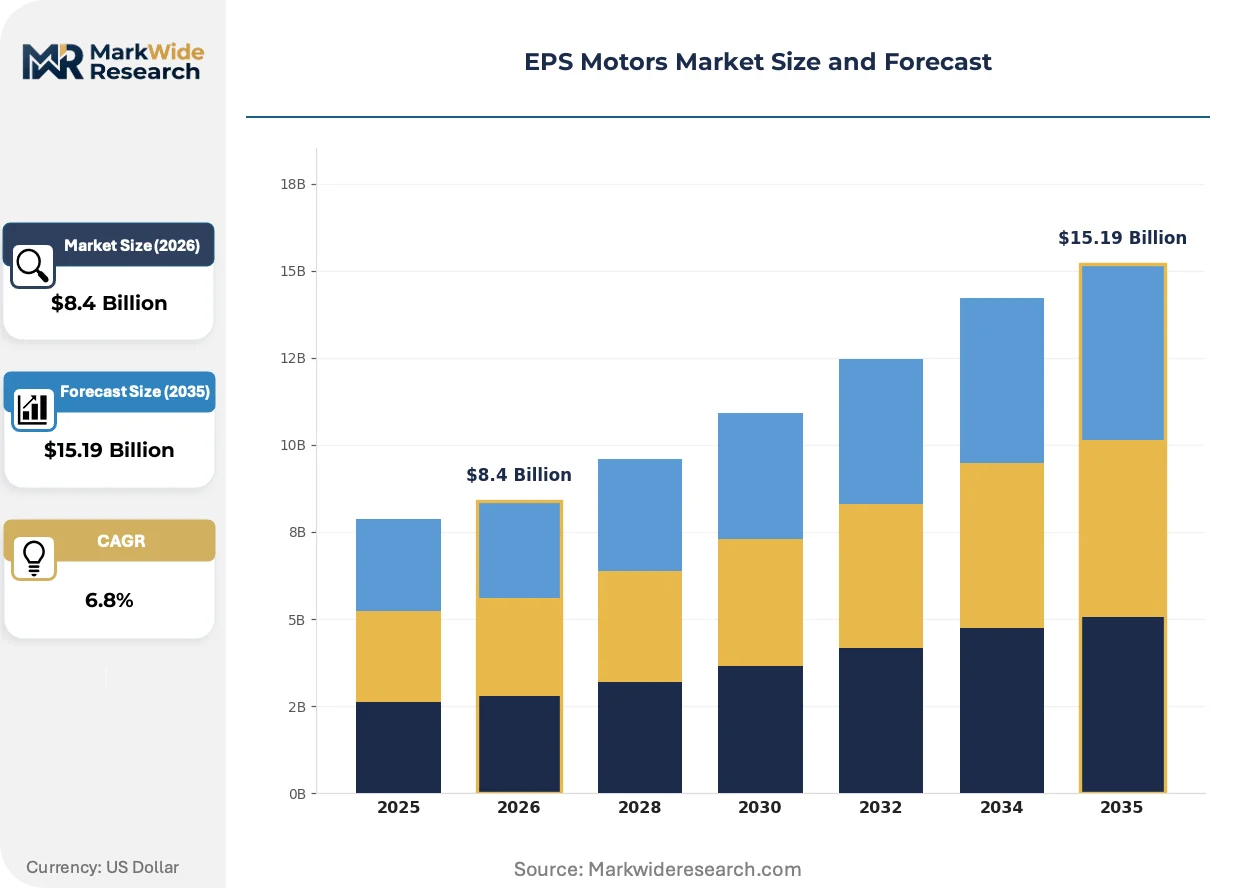
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors Technology: Brushless, Brushed, Induction, Synchronous Application: Automotive, Robotics, Industrial Automation, HVAC End User: Manufacturers, OEMs, Aftermarket, Distributors |
| Companies Covered | Johnson Electric, Bosch, JTEKT, Nidec, MITSUBA, Toshiba, FZB, LG Innotek, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPS Motors Market Trends and Innovations
Magnet chemistry diversification and torque-sensor integration are compressing motor footprints while elevating functional safety requirements for next-generation steering architectures.
Hairpin winding configurations in brushless DC stators are expanding into high-volume compact vehicle platforms. Tier-1 suppliers in Germany and Japan are adopting concentrated winding topologies to improve slot fill factors and thermal dissipation. This manufacturing shift is expanding into cost-sensitive segments previously reserved for conventional round-wire constructions.
EU REACH restrictions on rare-earth processing are compelling magnet suppliers to document full supply chain provenance and hazardous substance compliance. The regulation's industrial consequence is extended qualification timelines for new motor designs and accelerated investment in closed-loop recycling capabilities. Asian motor assemblers are responding by establishing European magnet finishing facilities to satisfy regional content requirements.
Fleet operators are consolidating EPS motor procurement through long-term supply agreements that bundle predictive maintenance analytics with hardware supply. Traditional spot-market component purchasing is yielding to performance-based contracts where uptime guarantees determine pricing tiers. This behavioral shift is most visible in German commercial vehicle leasing programs where total cost of ownership metrics dominate supplier selection criteria.
EPS Motors Market Segmentation
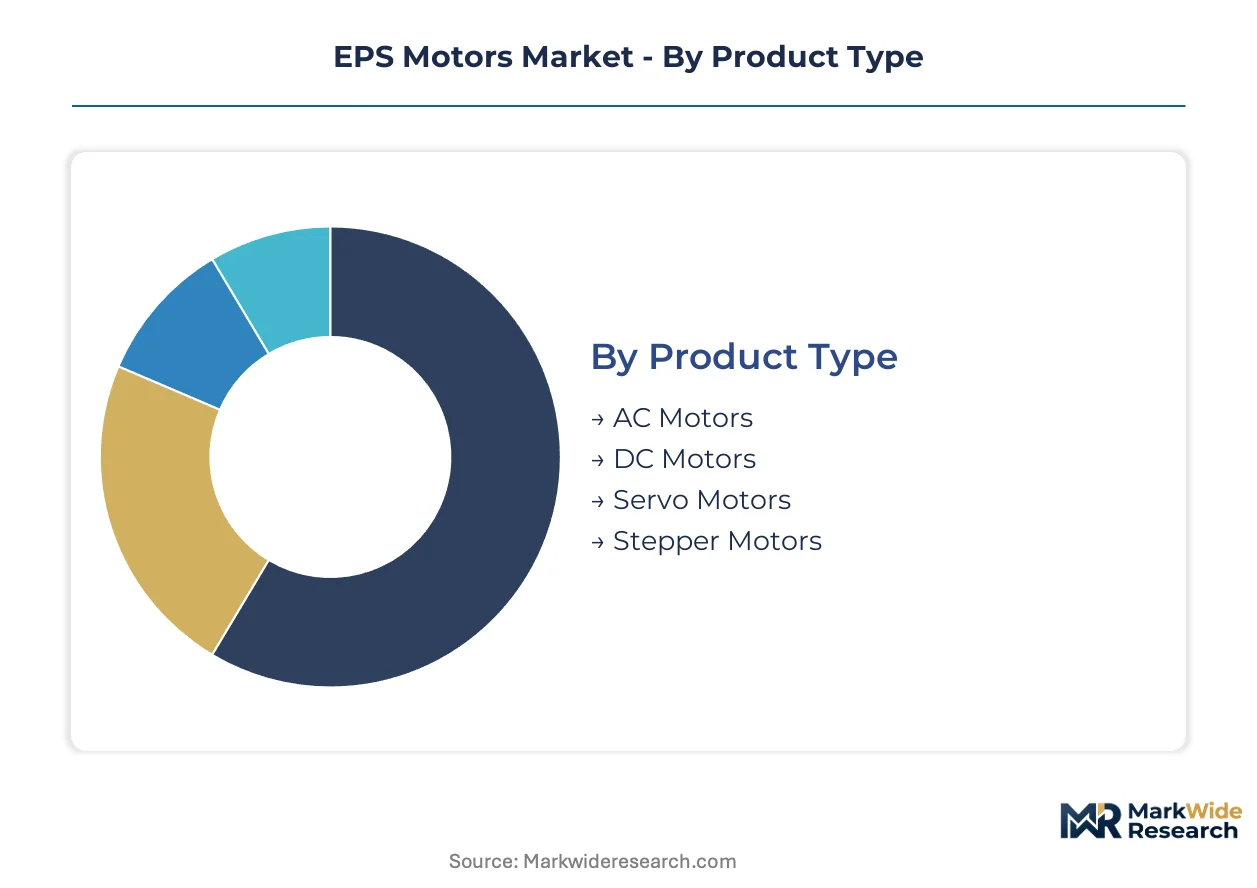
Motor topology and integration depth determine procurement economics across EPS supply chains. Segment boundaries reflect divergent thermal tolerances, magnet dependencies, and functional safety requirements that shape supplier qualification pathways.
Product Type:
Integration depth varies sharply across motor architectures, with standalone rack-assist units commanding distinct procurement protocols from embedded column-drive assemblies.
- DC Motors:Brushless DC architectures dominate rack-assist configurations through superior thermal tolerance above 90 percent peak efficiency. Demand concentrates in German and Japanese OEM light-duty platforms where EPA fuel-economy mandates compel hydraulic replacement.
- AC Motors:Induction variants persist in commercial vehicle hydraulic-retrofit programs, leveraging mature controller ecosystems and reduced rare-earth exposure. Fleet operators in North American heavy-duty segments favor these units for total cost of ownership metrics.
- Servo Motors:Redundant torque-feedback architectures for steer-by-wire prototypes.
- Stepper Motors:Limited EPS adoption; occasional use in diagnostic calibration equipment.
Volume placements concentrate in DC Motors; the faster expansion belongs to Servo Motors.
Technology:
Cost tier stratification separates premium brushless systems from economy brushed alternatives, with magnet chemistry driving the widest price spreads.
- Brushless:Hairpin winding configurations improve slot fill factors and thermal dissipation. Nidec dominates high-volume production for compact vehicle platforms where reduced maintenance intervals justify unit premiums.
- Brushed:Commutator wear limits service life; residual demand in emerging-market retrofit programs.
- Induction:Mature niche in commercial vehicle fleets delaying full electrification transitions.
- Synchronous:Ferrite-assisted hybrid magnet topologies gain traction in cost-sensitive segments.
Brushless technology captures the dominant revenue share; synchronous architectures are climbing the fastest on reduced rare-earth formulations.
Application:
Customer type divergence splits specification requirements between safety-critical automotive integration and precision-focused industrial motion control.
- Automotive:ISO 26262 ASIL-D certification demands 18-24 month qualification cycles. China, Germany, and Japan concentrate the highest OEM procurement volumes for steering motor assemblies.
- Robotics:Precision torque control for collaborative arm joints.
- Industrial Automation:Conveyor and positioning systems with moderate duty cycles.
- HVAC:Damper actuation and fan drive applications outside steering-specific torque requirements.
Automotive applications anchor procurement scale; robotics represents the steepest expansion trajectory on precision servo demand.
End User:
Supply concentration determines margin capture, with direct OEM contracts bypassing traditional Tier-1 integrators.
- OEMs:Long-term supply agreements bundle predictive maintenance analytics with hardware. German commercial vehicle leasing programs drive performance-based contract adoption.
- Manufacturers:Tier-1 steering system integrators like Bosch and JTEKT.
- Aftermarket:Replacement units for legacy hydraulic system conversions.
- Distributors:Spot-market component purchasing yielding to consolidated procurement.
OEM direct contracts dominate value capture; aftermarket channels are gaining share fastest on fleet electrification retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium mining concentration in China's Inner Mongolia region anchors the raw-material foundation for brushless EPS motor production. Germany and Japan concentrate the highest OEM procurement volumes for steering motor assemblies. The United States and India represent emerging demand centers where regulatory pressure and production incentives are reshaping local supply chain configurations.
China
Domestic OEM procurement for compact vehicle platforms and export-oriented Tier-1 supply contracts drive volume demand. MIIT dual carbon goals and GB standards for vehicle electrification compress timelines for hydraulic steering replacement. The Yangtze River Delta cluster around Shanghai concentrates magnet finishing facilities established by Asian motor assemblers to satisfy EU REACH regional content requirements.
Germany
Premium passenger vehicle steer-by-wire development programs and commercial vehicle fleet electrification create differentiated motor demand. KBA type-approval requirements and EU CO2 fleet targets tighten torque-assist specifications for light-duty platforms. The Stuttgart and Munich industrial corridors host dedicated steering-system integration labs where functional safety validation to ISO 26262 ASIL-D occurs.
Japan
High-volume brushless DC production for compact vehicle platforms and rare-earth magnet recycling infrastructure investment stabilize feedstock costs. METI industrial policy supports alternative magnet chemistry development to reduce single-country dependence. The Nagoya and Tokyo metropolitan areas concentrate electromagnetic compatibility engineering talent for ECE R10 certification.
United States
EPA Corporate Average Fuel Economy mandates compel hydraulic power steering replacement across light-duty vehicle programs. NHTSA safety standards shape motor design trajectories for steering-column integration. The Detroit automotive cluster and Southeast manufacturing belt attract motor assembly investments targeting domestic OEM procurement and NAFTA-region export hubs.
India
Production-linked incentives for advanced driver-assistance systems and electric powertrains attract motor assembly investments. The PLI scheme for automotive components targets domestic OEM procurement and export hub development. The Maharashtra and Tamil Nadu automotive corridors concentrate emerging Tier-1 supplier facilities qualifying alternative rare-earth suppliers from Vietnam and Australia.
EPS Motors Market Competitive Landscape
Global majors compete with regional champions across magnet sourcing and functional safety certification capabilities. The vendor base stratifies into three tiers: integrated steering-system suppliers with captive motor production, specialized motor manufacturers supplying multiple Tier-1 integrators, and emerging Asian fabricators competing on cost. Strategic archetypes include magnet-recycling specialists, hairpin-winding technology leaders, and direct-to-OEM contract disruptors. Dominant competitive moves encompass backward integration into permanent-magnet supply and geographic expansion through dedicated regional assembly facilities.
Among Japanese-based integrated suppliers, JTEKT and Nidec exemplify divergent strategic positions. JTEKT anchors the steering-system integrator archetype through dedicated integration labs in Japan and Europe. Nidec occupies the high-volume brushless production specialist tier for compact vehicle platforms. Bosch, a German GmbH-structured conglomerate, represents the magnet-recycling capability leader with in-house feedstock cost stabilization. These three companies collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning across the EPS motor value chain.
| Leading Market Players |
|---|
| Johnson Electric |
| Bosch |
| JTEKT |
| Nidec |
| MITSUBA |
| Toshiba |
| FZB |
| LG Innotek |
| Hitachi |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ASIL-D qualified brushless systems and economy-tier brushed alternatives manifests in both component pricing and magnet sourcing configurations. Premium motor assemblies command three-tier pricing stratification across OEM direct contracts, Tier-1 bundled supply, and aftermarket spot procurement, with each tier embedding distinct rare-earth exposure and warranty term structures.
Pricing Analysis
Warranty bundling separates long-term predictive maintenance agreements from bare hardware transactions. OEM direct contracts integrate uptime guarantees and field service coverage, while spot-market distributors trade unbundled units with limited recourse. Price differentiation hinges on ISO 26262 certification tier and magnet chemistry grade, with ferrite-assisted hybrids compressing mid-range quotations. Pricing pressure stems from neodymium-dysprosium volatility transmitted through Tier-1 procurement channels. Fleet operators exhibit highest price sensitivity; premium passenger vehicle platforms absorb certification premiums with minimal elasticity.
Supply Chain Analysis
ISO 26262 ASIL-D qualification gates Tier-1 supplier approval, extending procurement cycles and concentrating qualified volume among established integrators. Magnet finishing concentrates in China, Germany, and Japan, with Yangtze River Delta facilities serving export markets. Raw material dependencies center on neodymium-iron-boron alloys, copper hairpin windings, and silicon steel laminations. Single-source vulnerability in China's Inner Mongolia mining region threatens feedstock continuity. Distribution runs through captive Tier-1 assembly plants rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPS motor supply is consolidating around magnet-recycling capabilities and functional safety certification depth, with rare-earth price volatility forcing subscale producers toward exit or acquisition.
For Market Incumbents: Anchor competitive position through captive magnet recycling infrastructure and dedicated regional assembly facilities in Germany and Japan. ISO 26262 ASIL-D certification depth creates defensive moats against emerging Asian fabricators. Backward integration into permanent-magnet supply stabilizes input cost exposure against Chinese export quota disruptions. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized automotive corridors and Vietnam-sourced rare-earth qualification programs. The commercial vehicle hydraulic-retrofit segment offers lowest certification barriers for brushless DC penetration. Direct-to-OEM contract structures bypass entrenched Tier-1 margin capture. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated steering-system suppliers seeking hairpin-winding technology and ECE R10 certification capabilities. Long-term viability favors recyclers and rare-earth chemistry innovators over commodity assemblers. Monitor MIIT dual carbon enforcement intensity as inflection signal for Chinese magnet export policy.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Infrastructure Investment | Bosch's in-house pyrometallurgical capabilities stabilize neodymium feedstock costs against Chinese quota volatility. |
| Hairpin Winding Manufacturing Scale-Up | Nidec's concentrated slot-fill topology expands thermal tolerance for compact vehicle platform procurement. |
| Steer-by-Wire Servo Architecture Development | JTEKT's redundant torque-feedback prototypes capture premium passenger vehicle validation demand. |
| Alternative Magnet Chemistry R&D | Ferrite-assisted hybrid formulations reduce dysprosium dependence for cost-sensitive segment penetration. |
| Direct-to-OEM Supply Contract Negotiation | Bypassing Bosch and JTEKT integration layers captures margin previously absorbed by intermediate assemblers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and magnet recycling facility operators. EPA fuel-economy rulemakings, EU REACH substance restrictions, and MIIT dual carbon guidelines provided regulatory boundary conditions. Bottom-up motor shipment estimates triangulated against top-down vehicle production forecasts from IHS Markit registration databases.
Granularity-level modeling tracked brushless DC, AC induction, and servo architectures across rack-assist and column-drive integration depths. Vehicle class, propulsion architecture, and regional OEM procurement cluster dimensions shaped volume and value outputs across the projection horizon. CAGRs derived from segment-level growth rate synthesis with rare-earth price trajectory assumptions. Magnet chemistry adoption curves and steer-by-wire prototype deployment timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese export quota policy and alternative magnet chemistry breakthrough timing. Model outputs reflect documented assumptions on OEM electrification timelines and PLI scheme disbursement rates. A model refresh is warranted upon material change in MIIT dual carbon enforcement or EU REACH rare-earth processing restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market