
 Japan Automotive EPS Market | 2026-2036
Japan Automotive EPS Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive EPS Market Foresight
A widening capital-intensity gap between integrated motor producers and assembly-only suppliers is rotating procurement leverage toward companies with in-house magnetic material capabilities. JTEKT Corporation leverages its bearing-to-steering vertical chain to sustain margin control across rack-assist production. DENSO Corporation anchors high-volume sensor integration for digital-control architectures. NSK Ltd. competes through precision ball-screw specialization in column-assist systems.
Japan Automotive EPS refers to electromechanical steering assistance systems that replace hydraulic pumps with brushless DC motors, torque sensors, and ECU modules operating at 12-42V architectures to reduce fuel consumption by eliminating engine-driven hydraulic loads. The technology serves primarily to enable advanced driver-assistance functions while cutting parasitic losses in internal-combustion and electric powertrains. Column-assist configurations retain dominance in compact passenger vehicles where packaging constraints favor motor placement behind the dashboard. Rack-assist architectures are capturing expanded share in electric vehicles demanding higher steering rack forces from heavier battery platforms. Full-electric systems without mechanical backup columns remain nascent but concentrate development investment among OEM-facing Tier-1 suppliers.
METI fuel-economy standards and JIS safety certifications shape product validation timelines, forcing suppliers to synchronize ECU firmware updates with homologation cycles. The PMDA-equivalent roadworthiness framework under Japan's Ministry of Land, Infrastructure, Transport and Tourism mandates fail-safe redundancy for steer-by-wire precursors, elevating sensor-technology compliance costs. Stakeholders must monitor METI's next-phase carbon-neutral technology roadmap for signals on subsidies that could accelerate full-electric EPS replacement of residual hydraulic-electric hybrid systems.
Market Dynamics
The transition from hydraulic-electric hybrid systems to full-electric EPS architectures is compressing supplier margins while elevating firmware-validation costs under METI homologation timelines. Rack-assist configurations are capturing procurement priority as battery-electric vehicle platforms multiply across domestic OEM lineups.
Growth Catalysts
- METI Carbon Neutrality Roadmap:Subsidy eligibility tied to full-electric steering systems accelerates OEM procurement of rack-assist units over residual hydraulic architectures.
- Sensor Fusion Integration:Torque-angle sensors enabling ADAS Level 2+ functionality are becoming mandatory specification items in domestic premium vehicle segments.
- Kanto Manufacturing Belt Concentration:Proximity between Toyota City assembly plants and Nagoya corridor component suppliers compresses logistics costs and prototype iteration cycles.
Market Restraints
- Rare Earth Magnet Cost Volatility:Neodymium and dysprosium price swings embedded in brushless DC motor rotors destabilize Tier-1 supplier quoting models across multi-year contracts.
- Single-Source ECU Firmware Risk:Homologation lock-in with specific semiconductor foundries creates vulnerability to automotive-grade chip allocation constraints.
- Hydraulic-Electric Hybrid Persistence:Commercial vehicle segments retain hydraulic backup systems due to steering-force redundancy requirements under JIS safety certifications.
Strategic Opportunities
- Steer-by-Wire Precursor Systems:Fail-safe redundant sensor architectures required under Ministry of Land, Infrastructure, Transport and Tourism roadworthiness frameworks open premium pricing tiers.
- 42V Electrical Architecture Migration:Higher-voltage motor systems enabling heavier EV steering loads create specification differentiation against legacy 12V competitors.
- Kyushu Semiconductor Corridor:Proximity to emerging domestic chip fabrication capacity offers captive sourcing advantages for ECU module production.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineering for ISO 26262 ASIL-D compliance exceeds domestic labor pool depth, forcing compensation inflation.
- Homologation Cycle Compression:METI firmware update synchronization with JIS recertification timelines extends product launch windows by 8-14 months.
- Legacy Platform Integration Friction:Mechanical backup column retention in compact vehicle segments constrains full-electric system packaging optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive EPS Market |
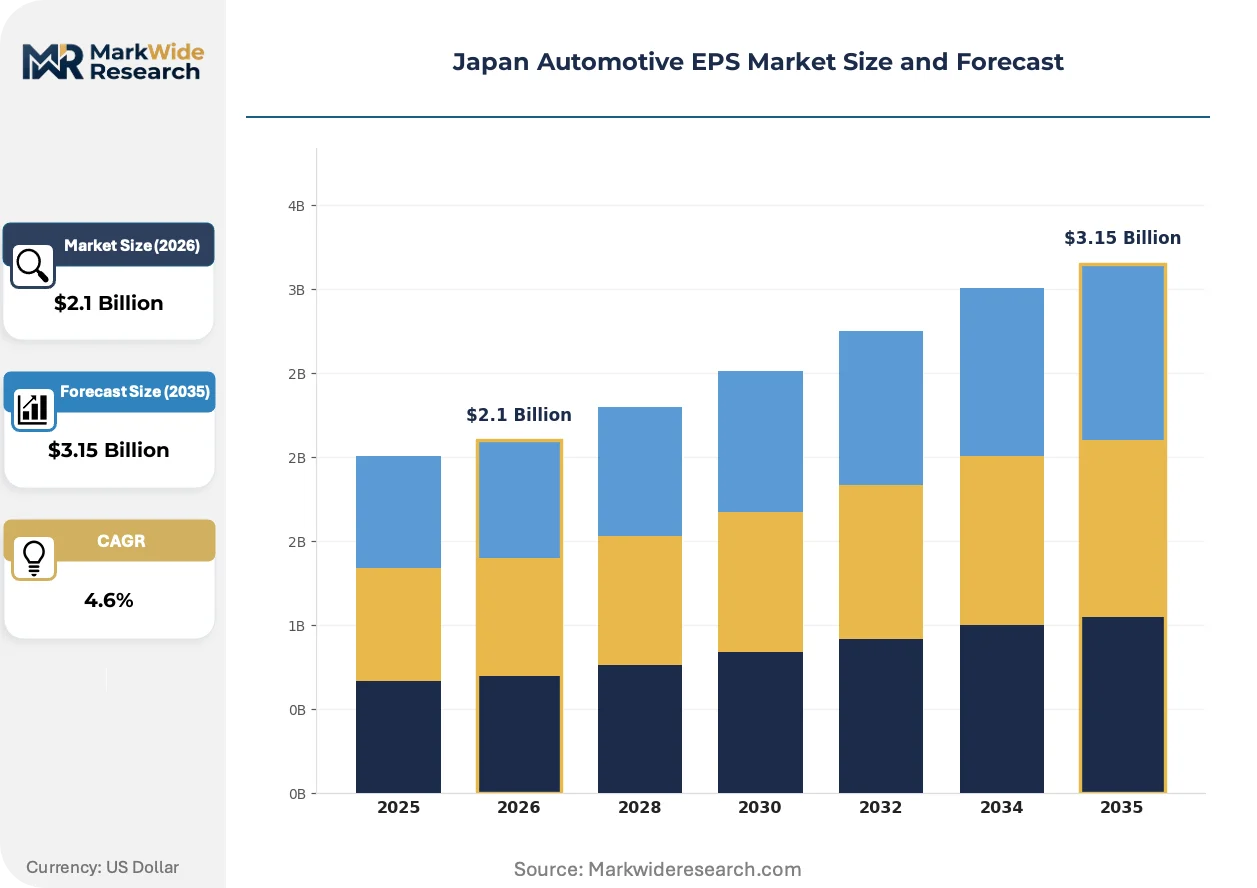
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Pull-Back Assist, Full Electric Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Off-Road Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Digital Control, Hydraulic Integration, Integrated Motors, Sensor Technology |
| Companies Covered | DENSO Corporation, Nexteer Automotive, JTEKT Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, NSK Ltd., Hitachi Astemo, Ltd., Hyundai Mobis, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive EPS Market Shifts & Advancements
Digital-control architectures and high-voltage motor platforms are restructuring supplier capability requirements faster than incumbents can reconfigure production footprints. Firmware-defined steering feel is displacing mechanical tuning as the primary value-creation layer.
Brushless DC motors with integrated position sensors are displacing conventional torque-sensor-plus-motor assemblies in rack-assist configurations. Domestic electric vehicle manufacturers are specifying these units at triple the rate of internal-combustion platforms. This displacement is compressing the addressable market for standalone sensor suppliers while elevating margin capture by integrated motor producers.
METI's next-phase fuel-economy standards are mandating parasitic loss elimination in all new vehicle registrations from 2030. The regulation forces hydraulic system phase-out timelines to accelerate by 18-24 months versus prior roadmaps. Full-electric EPS suppliers with pre-validated ECU architectures are securing sole-source positions on upcoming battery-electric platforms.
Fleet procurement departments are consolidating supplier panels from 4-6 approved vendors to 2-3 strategic partners with end-to-end firmware capabilities. Tier-1 suppliers with captive magnetic material processing and sensor calibration facilities are capturing these consolidated contracts. This concentration is most visible in the Kanto region, where Toyota-affiliated procurement organizations have completed their 2024-2025 supplier rationalization cycles.
Japan Automotive EPS Market Segmentation
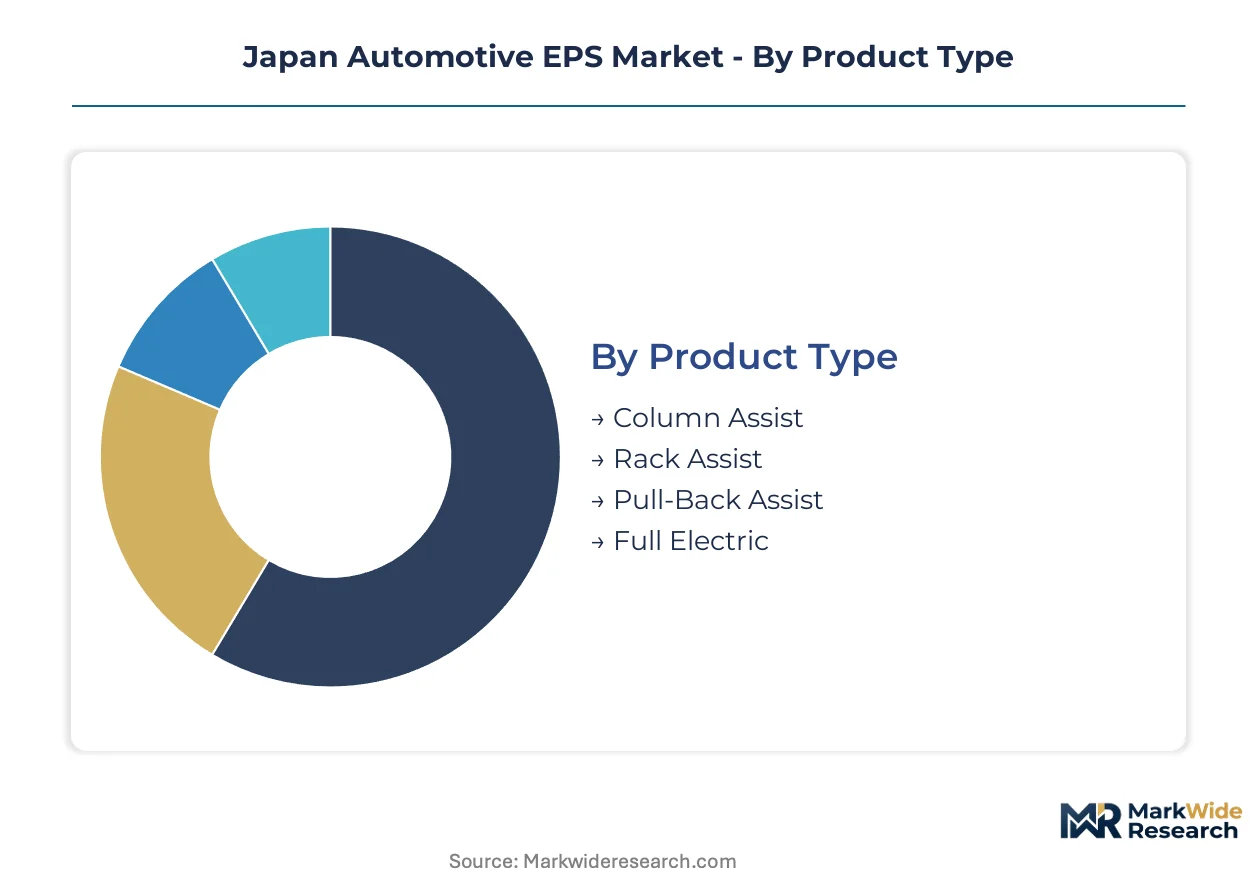
Segmentation in Japan's Automotive EPS market reveals how METI carbon neutrality mandates and JIS safety certifications are fragmenting procurement specifications across product architectures. Suppliers must align validation timelines with distinct regulatory pathways governing each configuration.
Product Type:
METI fuel-economy standards differentiate compliance burdens across motor placement architectures, with rack-assist units facing accelerated homologation cycles under battery-electric vehicle integration timelines.
- Column Assist:Motors mounted behind the dashboard retain dominance in compact passenger vehicles where packaging constraints limit firewall penetration. Kanto manufacturing belt procurement organizations specify these units for kei-car platforms under JIS D 5601 steering safety protocols.
- Rack Assist:Direct rack-mounted configurations deliver higher steering forces required by heavier battery-electric platforms. Toyota City assembly plants are tripling procurement volumes as OEMs phase out hydraulic-electric hybrid systems ahead of METI's 2030 parasitic loss elimination mandate.
- Pull-Back Assist:Specialized configurations for commercial vehicle steering-force augmentation.
- Full Electric:Steer-by-wire precursors without mechanical backup columns.
Established volume favors Column Assist; emerging adoption favors Rack Assist.
Application:
Vehicle platform electrification intensity determines EPS specification tiering, with battery mass and ADAS integration requirements driving architecture selection.
- Passenger Vehicles:Column-assist configurations dominate compact and mid-size segments where cost optimization outweighs steering-force demands. Nagoya corridor suppliers optimize production footprints for high-volume sedan and hatchback platforms.
- Commercial Vehicles:Hydraulic backup retention persists due to JIS-mandated steering-force redundancy for heavy-duty applications. METI homologation timelines extend 8-14 months for these dual-system architectures.
- Electric Vehicles:Rack-assist units with integrated position sensors are climbing the fastest as battery platform weights exceed conventional chassis specifications.
- Off-Road Vehicles:Specialized durability requirements for construction and agricultural equipment.
Procurement scale concentrates in Passenger Vehicles; specification complexity peaks in Electric Vehicles.
End User:
Supply chain position determines firmware validation responsibility and ECU architecture ownership.
- OEMs:Toyota, Honda, and Nissan procurement organizations consolidate supplier panels from 4-6 vendors to 2-3 strategic partners with captive sensor calibration facilities.
- Tier-1 Suppliers:JTEKT, DENSO, and NSK anchor high-volume production with end-to-end magnetic material processing capabilities.
- Aftermarket Providers:Replacement unit distribution for legacy hydraulic system conversions.
- Dealerships:Service-channel installation for warranty and repair segments.
Margin capture concentrates with Tier-1 Suppliers; price pressure intensifies at Aftermarket Providers.
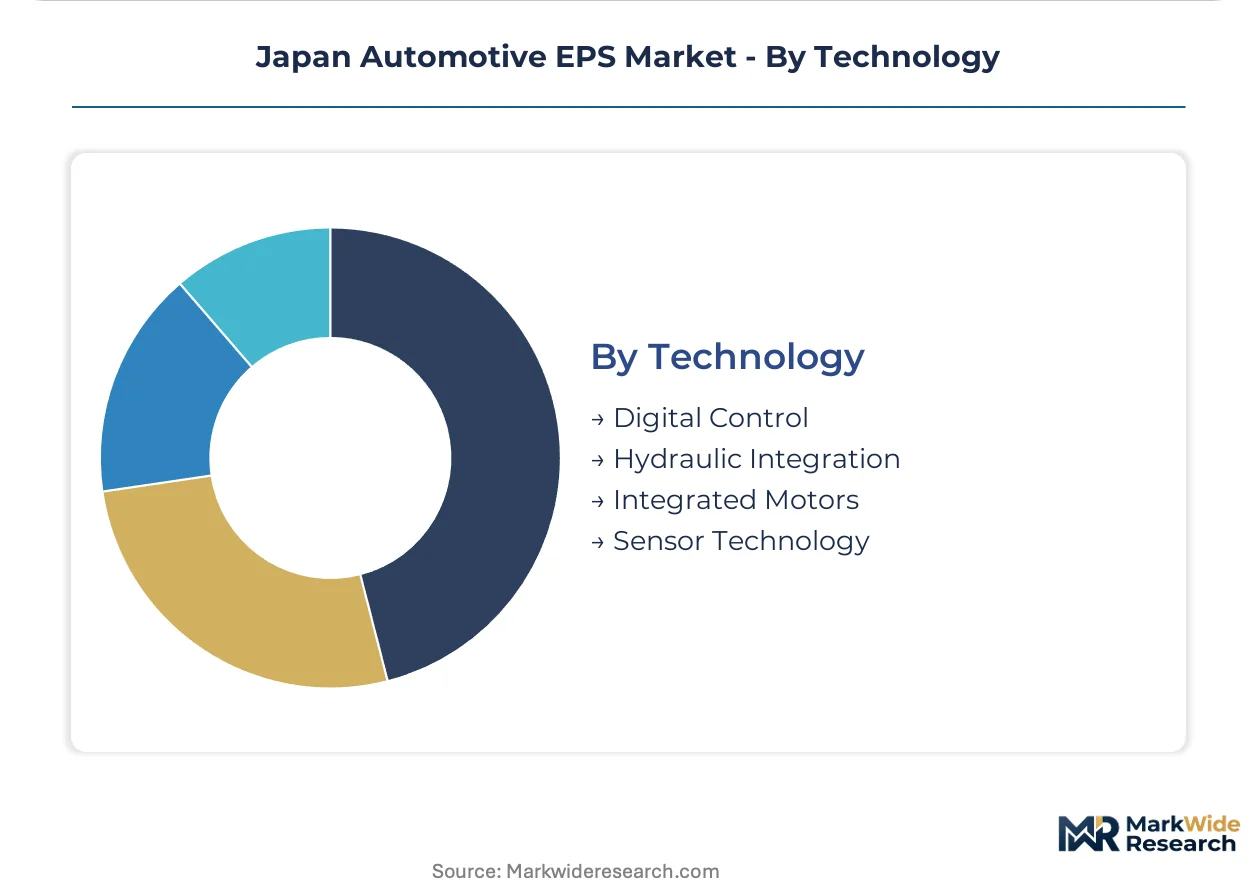
Technology:
Control architecture sophistication separates premium pricing tiers from commodity motor replacement markets.
- Digital Control:Firmware-defined steering feel with torque-angle sensor fusion enables ADAS Level 2+ functionality. Domestic premium vehicle segments mandate these specifications under Ministry of Land, Infrastructure, Transport and Tourism fail-safe redundancy frameworks.
- Hydraulic Integration:Residual hybrid architectures for commercial vehicle segments requiring mechanical backup compliance.
- Integrated Motors:Brushless DC units with embedded position sensors displace standalone torque-sensor assemblies.
- Sensor Technology:Standalone torque and angle measurement components facing compression from integrated motor displacement.
Value migration favors Digital Control; volume retention persists in Hydraulic Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across Japanese sub-regions, with Kanto manufacturing belt buyers prioritizing firmware integration over unit cost while Kyushu-based suppliers compete aggressively on magnetic material processing economics.
Kanto/Tokyo
Toyota City assembly plants anchor rack-assist EPS procurement as battery-electric vehicle platforms multiply under METI carbon neutrality mandates. The Ministry of Land, Infrastructure, Transport and Tourism enforces fail-safe redundancy requirements that extend homologation timelines for steer-by-wire precursors. Nagoya industrial corridor suppliers compress logistics costs through just-in-time delivery to Toyota City, Honda Saitama, and Nissan Oppama facilities.
Kansai/Osaka
Kei-car manufacturers in the Osaka-Kobe corridor sustain column-assist dominance where packaging constraints limit firewall penetration. JIS D 5601 steering safety protocols govern compact vehicle specifications, preserving mechanical backup column architectures. Sakai industrial zone component plants optimize high-volume production footprints for domestic hatchback and minivan platforms.
Chubu/Nagoya
Tier-1 supplier headquarters concentration creates captive sourcing advantages for sensor calibration and ECU firmware validation. METI fuel-economy standards force synchronization of product launch windows with JIS recertification cycles. Tokai region magnetic material processors supply neodymium-doped rotors to integrated motor producers, reducing rare earth price volatility exposure.
Kyushu
Emerging semiconductor fabrication capacity in Kumamoto and Fukuoka prefectures offers captive ECU module sourcing for digital-control architectures. The region's lower labor costs attract sensor-assembly operations from Kanto-based parent companies. Kyushu Economic Federation coordinates workforce development programs targeting functional safety engineering talent for ISO 26262 ASIL-D compliance.
Tohoku
Sendai-based aftermarket distribution networks service legacy hydraulic system conversions in northern Honshu commercial vehicle fleets. JIS-mandated steering-force redundancy preserves hydraulic-electric hybrid demand for heavy-duty applications. Regional suppliers specialize in pull-back assist configurations for agricultural and construction equipment durability requirements.
Japan Automotive EPS Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated motor producers commanding firmware-defined premium tiers while assembly-only suppliers compete on magnetic material sourcing efficiency. The supplier base concentrates around three strategic groupings: bearing-to-steering vertical chains, sensor-integrated digital-control specialists, and precision ball-screw component manufacturers. Consolidation pressures from OEM procurement panel reductions favor end-to-end capability ownership over modular specialization. Dominant competitive moves include backward integration into magnetic material processing and strategic partnerships with domestic semiconductor foundries.
Within the integrated systems tier, JTEKT Corporation, DENSO Corporation, and NSK Ltd. occupy positions reflecting distinct capability emphases. JTEKT exemplifies the bearing-to-steering vertical chain archetype, DENSO represents sensor-integrated digital-control specialization, and NSK sits within precision mechanical component manufacturing. These three Japanese entities anchor high-volume supply relationships with domestic OEM procurement organizations undergoing 2024-2025 supplier rationalization cycles. Foreign-owned competitors including Robert Bosch GmbH and ZF Friedrichshafen AG maintain technology licensing positions without equivalent production footprint scale in the Japanese market.
| Leading Market Players |
|---|
| DENSO Corporation |
| Nexteer Automotive |
| JTEKT Corporation |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| NSK Ltd. |
| Hitachi Astemo, Ltd. |
| Hyundai Mobis |
| Mitsubishi Electric Corporation |
| Others |
Supply & Pricing Matrix
Production scale advantages in Kanto manufacturing belt motor assembly plants compress per-unit fixed costs while simultaneously elevating price floors for non-integrated competitors lacking captive magnetic material processing. This dual-scale dynamic concentrates procurement leverage among JTEKT, DENSO, and NSK, forcing assembly-only suppliers into margin-eroding spot-market magnet sourcing.
Pricing Analysis
After-sales firmware update contracts and extended validation service agreements generate lifetime value multiples exceeding initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates rack-assist units with integrated position sensors from legacy column-assist configurations and hydraulic-electric hybrid remnants. Cost compression in economy-tier column-assist segments is intensifying because rare earth price volatility destabilizes multi-year contract quoting. Fleet procurement organizations at commercial vehicle operators exhibit highest price sensitivity, while OEM platform engineering teams prioritize firmware integration over unit cost.
Supply Chain Analysis
Rare earth concentrate processing through Chinese separation facilities creates chokepoint exposure for neodymium-doped rotor production across Japanese motor assembly plants. Domestic supply draws from China, Australia, and domestic Tokai region magnetic material processors for critical inputs including sintered neodymium magnets, silicon steel laminations, and automotive-grade ECU semiconductors. Single-source vulnerability concentrates in 12-42V motor controller chip fabrication, where allocation constraints disrupt Tier-1 supplier delivery schedules. Distribution runs through just-in-time supplier parks adjacent to Toyota City, Honda Saitama, and Nissan Oppama assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where METI homologation timelines and JIS certification lock-in create switching costs that entrench incumbents against foreign technology licensing competitors.
For Market Incumbents: Compound firmware-defined steering feel capabilities through backward integration into sensor calibration facilities, defending against emerging Korean and Chinese motor producers seeking technology licensing footholds. Prioritize captive neodymium magnet processing investments in Tokai region supplier parks to neutralize rare earth price volatility exposure. For New Entrants and Emerging Players: Lead with 42V high-voltage rack-assist architectures targeting Kyushu-based electric vehicle startups outside consolidated Toyota-Honda-Nissan procurement panels. Kei-car aftermarket conversion segments offer the most penetrable white space, accessible through dealership service channel partnerships rather than direct OEM supply relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated motor producers with end-to-end magnetic material capabilities over modular sensor specialists facing displacement. Long-term viability across the projection horizon rests on ECU firmware ownership and METI pre-validation status. The signal to monitor is METI subsidy eligibility announcements for full-electric steering systems, which would accelerate hydraulic phase-out timelines and revalue incumbent supplier contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Tokai region sintering capacity reduces rare earth price volatility exposure for rotor production. |
| Firmware-Defined Steering Platform Launch | ADAS Level 2+ torque-angle sensor fusion commands premium pricing in domestic premium vehicle segments. |
| Kyushu Semiconductor Corridor Partnership | Proximity to Kumamoto fabrication capacity secures captive ECU chip sourcing for digital-control architectures. |
| Steer-by-Wire Precursor Certification | Ministry of Land, Infrastructure, Transport and Tourism fail-safe redundancy compliance opens sole-source contract opportunities. |
| Supplier Panel Consolidation Defense | End-to-end capability ownership preserves strategic partner status under OEM 2024-2025 rationalization cycles. |
Research Methodology
Operator-level perspectives from Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and METI policy officials anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs trade records, and JIS certification filings. Bottom-up unit demand modeling and top-down market sizing triangulation cross-verified volume estimates across the analysis window.
Sensitivity analysis around rare earth price trajectories and METI subsidy eligibility scenarios framed the forecast framework. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from installed base turnover rates and platform electrification intensity assumptions, incorporating motor specification shifts from column-assist to rack-assist architectures as battery-electric vehicle penetration deepens.
The analysis sits within stated boundaries; outcomes outside sustained METI carbon neutrality enforcement or accelerated semiconductor localization would require recalibration. Forecasts reflect documented assumptions regarding homologation timeline compression and JIS recertification cycle synchronization. Practitioners should keep alternative scenarios live as rare earth supply chain restructuring and domestic chip fabrication capacity ramp rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market