
 Electrical Steering Column Lock Market | 2026-2036
Electrical Steering Column Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Steering Column Lock Market Analysis
Single-source to multi-source procurement is realigning how Tier-1 suppliers contract for electrical steering column lock modules. ZF Friedrichshafen leverages captive mechatronics production across European and North American plants to secure long-term OEM contracts. U-Shin Ltd anchors its position through specialized lock actuator manufacturing for Japanese and Korean vehicle platforms. Continental competes on integrated electronic control architectures that bundle column lock functions with steering angle sensors.
An electrical steering column lock is an electromechanical or fully electronic anti-theft device that immobilizes the steering shaft when the vehicle ignition is deactivated, typically operating through a pin-tumbler solenoid or brushless motor actuator with torque ratings between 15 and 35 Nm. The mechanism prevents unauthorized steering movement even if the ignition cylinder is compromised, serving as a mandatory passive safety layer in modern road vehicles. Passive system configurations retain the largest installed base among product types due to their lower unit cost and proven reliability in mass-market passenger vehicles, while electronic technology segments capture expanding margin pools as OEMs consolidate lock control into centralized body electronics modules. Wireless-enabled locks represent the fastest-growing technology trajectory, though mechanical hybrid variants still dominate commercial vehicle applications where electromagnetic interference resilience remains critical.
NHTSA Federal Motor Vehicle Safety Standard 114 governs theft protection and keyless ignition systems in the United States, directly mandating steering column lock performance criteria that shape product design and validation protocols. ECE Regulation 116 and the EU's General Safety Regulation extend comparable requirements across European type-approval processes, while China's GB standards under SAMR authority impose localized testing regimes for domestic-market vehicles. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces parallel anti-theft equipment rules through its motor vehicle type designation system. Stakeholders must monitor divergence between regional electromagnetic compatibility standards and evolving connected-vehicle cybersecurity mandates, as over-the-air lock control interfaces introduce new compliance vectors that will determine platform architecture choices and supplier qualification pathways.
Market Dynamics
Anti-theft mandate convergence across NHTSA, UNECE, and Japan's MLIT frameworks is compressing design validation cycles and forcing Tier-1 suppliers to requalify platforms for multi-jurisdiction homologation simultaneously.
Growth Catalysts
- MLIT Type Designation Enforcement:Japan's tightened motor vehicle theft prevention rules now require electronic steering immobilizers on all new passenger platforms, pulling actuator demand from domestic suppliers.
- Centralized Body Electronics Consolidation:OEMs are bundling column lock control into domain controllers, expanding addressable module content per vehicle.
- Eastern China Manufacturing Corridor:Domestic vehicle assemblers in Jiangsu and Zhejiang provinces source hybrid electronic-mechanical locks for export-focused production lines.
Market Restraints
- Rare Earth Magnet Cost Volatility:Neodymium price swings in Chinese spot markets directly compress margins on brushless motor actuator production.
- Single-Source Solenoid Supply:Precision pin-tumbler mechanisms rely on concentrated German and Japanese specialty metalworking suppliers, creating qualification bottlenecks.
- Electromagnetic Interference Hardening:Commercial vehicle platforms in mining and construction require mechanical hybrid backups that limit full electronic penetration.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced automotive electronics attract steering lock module assembly to Tamil Nadu and Gujarat manufacturing zones.
- Over-the-Air Lock Control Interfaces:Cybersecurity-certified wireless-enabled locks open recurring software revenue streams alongside hardware sales.
- ISO 26262 Functional Safety Convergence:ASIL-D certification for steering lock electronics creates premium positioning against uncertified competitors.
Industry Challenges
- Embedded Cybersecurity Engineering Talent:Shortage of engineers qualified in both automotive functional safety and connected-vehicle threat modeling delays OTA-capable lock development.
- Multi-Jurisdiction Homologation Parallelism:Simultaneous NHTSA FMVSS 114, ECE R116, and GB standard testing extends validation timelines and strains certification budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Steering Column Lock Market |
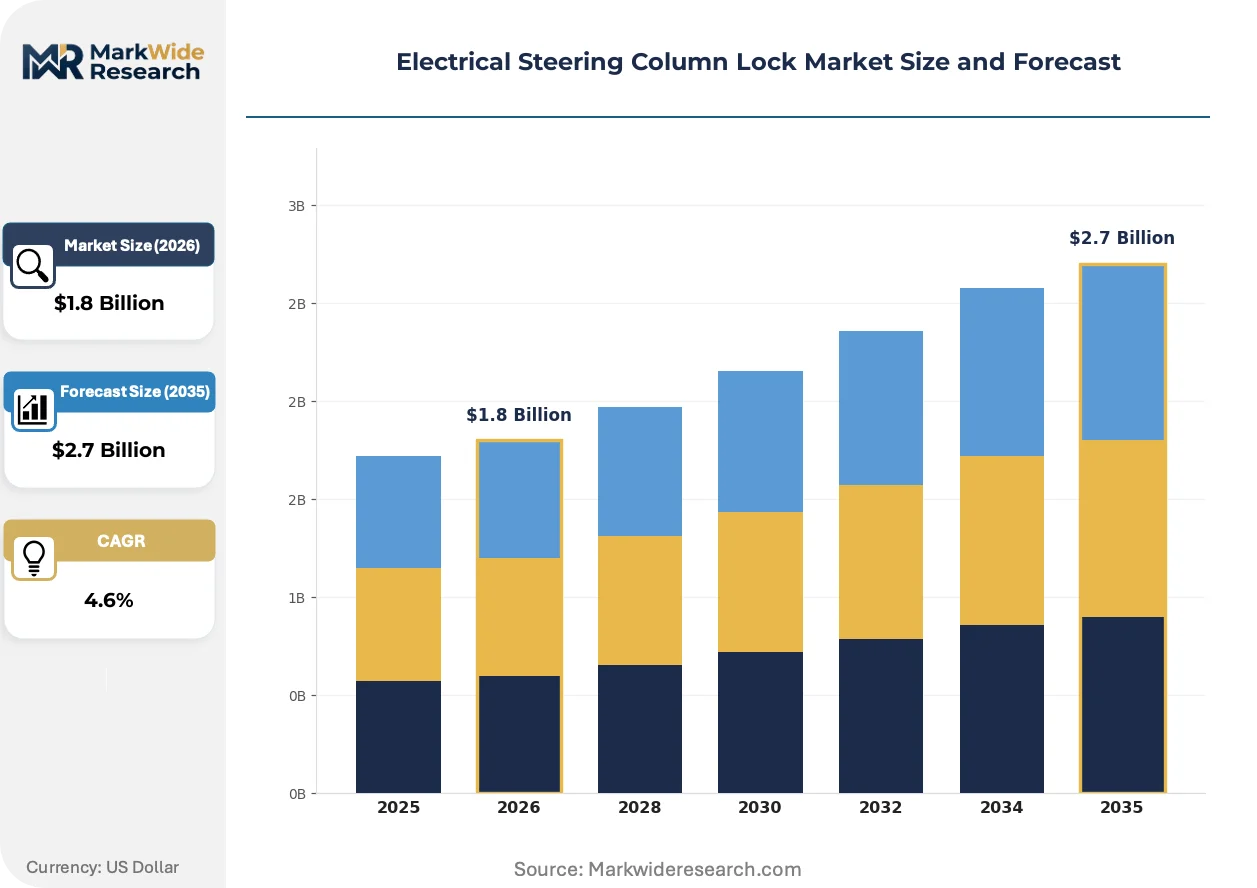
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active System, Passive System, Manual Lock, Automatic Lock End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Mechanical, Electronic, Hybrid, Wireless Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | ZF Friedrichshafen AG, U-Shin Ltd, Continental, Valeo SA, Johnson Electric, Nexteer Automotive, NSK Ltd., Huf Hülsbeck & Fürst GmbH & Co. KG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Steering Column Lock Market Emerging Trajectories
Technology trajectories in electrical steering column locks are diverging between full electronic integration for passenger vehicles and hardened hybrid architectures for commercial applications, with regulatory pressure on cybersecurity emerging as the decisive design variable.
Brushless motor actuators with integrated position sensing are absorbing torque-measurement and diagnostic functions previously handled by discrete steering angle sensors. Premium passenger vehicle OEMs in Germany and Japan are adopting these consolidated modules for new platform launches. The absorption of redundant sensing into the lock actuator itself is compressing the bill of materials for steering column assemblies and reshaping supplier competitive boundaries.
ECE Regulation 116 revisions now explicitly mandate electromagnetic compatibility testing for electronic immobilizers under expanded threat scenarios including intentional jamming. European type-approval bodies are rejecting platforms that cannot demonstrate resilience against 400 MHz band interference. Passenger vehicle segments with keyless entry systems are responding by hardening RF shielding around lock control modules and pre-qualifying for anticipated cybersecurity annexes.
Fleet operators and leasing companies are compressing supplier qualification cycles and demanding modular lock architectures that enable field-swappable actuator cores without full column replacement. This behavior is displacing traditional sealed-unit procurement contracts in North American commercial vehicle channels. The shift is most visible in rental fleet procurement specifications from operators with centralized maintenance hubs in Texas and Florida.
Electrical Steering Column Lock Market Segmentation
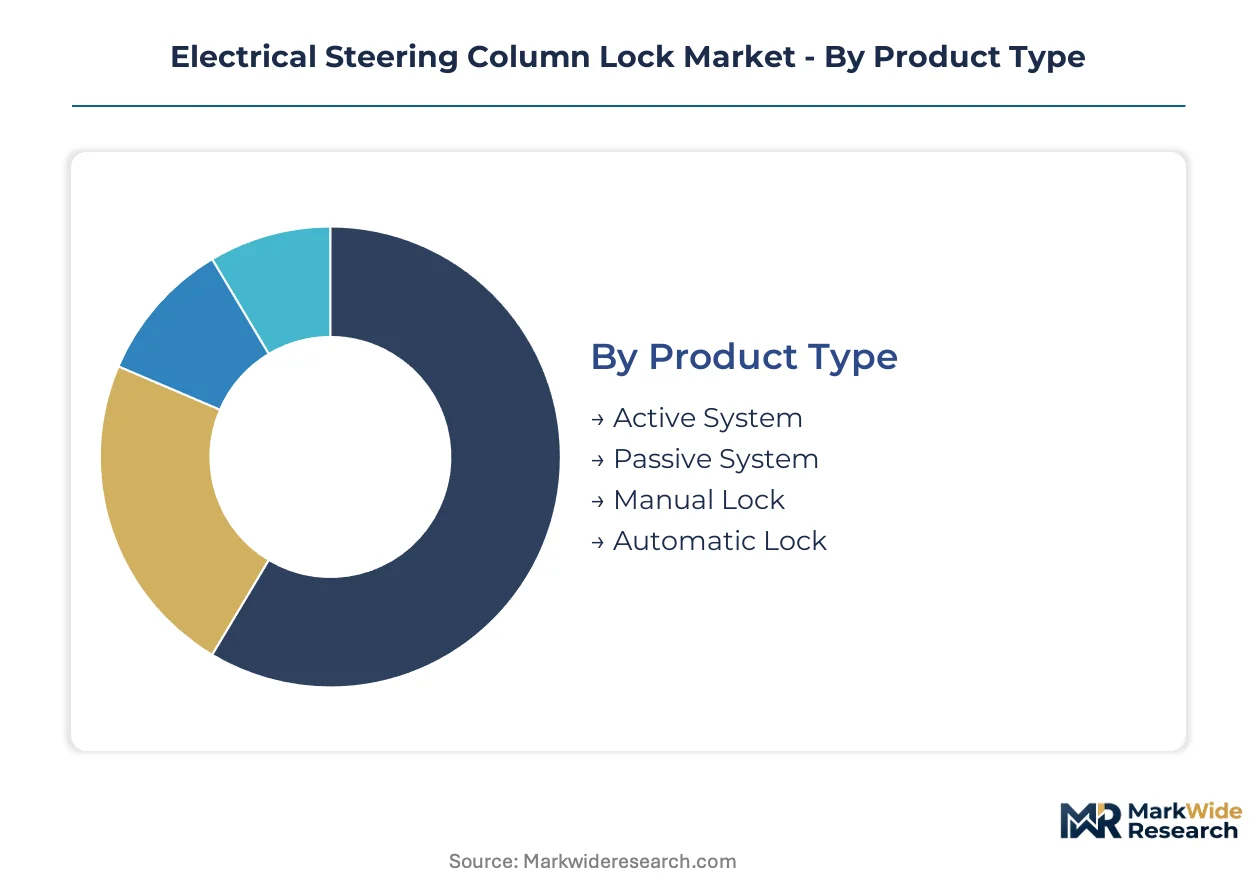
Electrical steering column lock procurement splits between standalone anti-theft modules and integrated body electronics bundles. Tier-1 suppliers calibrate R&D allocation across these boundaries based on OEM platform consolidation strategies and regional homologation requirements.
Product Type:
Standalone lock modules serve legacy platform refreshes where electronics integration lags, while embedded configurations dominate new vehicle architectures.
- Passive System:Retains the largest installed base among electrical steering column lock configurations due to proven reliability in mass-market passenger vehicles. German and Japanese OEMs specify passive systems for economy-tier platforms where unit cost sensitivity outweighs feature differentiation. Demand concentrates in China's eastern manufacturing corridor for export-focused production lines.
- Active System:Requires continuous power supply and electronic control unit communication, enabling real-time diagnostic feedback and centralized immobilizer management. Premium passenger vehicle OEMs in Germany and Japan are expanding procurement of active systems as domain controller consolidation accelerates. NHTSA FMVSS 114 compliance testing favors active architectures for keyless ignition platforms.
- Manual Lock:Mechanical override mechanisms for emergency release functions in hybrid electronic-mechanical systems.
- Automatic Lock:Triggered by ignition state changes without driver intervention, standard in electronic and wireless-enabled configurations.
Volume placements concentrate in Passive System configurations; the faster expansion belongs to Active System architectures as body electronics consolidation accelerates.
End User:
Procurement authority shifts from vehicle assemblers to domain controller suppliers as lock functions migrate into centralized electronics modules.
- OEMs:Direct specification of electrical steering column lock modules for in-house platform engineering, particularly among German and Japanese manufacturers with captive electronics divisions. OEM procurement teams now require ASIL-D functional safety certification and multi-jurisdiction homologation packages from Tier-1 suppliers.
- Vehicle Assemblers:Contract manufacturing arrangements in China's Jiangsu and Zhejiang provinces source hybrid electronic-mechanical locks for cost-optimized export platforms. These assemblers prioritize qualification speed and modular actuator architectures over proprietary electronics development.
- Fleet Operators:Centralized maintenance hubs in Texas and Florida are demanding field-swappable actuator cores without full column replacement.
- Aftermarket Providers:Replacement lock modules for collision repair and theft recovery, constrained by proprietary calibration requirements from OEM-locked electronic control units.
Contract volumes cluster with Vehicle Assemblers; margin expansion tracks toward OEM direct procurement as functional safety certification requirements tighten.
Technology:
Actuator technology selection hinges on electromagnetic interference resilience requirements and cybersecurity hardening mandates.
- Electronic:Brushless motor actuators with integrated position sensing absorb torque-measurement functions previously handled by discrete sensors. ECE Regulation 116 revisions now mandate electromagnetic compatibility testing for electronic immobilizers under expanded jamming threat scenarios.
- Wireless:Over-the-air lock control interfaces enable remote immobilization and fleet management integration, though cybersecurity certification delays deployment timelines. Fleet operators and leasing companies in North America are piloting wireless-enabled locks for rental vehicle tracking.
- Hybrid:Combines electronic control with mechanical backup actuation for commercial vehicle applications where electromagnetic interference resilience remains critical.
- Mechanical:Pin-tumbler solenoid mechanisms with torque ratings between 15 and 35 Nm, still specified for commercial vehicle platforms in mining and construction sectors.
Production volumes favor Hybrid configurations; the steepest expansion trajectory belongs to Wireless as cybersecurity-certified platforms reach series production.
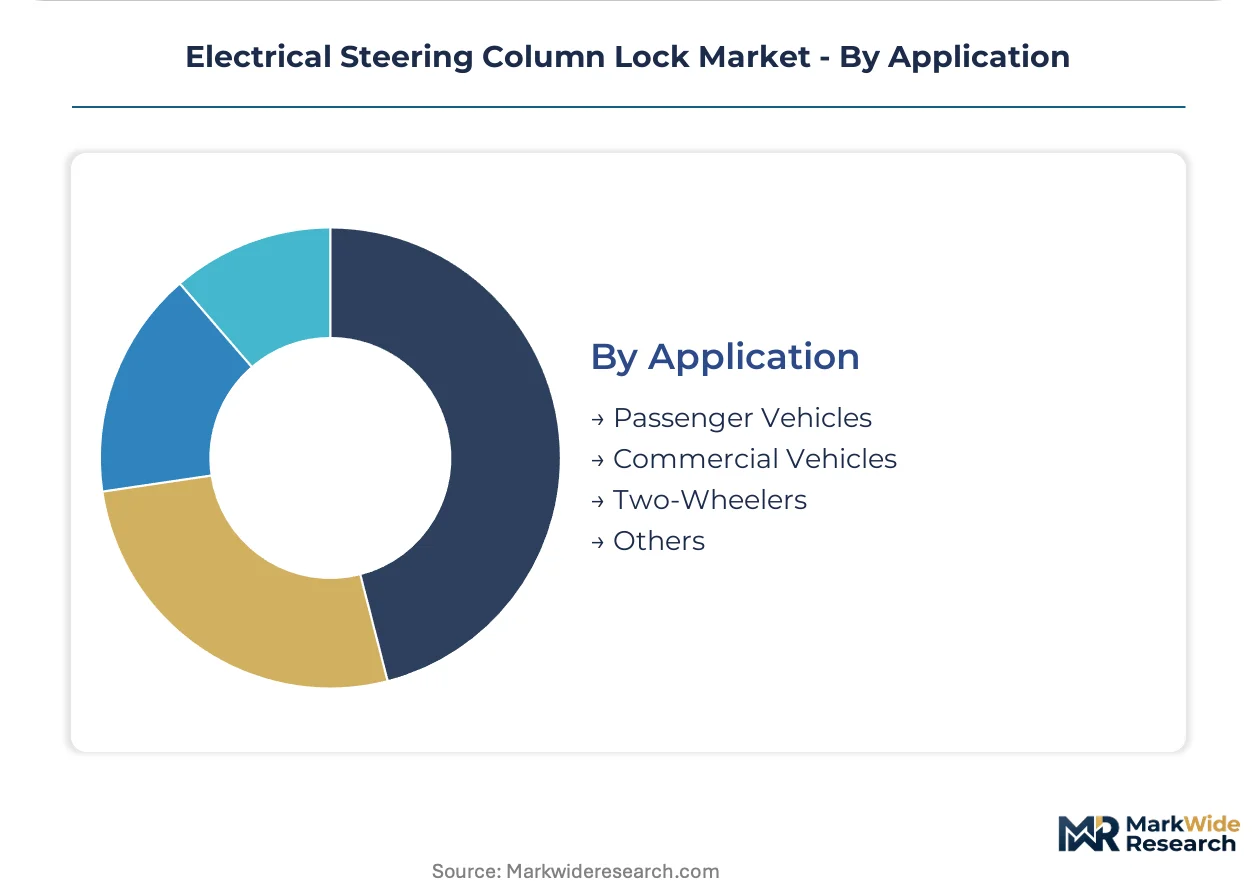
Application:
Vehicle category determines lock architecture hardening requirements and electronics integration depth.
- Passenger Vehicles:Domain controller integration drives demand for compact electronic lock modules with redundant sensing. German and Japanese OEMs specify brushless motor actuators for new platform launches, consolidating lock control into centralized body electronics.
- Commercial Vehicles:Mining and construction fleets require mechanical hybrid backups that limit full electronic penetration. ECE R116 electromagnetic compatibility testing has prompted hardened RF shielding around lock control modules in European commercial vehicle specifications.
- Two-Wheelers:Cost-optimized electronic immobilizers for emerging market scooter and motorcycle platforms, particularly in India's Tamil Nadu and Gujarat manufacturing zones under PLI scheme incentives.
- Others:Specialized off-highway and agricultural equipment with custom torque and environmental sealing requirements.
Shipment volumes dominate Passenger Vehicles; the fastest share gains belong to Two-Wheelers as India's production-linked incentive scheme attracts component assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet supply from Chinese spot markets anchors regional production economics for brushless motor actuators. Rare earth processing capacity in Jiangxi and Inner Mongolia shapes cost structures for electronic lock manufacturers worldwide. Regional demand patterns diverge sharply between passenger vehicle electronics integration and commercial vehicle mechanical hardening requirements.
China
Domestic vehicle assemblers in Jiangsu and Zhejiang provinces source hybrid electronic-mechanical locks for cost-optimized export platforms. SAMR-administered GB standards impose localized testing regimes that extend validation timelines for foreign suppliers. The Yangtze River Delta manufacturing corridor concentrates actuator assembly capacity serving both domestic OEMs and international tier-1 procurement.
United States
NHTSA FMVSS 114 mandates steering column lock performance criteria that compress design validation cycles for multi-jurisdiction homologation. Fleet operators in Texas and Florida demand field-swappable actuator cores without full column replacement. The Southeast automotive belt around Tennessee and South Carolina anchors electronic module assembly for domestic OEM platform launches.
Germany
Premium passenger vehicle OEMs specify brushless motor actuators with integrated position sensing for new platform engineering. ECE Regulation 116 and EU General Safety Regulation extend type-approval requirements that shape product validation protocols. Baden-Württemberg's automotive supplier cluster concentrates mechatronics R&D for centralized body electronics integration.
Japan
MLIT motor vehicle type designation rules now require electronic steering immobilizers on all new passenger platforms. Domestic suppliers anchor lock actuator manufacturing for Japanese and Korean vehicle platforms. The Nagoya-Tokyo industrial corridor concentrates precision metalworking capacity for pin-tumbler solenoid mechanisms.
India
PLI scheme incentives for advanced automotive electronics attract steering lock module assembly to Tamil Nadu and Gujarat manufacturing zones. Two-wheeler OEMs in these states source cost-optimized electronic immobilizers for emerging market scooter and motorcycle platforms. The Chennai-Bangalore industrial corridor is developing component testing infrastructure for ASIL-D functional safety certification.
Electrical Steering Column Lock Market Vendor Landscape
Multi-source procurement realignment dominates the current landscape as OEMs diversify supplier portfolios beyond single-source dependencies. The vendor base structures across three tiers: integrated mechatronics conglomerates with captive electronics divisions, specialized lock actuator manufacturers with precision metalworking heritage, and emerging electronics specialists pursuing domain controller integration. Strategic archetypes include full-system integrators bundling lock control with steering angle sensing, component specialists defending position through precision manufacturing, and software-capable entrants targeting over-the-air lock interfaces. Capacity expansion and strategic partnerships represent the dominant competitive moves, with qualification speed for multi-jurisdiction homologation serving as the critical differentiator.
Among European-based integrated suppliers, ZF Friedrichshafen AG and Continental occupy positions exemplifying full-system integration archetypes with captive mechatronics production across regional plants. U-Shin Ltd represents the specialized lock actuator manufacturing segment, anchoring supply relationships for Japanese and Korean vehicle platforms through precision mechanism expertise. These three companies illustrate the competitive tension between electronics consolidation and mechanical specialization that defines current procurement dynamics.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| U-Shin Ltd |
| Continental |
| Valeo SA |
| Johnson Electric |
| Nexteer Automotive |
| NSK Ltd. |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Precision metalworking engineers concentrated in Germany's Baden-Württemberg and Japan's Nagoya-Tokyo corridor command wage premiums that widen spreads between economy-tier passive locks and ASIL-D certified active systems. Labor-cost differentials between these engineering clusters and China's Yangtze River Delta assembly zones feed directly into three-tier pricing stratification across warranty-bundled, standard-validation, and unbundled procurement categories.
Pricing Analysis
Warranty and multi-jurisdiction homologation bundling separates premium-tier suppliers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with ASIL-D functional safety certification commanding substantial premiums. Cost compression in economy-tier hybrid electronic-mechanical locks is intensifying because Chinese domestic assemblers prioritize qualification speed over proprietary electronics development. Fleet operators in North America show least price sensitivity due to lifecycle cost framing, while China's export-focused vehicle assemblers exhibit highest sensitivity to unit cost differentials.
Supply Chain Analysis
Single-source vulnerability sits with precision pin-tumbler solenoid suppliers concentrated in Germany and Japan, creating qualification bottlenecks for Tier-1 module integrators. Brushless motor actuator production draws from neodymium processing capacity in China's Jiangxi and Inner Mongolia, with final assembly gravitating toward Germany, Japan, and China's eastern manufacturing corridor. Commodity price volatility in rare earth spot markets constitutes the dominant supply chain risk, compounded by tariff exposure on magnet exports. Distribution runs through OEM captive procurement channels and Tier-1 supplier direct contracts, with aftermarket replacement modules constrained by proprietary electronic control unit calibration lockouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as multi-jurisdiction homologation parallelism strains certification budgets and forces sub-scale competitors toward exit or acquisition.
For Market Incumbents: Lock in long-term OEM contracts through captive mechatronics production across European and North American plants, while accelerating ASIL-D certification investment to create premium positioning against uncertified competitors. Backward integration into rare earth magnet sourcing mitigates neodymium price volatility threatening brushless motor actuator margins. For New Entrants and Emerging Players: Over-the-air lock control interfaces with cybersecurity certification offer a technology-first wedge into fleet operator procurement specifications from centralized maintenance hubs in Texas and Florida. India's PLI scheme for auto components presents the most penetrable geography, with Tamil Nadu and Gujarat manufacturing zones offering production-linked incentives for steering lock module assembly targeting two-wheeler OEMs. For Investors and Strategic Acquirers: Re-rating potential sits with specialized lock actuator manufacturers possessing precision metalworking heritage given MLIT type designation enforcement pulling demand toward electronic steering immobilizers. Long-term viability favors suppliers with demonstrated multi-jurisdiction homologation speed and domain controller integration capabilities. Watch for cybersecurity-certified wireless-enabled locks reaching series production as the inflection signal separating premium-positioned platforms from commodity alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Functional Safety Certification | Premium positioning against uncertified competitors in German and Japanese OEM procurement. |
| Backward Integration into Rare Earth Magnet Sourcing | Margin protection against neodymium spot market volatility from Jiangxi and Inner Mongolia. |
| Over-the-Air Lock Control Interface Development | Recurring software revenue streams alongside hardware sales for fleet management integration. |
| Multi-Jurisdiction Homologation Parallelism | Qualification speed advantage compressing validation timelines for NHTSA, ECE R116, and GB standards. |
| Domain Controller Integration Partnership | Lock function migration into centralized body electronics modules expands addressable content per vehicle. |
Methodological Framework
Document review covered NHTSA FMVSS 114 regulatory filings, ECE Regulation 116 type-approval databases, and SAMR-administered GB standards documentation, complemented by interviews with Tier-1 supplier procurement managers, OEM platform engineers, and fleet operator maintenance directors. Secondary validation drew from vehicle production databases, customs and trade flow records for rare earth magnet shipments, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up volume modeling triangulated against top-down market sizing across passive system, active system, and wireless-enabled technology segments.
Unit shipment and value projections across the modeling period reflect analytical frameworks segmenting by product type, end user procurement authority, actuator technology, and vehicle application category. CAGRs were derived from regression analysis of historical penetration rates and OEM platform launch schedules, with neodymium price indices and MLIT enforcement timelines serving as key forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to electromagnetic compatibility testing protocols and cybersecurity annex revisions for connected-vehicle interfaces. Forecasts reflect assumptions regarding rare earth supply chain stability and OEM consolidation timelines for body electronics architectures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market