
 Wireline Trucks Market | 2026-2036
Wireline Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Wireline Trucks Market Analytics
API RP 19B certification is rotating as the primary gating standard for wireline truck operators seeking access to major basins. Schlumberger Limited leverages its integrated service model to sustain equipment utilization across multiple geographies. Baker Hughes anchors its position through specialized pressure control systems that differentiate its fleet specifications. Halliburton Company dominates North American deployment with manufacturing scale that controls regional availability of heavy-duty units.
Wireline trucks are self-propelled or trailer-mounted vehicles equipped with spooled cable, winch systems, and surface instrumentation for downhole logging, perforating, and intervention operations in oil and gas wells. These units typically carry up to 25,000 feet of armored cable rated for pressures exceeding 15,000 psi and temperatures above 350°F, enabling real-time data acquisition from reservoir depths. Heavy duty vehicle types command the largest installed base due to payload requirements for offshore and extended-reach applications, while electronic monitoring technology represents the fastest-growing segment as operators replace analog gauge systems with digital pressure-temperature logging suites. Hydraulic systems remain the mature backbone of winch and mast control, though margin pools are shifting toward autonomous operations where remote rig-up capabilities reduce crew exposure in high-pressure environments.
EPA methane regulations and API standards govern emissions compliance and equipment certification for wireline trucks operating in US territories, while Transport Canada and provincial regulators enforce vehicle weight and road-use specifications across Alberta and Saskatchewan. The EU F-Gas Regulation and REACH framework constrain hydraulic fluid formulations and pneumatic system designs for European deployments. Buyers must weigh technology refresh cycles against evolving downhole complexity as extended laterals and higher-pressure reservoirs test legacy fleet capabilities.
Market Dynamics
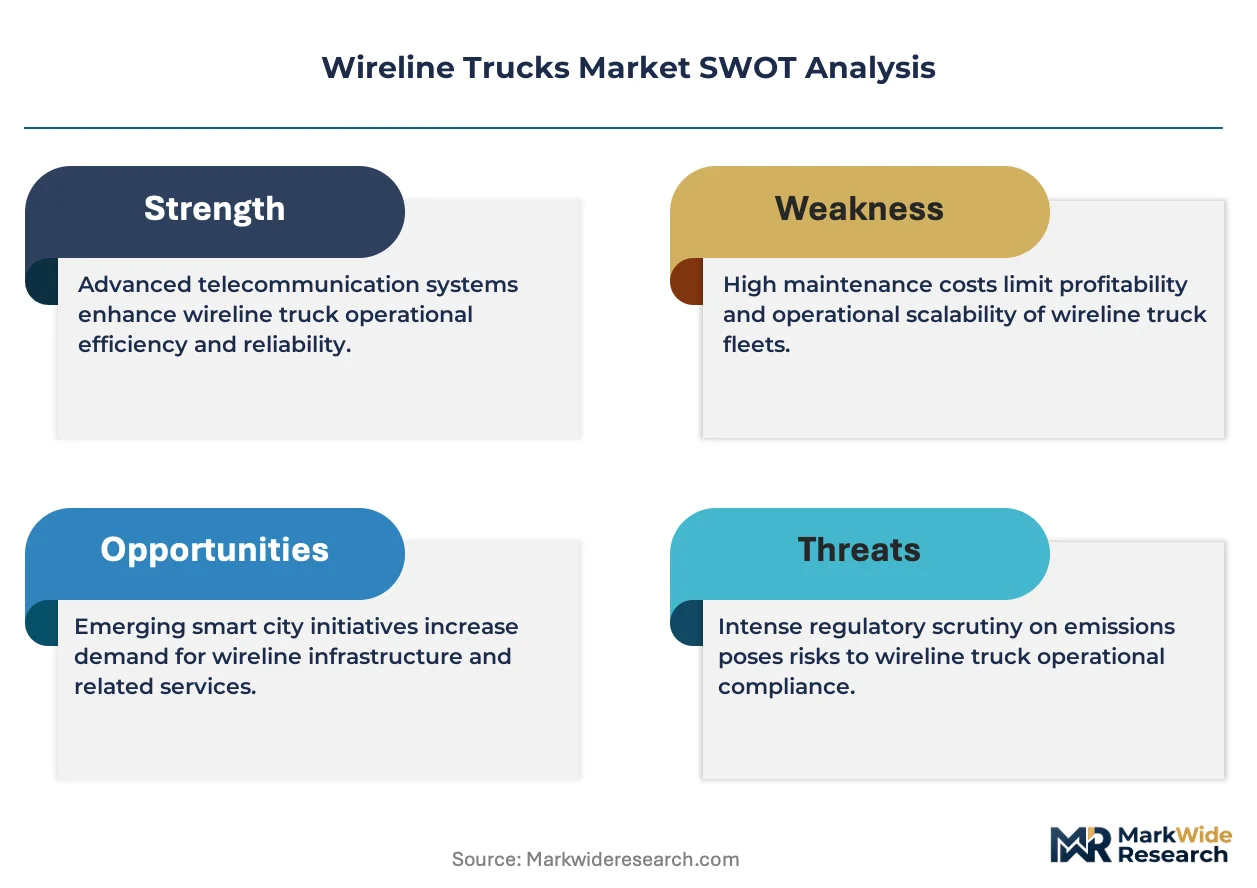
EPA methane emission rules are compressing logging cycles and forcing wireline truck operators toward real-time electronic monitoring systems that can document compliance during every perforating run.
Growth Catalysts
- EPA methane regulations:Tightened logging requirements in US shale basins mandate continuous downhole monitoring, expanding fleet utilization for compliant units.
- Horizontal well completions:Extended-reach laterals in Texas and Alberta require heavier cable payloads and specialized pressure control configurations.
- Hydraulic system upgrades:Real-time telemetry integration is accelerating replacement cycles among North American shale producers seeking operational visibility.
Market Restraints
- Specialized steel supply:Armored cable manufacturing concentrates among a limited set of European and Japanese metallurgical suppliers, creating input cost volatility.
- API RP 19B certification timelines:Pressure control system validation delays fleet deployment schedules by six to eighteen months for new market entrants.
- Skilled operator scarcity:Certified wireline engineers with high-pressure well control credentials remain concentrated in Texas and Alberta, limiting geographic expansion.
Strategic Opportunities
- Autonomous rig-up systems:Remote deployment capabilities reduce crew exposure in high-pressure environments, opening Arctic and deepwater applications.
- EU F-Gas Regulation adaptation:Hydraulic fluid reformulation requirements create first-mover advantage for fleets with biodegradable synthetic systems.
- Extended-reach offshore:Pre-salt and ultra-deepwater developments in Brazil and West Africa demand heavy-duty units with 30,000-foot cable capacity.
Industry Challenges
- Legacy analog gauge integration:Digital logging suites require retrofitting cable heads and surface instrumentation on existing fleets without full replacement.
- Cross-border equipment certification:Transport Canada weight specifications and provincial road-use permits fragment fleet mobility between Alberta and Saskatchewan.
- Real-time data cybersecurity:Downhole telemetry networks face escalating protection requirements under emerging critical infrastructure frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireline Trucks Market |
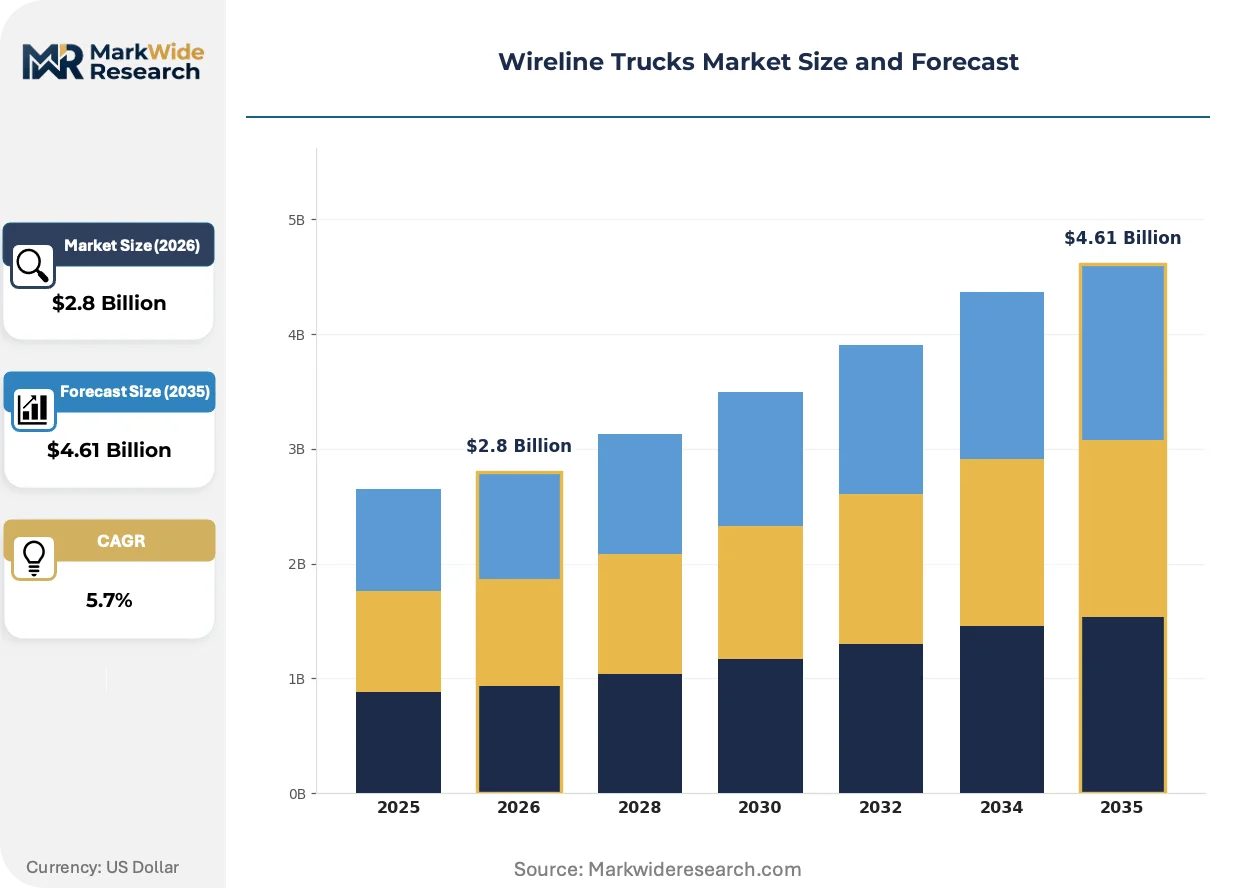
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Medium Duty, Heavy Duty, Specialized Units Application: Oil Extraction, Gas Production, Mining Operations, Maintenance Services End User: Energy Companies, Mining Firms, Contractors, Utility Providers Technology: Hydraulic Systems, Pneumatic Controls, Electronic Monitoring, Autonomous Operations |
| Companies Covered | Schlumberger Limited, Baker Hughes, Halliburton Company, Weatherford International plc, National Oilwell Varco, Synergy Industries, BenchMark Wireline, Turnkey Industries, Lee Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireline Trucks Market Evolving Landscape
Digital pressure-temperature logging suites are displacing analog systems across North American shale operations, while regulatory pressure on methane documentation accelerates sensor density requirements. Equipment manufacturers are embedding predictive maintenance algorithms directly into winch control systems.
Electronic monitoring technology is decomposing the traditional separation between surface instrumentation and downhole acquisition. Shale producers in the Permian Basin are adopting integrated digital suites that stream pressure, temperature, and gamma ray data in real time. This convergence is decomposing legacy procurement patterns that treated cable, winch, and logging tools as discrete purchasing decisions.
EPA methane rules are mandating continuous emission monitoring during completion operations, requiring wireline trucks to carry certified optical gas imaging and flow measurement systems. The regulatory burden falls heaviest on smaller operators lacking integrated service capabilities. Fleets are responding by consolidating logging, perforating, and intervention services under single certification umbrellas to streamline compliance documentation.
Buyer concentration among supermajors and large independents is compressing equipment specification cycles and demanding outcome-based service structures. Traditional day-rate contracting is giving way to per-stage pricing tied to documented production uplift. This shift is most visible in Texas, where integrated producers now specify minimum sensor density and real-time data delivery as standard contract terms rather than optional upgrades.
Wireline Trucks Market Segmentation
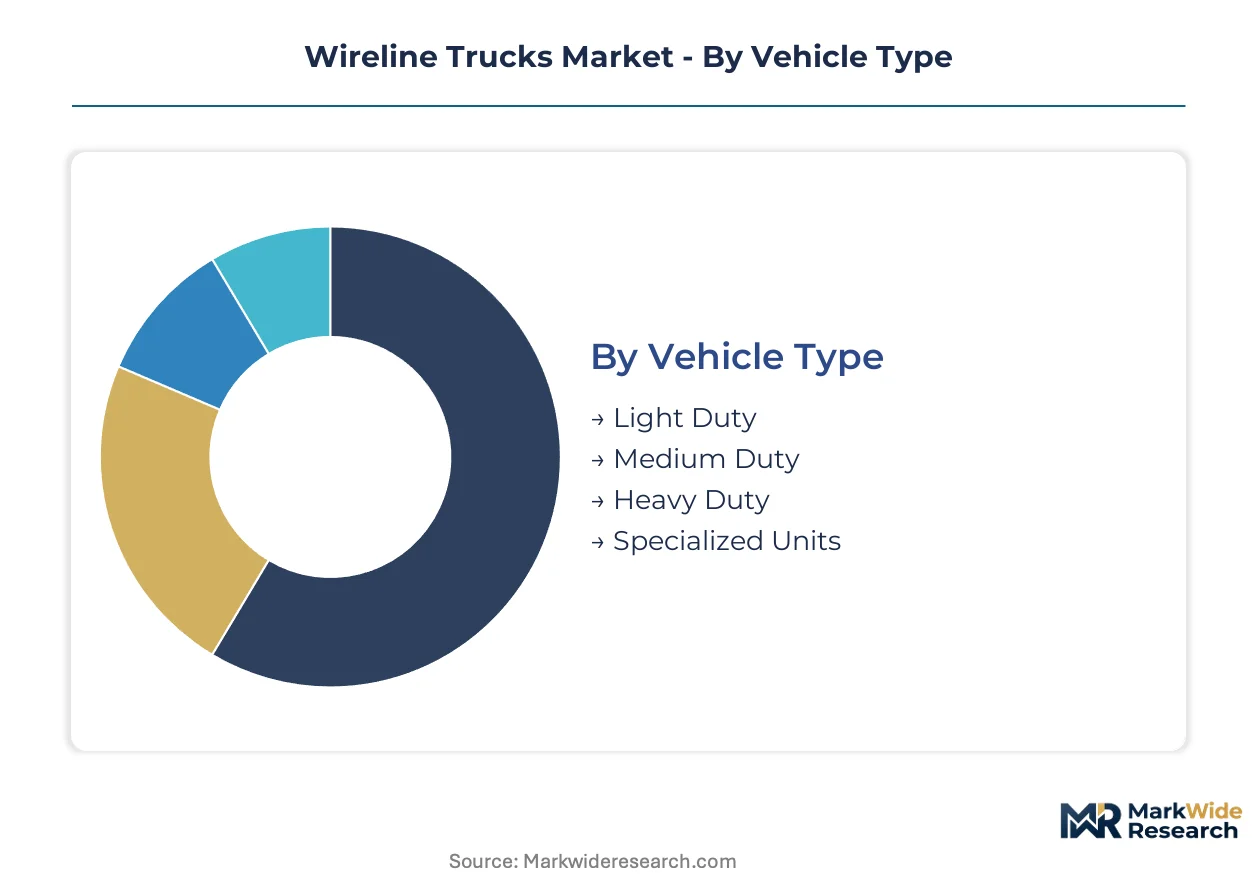
Wireline truck specifications diverge sharply across operating environments, from desert shale plays to offshore platforms. Fleet procurement patterns cluster around payload requirements and regulatory compliance tiers rather than brand preference.
Vehicle Type:
Heavy duty configurations anchor North American shale basins where extended-reach laterals demand maximum cable capacity. Light duty variants serve export markets with restricted road weight limits and compact wellsite footprints.
- Light Duty:Compact chassis configurations carry 10,000 to 15,000 feet of cable for conventional vertical wells. Demand concentrates in Appalachian coalbed methane operations and European onshore workovers where road weight restrictions limit heavier units.
- Heavy Duty:Purpose-built platforms accommodate 25,000 to 30,000 feet of armored cable rated for 15,000 psi and 350°F. Texas Permian operators and Alberta oil sands contractors specify these for extended-reach horizontal completions and offshore supply vessel deployment.
- Medium Duty:Intermediate payload capacity serves mid-continent conventional reservoirs and workover markets.
- Specialized Units:Arctic-rated and deepwater configurations address extreme environment specifications.
Heavy duty commands the established base. The steepest expansion runs through specialized units for pre-salt and ultra-deepwater applications.
Application:
Horizontal completion intensity determines fleet utilization rates and equipment replacement cycles. Maintenance services generate recurring revenue streams with lower capital intensity than greenfield extraction.
- Oil Extraction:Unconventional shale operations require continuous logging and perforating services through extended laterals. West Texas and southeastern New Mexico operators drive specification requirements for real-time data transmission and pressure control redundancy.
- Gas Production:Tight gas and coalbed methane applications emphasize lower-pressure ratings and reduced cable diameters. Appalachian Basin activity and Alberta Montney development anchor regional demand clusters.
- Mining Operations:Geophysical logging and borehole instrumentation for mineral exploration and geotechnical assessment.
- Maintenance Services:Workover, plug retrieval, and remedial cementing operations on producing wells.
Oil extraction absorbs the majority of deployed capacity. Gas production is climbing fastest as LNG export infrastructure expands Gulf Coast drilling programs.
End User:
Procurement authority concentrates among integrated operators with captive service arms. Independent contractors face equipment financing constraints and certification timeline pressures.
- Energy Companies:Supermajors and large independents specify API RP 19B certification, real-time data delivery, and outcome-based contracting. ExxonMobil, Chevron, and ConocoPhillips drive standardization through master service agreements.
- Contractors:Third-party service providers compete on fleet availability and regional mobilization speed. Halliburton, Schlumberger, and Baker Hughes dominate through vertical integration of manufacturing and field operations.
- Mining Firms:Mineral exploration companies and geotechnical contractors with specialized logging requirements.
- Utility Providers:Geothermal and carbon storage monitoring applications.
Energy companies control specification standards. Contractors are expanding most quickly through integrated service bundling.
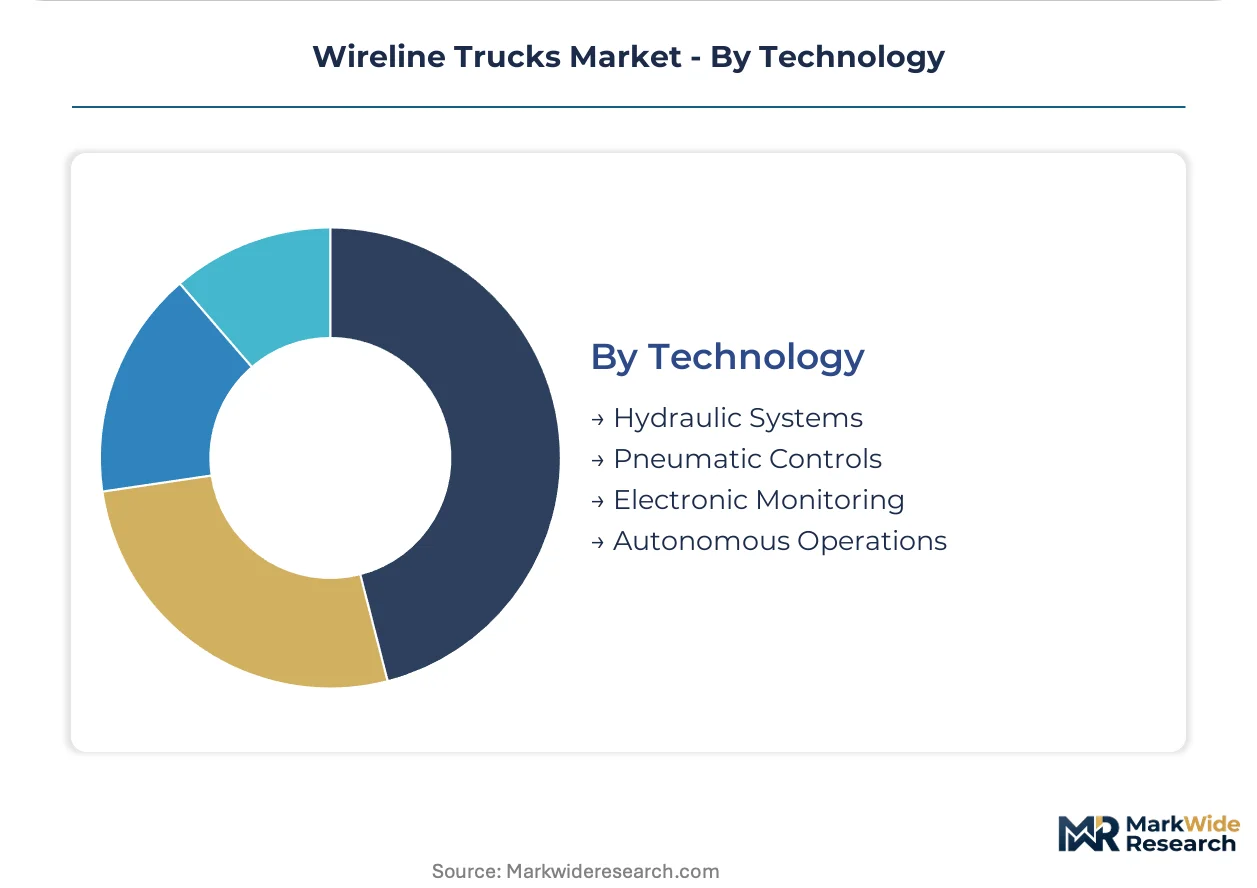
Technology:
Digital telemetry integration is decomposing legacy procurement patterns that treated cable, winch, and logging tools as discrete purchasing decisions. Regulatory methane documentation accelerates sensor density requirements.
- Electronic Monitoring:Digital pressure-temperature logging suites with real-time surface transmission displace analog gauge systems. Permian Basin operators now specify minimum sensor density and continuous data streaming as standard contract terms.
- Hydraulic Systems:Mature winch and mast control architectures remain the backbone of fleet operations. EPA and Transport Canada specifications govern fluid formulations and pressure ratings.
- Pneumatic Controls:Compressed air systems for surface instrumentation and valve actuation in hazardous environments.
- Autonomous Operations:Remote rig-up capabilities reduce crew exposure in high-pressure and Arctic environments.
Hydraulic systems retain the installed majority. Electronic monitoring is gaining share fastest as methane compliance mandates drive replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA methane regulations and API certification standards are redirecting capital toward compliant fleet deployments in established shale basins. Operators in jurisdictions with mature regulatory frameworks command pricing premiums for certified units. Geographic expansion concentrates where horizontal completion intensity intersects with enforceable environmental standards.
United States
Permian Basin operators in West Texas and southeastern New Mexico are expanding wireline truck fleets to meet tightened EPA logging requirements for methane documentation. The EPA mandates continuous downhole monitoring during perforating runs, accelerating replacement cycles for analog-equipped units. Midland-Odessa anchors the densest fleet concentration, with operators specifying API RP 19B certification as a baseline contract requirement.
Canada
Alberta oil sands contractors and Saskatchewan tight gas producers are driving demand for heavy-duty configurations rated for extended-reach laterals. Transport Canada and provincial regulators enforce vehicle weight specifications and road-use permits that fragment fleet mobility between provinces. Calgary and Edmonton host the primary service company headquarters coordinating Montney and Duvernay development programs.
Brazil
Pre-salt and ultra-deepwater developments offshore require specialized units with 30,000-foot cable capacity and pressure ratings exceeding 15,000 psi. ANVISA and environmental licensing frameworks govern offshore equipment certification timelines. Rio de Janeiro serves as the operational hub where international service contractors coordinate fleet deployment for Santos Basin campaigns.
Saudi Arabia
Aramco's unconventional gas program in the Jafurah Basin is stimulating demand for real-time electronic monitoring systems compatible with high-temperature reservoirs. The country's national oil company specifies API standards for pressure control systems and mandates Saudi Aramco certification for third-party service providers. Dhahran and the Eastern Province concentrate manufacturing partnerships and technical service operations.
Norway
North Sea electrification and subsea tieback projects are shifting specifications toward autonomous rig-up capabilities that reduce crew exposure in harsh environments. The country's petroleum regulator enforces strict well integrity standards that exceed baseline API requirements. Stavanger and Bergen host engineering centers developing Arctic-rated configurations for Barents Sea exploration.
Wireline Trucks Market Competitive Landscape
Player mix skews toward integrated oilfield service conglomerates with captive manufacturing arms and captive fleet deployment capabilities. The competitive structure concentrates around three strategic archetypes: vertically integrated supermajors controlling specification standards through master service agreements, specialized pressure control system fabricators differentiating on technical certification depth, and regional contractors competing on mobilization speed and local regulatory familiarity. Dominant competitive moves include backward integration into armored cable manufacturing to secure input supply, and technology licensing partnerships to accelerate digital telemetry adoption without full R&D burden.
Within the integrated service tier, Schlumberger Limited, Baker Hughes, and Halliburton Company exemplify the capital-scale archetype that dominates North American deployment. Schlumberger's geographic diversification across multiple basins sustains equipment utilization rates that pure regional players cannot match. Baker Hughes anchors its positioning through specialized pressure control system expertise that shapes fleet specification conversations with supermajor buyers. Halliburton's manufacturing scale controls regional availability of heavy-duty units for extended-reach applications, compressing delivery timelines for Permian and Alberta operators. These three entities collectively represent the certification and capacity threshold that new entrants must clear to access premium contract tiers.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes |
| Halliburton Company |
| Weatherford International plc |
| National Oilwell Varco |
| Synergy Industries |
| BenchMark Wireline |
| Turnkey Industries |
| Lee Specialties |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Permian Basin operators and wireline service providers lock in armored cable supply commitments while anchoring day-rate visibility across multi-year drilling programs. These contracts bundle API RP 19B certification, real-time monitoring system upgrades, and priority fleet allocation into single pricing frameworks that insulate buyers from spot-market volatility in specialized steel inputs.
Pricing Analysis
Certification level (API RP 19B versus baseline pressure control) creates the primary spread between premium and standard fleet tiers. Three-tier pricing structure across premium, standard, and economy levels reflects sensor density specifications, hydraulic system age, and bundled compliance documentation. Cost compression in standard-tier day rates is intensifying because smaller operators consolidate logging and perforating services to meet EPA methane documentation mandates. Independent contractors exhibit highest price sensitivity, while supermajors with captive service arms prioritize outcome-based contracting over rate minimization.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes from Japanese and European metallurgical suppliers inflate lead times for armored cable deliveries to Texas and Alberta manufacturing hubs. Manufacturing concentrates in Germany, Japan, and the United States for specialized steel alloys rated to 15,000 psi. Raw material dependencies include nickel-chromium alloy wire, synthetic hydraulic fluids, and high-temperature sensor housings. Single-source vulnerability around European cable suppliers feeds pricing volatility when EPA certification deadlines compress procurement windows. Distribution runs through Halliburton, Schlumberger, and Baker Hughes captive fleet networks that control regional availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireline truck demand follows upstream capital expenditure cycles, with EPA methane enforcement and horizontal completion intensity serving as the current cyclical recovery drivers.
For Market Incumbents: Fortify API RP 19B certification depth and backward integration into armored cable manufacturing to secure input supply against Japanese and European metallurgical bottlenecks. Expand heavy-duty fleet capacity in Texas and Alberta to capture extended-reach lateral demand from Permian and Montney operators. Counter skilled operator scarcity by embedding autonomous rig-up capabilities that reduce crew exposure and certification burden. For New Entrants and Emerging Players: Differentiate on biodegradable hydraulic fluid systems that preempt EU F-Gas Regulation compliance requirements for European deployment opportunities. Target Arctic-rated and deepwater specialized units where Schlumberger and Baker Hughes have thinner fleet presence. Pursue technology licensing partnerships with digital telemetry providers to accelerate electronic monitoring adoption without full R&D burden. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap contractors with established Transport Canada permits and Alberta road-use certifications that fragment fleet mobility barriers. Long-term viability hinges on exposure to pre-salt and ultra-deepwater developments in Brazil and West Africa where cable capacity requirements exceed 30,000 feet. Monitor ANVISA environmental licensing timeline acceleration as the inflection signal for offshore fleet utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| API RP 19B Certification Investment | Pressure control system validation opens access to supermajor master service agreements in Texas and Alberta. |
| Backward Integration into Armored Cable | In-house production of specialized steel alloys insulates against European and Japanese supplier concentration. |
| Autonomous Rig-Up Development | Remote deployment capabilities reduce crew exposure in high-pressure Arctic and deepwater environments. |
| Biodegradable Hydraulic Fluid Reformulation | EU F-Gas Regulation adaptation creates first-mover positioning for European fleet deployments. |
| Extended-Reach Cable Capacity Expansion | 30,000-foot cable systems capture pre-salt and ultra-deepwater demand from Brazil and West Africa operators. |
Research Methodology
Cross-validation between regulatory filing analysis and operator procurement documentation anchors the qualitative findings on EPA methane compliance and API certification timelines. Primary interviews with wireline service company fleet managers, Permian Basin drilling superintendents, Alberta oil sands contractors, and Halliburton manufacturing engineers combined with secondary validation from EPA enforcement records, Transport Canada vehicle specifications, ANVISA offshore licensing databases, and SEC 10-K equipment disclosures. Bottom-up fleet deployment counts triangulate against top-down shale completion intensity estimates.
Sensitivity analysis on cable replacement cycles and horizontal well lateral length assumptions tests forecast robustness across the projection horizon. The analytical framework models vehicle type, application, end user, and technology segmentation dimensions alongside regional regulatory cluster variations. CAGRs derive from equipment replacement velocity tied to EPA methane rule phase-in schedules and digital telemetry adoption curves. Forecast inputs include Permian Basin drilling permit trends and Alberta Montney completion stage counts.
Material uncertainties — regulatory enforcement acceleration, specialized steel supply disruptions, and autonomous rig-up technology maturation — sit outside the modeled envelope. Forecasts reflect documented assumptions about EPA rule stability and API standard continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market