
 Automotive Charge Port Actuator Market | 2026-2036
Automotive Charge Port Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Charge Port Actuator Market Insights
IP67 ingress protection is collapsing from premium-grade specification to baseline expectation across EV charge port modules. Robert Bosch GmbH leverages in-house motor and controller production to sustain margin on high-reliability actuator lines. Continental AG anchors European supply through dedicated e-mobility actuator capacity in Germany. Johnson Electric Holdings Limited competes on micro-motor miniaturization for space-constrained charge port doors.
An automotive charge port actuator is an electromechanical device that converts electrical energy into precise linear or rotary motion to open, close, and seal vehicle charge port covers, typically operating at voltages between 12V and 48V with position feedback via Hall-effect sensors. Its primary purpose is to protect high-voltage charging interfaces from environmental contamination while enabling automated, hands-free access for drivers. Electromechanical actuators dominate current OEM specifications due to their silent operation and programmability, while brushless DC motor technology leads on efficiency and thermal durability in sealed housings. Piezoelectric variants remain niche but occupy the highest-precision tier for premium vehicle applications where minimal acoustic signature commands price premiums.
NHTSA in the United States and ECE R100 in Europe mandate electromagnetic compatibility and ingress protection thresholds that directly determine actuator sealing architecture and shielding material selection. China's GB standards and MIIT technical rules impose additional high-voltage safety and localization requirements on charge port subsystems sold into domestic EV platforms. Stakeholders must monitor how regional certification divergence affects platform engineering costs and supplier qualification timelines.
Market Dynamics
Sealed actuator architectures are compressing development cycles as NHTSA and ECE R100 standards force simultaneous compliance with electromagnetic shielding and ingress protection thresholds that previously qualified sequentially.
Growth Catalysts
- ECE R100 electromagnetic compatibility mandates:European OEMs must redesign charge port subsystems to meet radiated emission limits, pulling demand for shielded actuator housings across premium EV platforms.
- IP67 baseline specification:Dust and water intrusion protection is displacing IP54 as the minimum viable rating for charge port modules in vehicles sold across Germany, China, and the United States.
- Hands-free charging protocols:Automated port opening triggered by proximity sensors is becoming standard equipment on luxury EV lines, requiring precision position feedback via Hall-effect arrays.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium price swings in Chinese spot markets squeeze margins on brushless DC motor production, forcing actuator suppliers to absorb input fluctuations or renegotiate annual contracts.
- Single-source controller ASICs:Semiconductor concentration in Taiwanese foundries creates vulnerability for motor driver chips that integrate position sensing and fault protection logic.
- Piezoelectric actuator thermal limitations:Ceramic stack actuators face stroke degradation above 85°C ambient, restricting deployment to cabin-protected charge port locations away from battery thermal management zones.
Strategic Opportunities
- India PLI scheme for EV components:Domestic manufacturing incentives are opening qualification pathways for actuator suppliers willing to localize motor winding and controller assembly operations.
- Vehicle-to-grid bidirectional charging:Heavy-cycling charge port doors on fleet vehicles require actuator duty ratings beyond current passenger-car specifications, creating a performance-tier gap.
- Silicon carbide MOSFET integration:Wide-bandgap power electronics converging with 48V actuator bus architectures enable faster response times and reduced copper mass in sealed housings.
Industry Challenges
- Multi-physics simulation expertise:Coupled thermal-electromagnetic-mechanical modeling for sealed actuator design requires scarce cross-functional engineers conversant in motor magnetics and CFD for ingress-protected enclosures.
- GB standard localization timelines:China's MIIT certification process for charge port subsystems imposes 18-24 month qualification windows that delay platform launches for foreign suppliers lacking in-country testing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Charge Port Actuator Market |
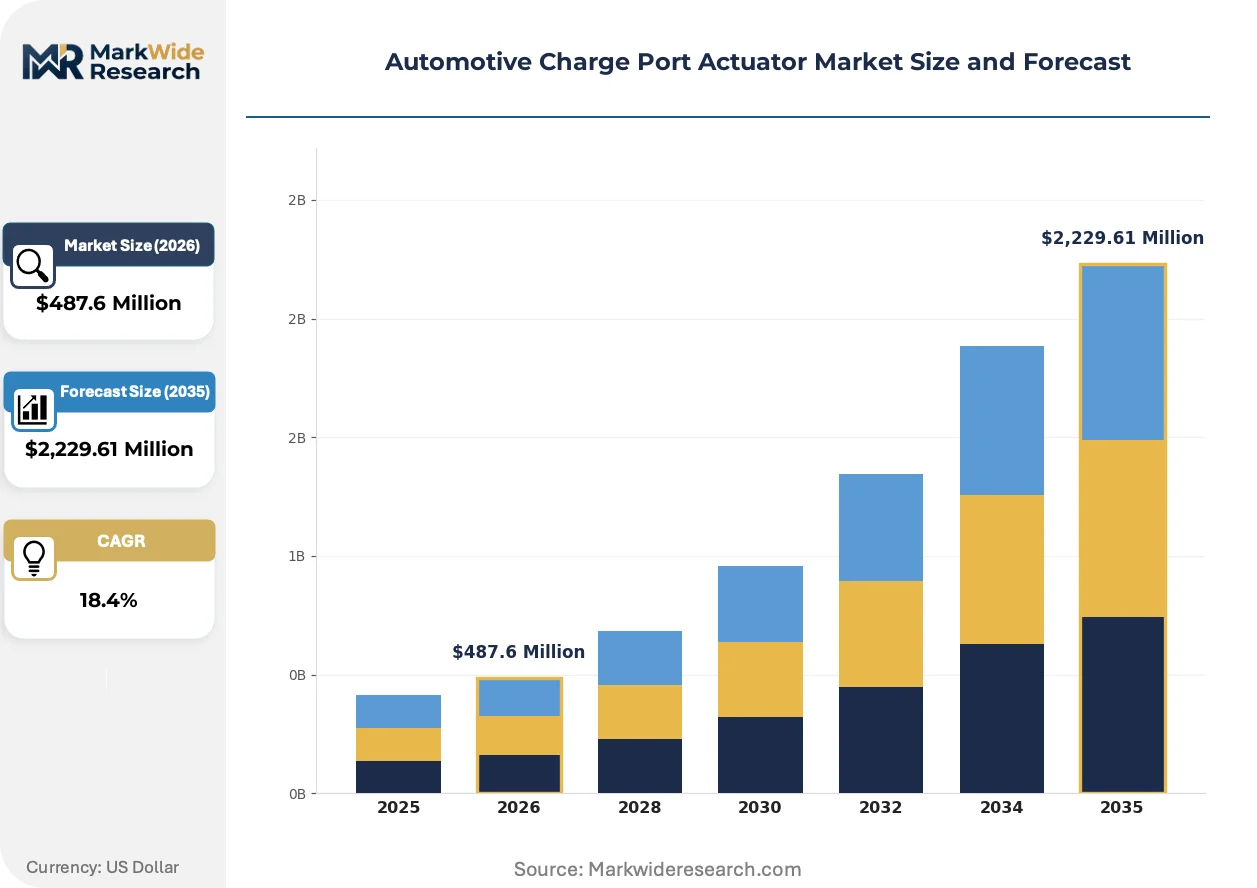
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Pneumatic, Hydraulic, Magnetic, Thermal Technology: Brushless DC Motor, Stepper Motor, Linear Actuator, Servo Motor, Piezoelectric Application: Electric Vehicle, Hybrid Electric Vehicle, Fuel Cell Vehicle, Plug-in Hybrid, Light Commercial Vehicle End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Retrofitters |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Johnson Electric Holdings Limited, Magna International, Valeo, Brose Fahrzeugteile, Nidec Corporation, Marquardt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Charge Port Actuator Market Trends and Innovations
Actuator architectures are bifurcating between commodity 12V electromechanical units for mass-market EVs and precision 48V systems with integrated diagnostics for premium segments, with material selection and control intelligence as the primary differentiators.
Brushless DC motor technology with integrated Hall-effect commutation is displacing brushed DC and stepper motor alternatives in charge port applications. Tier 1 suppliers are standardizing on this topology for its silent operation and 10,000+ cycle durability under sealed conditions. The shift is compressing qualification timelines for legacy motor suppliers unable to demonstrate equivalent mean-time-between-failure data.
NHTSA's updated electromagnetic compatibility test procedures for electric vehicle charging systems are forcing redesigns of actuator cable routing and shielding termination. The regulation's industrial consequence is mandatory ferrite core integration on motor leads and braided shield continuity testing at the connector level. Premium EV platforms in the United States are responding by specifying fully shielded actuator assemblies with 360-degree circumferential grounding.
Fleet operators and charging network providers are consolidating procurement around actuator modules with embedded condition monitoring and predictive failure algorithms. Direct sourcing agreements with component manufacturers are displacing traditional tiered supply arrangements where vehicle OEMs mediated all subsystem transactions. This pattern is most visible in Germany, where energy utilities operating charging infrastructure are qualifying actuators independently for reliability-critical fast-charging depots.
Automotive Charge Port Actuator Market Segmentation
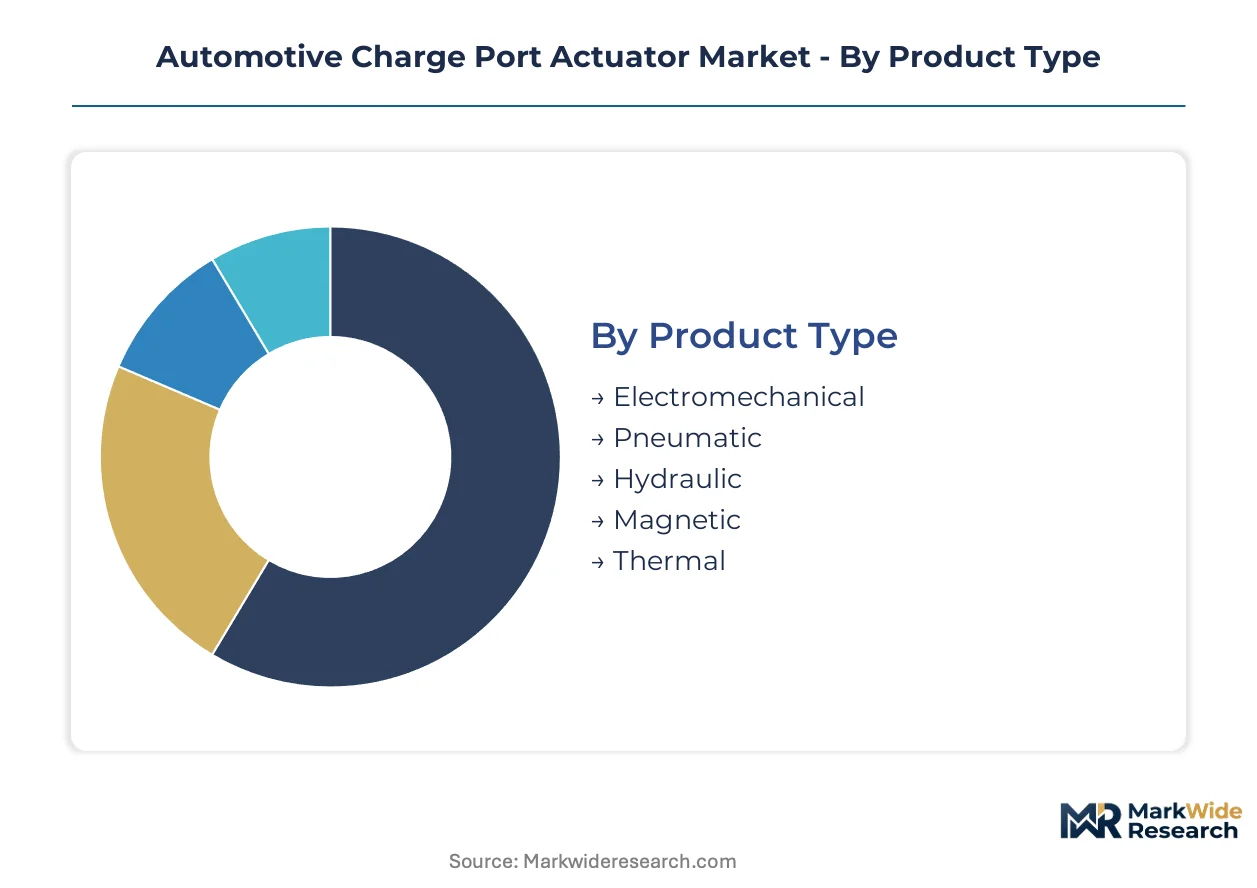
Actuator procurement patterns diverge sharply across product architectures and voltage classes. Technology selection determines sealing complexity, electromagnetic compliance burden, and qualification timelines for sealed charge port modules.
Product Type:
Electromechanical architectures command premium margin pools due to programmability and silent operation requirements on luxury EV platforms.
- Electromechanical:Converts electrical energy to linear or rotary motion via motor-driven lead screws or rack-and-pinion mechanisms. Hall-effect position feedback enables precise port sequencing for hands-free charging protocols on German and Chinese premium EV lines. NHTSA electromagnetic compatibility mandates favor shielded electromechanical designs with integrated ferrite cores.
- Pneumatic:Compressed air drives diaphragm or piston actuation for high-force, rapid-cycle applications. Demand concentrates in commercial vehicle depots where fleet operators prioritize cycle speed over acoustic refinement, though air supply infrastructure limits passenger car adoption.
- Hydraulic:Pressurized fluid transmits force through sealed cylinders for extreme load conditions. Heavy-duty fuel cell buses in South Korea deploy hydraulic actuators for charge port doors exceeding 15kg mass.
- Magnetic:Electromagnetic solenoids provide binary open/close functionality with minimal moving parts. Simplified control logic suits cost-optimized EV platforms in India where PLI scheme localization targets drive component simplification.
- Thermal:Shape-memory alloy wires contract when heated to generate motion. Niche deployment in cabin-protected charge port locations where minimal electromagnetic signature outweighs slow response times.
Electromechanical holds installed capacity. Magnetic is rotating up the share rankings.
Technology:
Brushless DC motor topology dominates engineering hours as OEMs specify 10,000+ cycle durability under IP67 sealing.
- Brushless DC Motor:Electronic commutation eliminates brush wear and enables precise speed control through Hall-effect sensor arrays. ECE R100 electromagnetic compatibility thresholds favor this topology for European premium EV platforms where radiated emission limits are tightening.
- Stepper Motor:Discrete angular positioning suits applications requiring indexed port door sequencing without external feedback sensors. Cost-sensitive hybrid electric vehicles in Japan specify stepper drives for simplified controller architectures.
- Linear Actuator:Direct thrust generation eliminates rotary-to-linear conversion losses. Space-constrained charge port modules on compact urban EVs leverage integrated linear designs to minimize envelope dimensions.
- Servo Motor:Closed-loop torque and position control enables adaptive force limiting against obstruction. Luxury EV lines specify servo drives for premium tactile feedback during automated port operation.
- Piezoelectric:Ceramic stack expansion generates nanometer-precision displacement with minimal acoustic signature. Ultra-premium vehicle applications accept thermal limitations below 85°C ambient for silent operation.
Brushless DC Motor anchors current production volumes. Piezoelectric is climbing the fastest as acoustic specifications tighten.
Application:
Battery electric platforms absorb the majority of sealed actuator development investment as charging infrastructure scales.
- Electric Vehicle:Pure battery electric architectures require automated charge port access for DC fast-charging sessions. United States and Chinese OEM specifications prioritize IP67 sealing and Hall-effect position feedback for hands-free charging protocols.
- Hybrid Electric Vehicle:Smaller battery capacities reduce charging frequency but still demand reliable port actuation. Japanese and European mild-hybrid platforms specify cost-optimized electromechanical units with reduced cycle ratings.
- Fuel Cell Vehicle:Hydrogen refueling ports require specialized sealing against high-pressure gas exposure. South Korean commercial bus fleets drive demand for heavy-duty actuator architectures.
- Plug-in Hybrid:Dual powertrain complexity increases charge port utilization versus conventional hybrids. German premium OEMs specify premium actuator tiers with integrated diagnostics for PHEV lines.
- Light Commercial Vehicle:Fleet duty cycles exceed passenger car specifications for cycle count and environmental exposure. Last-mile delivery van operators in Germany prioritize predictive maintenance capabilities.
Electric Vehicle holds installed capacity. Light Commercial Vehicle is gaining share fastest as fleet electrification accelerates.
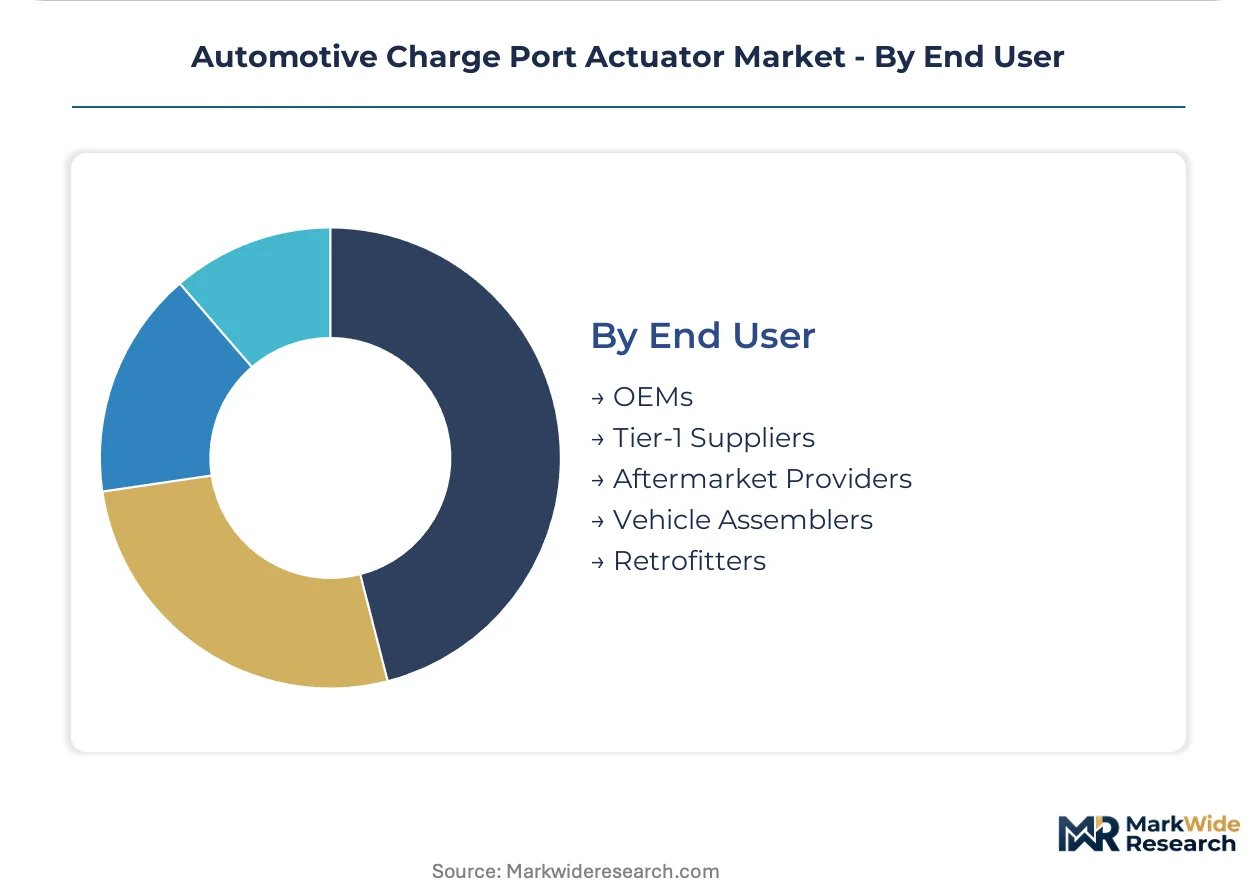
End User:
OEM direct procurement concentrates margin capture as platform integration requirements tighten.
- OEMs:Vehicle manufacturers specify actuator performance envelopes and qualification protocols. German and Chinese OEMs increasingly mandate in-house motor magnetics and controller firmware for charge port subsystems.
- Tier-1 Suppliers:System integrators aggregate actuator modules with charging inlets and cable management. Continental AG and Robert Bosch GmbH anchor European supply through dedicated e-mobility actuator capacity.
- Aftermarket Providers:Replacement actuators serve collision repair and warranty channels. United States independent service networks stock IP67-rated units for Tesla and legacy EV platforms.
- Vehicle Assemblers:Contract manufacturers execute final integration per OEM build specifications. Magna Steyr and Valmet Automotive incorporate actuator subassemblies into complete vehicle programs.
- Retrofitters:Specialty converters add charging ports to internal combustion platforms. Niche demand in commercial vehicle upfitters serving municipal electrification mandates.
OEMs hold installed capacity. Aftermarket Providers are rotating up the share rankings as EV parc ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in sealed automotive actuators tilt toward manufacturing surplus in Germany and China, while the United States absorbs premium-tier imports to supply domestic EV assembly lines. Trade balances reflect divergent regulatory certification burdens and localized content mandates.
Germany
Premium EV platforms from BMW and Mercedes-Benz pull high-reliability actuator volumes. ECE R100 electromagnetic compatibility mandates force shielded housing designs that qualify for pan-European distribution. Stuttgart and Munich anchor Continental AG and Robert Bosch GmbH production clusters serving OEM direct procurement.
China
BYD and NIO production scaling drives domestic actuator demand exceeding export capacity. MIIT certification under GB standards imposes 18-24 month qualification windows that favor local suppliers with in-country testing partnerships. Shanghai and Shenzhen concentrate motor winding and controller assembly operations under PLI-equivalent provincial schemes.
United States
Tesla and legacy Detroit OEMs specify IP67-rated actuators for hands-free charging protocols on luxury EV lines. NHTSA electromagnetic compatibility test procedures mandate ferrite core integration and braided shield continuity testing. Michigan and California assembly plants source through Tier-1 integrators with domestic qualification laboratories.
Japan
Hybrid electric vehicle production sustains demand for cost-optimized electromechanical units with reduced cycle ratings. METI technical standards emphasize motor efficiency benchmarks that favor brushless DC topologies. Nagoya and Osaka industrial corridors host precision micro-motor specialists serving Toyota and Honda supply chains.
South Korea
Hyundai and Kia EV platforms require automated charge port access for DC fast-charging sessions. MFDS-aligned technical regulations cross-reference ECE R100 electromagnetic thresholds for export compatibility. Busan-Ulsan manufacturing zones concentrate heavy-duty actuator capacity for commercial fuel cell bus fleets.
Automotive Charge Port Actuator Market Competitive Landscape
Concentration sits with diversified automotive Tier-1 suppliers that leverage captive motor production and controller firmware development. The vendor base clusters around three strategic archetypes: integrated electromechanical specialists with in-house magnetics, diversified automotive component conglomerates with e-mobility divisions, and precision micro-motor manufacturers competing on miniaturization. Dominant competitive moves include backward integration into rare-earth magnet supply chains and geographic expansion through India PLI scheme localization partnerships.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify integrated production architectures that span motor winding, controller assembly, and sealed housing fabrication. Johnson Electric Holdings Limited occupies a position among precision micro-motor specialists competing for space-constrained charge port door applications. These three anchors represent divergent strategic postures: captive vertical control versus component specialization versus miniaturization leadership.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Johnson Electric Holdings Limited |
| Magna International |
| Valeo |
| Brose Fahrzeugteile |
| Nidec Corporation |
| Marquardt |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between German Tier-1 suppliers and premium OEMs lock in rare-earth magnet supply and price visibility for brushless DC motor production, insulating actuator margins from Chinese spot market volatility while binding buyers to volume commitments.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures across the actuator market. Three-tier pricing structure across premium, standard, and economy levels separates IP67-certified Hall-effect feedback units from basic magnetic solenoids and unsealed variants. Cost compression in standard-tier electromechanical units is intensifying because neodymium price fluctuations squeeze motor winding margins. Fleet procurement teams at commercial vehicle operators exhibit highest price sensitivity, while luxury German OEM platform engineers prioritize certification grade over unit cost.
Supply Chain Analysis
China and Germany anchor sealed actuator manufacturing, with Taiwan feeding controller ASIC fabrication. Motor magnetics draw from Chinese rare-earth processing and German precision winding operations. Single-source vulnerability concentrates in Taiwanese foundries producing integrated motor driver chips. Distribution runs through Tier-1 system integrators qualifying modules for OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as fleet electrification and bidirectional charging protocols create performance-tier gaps that specialized suppliers can occupy alongside incumbent conglomerates.
For Market Incumbents: Shield margin pools by deepening backward integration into rare-earth magnet supply chains and expanding dedicated e-mobility actuator capacity in Germany to serve ECE R100 compliance demand. Magnetic solenoid entrants from India threaten standard-tier pricing. Certification investment in MIIT-aligned testing partnerships defends Chinese platform access against 18-24 month qualification delays. For New Entrants and Emerging Players: Lead with heavy-duty actuator architectures for vehicle-to-grid fleet applications where duty ratings exceed passenger-car specifications. Light commercial vehicle electrification in Germany offers the most penetrable segment. Direct sourcing agreements with charging network operators bypass traditional OEM-mediated supply tiers. For Investors and Strategic Acquirers: Capital is best deployed toward precision micro-motor specialists with demonstrated Hall-effect integration expertise and established OEM qualification records. Long-term viability hinges on thermal management capabilities for sealed housings and silicon carbide controller readiness. Watch for inflection when India PLI scheme localization partnerships achieve MIIT certification equivalence.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BMW and Mercedes-Benz convergence on 48V actuator buses reduces supplier qualification burden. |
| Battery Supply Agreement | Cell manufacturer partnerships secure rare-earth magnet allocation for brushless DC motor production. |
| Software-Defined Vehicle Investment | Embedded condition monitoring algorithms enable predictive maintenance for fleet operators. |
| Geographic Manufacturing Footprint | India PLI scheme localization opens qualification pathways for MIIT-certified export capacity. |
| Charging Infrastructure Partnership | Energy utility direct procurement displaces traditional tiered supply arrangements in Germany. |
Research Methodology
Cross-validation between OEM platform engineering interviews and Tier-1 supplier production data anchors the qualitative findings. Primary discussions with actuator procurement managers, motor winding specialists, electromagnetic compliance engineers, and fleet operations directors combined with secondary validation against NHTSA filing databases, ECE R100 technical documentation, MIIT certification registries, and vehicle production databases. Bottom-up unit volume estimates triangulate with top-down OEM platform content analysis.
Sensitivity analysis around neodymium price trajectories and semiconductor lead times informs the analytical framework across the projection horizon. Segmentation dimensions include product architecture, voltage class, motor topology, vehicle propulsion type, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to OEM platform rollout schedules and charging infrastructure deployment curves. Content-per-vehicle assumptions and cycle-life specifications feed industry-specific forecast inputs.
Forecasts assume regulatory continuity in NHTSA, ECE R100, and MIIT regimes; material policy shifts would require re-modeling. Rare-earth export restrictions, semiconductor trade controls, or accelerated electromagnetic compatibility threshold revisions represent specific risk factors. Recalibration cycles align with material shifts in OEM platform electrification timelines and charging protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market