
 Automated Valet Parking (AVP) Market | 2026-2036
Automated Valet Parking (AVP) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Valet Parking (AVP) Market Insights
Modular sensor fusion packages are expanding buyer choice across the AVP ecosystem. Robert Bosch leverages its integrated LiDAR-camera stacks to dominate manufacturing scale in European deployments. Valeo sustains technology leadership in ultrasonic sensor miniaturization for tight-space maneuvering. Continental anchors geographic presence through deep partnerships with German premium OEMs.
Automated Valet Parking denotes a Level 4 autonomous driving function wherein a vehicle navigates parking structures and executes parking maneuvers without a human occupant, relying on sensor arrays with sub-10-centimeter localization accuracy and real-time occupancy mapping. The primary commercial purpose is to eliminate driver time spent in parking facilities while maximizing space utilization through denser stall configurations. Camera-based systems occupy the fastest-growing technology tier as cost curves fall faster than LiDAR alternatives. Commercial parking applications concentrate current revenue, while airport parking represents an emerging margin pool due to premium pricing tolerance and predictable traffic patterns. Integration services dominate the service-type landscape, though software development captures expanding share as operators seek white-label platform control.
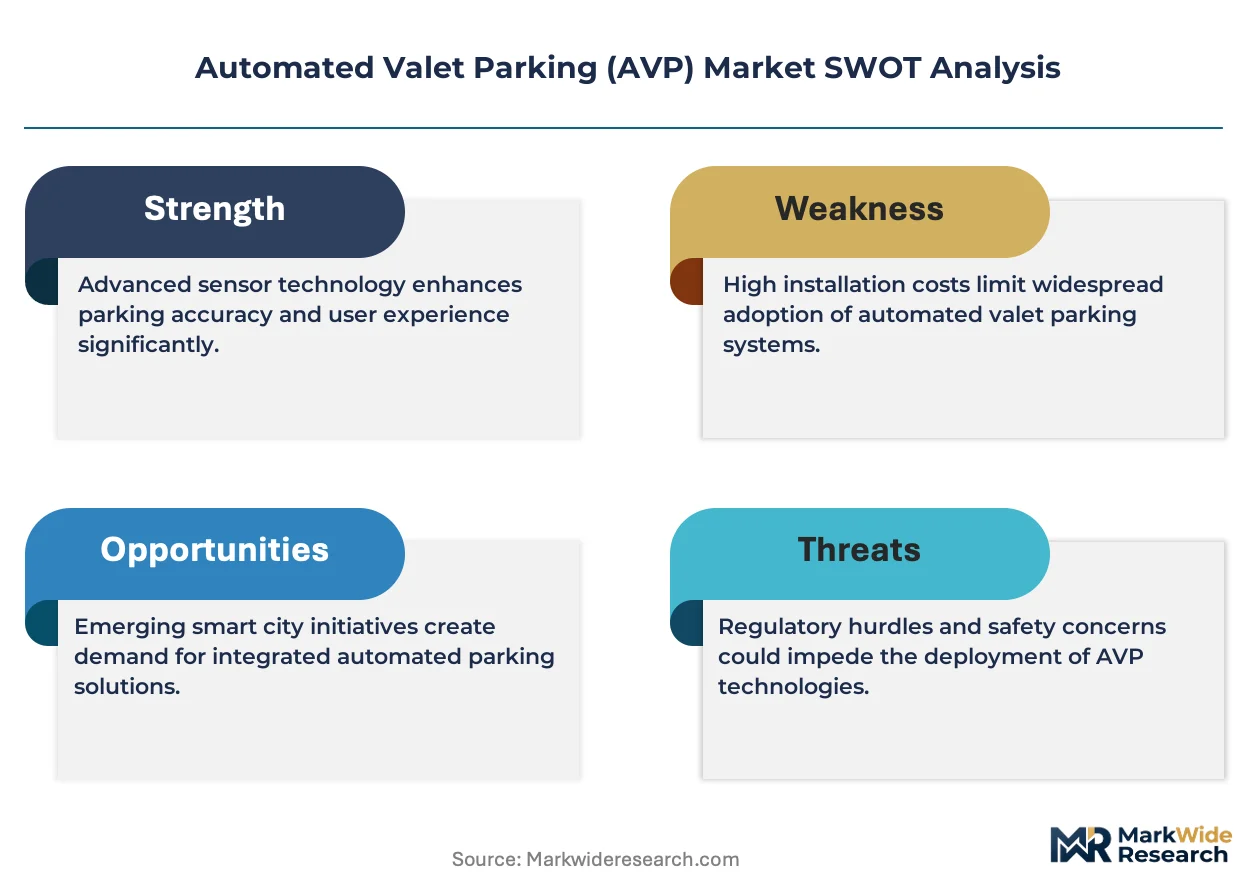
The EU AI Act and CE marking requirements under the MDR framework shape product standards for algorithmic decision-making in autonomous parking systems across Europe. Germany's KBA enforces type-approval protocols that directly gate market access for AVP-enabled vehicles sold in that jurisdiction. Stakeholders must monitor how national regulators transpose the EU AI Act's risk-classification rules into concrete testing burdens for unsupervised parking maneuvers.
Market Dynamics
Camera-based localization systems are compressing cost structures faster than LiDAR alternatives, forcing incumbent sensor suppliers to reconfigure hardware-software bundling strategies across European and Chinese deployments.
Growth Catalysts
- EU AI Act risk-classification framework:Mandatory algorithmic safety documentation for unsupervised parking maneuvers creates compliance-driven replacement cycles among German commercial parking operators.
- Airport parking vertical:Premium pricing tolerance and predictable traffic patterns attract AVP deployments in high-throughput transit hubs seeking denser stall utilization.
- Ultrasonic sensor miniaturization:Tight-space maneuvering capabilities unlock retrofit opportunities in legacy parking structures with constrained ceiling heights and narrow ramps.
Market Restraints
- LiDAR component cost volatility:Rare-earth processing concentration in Chinese supply chains exposes European integrators to input price swings that erode project margins.
- CE marking timeline under MDR:Extended conformity assessment periods for safety-critical parking algorithms delay revenue recognition on contracted installations.
- Human valet labor arbitrage:Low-wage attendant pools in emerging markets substitute against capital-intensive automation in cost-sensitive deployments.
Strategic Opportunities
- Residential complex retrofits in China:Dense urban retail and residential clusters with limited surface area present white-space demand for infrastructure-light camera systems.
- White-label platform control:Commercial operators seek software development partnerships to own customer data and dynamic pricing algorithms rather than outsourcing to tier-one suppliers.
- ISO 26262 functional safety convergence:Alignment between automotive and parking infrastructure certification standards reduces duplicate testing burdens for cross-sector technology vendors.
Industry Challenges
- Sub-10-centimeter localization talent scarcity:Sensor fusion engineering expertise concentrates in automotive ADAS teams, forcing parking-focused vendors to compete for specialized calibration specialists.
- Legacy parking management system integration:API fragmentation across incumbent access control and payment platforms complicates real-time occupancy data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Valet Parking (AVP) Market |
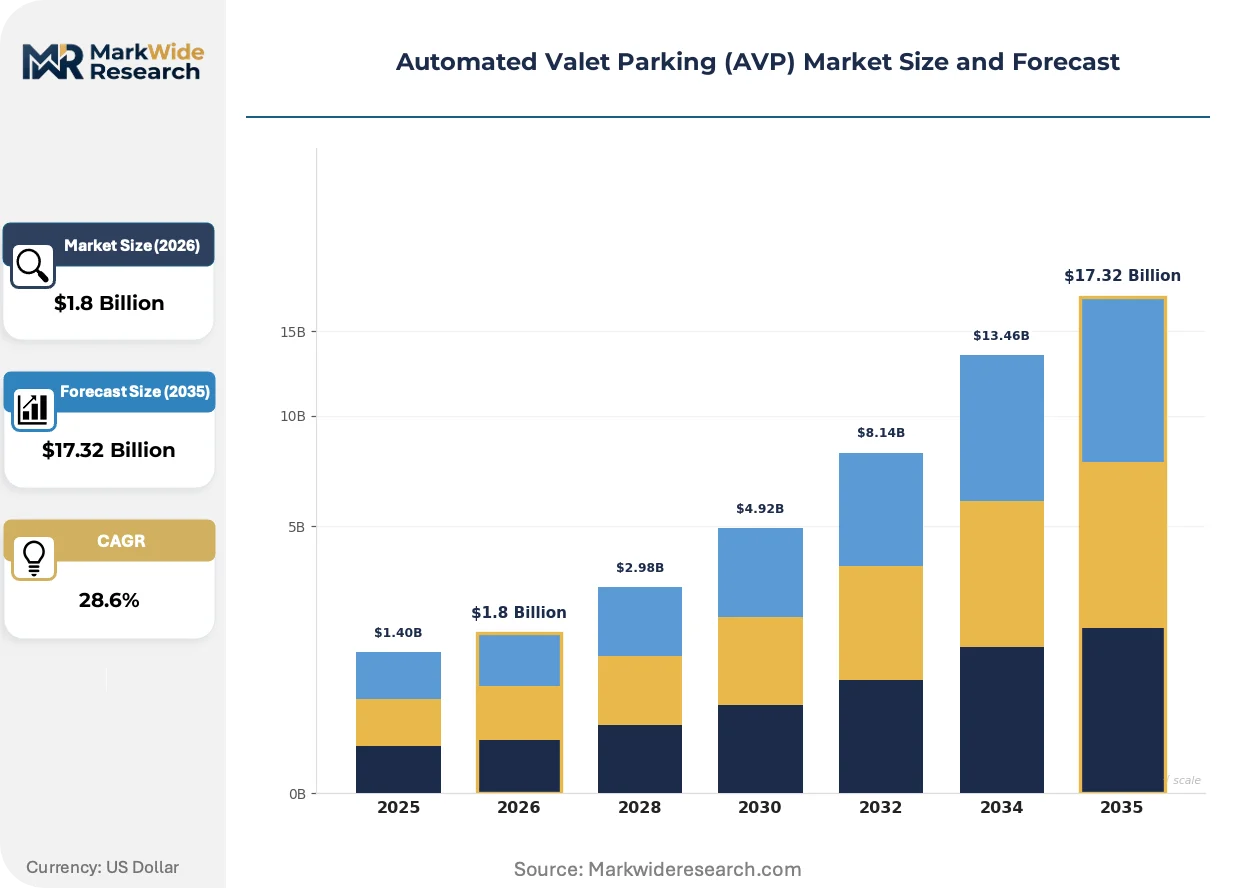
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Camera-Based Systems, GPS, Ultrasonic Sensors Application: Commercial Parking, Residential Parking, Airport Parking, Hotel Parking End User: Car Manufacturers, Parking Operators, Fleet Management, Real Estate Developers Service Type: Integration Services, Maintenance Services, Consulting, Software Development |
| Companies Covered | Robert Bosch, Valeo, Continental, Toyota, Volkswagen, Daimler, Aptiv, ZF Friedrichshafen, Baidu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Valet Parking (AVP) Market Trends and Innovations
Edge computing architectures are redistributing processing loads from centralized servers to distributed camera nodes, enabling faster obstacle response without fiber dependency in subterranean structures.
Multi-camera triangulation arrays with embedded AI accelerators are electrifying localization performance in GPS-denied environments. German premium OEMs embed these stacks in vehicle-born compute platforms for infrastructure-agnostic valet execution. The shift compresses reliance on fixed-structure sensor networks and enables roaming across heterogeneous parking facilities.
Germany's KBA type-approval protocols now mandate traceable training data documentation for neural networks controlling unsupervised parking trajectories. The requirement forces algorithm developers to restructure model development pipelines with audit-ready versioning systems. Tier-one suppliers with established automotive compliance functions capture certification bandwidth that excludes smaller software entrants.
Facility operators increasingly unbundle after-sales service contracts from initial hardware procurement, selecting specialized maintenance vendors on performance-based uptime guarantees. This procurement pattern disrupts traditional single-source supplier relationships. The shift concentrates in Dutch and Belgian commercial parking markets where facility management has professionalized around SLA-driven outsourcing.
Automated Valet Parking (AVP) Market Segmentation
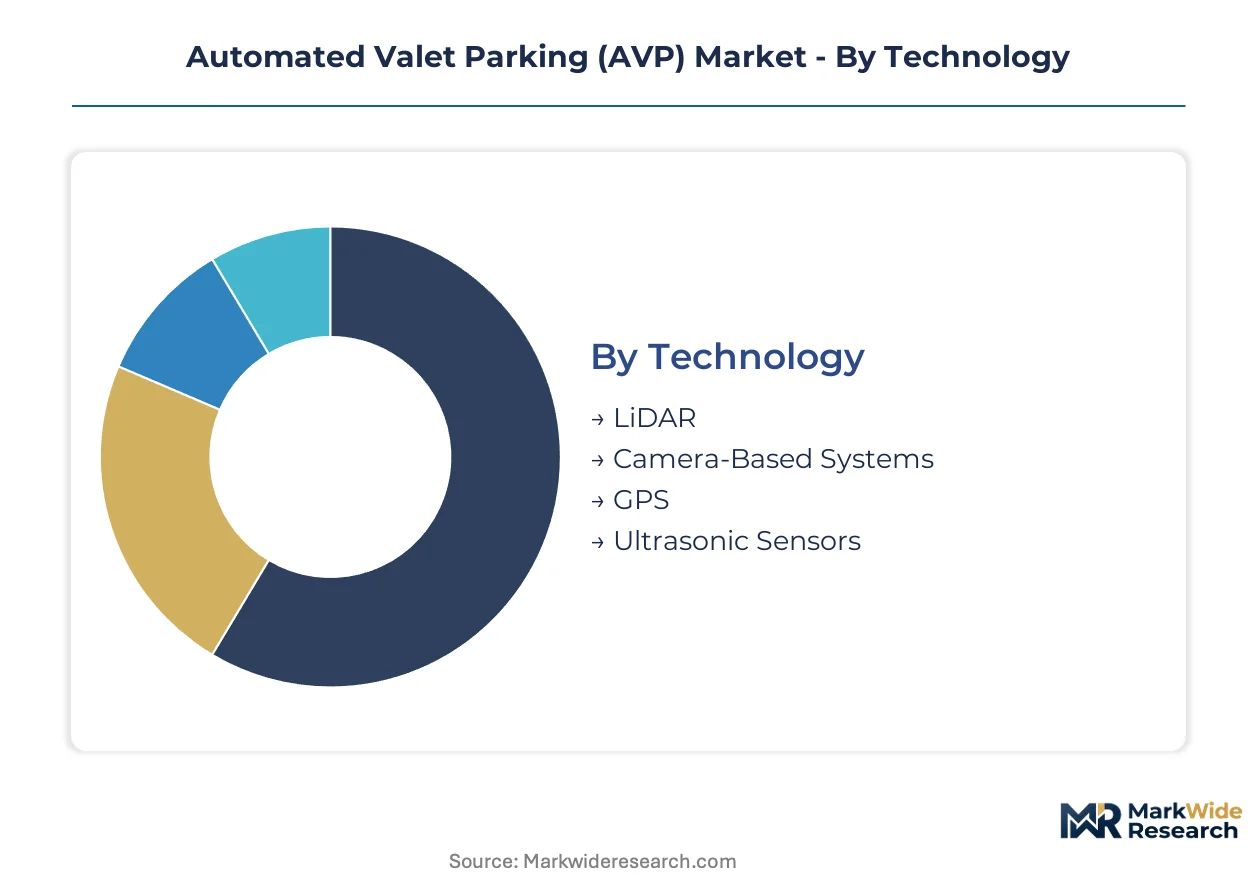
Technology choices in Automated Valet Parking determine capital intensity, regulatory compliance pathways, and retrofit feasibility across parking infrastructure. Application contexts shape sensor fusion requirements and pricing tolerance. End-user procurement power concentrates around fleet scale and real estate development pipelines.
Technology:
Sensor supply concentrates among three European and Asian component ecosystems with divergent cost curves and certification readiness.
- Camera-Based Systems:Multi-camera triangulation arrays with embedded AI accelerators deliver sub-10-centimeter localization in GPS-denied environments. Demand clusters in China where Baidu and domestic OEMs deploy infrastructure-light stacks in dense urban retail and residential complexes with constrained ceiling heights.
- LiDAR:Integrated LiDAR-camera stacks from Robert Bosch dominate manufacturing scale in European deployments requiring KBA type-approval for unsupervised parking trajectories. Rare-earth processing concentration in Chinese supply chains exposes integrators to input price volatility that erodes project margins.
- Ultrasonic Sensors:Valeo sustains technology leadership in miniaturization for tight-space maneuvering in legacy structures with narrow ramps and constrained vertical clearance.
- GPS:Satellite-based localization functions primarily as redundant overlay in surface parking lots with clear sky visibility; limited adoption in subterranean or dense urban deployments.
Camera-based systems absorb the bulk of installed capacity in new Chinese deployments; ultrasonic sensors are expanding most quickly in European retrofit applications.
Application:
Facility types stratify by pricing tolerance, traffic predictability, and space utilization pressure.
- Commercial Parking:Multi-story urban facilities with high turnover demand real-time occupancy mapping and dense stall configurations. Revenue concentrates in Germany where EU AI Act compliance drives replacement cycles among operators seeking algorithmic safety documentation.
- Airport Parking:Premium pricing tolerance and predictable traffic patterns attract deployments in high-throughput transit hubs. Denser stall utilization justifies capital expenditure through improved yield per square meter.
- Residential Parking:Limited surface area in dense urban clusters creates white-space demand for infrastructure-light camera systems with minimal structural modification.
- Hotel Parking:Guest experience differentiation drives adoption in premium hospitality segments; lower utilization rates compared to commercial facilities extend payback periods.
Commercial parking anchors current revenue recognition; airport parking is climbing the fastest as premium pricing tolerance justifies sensor density.
End User:
Procurement authority fragments across vehicle OEMs, facility operators, and development entities with divergent technical specifications.
- Car Manufacturers:German premium OEMs embed vehicle-born compute platforms for infrastructure-agnostic valet execution, compressing reliance on fixed-structure sensor networks.
- Parking Operators:Dutch and Belgian commercial markets professionalize around SLA-driven outsourcing, unbundling after-sales service from initial hardware procurement.
- Fleet Management:Predictable return-to-base patterns enable amortization of AVP infrastructure across high-utilization vehicle pools.
- Real Estate Developers:Pre-installation in new construction avoids retrofit complexity; certification alignment with ISO 26262 reduces duplicate testing burdens.
Parking operators deploy the majority of infrastructure-side installations; car manufacturers are gaining share fastest through vehicle-born platform integration.
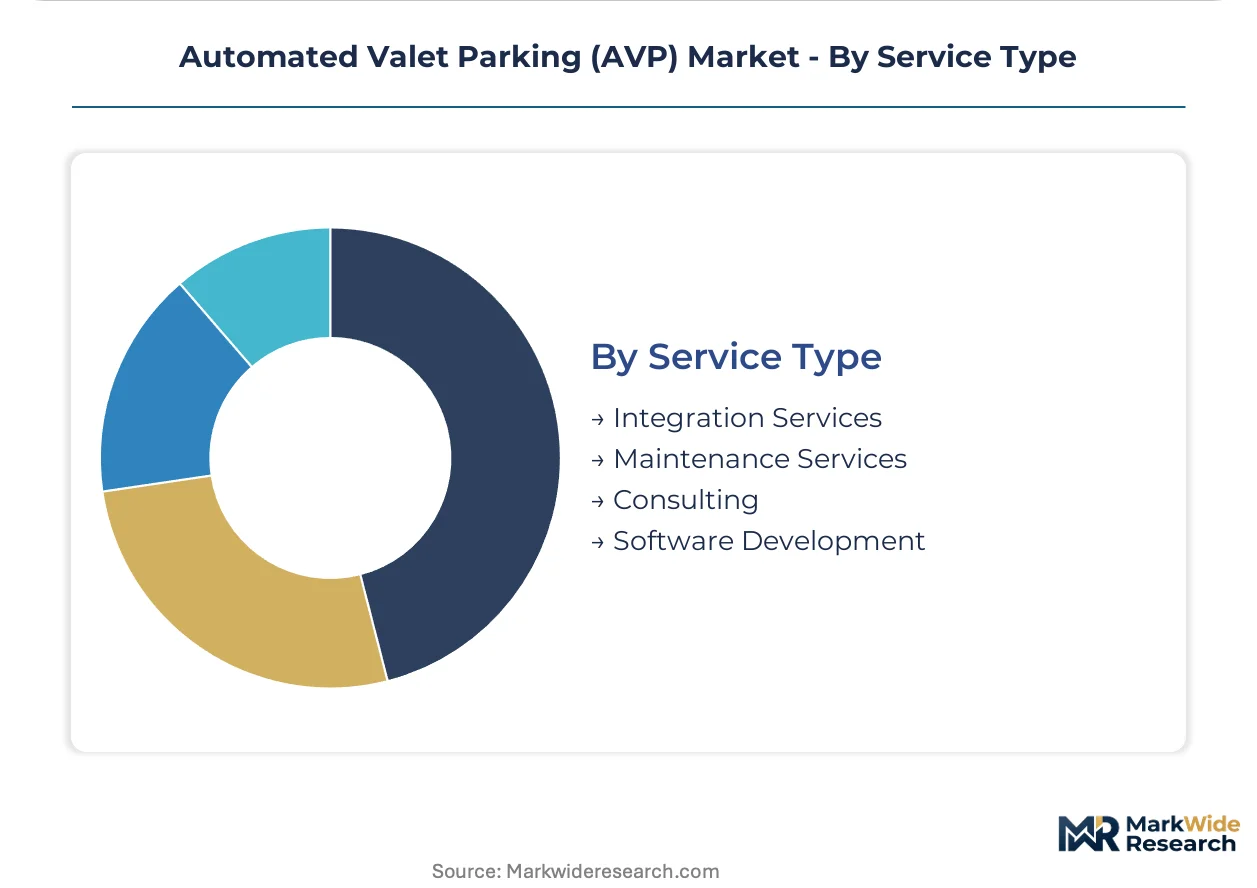
Service Type:
Margin capture shifts from hardware integration toward software ownership and performance-based maintenance.
- Integration Services:API fragmentation across incumbent access control and payment platforms complicates real-time occupancy data synchronization, extending project timelines.
- Software Development:Commercial operators seek white-label platform control to own customer data and dynamic pricing algorithms rather than outsourcing to tier-one suppliers.
- Maintenance Services:Facility operators select specialized vendors on performance-based uptime guarantees, disrupting traditional single-source supplier relationships.
- Consulting:Regulatory navigation support for EU AI Act risk-classification and KBA type-approval documentation concentrates among established automotive compliance functions.
Integration services dominate current contract value; software development is expanding most quickly as operators prioritize data sovereignty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of AVP sensor systems concentrates in Germany and China while consumption spreads across premium automotive markets and dense urban parking infrastructure. Manufacturing scale for LiDAR-camera stacks and embedded AI accelerators tilts toward established automotive electronics hubs. Deployment velocity varies sharply by regulatory environment and real estate development patterns.
China
Baidu and domestic OEMs drive infrastructure-light camera system deployments across dense urban retail and residential complexes in Shanghai and Shenzhen. MIIT standards for intelligent connected vehicles shape algorithmic safety documentation requirements for unsupervised parking functions. The Yangtze River Delta cluster anchors manufacturing scale for multi-camera triangulation arrays with embedded AI accelerators.
Germany
Commercial parking operators in Berlin and Munich accelerate replacement cycles as KBA type-approval protocols tighten for neural networks controlling autonomous trajectories. The EU AI Act risk-classification framework mandates traceable training data documentation that gates market access. Baden-Württemberg hosts integrated LiDAR-camera stack production serving European premium OEM vehicle-born compute platforms.
United States
Airport parking verticals in Atlanta and Dallas-Fort Worth attract premium-priced AVP installations leveraging predictable traffic patterns and denser stall utilization economics. NHTSA guidelines for automated driving systems influence liability frameworks for infrastructure-agnostic valet execution. The Southeast corridor concentrates fleet management pilot programs amortizing infrastructure across high-utilization vehicle pools.
Japan
METI funding for mobility-as-a-service infrastructure accelerates residential complex retrofits in Tokyo and Osaka with constrained surface area and narrow structural clearances. JIS standards alignment with ISO 26262 reduces duplicate certification burdens for cross-sector technology vendors. The Kanto region anchors ultrasonic sensor miniaturization R&D for tight-space maneuvering capabilities.
Netherlands
Dutch commercial parking markets professionalize around SLA-driven outsourcing models that unbundle after-sales service from initial hardware procurement. CE marking timelines under the MDR framework extend conformity assessment periods for safety-critical parking algorithms. The Randstad cluster leads facility management adoption of performance-based uptime guarantee contracts with specialized maintenance vendors.
Automated Valet Parking (AVP) Market Competitive Landscape
The competitive structure tilts toward tier-one automotive suppliers with established type-approval bandwidth and integrated hardware-software bundling capabilities. Sensor fusion engineering expertise concentrates among incumbent ADAS teams, forcing parking-focused vendors to compete for specialized calibration talent. Three archetypes dominate: integrated stack suppliers, miniaturization specialists, and vehicle-born platform integrators. Strategic moves center on certification bandwidth capture and geographic partnership anchoring rather than price-based displacement.
Among European tier-one suppliers, Robert Bosch exemplifies the integrated stack archetype through manufacturing scale dominance, while Valeo occupies a position within the miniaturization specialist tier. Continental anchors the vehicle-born platform integrator category through deep OEM partnerships. Baidu represents the infrastructure-light camera system archetype in Chinese deployments. Each archetype captures margin through distinct compliance pathways and sensor fusion configurations rather than converging on identical technology stacks.
| Leading Market Players |
|---|
| Robert Bosch |
| Valeo |
| Continental |
| Toyota |
| Volkswagen |
| Daimler |
| Aptiv |
| ZF Friedrichshafen |
| Baidu |
| Others |
Pricing and Supply Chain Analysis
Tier-one automotive suppliers with sovereign-backed R&D financing dominate AVP component production, compressing margin capture for independent integrators while enforcing strict certification-tier pricing discipline across European and Chinese procurement channels.
Pricing Analysis
Cost-down pressure on infrastructure-side installations accelerates as camera-based systems undercut LiDAR stacks by fifty percent or more at equivalent localization performance. Three-tier pricing structure across premium, standard, and economy levels separates KBA-certified German deployments from MIIT-compliant Chinese retrofits and uncertified emerging-market pilots. Price differentiation hinges on algorithmic safety documentation depth and after-sales service bundling. Parking operators in the Netherlands and Belgium exhibit lowest price sensitivity due to SLA-driven outsourcing professionalization, while Southeast Asian commercial facilities resist capital expenditure without labor-cost parity proof points.
Supply Chain Analysis
Regional distribution centers in Stuttgart and Shanghai anchor hub-and-spoke fulfillment for multi-camera triangulation arrays and embedded AI accelerators. Manufacturing concentrates in Germany for integrated LiDAR-camera stacks, China for infrastructure-light camera systems, and Japan for ultrasonic sensor miniaturization. Rare-earth processing for LiDAR components rests on Chinese supply chains, exposing European integrators to commodity price volatility and export restriction risk. Distribution runs through automotive tier-one channels rather than direct facility operator procurement, preserving supplier pricing control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AVP market sits in a technology-transition phase where infrastructure-agnostic vehicle-born platforms displace fixed-structure sensor networks as the dominant deployment architecture.
For Market Incumbents: Anchor certification bandwidth in KBA and MIIT jurisdictions to exclude software-only entrants lacking automotive compliance infrastructure. Deepen vertical integration into embedded AI accelerator production to capture margin migrating from hardware procurement to software ownership. Defend against Baidu's infrastructure-light camera dominance in Chinese residential retrofits through premium OEM partnership exclusivity. For New Entrants and Emerging Players: Dutch facility management specialists present the most penetrable channel for performance-based maintenance contracts unbundled from tier-one hardware supply. Target airport parking verticals in the US Southeast where premium pricing tolerance justifies sensor density without legacy system integration burden. Pursue white-label software development partnerships with commercial operators seeking dynamic pricing algorithm control. For Investors and Strategic Acquirers: Distressed-cycle entries favor ultrasonic sensor miniaturization specialists with JIS certification alignment in Japan's Kanto region. Long-term viability concentrates in vendors bridging ISO 26262 automotive and parking infrastructure standards. Monitor CE marking timeline compression under MDR framework as inflection signal for European replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| KBA Type-Approval Certification Investment | Gates market access for unsupervised parking trajectories in German premium OEM channels. |
| Vehicle-Born Compute Platform Integration | Enables roaming across heterogeneous facilities without fixed-structure sensor dependency. |
| White-Label Software Development Partnership | Transfers customer data and dynamic pricing ownership from tier-one suppliers to operators. |
| Ultrasonic Sensor Miniaturization R&D | Unlocks retrofit opportunities in legacy structures with constrained ceiling heights and narrow ramps. |
| Performance-Based Maintenance Contracting | Disrupts single-source supplier relationships through SLA-driven uptime guarantee competition. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with parking facility operators, Tier 1 supplier procurement managers, OEM platform engineers, and automotive compliance specialists. KBA type-approval documentation, MIIT intelligent connected vehicle standards, and EU AI Act risk-classification guidance provided regulatory validation. Bottom-up installation tracking across commercial, airport, and residential parking facilities triangulated against top-down sensor component shipment analysis.
Data-stream reconciliation across technology tier, application vertical, end-user procurement authority, and service-type margin capture shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by pricing tolerance and certification timeline constraints. Forecast inputs incorporated infrastructure-agnostic vehicle-born platform penetration rates and edge computing architecture deployment velocity in GPS-denied environments.
Caveats apply where CE marking timeline extensions under MDR or rare-earth supply disruption could materially shift the outlook. Forecasts reflect stated assumptions regarding KBA and MIIT regulatory convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) System Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market