
 Automotive Power Module Packaging Market | 2026-2036
Automotive Power Module Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Module Packaging Market Outlook
Silicon carbide integration into traction inverters is narrowing the thermal performance gap between discrete modules and full power modules. Infineon Technologies leverages its Dresden fab capacity to anchor European supply for automotive-grade packaging substrates. Mitsubishi Electric dominates high-voltage module architectures for heavy electric vehicles across Asian production networks. Toshiba Electronics Device & Storage Corporation specializes in compact dual in-line package designs that target passenger EV onboard chargers.
Automotive power module packaging encompasses the protective enclosure, electrical interconnection, and thermal management systems that house semiconductor switches operating at voltages from 400V to 800V and junction temperatures exceeding 175°C; its primary purpose is to ensure electrical isolation, mechanical integrity, and heat dissipation under severe automotive load cycles. Plastic encapsulated modules carry the highest unit volumes in cost-sensitive compact EV platforms, while ball grid array formats are capturing the fastest growth in 800V architectures where power density requirements intensify. Dual in-line package configurations retain a stable position in aftermarket replacement channels where design-in flexibility matters more than peak thermal performance.
F-Gas Regulation in Europe and REACH chemical restrictions are banning certain polymer compounds used in encapsulant formulations, forcing reformulation of thermal interface materials across the supply base. EPA vehicle emissions standards in the United States and China's MIIT new energy vehicle mandates are synchronizing to push higher inverter efficiencies that only advanced packaging can deliver. NHTSA safety standards for high-voltage isolation add a third compliance layer that shapes product qualification timelines. Stakeholders must monitor how material substitution timelines intersect with customer platform lock-in periods across major automotive manufacturing regions.
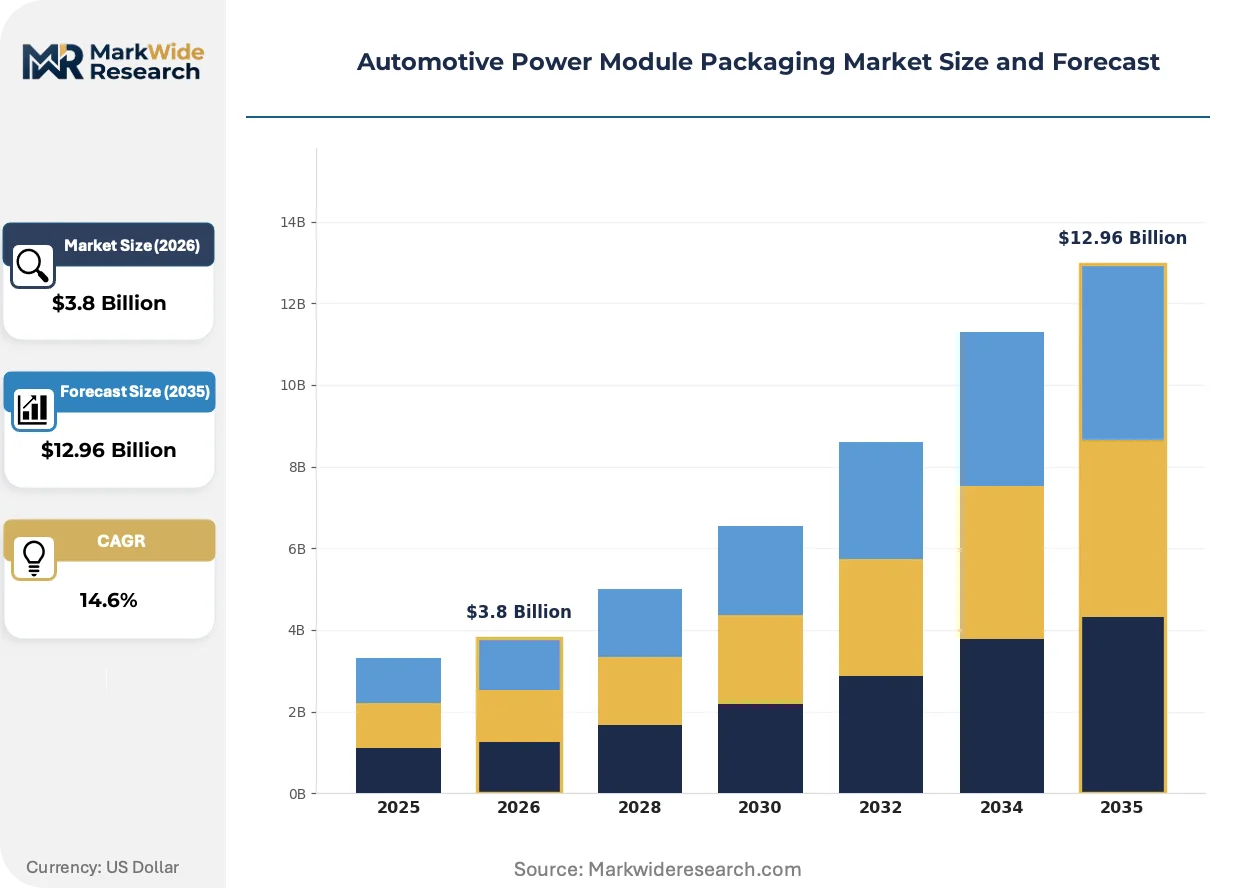
Market Dynamics
Silicon carbide inverter adoption is compressing thermal management tolerances and forcing packaging architectures to migrate from 400V to 800V platforms within single vehicle generations. This voltage transition is restructuring supplier qualification timelines and substrate material specifications simultaneously.
Growth Catalysts
- MIIT new energy vehicle mandates:China's efficiency targets for traction inverters are accelerating demand for advanced thermal interface materials in domestic EV production lines.
- 800V platform proliferation:Passenger electric vehicle OEMs are specifying ball grid array formats to achieve power density targets that discrete modules cannot satisfy.
- Germany's automotive corridor:Manufacturing concentration around Stuttgart and Munich is pulling packaging substrate capacity toward European qualification standards.
Market Restraints
- Silver and copper price volatility:Electrical interconnection materials face input cost swings that compress gross margins on high-volume plastic encapsulated modules.
- Dresden fab concentration:European automotive-grade substrate capacity remains anchored at a single high-volume facility, creating geographic supply vulnerability.
- F-Gas polymer bans:REACH-compliant reformulation of encapsulant compounds is extending material qualification cycles by 12-18 months.
Strategic Opportunities
- Heavy electric vehicle segment:High-voltage module architectures for commercial trucks and buses remain underpenetrated relative to passenger car saturation.
- Aftermarket dual in-line packages:Replacement channel flexibility is creating white space for second-source packaging suppliers outside OEM captive programs.
- Onboard charger integration:Compact packaging designs for AC-DC conversion are converging with traction inverter thermal management expertise.
Industry Challenges
- Thermal simulation talent scarcity:Finite element analysis expertise for multi-physics packaging design is concentrated at semiconductor fabs and unavailable to tier-two suppliers.
- NHTSA high-voltage isolation certification:Safety standard compliance timelines are misaligned with automotive platform lock-in windows, squeezing design-in opportunities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Module Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Modules, Dual In-line Package, Ball Grid Array, Plastic Encapsulated End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Aluminum, Copper, Polymer, Silicon Carbide Application: Power Distribution, Electric Drive, Thermal Management, Energy Storage |
| Companies Covered | Fuji Electric, Semikron Danfoss, Infineon Technologies, Mitsubishi Electric, onsemi, STMicroelectronics, Toshiba Electronics Device & Storage Corporation, JCET Group, Amkor Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Module Packaging Market Strategic Shifts
Packaging architectures are migrating from passive thermal dissipation toward active thermal management integration. This shift is compressing the boundary between semiconductor substrate and system-level cooling infrastructure.
Silver sintering die-attach technology is replacing solder-based interconnection in high-reliability automotive modules. Tier-one inverter suppliers are qualifying sintered joints for 800V silicon carbide devices to survive junction temperatures exceeding 175°C under severe load cycles. This transition is virtualizing the traditional distinction between power module packaging and bare die thermal management, forcing substrate suppliers to absorb cooling system design responsibility.
Europe's F-Gas Regulation is banning hydrofluorocarbon-based polymer precursors used in conventional encapsulant formulations. Compound suppliers are reformulating thermal interface materials with silicone alternatives that satisfy REACH chemical restrictions while maintaining dielectric strength. German automotive OEMs are pushing these reformulated materials through accelerated aging protocols to prevent platform delays.
Electric vehicle OEMs are consolidating inverter procurement around vertically integrated powertrain divisions rather than discrete component sourcing. Tier-one suppliers are responding by offering packaged module subassemblies that include gate drivers and current sensors. This purchasing concentration is most visible in Germany and China, where platform-scale commitments are locking out second-source packaging vendors from 2026 vehicle programs.
Automotive Power Module Packaging Market Segmentation
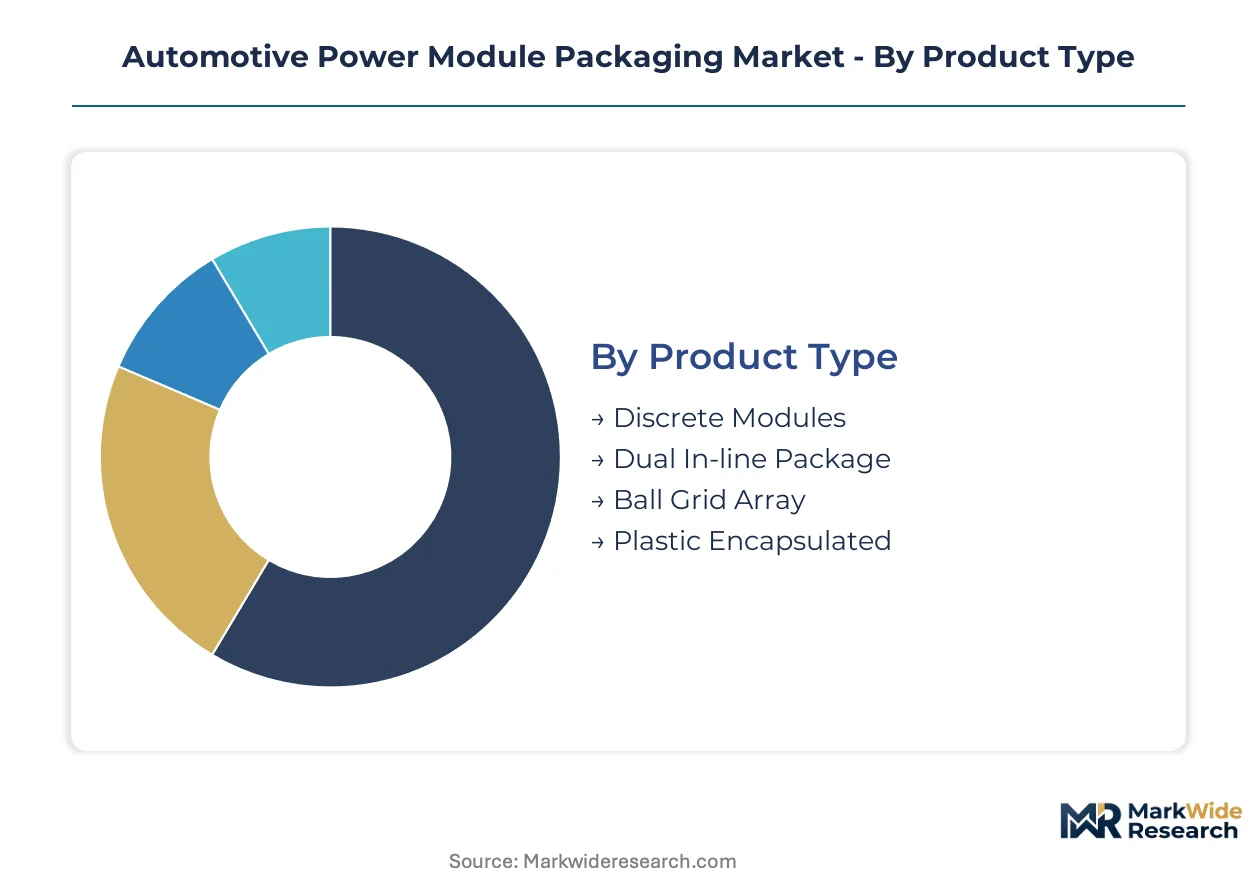
Automotive power module packaging segmentation reveals divergent technical requirements across voltage classes and thermal loads. Product architecture, procurement channel, substrate material, and system integration point each reshape supplier qualification protocols and margin structures differently.
Product Type:
After-sales-service intensity varies sharply across formats, with field-replaceable units demanding inventory depth and technical documentation that captive OEM supply chains rarely maintain.
- Plastic Encapsulated:Molded polymer housings with integrated leadframes dominate cost-optimized compact EV platforms where unit economics favor high-volume, lower-thermal-performance solutions. Procurement concentrates at Chinese and German vehicle assemblers seeking 400V traction inverter cost reduction.
- Ball Grid Array:Solder sphere interconnection arrays enable the highest interconnect density for 800V silicon carbide inverters where junction temperatures exceed 175°C. Demand clusters at premium passenger EV programs in Germany's Stuttgart corridor requiring power density thresholds discrete formats cannot satisfy.
- Discrete Modules:Individual semiconductor packages with external thermal management suit prototype development and low-volume commercial vehicle conversions.
- Dual In-line Package:Through-hole mounting configurations persist in aftermarket replacement channels where design-in flexibility outweighs peak thermal specifications.
By volume, Plastic Encapsulated leads. By growth pace, Ball Grid Array is expanding most quickly.
End User:
Cost tier stratification separates specification authority from manufacturing execution across the value chain.
- OEMs:Captive powertrain divisions at Volkswagen, BYD, and Tesla directly specify packaging substrates and thermal interface materials, locking qualification timelines to platform development cycles.
- Tier-1 Suppliers:Delphi Technologies and Vitesco Technologies package modules with integrated gate drivers and current sensors, absorbing cooling system design responsibility from semiconductor fabs.
- Vehicle Assemblers:Contract manufacturers in Hungary and Mexico execute final module integration without substrate specification authority.
- Aftermarket Providers:Independent distributors stock dual in-line configurations for legacy hybrid fleets outside OEM warranty networks.
Specification control concentrates at OEMs. Procurement volume growth is strongest at Tier-1 Suppliers.
Material:
Application temperature ceiling dictates substrate selection, with thermal conductivity requirements climbing alongside silicon carbide adoption.
- Silicon Carbide:Wide-bandgap semiconductor substrates enable 800V architectures with switching losses below silicon equivalents, though silver sintering die-attach requirements complicate packaging qualification.
- Copper:High-conductivity electrical interconnection layers face price volatility that compresses margins on plastic encapsulated modules produced at volume.
- Aluminum:Lightweight baseplates serve mid-power 400V inverters where cost sensitivity outweighs thermal performance optimization.
- Polymer:Encapsulant compounds are undergoing REACH-compliant reformulation as F-Gas Regulation bans hydrofluorocarbon-based precursors across European supply chains.
Silicon Carbide commands premium positioning. Aluminum retains the broadest installed base.
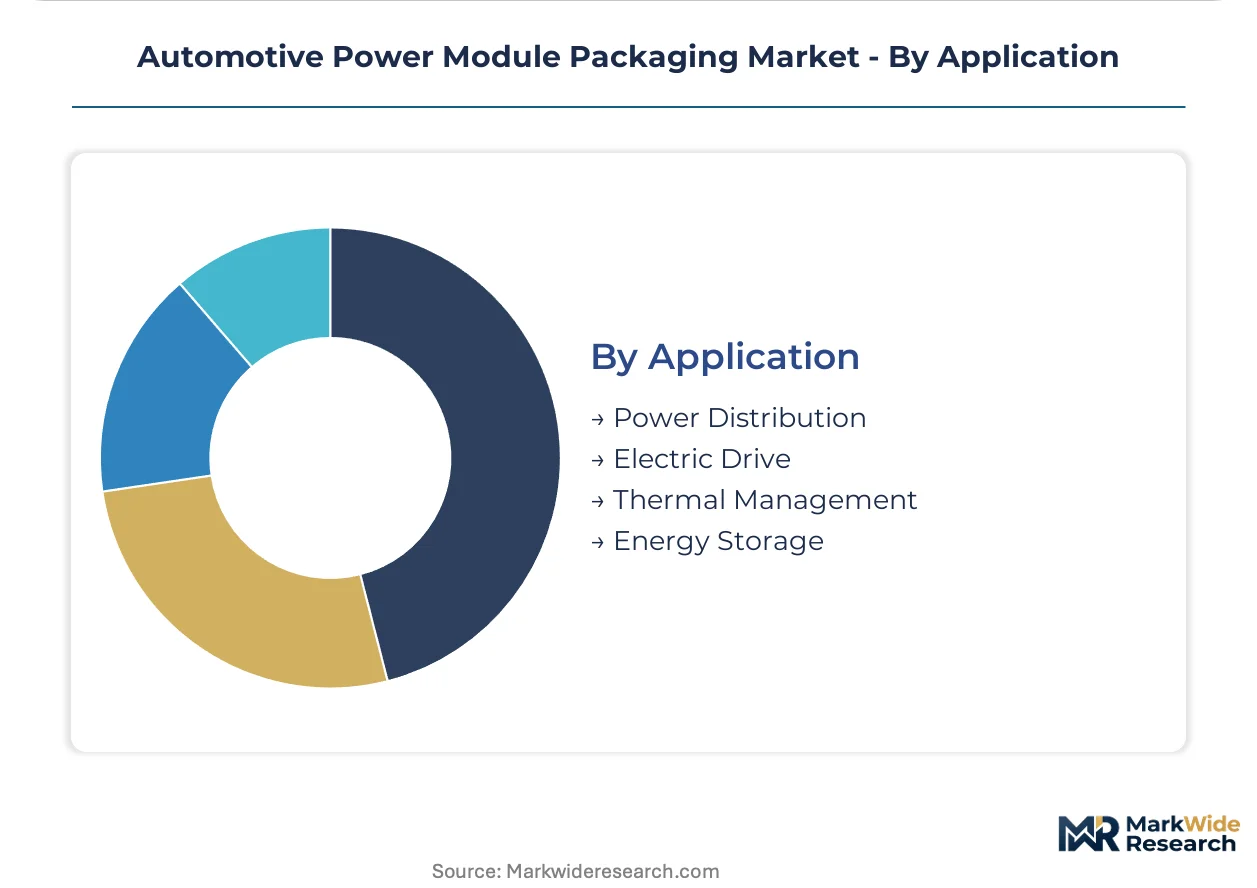
Application:
Customer type divergences separate high-voltage traction systems from auxiliary power conversion in procurement priority.
- Electric Drive:Traction inverter packaging integrates active thermal management with semiconductor substrates, compressing the boundary between module and system-level cooling infrastructure.
- Thermal Management:Interface materials and heat spreaders qualify separately from power modules under NHTSA high-voltage isolation protocols.
- Power Distribution:DC-DC converter packaging for auxiliary systems operates at lower switching frequencies with less stringent junction temperature requirements.
- Energy Storage:Battery management system packaging emphasizes electrical isolation over thermal dissipation, using simpler polymer encapsulation.
Electric Drive absorbs the majority of advanced packaging R&D investment. Thermal Management is gaining share fastest as 800V platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging substrate exports flow predominantly to Chinese electric vehicle assembly plants, while Japanese power module architectures serve heavy commercial vehicle programs across Southeast Asian production networks.
Germany
Stuttgart and Munich anchor European demand for 800V silicon carbide packaging substrates as Volkswagen and BMW accelerate platform electrification. ECHA REACH compliance and F-Gas Regulation restrictions are forcing reformulation of polymer encapsulants across the supplier base. Infineon Technologies leverages its Dresden fab capacity to serve domestic OEM qualification timelines.
China
MIIT new energy vehicle mandates are compressing supplier qualification cycles for traction inverter packaging across BYD and NIO production lines. GB standards for high-voltage isolation are tightening concurrently with efficiency targets. The Yangtze River Delta concentration around Shanghai pulls ball grid array substrate capacity toward domestic EV platform lock-ins.
United States
EPA vehicle emissions standards are synchronizing with NHTSA high-voltage isolation protocols to reshape packaging procurement at Tesla and Ford powertrain divisions. The Inflation Reduction Act domestic content requirements are redirecting substrate sourcing patterns. Michigan and Texas manufacturing corridors are absorbing qualification capacity for 800V silicon carbide module designs.
Japan
METI carbon neutrality roadmaps are accelerating heavy electric vehicle packaging demand for commercial bus and truck inverter architectures. JIS standards for thermal interface materials are converging with automotive reliability protocols. Nagoya and Tokyo industrial basins concentrate Mitsubishi Electric and Toshiba module packaging expertise for Asian export markets.
South Korea
MFDS chemical safety assessments are extending material qualification timelines for encapsulant compounds in Hyundai-Kia supply chains. Government battery and powertrain investment programs are concentrating procurement authority at captive tier-one divisions. The Seoul Capital Area anchors domestic packaging substrate demand for 800V platform proliferation.
Automotive Power Module Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure concentrates specification authority at semiconductor fabs with captive packaging capacity, while tier-one inverter suppliers absorb module integration responsibility. Three archetypes dominate: vertically integrated semiconductor manufacturers, independent packaging service providers, and captive automotive tier-one divisions. Capacity expansion and strategic partnerships represent the primary competitive vectors as qualification timelines compress.
Within the integrated semiconductor tier, Infineon Technologies and Mitsubishi Electric exemplify fab-anchored packaging strategies that internalize substrate production and thermal management design. Toshiba Electronics Device & Storage Corporation occupies a position among Japanese specialists emphasizing compact formats for auxiliary power conversion applications. These three anchors illustrate how geographic manufacturing concentration and product architecture specialization stratify competitive positioning across voltage class and thermal performance requirements.
| Leading Market Players |
|---|
| Fuji Electric |
| Semikron Danfoss |
| Infineon Technologies |
| Mitsubishi Electric |
| onsemi |
| STMicroelectronics |
| Toshiba Electronics Device & Storage Corporation |
| JCET Group |
| Amkor Technologies |
| Others |
Value Chain & Pricing Dynamics
Silver price volatility determines both pricing tier spreads and supply chain shape across automotive power module packaging. Input cost swings compress margins on high-volume plastic encapsulated modules while forcing buyers toward longer-term offtake contracts that lock in substrate capacity at Infineon's Dresden fab.
Pricing Analysis
The 400V-to-800V technology-generation pricing gap separates legacy silicon-based modules from silicon carbide premium tiers. Three-tier pricing structure across premium ball grid array, standard plastic encapsulated, and economy dual in-line configurations reflects certification grade differentiation under NHTSA high-voltage isolation protocols. Cost compression in the plastic encapsulated tier is intensifying because Chinese vehicle assemblers are consolidating procurement around vertically integrated powertrain divisions. Tier-1 suppliers exhibit the lowest price sensitivity due to captive platform lock-ins, while aftermarket distributors face acute margin pressure from spot-market silver and copper sourcing.
Supply Chain Analysis
Upstream feedstock concentration in Chilean copper mining, Chinese rare earth processing, and German polymer precursor production anchors global substrate availability. Raw material dependencies center on silver sintering pastes, ceramic substrates, and REACH-compliant silicone encapsulants. Single-source vulnerability concentrates at the Dresden fab for European automotive-grade qualification. Distribution runs through captive OEM supply chains in Germany and China, with secondary channels serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
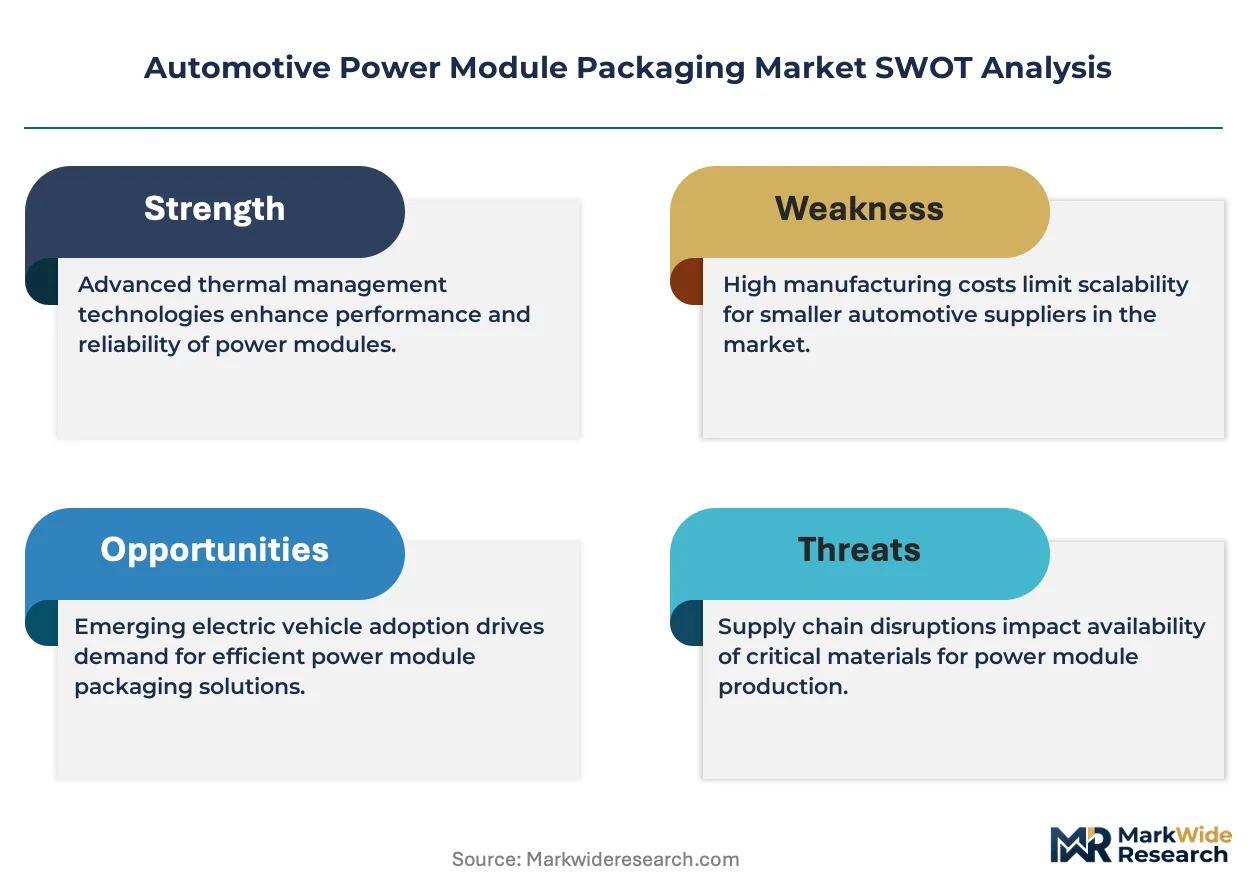
Incumbents must navigate gallium nitride inverter modules as a substitute threat that could displace silicon carbide packaging architectures in cost-optimized 400V platforms.
For Market Incumbents: Harden qualification timelines by securing silver sintering die-attach capacity ahead of 800V platform lock-ins. Deepen backward integration into ceramic substrate production to offset copper price volatility. Absorb thermal simulation expertise from semiconductor fabs before tier-two suppliers lose access entirely. For New Entrants and Emerging Players: Pursue aftermarket dual in-line package channels where OEM warranty networks create service gaps. Heavy electric vehicle high-voltage architectures remain the most penetrable segment relative to passenger car saturation. Qualify reformulated REACH-compliant encapsulants as a go-to-market angle for European replacement demand. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors packaging service providers with captive thermal management design capability. Long-term viability hinges on substrate suppliers absorbing cooling system responsibility from inverter integrators. Watch silver sintering qualification timelines as the inflection indicator for technology-generation transition speed.| Strategic Initiative | Industry Significance |
|---|---|
| Silver Sintering Capacity Expansion | Infineon and Mitsubishi Electric are qualifying sintered joints for 175°C junction temperatures under MIIT mandates. |
| REACH-Compliant Encapsulant Reformulation | German compound suppliers are accelerating aging protocols to prevent platform delays from F-Gas Regulation bans. |
| Captive Thermal Management Integration | Tier-1 suppliers like Vitesco Technologies absorb cooling system design from semiconductor fabs. |
| 800V Platform Standardization | Volkswagen and BMW procurement concentrates around ball grid array formats in the Stuttgart corridor. |
| Aftermarket Channel Partnership | Independent distributors stock dual in-line configurations for legacy hybrid fleets outside OEM networks. |
Study Parameters
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and semiconductor fab thermal management directors converged on the working assumptions. Primary interviews combined with secondary validation from EPA vehicle emissions filings, MIIT new energy vehicle mandate disclosures, ECHA REACH substance restriction updates, and IHS Markit vehicle production databases. Bottom-up unit demand estimates triangulated against top-down powertrain content projections.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include product architecture, voltage class, substrate material, and regional production cluster alignment with OEM platform sourcing. CAGRs derived from technology adoption curve analysis for silicon carbide inverter penetration and regulatory compliance timeline compression. Forecast inputs incorporated silver price trajectory assumptions and F-Gas Regulation material substitution schedules.
Sensitivities concentrate around silver commodity volatility, REACH reformulation delays, and 800V platform adoption speed. Forecasts reflect documented assumptions about semiconductor fab capacity expansion and thermal simulation talent availability. Cross-checking against IEA electric vehicle deployment benchmarks and MIIT production target disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market