
 Automotive Clean Cold Technology Market | 2026-2036
Automotive Clean Cold Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Clean Cold Technology Market Analysis
Electric vehicle thermal management is expanding faster than conventional passenger car cooling, pulling investment toward high-voltage-compatible clean cold architectures. MAHLE GmbH leverages its compressor R&D pipeline to anchor European OEM supply relationships for CO2 heat pump systems. Valeo competes through integrated module designs that combine refrigerant circuits with battery thermal regulation. DENSO dominates production scale for electric compressor platforms serving Japanese and North American automakers.
Automotive clean cold technology encompasses refrigerant systems, heat exchangers, and thermal control units engineered to replace high-global-warming-potential fluids with substances below 150 GWP, operating at pressures up to 100 bar in transcritical CO2 cycles to maintain cabin and battery temperatures across ambient extremes. Compressor and refrigerant segments attract the deepest engineering investment as OEMs confront material compatibility challenges with CO2 and hydrocarbon alternatives. Electric vehicle applications generate the fastest growth trajectory within the application dimension, though heavy-duty platforms sustain premium pricing for multi-circuit configurations. Magnetic refrigeration occupies an early-phase position with limited commercial deployment but concentrated patent activity from specialized developers.
EU F-Gas Regulation mandates phased reduction of fluorinated gas emissions, forcing refrigerant transitions across European vehicle production lines. EPA SNAP program and California Air Resources Board rules constrain acceptable refrigerant formulations in the United States, while China's MEE implements parallel controls under national carbon neutrality commitments. OEM procurement teams must monitor regulatory divergence between jurisdictions to avoid platform redesign costs as compliance timelines tighten across major production regions.
Market Dynamics
The EU F-Gas Regulation's phasedown schedule is forcing OEMs to abandon R-134a and R-1234yf refrigerants before 2030, compressing engineering timelines for CO2 and hydrocarbon system validation across vehicle platforms.
Growth Catalysts
- EU F-Gas Regulation:Mandatory HFC phase-down creates binding compliance deadlines that accelerate refrigerant transition investments across European production lines.
- Electric vehicle battery thermal management:High-voltage architectures require dedicated cooling circuits that clean cold systems address more efficiently than legacy refrigerants.
- China's MEE enforcement:National carbon neutrality commitments drive parallel regulatory controls that expand addressable market for low-GWP platforms in the world's largest vehicle production base.
Market Restraints
- Stainless steel cost volatility:CO2 systems require high-pressure-rated alloys that expose OEMs to raw material price swings from concentrated metallurgical suppliers.
- Sealing technology bottleneck:Elastomer compatibility at 100 bar transcritical pressures remains unresolved for several polymer classes, limiting component sourcing options.
- EPA SNAP program fragmentation:State-level regulatory divergence between California Air Resources Board rules and federal frameworks forces redundant certification pathways.
Strategic Opportunities
- Heavy-duty commercial vehicles:Multi-circuit thermal configurations for battery-electric trucks and buses command premium positioning with limited incumbent competition.
- Magnetic refrigeration convergence:Solid-state cooling eliminates refrigerant fluids entirely, offering breakthrough pathway for next-generation platforms if magnetocaloric materials scale.
- India's BIS adoption timeline:Pending national standards for low-GWP refrigerants create first-mover window for suppliers establishing local assembly partnerships.
Industry Challenges
- High-pressure system validation:OEMs must rebuild entire test protocols for 100 bar CO2 cycles, extending development cycles by 18-24 months versus conventional refrigerants.
- Cross-contamination protocols:Service networks require complete infrastructure separation between flammable hydrocarbon and non-flammable CO2 systems, complicating aftermarket rollout.
- Thermodynamics expertise scarcity:Transcritical cycle optimization demands specialized competency that traditional HVAC engineering pools rarely possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Clean Cold Technology Market |
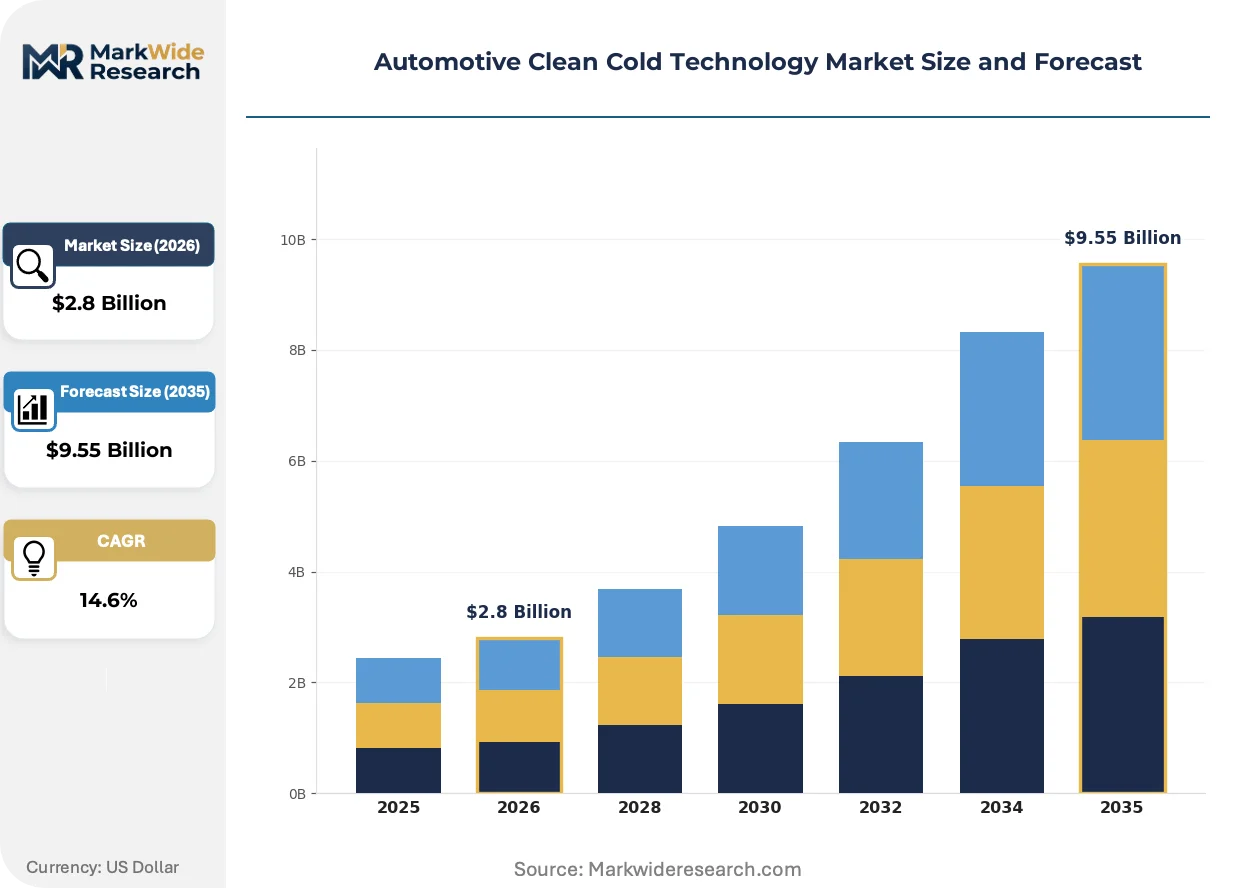
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Compressors, Condensers, Evaporators, Refrigerants Application: Passenger Vehicles, Light Trucks, Heavy-Duty Vehicles, Electric Vehicles Technology: Hydrocarbon-Based, CO2 Systems, Mixed Refrigerants, Magnetic Refrigeration End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships |
| Companies Covered | Mitsubishi Heavy Industries, Hanon Systems, Dearman Engine Company, MAHLE GmbH, Valeo, Carrier, DENSO, Sanden, Thermo King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Clean Cold Technology Market Emerging Trajectories
Refrigerant chemistry and system architecture are converging around pressure-tolerant designs that abandon century-old vapor compression assumptions. Three developments dominate engineering investment.
CO2 transcritical heat pump architecture is absorbing the bulk of European OEM engineering resources as the technology matures from concept to production scale. Battery-electric vehicle programs in Germany and France are adopting these systems for simultaneous cabin heating and battery conditioning. The shift is absorbing development budgets that previously supported incremental R-1234yf improvements.
REACH chemical registration requirements are tightening material qualification timelines for sealants and lubricants exposed to new refrigerant chemistries. ECHA's expanded substance evaluation portfolio now captures several candidate hydrofluoroolefin alternatives. Suppliers serving French and Italian OEMs are pre-emptively reformulating compound portfolios to avoid authorization delays.
Fleet procurement departments are bundling thermal system specifications into long-term vehicle supply agreements rather than treating components as commodity afterthoughts. Large logistics operators in the United States are demanding 15-year refrigerant serviceability commitments. This pattern is most visible in California and Texas, where electrified commercial vehicle deployment timelines are accelerating.
Automotive Clean Cold Technology Market Segmentation
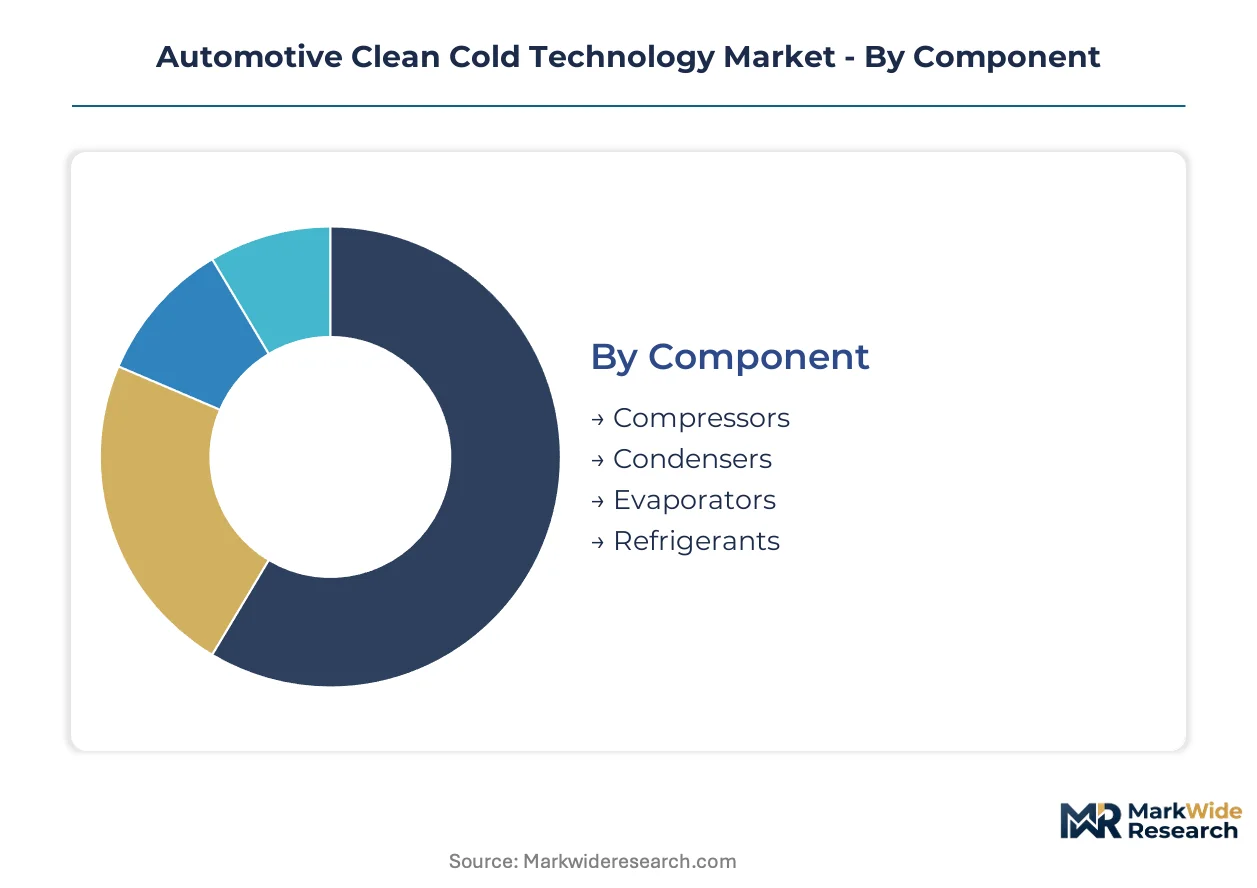
Clean cold technology procurement decisions diverge sharply across vehicle electrification levels and thermal load requirements. Component selection and refrigerant chemistry choices cascade through system architecture, creating distinct supplier qualification pathways for each segment cluster.
Component:
Buyer procurement teams weight pressure tolerance specifications and electric motor compatibility differently based on vehicle thermal load profiles.
- Compressors:Electric compressor platforms integrate high-voltage motor drives and inverter controls for battery thermal management. European OEMs in Germany and France concentrate CO2 heat pump compressor sourcing as EU F-Gas Regulation deadlines compress validation timelines.
- Refrigerants:Low-GWP formulations below 150 GWP include CO2, hydrocarbon blends, and hydrofluoroolefin alternatives with distinct material compatibility requirements. China's MEE enforcement expands addressable demand for CO2 and hydrocarbon platforms in domestic production lines.
- Condensers:High-pressure-rated aluminum microchannel designs serve transcritical CO2 cycles.
- Evaporators:Compact plate-and-fin configurations optimize packaging density for electric vehicle front-end modules.
Volume sits with compressors; growth tilts toward refrigerant chemistry transitions.
Application:
Thermal system complexity scales with vehicle mass and battery pack energy density, fragmenting engineering specifications across weight classes.
- Electric Vehicles:Dedicated high-voltage cooling circuits condition battery packs, power electronics, and cabin environments simultaneously. CO2 transcritical heat pump architectures from German and French OEM programs absorb the deepest engineering investment as battery-electric platforms multiply.
- Heavy-Duty Vehicles:Multi-circuit thermal configurations address battery-electric truck and bus applications with premium positioning. Fleet operators in California and Texas demand extended serviceability commitments for electrified commercial deployments.
- Passenger Vehicles:Conventional internal combustion platforms transition refrigerant chemistry under regulatory pressure.
- Light Trucks:Pickup and van segments balance payload capacity with thermal efficiency requirements.
Revenue concentrates in electric vehicles; expansion accelerates most steeply in heavy-duty configurations.
Technology:
Regulatory phase-down schedules and material availability constrain technology selection windows for platform engineers.
- CO2 Systems:Transcritical cycles operate at pressures up to 100 bar, demanding stainless steel alloys and specialized sealing compounds. European production lines lead validation as REACH chemical registration tightens material qualification timelines for sealants and lubricants.
- Magnetic Refrigeration:Solid-state cooling eliminates refrigerant fluids entirely through magnetocaloric materials. Patent activity concentrates among specialized developers with limited commercial deployment but breakthrough pathway potential if materials scale.
- Hydrocarbon-Based:Propane and isobutane blends offer low-GWP performance with flammability management requirements.
- Mixed Refrigerants:Custom blends balance thermodynamic performance with regulatory compliance across jurisdictions.
Deployment clusters in CO2 systems; magnetic refrigeration climbs fastest as next-generation investment.
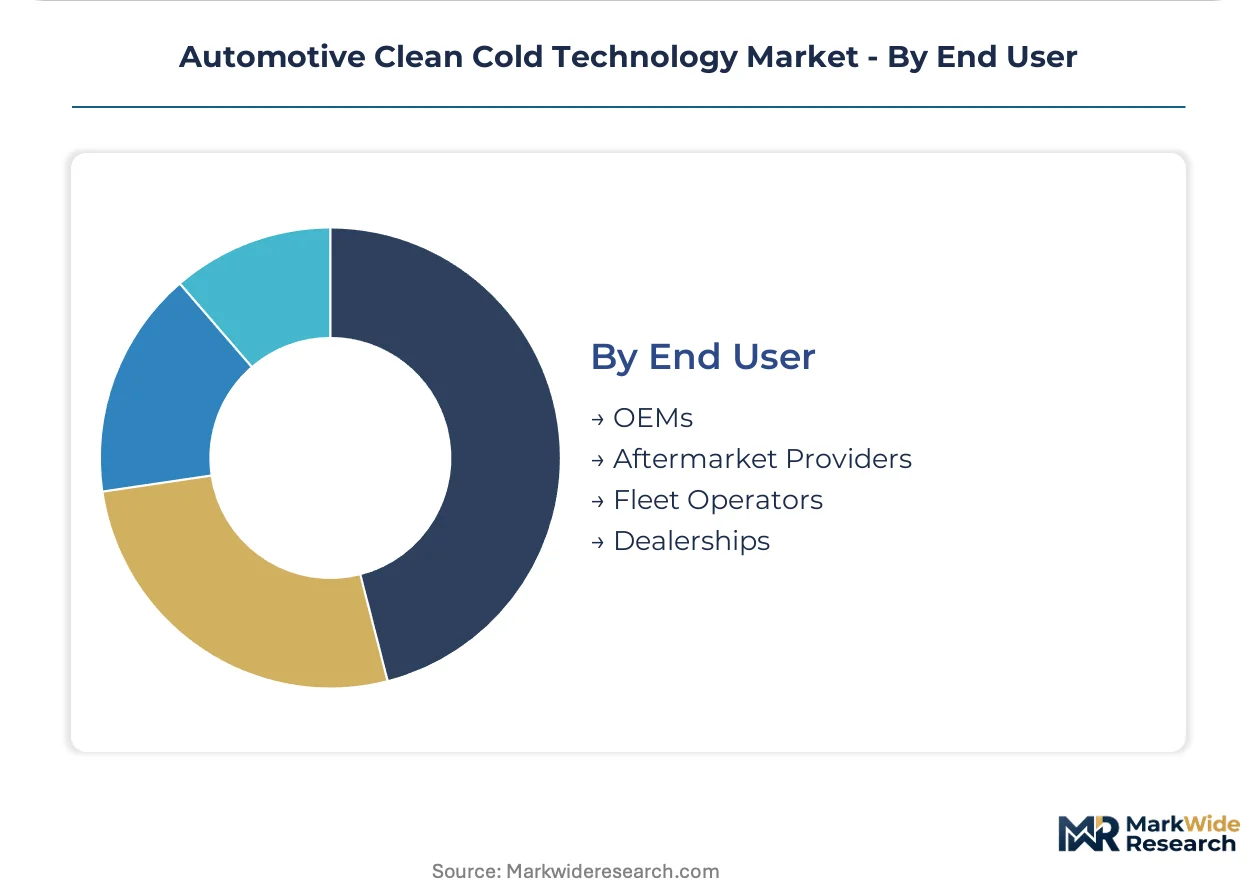
End User:
Procurement authority and service infrastructure requirements segment the supply chain between factory-fit and post-sale channels.
- OEMs:Vehicle manufacturers specify thermal system architectures during platform development, locking supplier relationships years before production. MAHLE GmbH, Valeo, and DENSO anchor European, integrated module, and Japanese-North American supply positions respectively.
- Fleet Operators:Large logistics departments bundle thermal specifications into long-term vehicle agreements with 15-year refrigerant serviceability demands. California-based electrified commercial vehicle procurement shows this pattern most visibly.
- Aftermarket Providers:Service networks require infrastructure separation between flammable hydrocarbon and non-flammable CO2 systems.
- Dealerships:Authorized service channels handle warranty thermal system maintenance and refrigerant recovery.
Platform decisions rest with OEMs; fleet operator influence expands most quickly in commercial electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany, China, and the United States concentrate OEM thermal system engineering and component manufacturing. These jurisdictions combine regulatory pressure with production incentives that accelerate clean cold technology deployment.
Germany
Battery-electric vehicle platforms from Stuttgart and Munich drive CO2 heat pump compressor demand. The EU F-Gas Regulation mandates HFC phasedown timelines that compress supplier validation schedules. Bavaria's automotive cluster hosts MAHLE GmbH R&D facilities anchoring European OEM supply relationships.
China
Domestic electric vehicle production scales in Shanghai and Shenzhen require high-voltage-compatible thermal management. The MEE enforces national carbon neutrality commitments through parallel refrigerant controls. Yangtze River Delta manufacturing bases expand CO2 system assembly capacity for export and domestic programs.
United States
California and Texas fleet operators demand 15-year refrigerant serviceability commitments for electrified commercial vehicles. The EPA SNAP program and California Air Resources Board rules constrain acceptable refrigerant formulations with fragmented certification pathways. Detroit-area engineering centers validate multi-circuit configurations for battery-electric trucks.
Japan
Tokyo and Nagoya metropolitan areas concentrate electric compressor production for Japanese and North American automakers. METI oversees industrial standards alignment with international refrigerant phase-down schedules. Kansai-region suppliers scale manufacturing for high-voltage motor drive integration.
France
Paris-based OEM programs adopt integrated module designs combining refrigerant circuits with battery thermal regulation. REACH chemical registration tightens material qualification timelines for sealants and lubricants exposed to new refrigerant chemistries. Auvergne-Rhône-Alpes hosts Valeo development facilities for next-generation heat pump architectures.
Automotive Clean Cold Technology Market Vendor Landscape
Top-tier vendors anchor European and Asian supply chains, while mid-tier specialists occupy niche technology positions. The vendor base clusters around compressor manufacturing, integrated thermal modules, and refrigerant chemistry innovation. Three archetypes dominate: diversified automotive suppliers with full-system capability, component specialists with electric motor expertise, and emerging technology developers pursuing magnetic refrigeration pathways. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs consolidate supplier relationships ahead of platform launches.
Within the diversified supplier tier, MAHLE GmbH, Valeo, and DENSO exemplify distinct geographic and technical positioning. MAHLE GmbH anchors European OEM relationships through compressor-focused R&D pipelines. Valeo occupies a position emphasizing integrated module designs that combine multiple thermal functions. DENSO represents scale-driven manufacturing concentration serving Japanese and North American production lines. These three entities illustrate how supplier archetypes map to regional OEM procurement patterns and electrification timelines.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Hanon Systems |
| Dearman Engine Company |
| MAHLE GmbH |
| Valeo |
| Carrier |
| DENSO |
| Sanden |
| Thermo King |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between REACH-compliant sealant portfolios and commodity elastomer alternatives manifests in both component pricing and supplier qualification pathways across European and Chinese production networks. OEM procurement teams face extended validation timelines for high-pressure CO2-compatible materials that compress supplier margins while elevating pricing power for qualified tier-one vendors serving German and French battery-electric platforms.
Pricing Analysis
Lead-time premiums attach to stainless steel alloy deliveries from concentrated metallurgical suppliers serving transcritical CO2 compressor manufacturing. Contract-based long-term offtake agreements dominate procurement for high-pressure-rated components, with price differentiation driven by REACH chemical registration status and electric motor integration complexity. Cost compression in commodity refrigerant alternatives is intensifying because hydrocarbon system validation cycles remain shorter than CO2 pathways. Fleet operators in California demonstrate lowest price sensitivity due to bundled 15-year serviceability commitments, while aftermarket distributors face margin pressure from infrastructure separation requirements.
Supply Chain Analysis
Single-source vulnerability sits with German stainless steel forging capacity for 100-bar pressure-rated compressor housings. Manufacturing concentration spans Germany, China, and Japan for electric compressor platforms, with raw material dependencies on nickel-chromium alloys, rare-earth motor magnets, and specialized polymeric sealants. Tariff exposure on European-sourced high-pressure components threatens cost structures for North American OEMs validating multi-circuit thermal configurations. Distribution runs through Tier 1 supplier direct-to-OEM channels with limited aftermarket penetration due to service network infrastructure requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's binding HFC phasedown creates a cost-of-compliance barrier that entrenches incumbent suppliers with validated CO2 system portfolios while raising capital requirements for unqualified entrants.
For Market Incumbents: Cement European OEM relationships through captive production of REACH-registered sealant compounds in Auvergne-Rhône-Alpes and Bavaria. Expand high-pressure validation facility capacity to capture battery-electric truck multi-circuit demand from California and Texas fleet operators. Defend against magnetic refrigeration patent clusters by accelerating transcritical CO2 heat pump production scale. For New Entrants and Emerging Players: Launch via technology licensing partnerships with Indian BIS standardization committees ahead of national low-GWP refrigerant adoption timelines. Target heavy-duty commercial vehicle aftermarket service networks where infrastructure separation requirements have slowed incumbent rollout. Penetrate through specialized sealing compound reformulation for hydrocarbon-CO2 compatibility gaps. For Investors and Strategic Acquirers: Re-rating potential sits with diversified thermal module suppliers given magnetic refrigeration breakthrough pathway uncertainty. Long-term viability favors entities with vertical integration into electric compressor motor drives and inverter controls. Watch for fleet operator procurement pattern shifts toward solid-state cooling commitments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Sealant Portfolio Expansion | ECHA substance evaluation timelines compress supplier qualification windows for French and Italian OEM programs. |
| High-Pressure Validation Facility Investment | 100-bar CO2 test protocol capacity anchors German and French battery-electric platform supplier selection. |
| Magnetic Refrigeration Patent Acquisition | Magnetocaloric material IP clusters offer next-generation pathway if solid-state cooling scales beyond laboratory demonstration. |
| India Local Assembly Partnership | BIS low-GWP refrigerant standards create first-mover positioning in domestic production lines ahead of enforcement timelines. |
| Fleet Operator Long-Term Service Agreement | 15-year refrigerant serviceability commitments from California logistics operators lock in aftermarket revenue streams. |
Methodological Framework
Vehicle production databases, IHS Markit registration data, and customs trade records formed the secondary backbone for market sizing validation. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership service operations supplemented secondary sources. Bottom-up and top-down triangulation cross-validated segment-level demand estimates against aggregate production forecasts.
Bottom-up modeling anchored volume projections to named OEM platform launches and battery-electric vehicle thermal content per vehicle assumptions across the analysis window. Segmentation dimensions included vehicle class, propulsion architecture, refrigerant chemistry, and regional regulatory cluster. CAGRs derived from production ramp schedules and technology adoption curves specific to CO2 transcritical heat pump penetration rates.
The model assumes a particular technology adoption path; alternative pathways for magnetic refrigeration would alter the outlook if magnetocaloric materials achieve production-scale cost parity. Forecasts reflect assumptions about EU F-Gas Regulation enforcement consistency and China's MEE parallel control implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Automotive PCB Market