
 Global Automotive Coupling Market | 2026-2036
Global Automotive Coupling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Coupling Market Intelligence
The capital investment gap between integrated electromechanical system development and traditional mechanical component manufacturing is reorganizing the competitive landscape. BorgWarner Inc. leverages its deep expertise in powertrain technologies to serve the growing electric vehicle segment. GKN Automotive sustains its market position through advanced driveline systems and specialized EV solutions. Meanwhile, Eaton Corporation competes on the strength of its extensive portfolio in hydraulic and fluid conveyance couplings for both commercial and passenger vehicles.
An automotive coupling is a mechanical or fluid-based device designed to connect drive shafts or fluid lines within a vehicle's powertrain, driveline, or auxiliary systems. These components are engineered to transmit torque, accommodate misalignment, and manage vibration, with specifications defined by material strength and pressure-handling capabilities. While flexible couplings remain the largest product segment by volume, demand for fluid and electromagnetic couplings is rising in specialized applications like EV thermal management. The application landscape is shifting, with growth in the electric vehicle segment creating new requirements distinct from those in the mature commercial vehicle sector.
Regulatory frameworks such as the US EPA's emissions standards and the EU's vehicle General Safety Regulation (GSR) indirectly influence coupling design by setting targets for vehicle efficiency and safety. In parallel, China's GB standards for vehicle components and materials impose strict quality and performance benchmarks for market access. Suppliers must now strategically allocate R&D resources between optimizing components for legacy internal combustion engines and developing novel solutions for emerging electric and autonomous vehicle platforms.
Market Dynamics
The divergence in capital allocation between developing integrated electromechanical systems and manufacturing traditional mechanical components is the central force shaping the automotive coupling market, creating distinct competitive pressures for legacy and next-generation vehicle platforms.
Growth Catalysts
- EV Thermal Management:Demand for advanced fluid couplings is rising to support complex thermal management systems in electric vehicles, which require precise fluid conveyance for battery and powertrain cooling.
- Lightweight Composites:Innovations in composite materials enable the production of couplings that reduce vehicle weight and rotational inertia, improving efficiency and performance in both EV and high-performance combustion engine applications.
- Chinese Government Incentives:Subsidies and policy support for the new energy vehicle (NEV) sector in China create a concentrated and high-volume demand center for specialized EV-specific coupling technologies.
Market Restraints
- Material Cost Volatility:Price fluctuations in specialty alloys and composite resins create margin pressure and complicate long-term supply agreements for manufacturers of high-performance flexible and fluid couplings.
- Technical Performance Trade-offs:Developing couplings that simultaneously meet conflicting requirements for high torque capacity, extreme flexibility, and lightweight design remains a significant engineering constraint, particularly for advanced driveline systems.
- Legacy System Integration:The difficulty of integrating new, advanced coupling technologies into existing internal combustion engine vehicle platforms without extensive redesign limits their adoption rate in the large but mature commercial vehicle sector.
Strategic Opportunities
- Autonomous Vehicle Sensors:The need for ultra-reliable connections for steering and braking actuators in autonomous driving systems opens a new market for fail-safe electromechanical couplings with integrated diagnostics.
- Specialized Aftermarket Solutions:Developing specialized coupling kits for performance tuning and EV conversion of popular vehicle models presents an opportunity to serve a high-margin niche in the automotive aftermarket.
- Hydrogen Fuel Cell Systems:The emergence of hydrogen-powered vehicles creates demand for specialized fluid couplings capable of handling cryogenic fluids and high-pressure hydrogen gas safely and efficiently.
Industry Challenges
- R&D Resource Allocation:Suppliers face the difficult strategic challenge of allocating R&D investment between optimizing components for the vast legacy ICE market and developing novel solutions for the nascent but fast-growing EV sector.
- Skilled Engineering Talent:A scarcity of engineers with combined expertise in mechanical engineering, fluid dynamics, and power electronics hinders the development of next-generation integrated electromechanical coupling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Coupling Market |
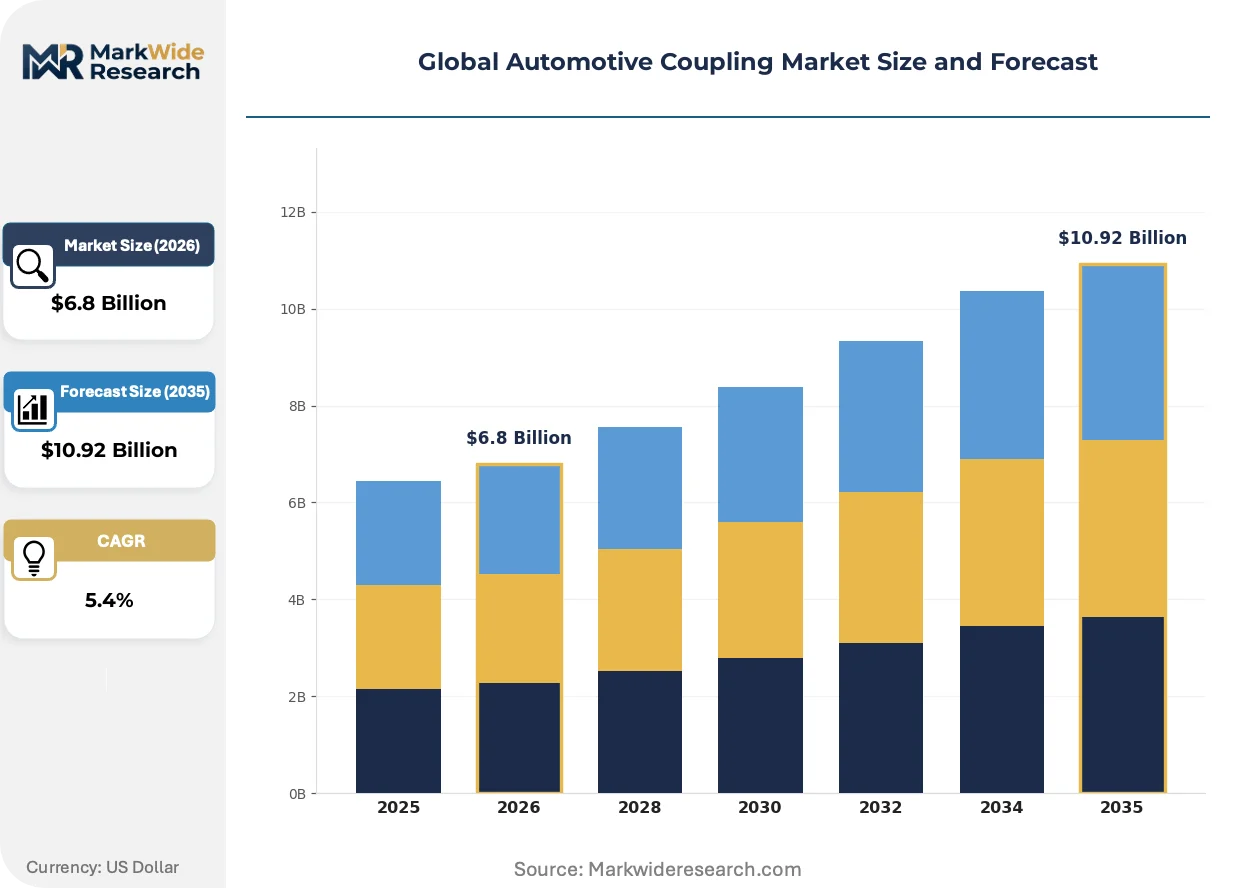
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Couplings, Flexible Couplings, Fluid Couplings, Magnetic Couplings, Torque Limiters Technology: Hydraulic, Pneumatic, Electromagnetic, Mechanical, Electromechanical Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles, Autonomous Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Suppliers, Maintenance Providers |
| Companies Covered | Dana Limited, BorgWarner Inc, Nexteer Automotive, Suddeutsche Gelenkscheibenfabrik GmbH & Co, Eaton Corporation, GKN Automotive, American Axle & Manufacturing, JTEKT Corporation, AAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Coupling Market Strategic Shifts & Innovations
A fundamental bifurcation defines the market's trajectory, splitting R&D and manufacturing focus between cost-optimized components for legacy vehicles and performance-driven, integrated systems for new electric and autonomous platforms. This divergence impacts every aspect of design and supply.
Advanced composite materials provide a pathway to producing lightweight couplings with high torsional stiffness. Performance-focused automotive segments, including electric supercars and motorsport, are early adopters of this technology. The use of these materials is bifurcating the supply chain into specialists for bespoke composite solutions and high-volume producers of traditional metallic couplings.
The European Union's General Safety Regulation (GSR) mandates advanced safety features, indirectly influencing coupling design for steering and braking systems. This regulation forces component suppliers to invest in technologies that support higher levels of reliability and fail-safe operation. Driveline and chassis system suppliers are most affected, accelerating the integration of diagnostic sensors into their coupling products.
Co-development partnerships are replacing traditional transactional purchasing for critical EV components. Vehicle manufacturers now engage coupling suppliers early in the design process to create integrated thermal and powertrain management solutions, bypassing conventional procurement channels. This collaborative model is most evident in the North American and European EV startup ecosystem.
Global Automotive Coupling Market Segmentation
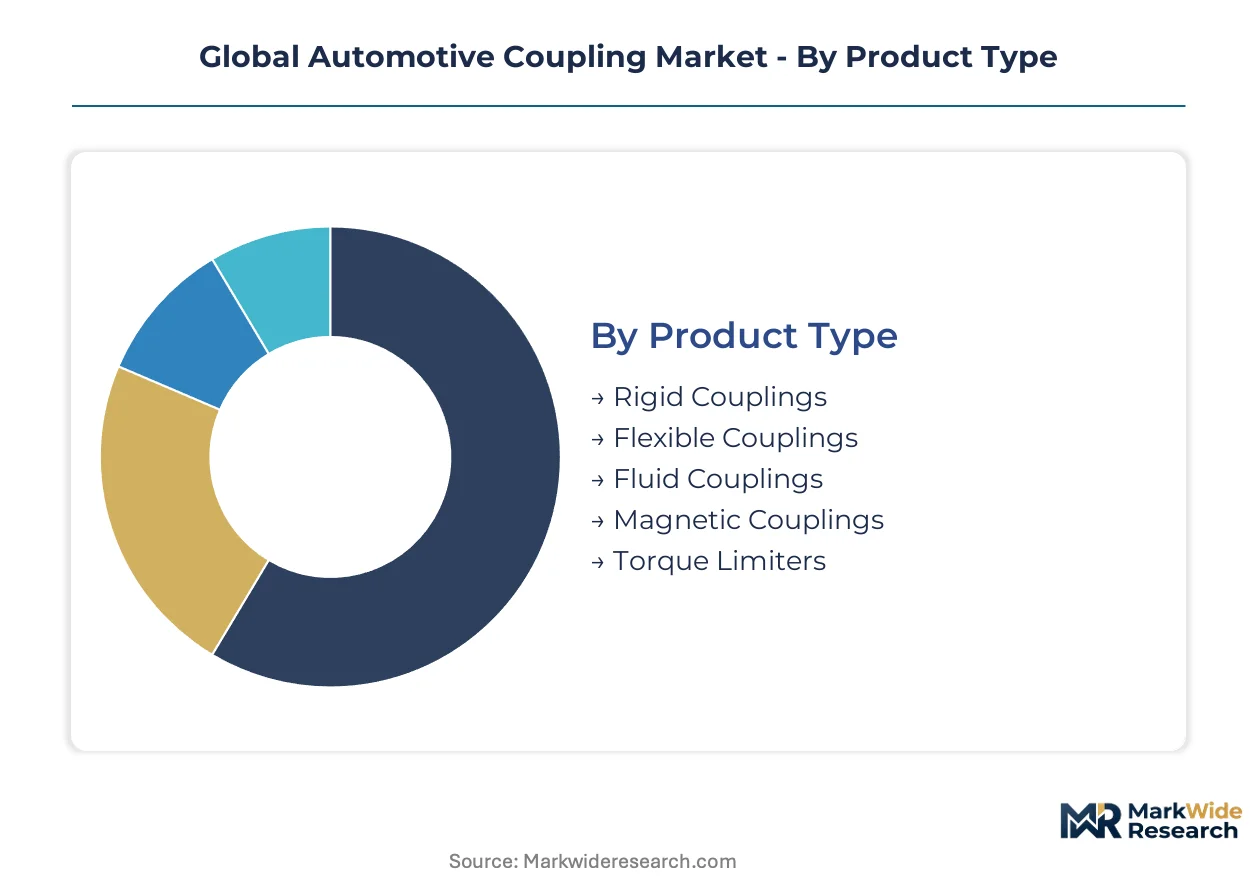
The segmentation of the global automotive coupling market provides a granular view of how distinct product types, technologies, applications, and end-users contribute to the market's overall structure and growth dynamics. Understanding these segments is crucial for identifying specific demand centers and technological shifts within the automotive industry.
Product Type:
The product type segmentation reveals how different coupling designs cater to varied regional demands, with some types dominating local manufacturing while others are integral to global supply chains.
- Flexible Couplings:These mechanical devices connect shafts, allowing for angular, parallel, and axial misalignment while dampening shock and vibration. Demand concentrates in established automotive manufacturing hubs like Germany and Japan, where powertrain refinement remains a design priority.
- Fluid Couplings:Fluid couplings transmit power through hydraulic oil, offering smooth power transfer and overload protection without mechanical contact. Their demand is rising significantly in China's new energy vehicle sector, driven by complex thermal management requirements for battery systems.
- Rigid Couplings:Rigid couplings provide precise shaft alignment and torque transmission, predominantly used in applications where no misalignment is tolerable.
- Magnetic Couplings:Magnetic couplings transmit torque without physical contact, offering wear-free operation for sealed systems, particularly in specialized pump applications.
- Torque Limiters:Torque limiters protect machinery from overload by disengaging power when a preset torque is exceeded, safeguarding driveline components.
Flexible Couplings commands the established base. The steepest expansion runs through Fluid Couplings.
Technology:
Technology segmentation illustrates the maturity curve of coupling solutions, from well-established mechanical systems to advanced integrated electromechanical offerings.
- Electromechanical:Electromechanical couplings integrate mechanical power transmission with electronic control and diagnostic capabilities, enabling precise system management. Demand is accelerating in North American and European EV startup ecosystems, where integrated thermal and powertrain solutions are paramount.
- Electromagnetic:Electromagnetic couplings use magnetic fields to engage and disengage power, offering precise control and rapid response times without mechanical wear. Their application is expanding in advanced driver-assistance systems and specialized EV thermal management.
- Hydraulic:Hydraulic couplings transmit power using fluid pressure, providing smooth engagement and overload protection, common in heavy-duty commercial vehicles.
- Pneumatic:Pneumatic couplings utilize compressed air for engagement and disengagement, favored in auxiliary systems requiring quick actuation.
- Mechanical:Mechanical couplings rely on direct physical contact to transmit torque, encompassing a wide range of designs for various power and alignment needs.
Mechanical technologies form the bedrock of current installations. Electromechanical solutions are gaining share fastest.
Application:
The application landscape for automotive couplings reflects distinct performance and reliability requirements driven by vehicle type and operational demands.
- Electric Vehicles:Couplings for electric vehicles must address new challenges like high-speed motor integration and complex thermal management for battery packs and power electronics. China's new energy vehicle market presents a concentrated demand for these specialized components.
- Autonomous Vehicles:Autonomous vehicles require ultra-reliable and fail-safe couplings for critical steering and braking actuators, often incorporating integrated diagnostics. This demand is emerging from advanced development programs in the US and Germany.
- Passenger Vehicles:Passenger vehicle couplings primarily connect driveline components and auxiliary systems, balancing performance with cost-effectiveness for mass production.
- Commercial Vehicles:Commercial vehicle applications prioritize durability and high torque capacity for heavy loads and continuous operation, often using robust mechanical and hydraulic designs.
- Off-Road Vehicles:Off-road vehicle couplings are engineered for extreme durability, shock absorption, and resistance to harsh environmental conditions, essential for demanding terrains.
Passenger Vehicles represent the largest volume segment. The Electric Vehicles segment is expanding most quickly.
End User:
End-user segmentation highlights the distinct roles various stakeholders play in the automotive coupling supply chain, from initial design to long-term vehicle maintenance.
- OEMs:Original Equipment Manufacturers integrate couplings directly into vehicle designs, increasingly engaging in co-development partnerships with suppliers for critical EV components. This trend is prominent in North American and European EV startup ecosystems.
- Tier-1 Suppliers:Tier-1 suppliers develop and produce complete coupling systems and modules, often acting as innovation partners for OEMs in areas like advanced driveline and thermal management systems. Companies like GKN Automotive exemplify this role.
- Aftermarket Suppliers:Aftermarket suppliers provide replacement couplings and performance upgrade kits, serving vehicle owners and independent repair shops globally.
- Vehicle Assemblers:Vehicle assemblers integrate pre-manufactured coupling components into the final vehicle assembly process, ensuring correct fit and function.
- Maintenance Providers:Maintenance providers offer repair and replacement services for couplings, ensuring the continued operational integrity of vehicles throughout their lifecycle.
OEMs drive initial design and integration. Tier-1 Suppliers are climbing the fastest in terms of innovation influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for advanced couplings is stronger in developed automotive markets like Germany, while cost optimization drives procurement in high-volume regions such as China. This reflects differing technological maturity. Manufacturers in these regions face distinct pressures.
China
China's automotive coupling demand is driven by the rapid expansion of its new energy vehicle sector and complex EV thermal management systems. The country's GB standards for vehicle components impose strict quality and performance benchmarks for market access. In the Yangtze River Delta, numerous EV manufacturing hubs concentrate specialized coupling suppliers for battery cooling and powertrain integration.
Germany
German demand for automotive couplings focuses on high-performance passenger vehicles and advanced driveline systems requiring precision and durability. The EU's General Safety Regulation (GSR) indirectly influences coupling design for steering and braking, mandating higher reliability. Bavaria remains a central hub for automotive engineering, fostering innovation in composite materials and integrated electromechanical solutions for premium brands.
United States
United States demand for automotive couplings is shaped by the emerging autonomous vehicle sector and a vibrant EV startup ecosystem. US EPA emissions standards indirectly influence lightweighting efforts, impacting material choices for driveline components. California's tech clusters, particularly around Silicon Valley, are driving requirements for ultra-reliable electromechanical couplings with integrated diagnostics.
Japan
Japanese automotive coupling requirements stem from a strong focus on hybrid vehicle technologies and continuous powertrain refinement. JIS standards for automotive components ensure stringent quality and performance benchmarks across the supply chain. The Chubu region, centered around Nagoya, houses major automotive manufacturers and their suppliers, emphasizing flexible couplings for vibration dampening.
India
India's automotive coupling market is experiencing growth from its expanding passenger vehicle sector and increasing EV adoption. The PLI scheme for automotive components encourages domestic manufacturing and technological upgrades for local suppliers. Chennai, a significant automotive manufacturing base, is seeing increased investment in components that support both traditional and new energy vehicle platforms.
Global Automotive Coupling Market Key Industry Players
Concentration sits with established Tier-1 automotive suppliers possessing extensive powertrain and driveline expertise. The market exhibits a tiered structure, ranging from global conglomerates to specialized component manufacturers. Three strategic archetypes include integrated system providers, material innovation specialists, and high-volume mechanical component producers. Dominant competitive moves involve strategic partnerships for EV integration, continuous portfolio diversification into advanced electromechanical solutions, and targeted capacity expansion in key growth regions like China. These actions aim to capture demand across both legacy and next-generation vehicle platforms.
Among the integrated system providers, BorgWarner Inc., a US-based corporation, represents a global player leveraging deep powertrain expertise to serve the evolving electric vehicle segment. GKN Automotive, a UK-based entity, exemplifies sustained market position through advanced driveline systems and specialized EV solutions, particularly for high-performance applications. Eaton Corporation, an Ireland-domiciled global power management company, anchors the segment with its extensive portfolio in hydraulic and fluid conveyance couplings for both commercial and passenger vehicles. These companies occupy positions at the forefront of technological integration and system-level innovation, often engaging in co-development partnerships with OEMs for critical EV components.
| Leading Market Players |
|---|
| Dana Limited |
| BorgWarner Inc |
| Nexteer Automotive |
| Suddeutsche Gelenkscheibenfabrik GmbH & Co |
| Eaton Corporation |
| GKN Automotive |
| American Axle & Manufacturing |
| JTEKT Corporation |
| AAM |
| Others |
Cost & Logistics Intelligence
Economies of scale in automotive component manufacturing significantly influence supply concentration, allowing for lower per-unit costs that establish competitive price floors. This dynamic shapes both procurement strategies and market entry barriers for new players.
Pricing Analysis
Customization-premium pricing distinguishes between bespoke solutions for performance segments and standard offerings for mass-market vehicles. The dominant pricing model remains per-unit transactional, often under long-term contracts with OEMs. Price differentiation stems from customization levels for specific vehicle platforms and the quality grade of materials used. Pricing pressure stems from high-volume OEM procurement in established segments. Commercial vehicle manufacturers exhibit the highest price sensitivity, while EV startup ecosystems prioritize performance and reliability, showing less price sensitivity for critical components.
Supply Chain Analysis
Inventory optimization and lead-time management are critical for automotive coupling suppliers, given the just-in-time demands of vehicle manufacturing. Geographic supply concentration includes China for high-volume EV components, Germany for precision engineering, and Japan for hybrid vehicle systems. The supply chain sources specialty alloys for mechanical couplings and composite resins for lightweight solutions. Material cost volatility presents a structural risk for manufacturers. Distribution runs through direct sales to OEMs and Tier-1 suppliers, who then integrate components into larger systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive coupling market is experiencing a cyclical recovery, driven by renewed investment in vehicle production after recent supply chain disruptions. This rebound is particularly evident in the new energy vehicle sector.
For Market Incumbents: Secure co-development partnerships with emerging EV startups to integrate advanced coupling solutions early in platform design. Diversify product portfolios into sophisticated electromechanical systems to counter the threat from novel EV architectures. Invest in R&D for power electronics integration and advanced materials. This strategy helps maintain relevance against specialized component manufacturers.
For New Entrants and Emerging Players: Lead with specialized aftermarket solutions for performance tuning and EV conversion kits, targeting niche enthusiast segments. Focus on developing components for hydrogen fuel cell systems, a nascent but high-growth white space. The EV conversion market in North America represents a penetrable segment. A go-to-market angle emphasizing enhanced vehicle performance and efficiency will resonate with early adopters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized material innovation firms with expertise in lightweight composites and advanced fluid dynamics. The market offers sustained long-term viability over the next 5-10 years, driven by the ongoing EV transition. Acquisition targets should possess unique intellectual property in electromechanical or magnetic coupling technologies. Watch for an increase in EV platform standardization as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-development with EV OEMs | Integrates coupling suppliers into next-generation vehicle platforms. |
| Investment in Composite Materials | Reduces vehicle weight and enhances performance for EV applications. |
| Capacity Expansion in China | Captures concentrated demand from the rapidly expanding NEV sector. |
| R&D for Hydrogen Systems | Positions companies for the emerging hydrogen fuel cell vehicle market. |
| Integration of Diagnostic Sensors | Meets reliability mandates for autonomous driving systems in vehicles. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier-1 procurement leads, material science R&D directors, and aftermarket distributors converged on the working assumptions for this study. Primary interviews were combined with secondary validation from vehicle production databases, automotive component trade statistics, and regulatory filings. This approach ensured comprehensive data collection. Bottom-up market sizing was triangulated with top-down industry reports to refine market estimates.
The segmentation dimensions modeled include product type, technology, application, end-user, and regional production clusters. An analytical framework projected market values and volumes across the analysis window. Compound annual growth rates were derived from historical trends and anticipated shifts in demand. Forecast inputs considered evolving EV adoption rates and the penetration of lightweight material solutions.
The analysis sits within stated boundaries; outcomes outside significant geopolitical trade policies or raw material supply shocks would require recalibration. Forecasts reflect assumptions regarding technological progression and regulatory stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Iran Automotive Lubricants Market