
 Automotive Carbon Fiber Components Market | 2026-2036
Automotive Carbon Fiber Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Fiber Components Market Insights
The automotive carbon fiber sector is rebalancing as premium OEMs pursue full-vehicle CFRP architectures while mainstream manufacturers adopt selective hybrid-metal-composite strategies for cost containment. Toray Industries dominates upstream PAN precursor supply and extends its position through captive carbon fiber capacity serving Japanese and European OEM programs. Hexcel Corporation competes in aerospace-grade fiber crossover applications, leveraging its resin chemistry expertise to qualify automotive-qualified prepreg systems. SGL Carbon anchors the European supply base with dedicated automotive preform capacity in Germany, specializing in large-series compression-molded components for BMW's electric architecture.
Automotive carbon fiber components are fiber-reinforced polymer structures manufactured from polyacrylonitrile-derived or pitch-based carbon fibers impregnated with thermoset or thermoplastic matrices, typically achieving tensile strengths exceeding 3,500 MPa at densities below 1.6 g/cm³. Their primary industrial purpose is mass reduction in vehicle structures where every kilogram eliminated translates to extended electric range or reduced emissions compliance burden. Structural Elements command the deepest margin pools as OEMs integrate carbon fiber into crash-critical battery enclosures and load-bearing chassis members. Electric Vehicles represent the fastest-growing application dimension as platform skateboard architectures create contiguous flat surfaces ideal for automated fiber placement. Prepreg manufacturing stages retain technology leadership in performance vehicle programs where autoclave-cured laminates deliver maximum specific stiffness.
The US EPA and NHTSA coordinate fuel economy and safety standards that directly incentivize lightweighting investments, while the EU's F-Gas Regulation and REACH framework govern precursor chemical handling and end-of-life recyclability for composite components. Japan's METI supports domestic carbon fiber supply chain resilience through industrial technology grants targeting automotive qualification timelines. Stakeholders must monitor regulatory convergence on end-of-life vehicle directives and recycled carbon fiber content mandates that will reshape material specifications and supplier qualification protocols.
Market Dynamics
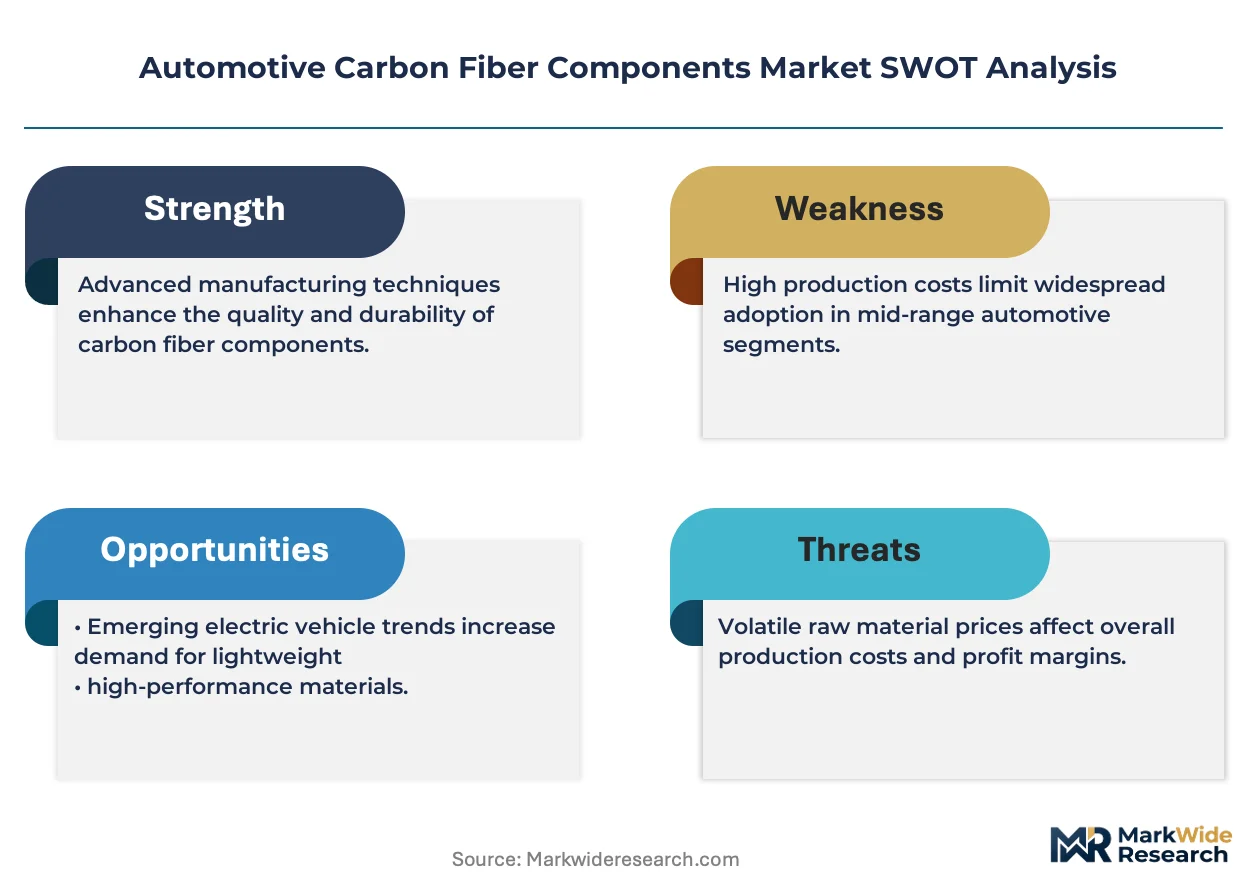
Electric vehicle platform architectures are compressing carbon fiber qualification timelines as OEMs race to reduce battery enclosure mass while maintaining crash integrity under tightened fleet emission rules.
Growth Catalysts
- EU F-Gas Regulation:Tightened fluorinated gas controls are pressuring automakers to eliminate heavier metal cooling systems in favor of lightweight composite battery housings.
- Skateboard platform proliferation:Flat underfloor EV architectures create contiguous surfaces ideal for automated fiber placement, accelerating adoption of thermoplastic composite floor pans.
- Japan METI industrial grants:Domestic supply chain resilience funding is compressing automotive qualification timelines for pitch-based carbon fiber precursors.
Market Restraints
- PAN precursor cost volatility:Polyacrylonitrile feedstock prices swing with acrylonitrile monomer supply, locking composite component margins below 15% for non-integrated converters.
- Oligopolistic fiber supply:Three Japanese and German producers control 80% of aerospace-qualified tow capacity, creating allocation risk during automotive program ramp-ups.
- Thermoset recycling dead-ends:Cross-linked epoxy matrices lack scalable depolymerization pathways, exposing OEMs to EU end-of-life vehicle directive penalties.
Strategic Opportunities
- Recycled fiber qualification:Pyrolysis-recovered carbon fiber from aerospace scrap is achieving automotive structural specifications at 40% of virgin cost.
- India PLI scheme alignment:Production-linked incentives for advanced chemistry cell manufacturing are creating localized demand for composite battery module housings.
- Thermoplastic tape welding:Laser-assisted consolidation of unidirectional tapes is enabling sub-60-second cycle times for A-pillar reinforcements.
Industry Challenges
- Automated fiber placement programming:Path-planning for complex double-curvature surfaces requires specialized CAM expertise scarce outside aerospace supply chains.
- Multi-material corrosion management:Galvanic coupling between carbon fiber and aluminum subframes demands isolation systems adding 8-12% assembly cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Fiber Components Market |
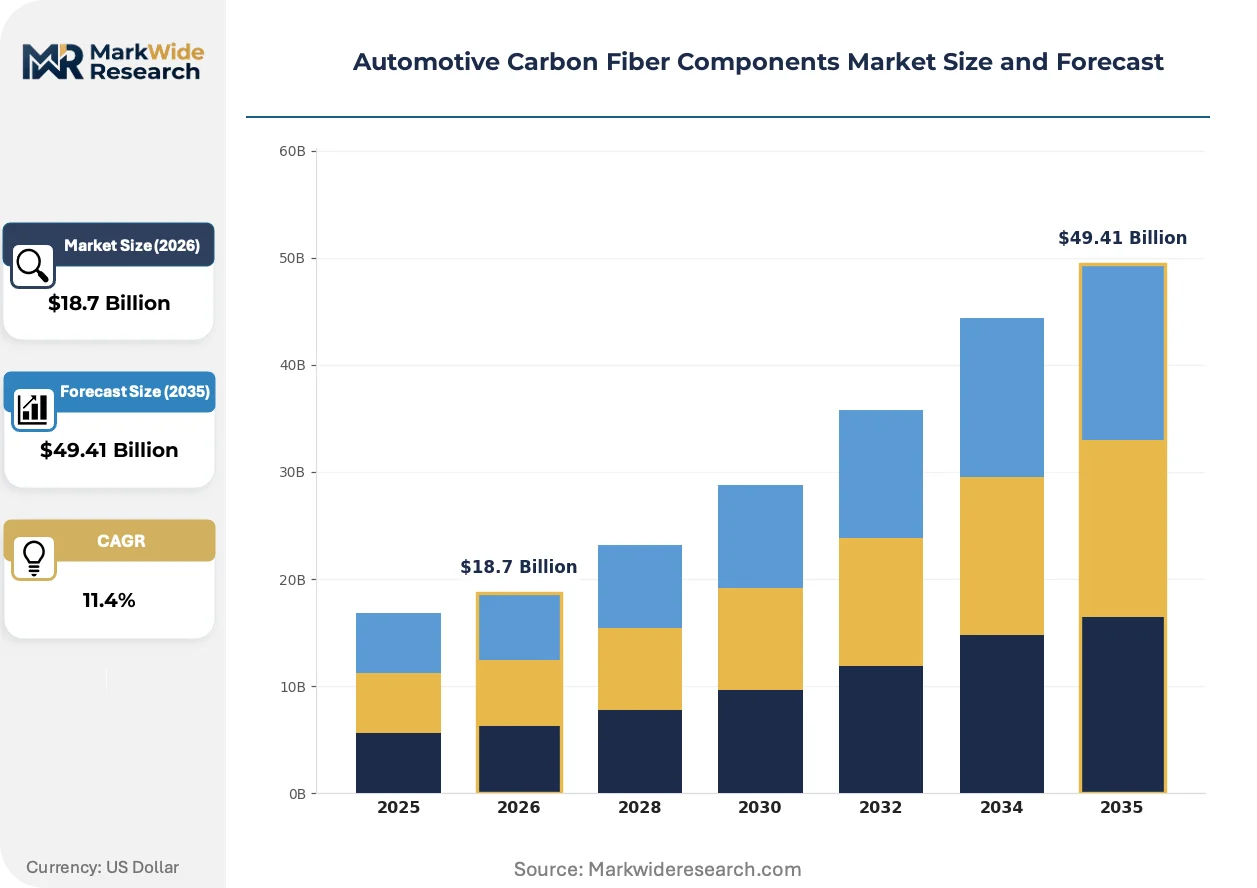
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Panels, Interior Components, Chassis Parts, Structural Elements End User: OEMs, Aftermarket Suppliers, Custom Vehicle Builders, Automotive Startups Manufacturing Stage: Prepreg, Wet Layup, Resin Transfer Molding, Compression Molding Application: Performance Vehicles, Luxury Cars, Electric Vehicles, Racing Vehicles |
| Companies Covered | Toray Industries Inc., Hexcel Corporation, SGL Carbon, Teijin Limited, Mitsubishi Chemical Corporation, Hyosung Advanced Materials, DowAksa Advanced Composites, Nippon Graphite Fiber Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Fiber Components Market Trends and Innovations
Manufacturing process innovation is compressing the cost gap between stamped metal and composite structures, enabling migration from cosmetic trim to primary load-bearing applications.
High-speed resin transfer molding is decentralizing carbon fiber component production from centralized autoclave facilities to regional stamping-plant adjacent cells. Tier-1 suppliers in Germany and the United States are adopting out-of-autoclave processes for battery enclosure side rails, cutting capital intensity by 60% versus traditional prepregs. This geographic diffusion is enabling just-in-sequence delivery to EV assembly lines without intercontinental logistics exposure.
REACH chemical authorization is forcing reformulation of epoxy hardener systems across European automotive programs. ECHA's sunset date for nonyl phenol derivatives has triggered supplier qualification of anhydride-cured alternatives with equivalent Tg performance. Battery enclosure manufacturers serving BMW and Polestar programs are absorbing 18-month requalification timelines to maintain EU market access.
Fleet procurement contracts are consolidating carbon fiber buying power among EV-dedicated platform engineers. Traditional commodity purchasing departments are ceding specification authority to vehicle architecture teams who bundle composite content across body-in-white, closure panels, and chassis members. This concentration is most pronounced in California and Shanghai, where zero-emission vehicle mandates have created dedicated lightweighting budget pools outside legacy cost targets.
Automotive Carbon Fiber Components Market Segmentation
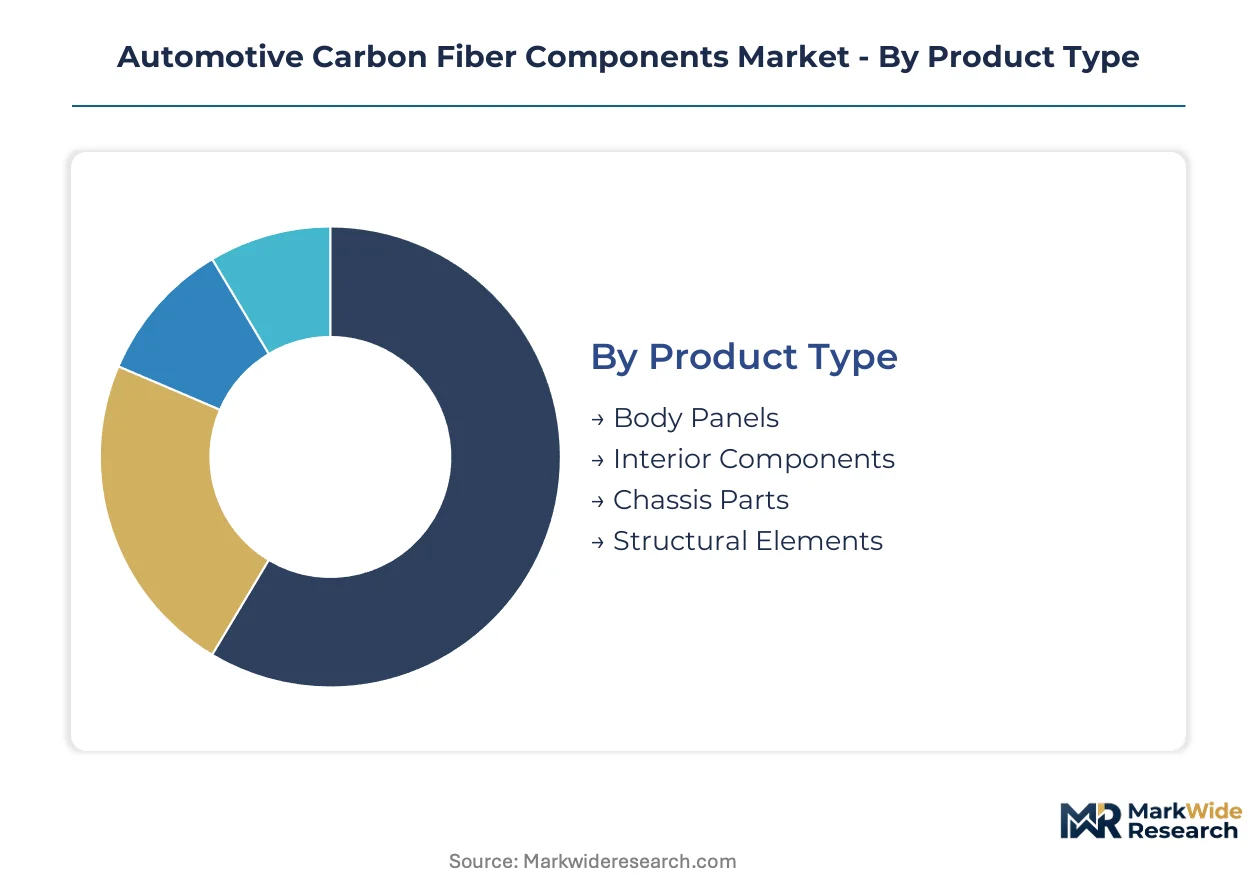
Segmentation in automotive carbon fiber reveals how material specifications, manufacturing economics, and end-use requirements fragment supply chains. Each dimension governs distinct qualification protocols, capital intensity thresholds, and customer procurement behaviors that shape competitive positioning.
Product Type:
Supply concentration among Japanese and German fiber producers directly dictates which product categories achieve scalable automotive qualification first.
- Structural Elements:Crash-critical battery enclosures and load-bearing chassis members utilize high-modulus PAN-based prepregs with tensile strengths exceeding 3,500 MPa. BMW and Polestar electric architectures in Germany and Sweden concentrate demand here, driven by EU fleet emission compliance deadlines that penalize overweight vehicles.
- Chassis Parts:Suspension links, subframes, and steering knuckles employ braided carbon fiber overmolded with thermoplastic matrices for impact absorption. Japanese OEM programs through Toyota and Honda anchor volume, with METI industrial grants accelerating qualification timelines for domestic supply chain security.
- Body Panels:Hoods, roofs, and fenders achieve Class-A surfaces through compression-molded SMC formulations. US EPA fuel economy standards incentivize adoption on performance variants of domestic full-size trucks.
- Interior Components:Dashboard carriers, seat shells, and trim panels utilize recycled fiber blends to meet EU end-of-life vehicle directive recyclability mandates. German premium OEMs specify these for cockpit modules.
Structural Elements absorb the bulk of installed capacity; Electric Vehicles within Application is expanding most quickly across all product categories.
End User:
Customer type determines specification authority, with platform engineering teams displacing traditional commodity purchasing in high-growth segments.
- OEMs:Vehicle manufacturers with dedicated EV architectures bundle composite content across body-in-white, closures, and chassis. California and Shanghai zero-emission mandates have created lightweighting budget pools outside legacy cost targets for these buyers.
- Automotive Startups:EV-native companies without metal stamping heritage specify full-vehicle CFRP architectures from inception. Rivian and Lucid programs in the United States qualify structural battery enclosures through direct fiber placement partnerships.
- Custom Vehicle Builders:Low-volume producers of restomod and coachbuilt vehicles source hand-laid prepregs for aesthetic panels. Italian and British specialist manufacturers dominate this niche with heritage marque licensing.
- Aftermarket Suppliers:Tuners and upgrade specialists provide bolt-on aerodynamic packages using wet layup methods. German TÜV certification requirements govern structural integrity claims for road-legal components.
OEM procurement absorbs the majority of qualified fiber supply; Automotive Startups are climbing the fastest as a customer category.
Manufacturing Stage:
Process selection locks in capital requirements, cycle times, and geographic deployment patterns for component supply.
- Prepreg:Autoclave-cured unidirectional tapes deliver maximum specific stiffness for motorsport and aerospace-crossover applications. Japanese suppliers Toray and Mitsubishi Chemical dominate aerospace-qualified tow capacity feeding this stage.
- Resin Transfer Molding:High-pressure injection of thermoset resins into closed molds enables sub-10-minute cycle times for structural battery enclosure side rails. Out-of-autoclave adoption in Germany and the United States cuts capital intensity versus traditional prepregs.
- Compression Molding:Matched-die forming of SMC and BMC compounds produces Class-A body panels at automotive-scale volumes. BMW's Leipzig and Spartanburg plants deploy this for roof and hood assemblies.
- Wet Layup:Manual resin impregnation of dry fiber fabrics persists in prototype, repair, and custom vehicle applications. Labor intensity constrains this method to volumes below 1,000 units annually.
Resin Transfer Molding is gaining share fastest as OEMs compress EV qualification timelines; Prepreg retains the deepest margin pools.
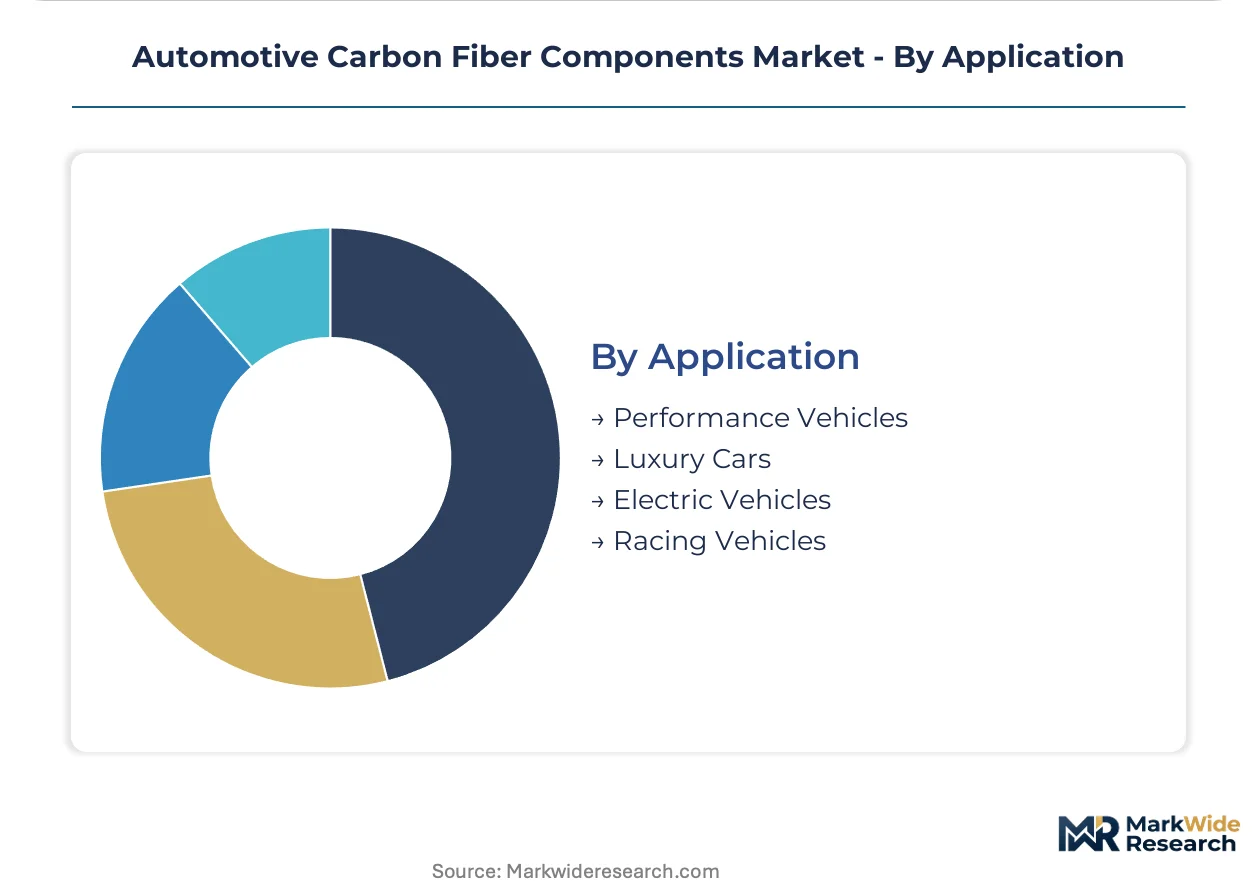
Application:
End-use performance requirements create tiered material specifications that cascade back to precursor chemistry and fiber modulus selection.
- Electric Vehicles:Skateboard platform architectures generate contiguous flat surfaces ideal for automated fiber placement of floor pans and battery enclosures. EU F-Gas Regulation pressures elimination of heavy metal cooling systems in favor of lightweight composite housings.
- Performance Vehicles:Track-focused road cars specify aerospace-grade intermediate-modulus fibers for torsional rigidity in monocoque tubs. Porsche and Ferrari programs in Germany and Italy qualify these through multi-year durability testing protocols.
- Luxury Cars:Comfort-oriented flagship sedans utilize carbon fiber for vibration damping and acoustic isolation in structural members. Mercedes-Benz S-Class and BMW 7-Series integrate these in roof bows and parcel shelves.
- Racing Vehicles:FIA-homologated prototypes and GT3-category cars consume ultra-high-modulus pitch-based fibers at premium pricing. Japanese suppliers supply this segment through dedicated motorsport divisions.
Electric Vehicles command the steepest expansion trajectory; Performance Vehicles retain the highest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European automotive carbon fiber demand through BMW's dedicated CFRP production campus and Porsche's motorsport composite development center.
Germany
BMW's Leipzig and Spartanburg-adjacent facilities consume high-modulus prepregs for i-series battery enclosures and carbon core passenger cells. The EU F-Gas Regulation pressures elimination of metal cooling systems in favor of lightweight composite housings. Bavaria's Munich-Stuttgart corridor concentrates Toray-SGL joint development programs for automated fiber placement.
United States
EPA and NHTSA coordinated fuel economy standards incentivize lightweighting investments across Detroit Three EV truck platforms. Rivian and Lucid programs in California qualify structural battery enclosures through direct fiber placement partnerships. The Pacific Northwest hosts Hexcel's aerospace-grade fiber crossover qualification labs serving automotive programs.
Japan
Toyota and Honda anchor domestic demand for braided carbon fiber chassis components through METI industrial technology grants. METI funding compresses automotive qualification timelines for pitch-based carbon fiber precursors. Nagoya's Chubu region concentrates Mitsubishi Chemical and Teijin precursor-to-component integrated supply.
China
CATL and BYD battery enclosure programs drive thermoplastic composite floor pan adoption for domestic EV platforms. MIIT dual carbon goals accelerate lightweighting mandates in NEV subsidy qualification criteria. Yangtze River Delta manufacturing clusters near Shanghai deploy high-speed resin transfer molding for regional OEM supply.
South Korea
Hyundai-Kia's E-GMP platform generates demand for carbon fiber-reinforced polymer battery protection structures. MFDS chemical handling frameworks govern precursor import and composite waste management protocols. Busan-Ulsan heavy industry zones host Hyosung Advanced Materials' tow capacity expansion serving domestic EV programs.
Automotive Carbon Fiber Components Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fiber modulus tiers and aerospace qualification heritage. Three Japanese and German producers control aerospace-qualified tow capacity, creating allocation bottlenecks during automotive program ramp-ups. The vendor base stratifies into PAN precursor specialists, composite converters, and full-stack integrated suppliers. Dominant competitive moves include backward integration into precursor production and geographic co-location with OEM EV platform engineering centers.
Among Japanese fiber producers, Toray Industries Inc., Teijin Limited, and Mitsubishi Chemical Corporation occupy positions spanning PAN precursor through prepreg supply. These Tokyo and Osaka-headquartered entities exemplify the integrated archetype controlling upstream chemistry and downstream automotive qualification timelines. Their collective capacity allocation decisions ripple through European and North American converter supply chains.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Hexcel Corporation |
| SGL Carbon |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Hyosung Advanced Materials |
| DowAksa Advanced Composites |
| Nippon Graphite Fiber Corporation |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Acrylonitrile monomer spot pricing cascades through PAN precursor contracts into three-tier automotive fiber quotations, compressing margins for non-integrated converters while aerospace-qualified tow commands allocation premiums. Japanese and German producers leverage captive precursor capacity to buffer automotive buyers from feedstock volatility, locking in long-term offtake structures that insulate EV platform budgets.
Pricing Analysis
Yield-per-kilogram pricing anchors composite component valuations, with structural battery enclosures commanding premiums tied to crash-test certification throughput. Three-tier pricing structure across aerospace-qualified, automotive-structural, and industrial-grade fiber tiers separates BMW and Polestar programs from commodity SMC applications. Cost compression in standard-modulus tow is intensifying because Korean and Chinese capacity additions loosen aerospace allocation bottlenecks. Aftermarket tuners exhibit acute price sensitivity, while OEM platform engineering teams absorb specification premiums for qualified prepreg systems.
Supply Chain Analysis
Aerospace-to-automotive qualification gating restricts supply base expansion, with Toray, Teijin, and Mitsubishi Chemical holding effective veto over new program approvals. Manufacturing concentrates in Japan, Germany, and the United States, where precursor-to-component integrated supply chains serve BMW Leipzig, Porsche Weissach, and Rivian Normal facilities. The supply chain draws from acrylonitrile monomer, pitch-based precursor, and epoxy resin inputs. Single-source vulnerability in aerospace-qualified tow capacity exposes automotive ramp-ups to allocation risk during defense procurement surges. Distribution runs through Tier 1 converter networks co-located with OEM EV platform engineering centers in Stuttgart, Nagoya, and Detroit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive carbon fiber operates as a supply-constrained market where oligopolistic fiber allocation props pricing power for integrated Japanese and German incumbents.
For Market Incumbents: Deploy captive precursor capacity expansion as the primary defensive lever. Lock in multi-year offtake agreements with Rivian and Lucid before Korean tow capacity achieves automotive qualification. Absorb 18-month REACH requalification costs for anhydride-cured epoxy systems to maintain EU market access against emerging thermoplastic competitors. For New Entrants and Emerging Players: Thermoplastic tape welding expertise offers entry into A-pillar reinforcement programs where sub-60-second cycle times displace thermoset incumbent. Target Indian PLI-aligned battery enclosure contracts where localized composite housing demand outpaces qualified converter supply. Pursue direct fiber placement partnerships with EV-native startups lacking metal stamping heritage. For Investors and Strategic Acquirers: The window for entry favors pyrolysis-recovered carbon fiber specialists achieving automotive structural specifications at virgin cost discounts. Long-term viability hinges on EU end-of-life vehicle directive enforcement timelines that mandate recycled content minimums. Watch for ECHA sunset date acceleration on nonyl phenol derivatives as inflection trigger for incumbent reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray and Mitsubishi Chemical lock in margin capture against acrylonitrile volatility. |
| Thermoplastic Composite Floor Pan Adoption | BMW and Polestar skateboard architectures enable automated fiber placement cycle time compression. |
| REACH Anhydride-Cured Epoxy Requalification | Battery enclosure manufacturers absorb 18-month timelines to maintain EU F-Gas Regulation compliance. |
| Pyrolysis-Recovered Fiber Qualification | Aerospace scrap recovery achieves automotive structural specifications at 40% virgin fiber cost. |
| Geographic Co-location with EV Platforms | SGL Carbon's Moses Lake facility anchors Pacific Northwest supply to Rivian and Lucid programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving OEM platform engineers, Tier 1 converter procurement leads, precursor plant managers, and ECHA regulatory affairs specialists. Bottom-up fiber consumption estimates triangulated against top-down vehicle production forecasts from IHS Markit registration databases and ACC automotive composite shipment reports.
Production volume and value outputs reconciled supply-side capacity announcements with demand-side platform engineering budgets across the projection horizon. Segmentation modeling spanned product type, manufacturing stage, propulsion architecture, and regional production cluster dimensions. CAGRs derived from installed capacity ramp schedules against EU fleet emission compliance deadlines and EPA fuel economy standard phase-ins.
Several conditions sit outside the modeled scope, including defense procurement allocation shocks, breakthrough thermoplastic recycling economics, and unilateral tariff restructuring. Forecasts reflect assumptions on qualification timeline compression and precursor cost pass-through structures. A model refresh is warranted upon material change in ECHA chemical authorization timelines or METI industrial grant disbursement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
China Automotive Composites Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market