
 West Africa Platform Supply Vessel (PSV) Market | 2026-2036
West Africa Platform Supply Vessel (PSV) Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Platform Supply Vessel (PSV) Market Analytics
Project finance through bareboat charter arrangements is fragmenting competitive access across the West Africa PSV fleet. Bourbon leverages its integrated vessel management platform to sustain long-term contracts with international oil companies. SeaForce Shipping Company Ltd anchors its position through specialized crew boat operations in Nigerian waters. Starzs Marine and Engineering Limited competes by dominating maintenance-intensive contracts for aging offshore infrastructure.
A Platform Supply Vessel is a dynamically positioned offshore support craft typically measuring 65 to 95 meters in length, with deck capacities exceeding 1,000 square meters and cargo tanks for fuel, water, drilling fluids, and dry bulk. These vessels serve as critical logistics links between onshore supply bases and fixed or floating production facilities. Anchor Handling vessels command premium day rates due to dual-capability requirements in deepwater mooring operations. Small and Medium PSV categories retain structural importance in shallow-water Nigerian and Angolan fields where draft restrictions limit larger hull deployment. ROV Support configurations represent the fastest-growing vessel type as subsea inspection demands intensify across maturing West African oil provinces.
Nigeria's Maritime Administration and Safety Agency enforces cabotage compliance requirements that reserve coastal vessel employment for domestically registered operators. The International Maritime Organization's Energy Efficiency Existing Ship Index shapes retrofit investment decisions across aging West African fleets. Ghana's Petroleum Commission mandates local content participation thresholds that restructure contractor eligibility for offshore logistics awards. Stakeholders must monitor how regional refining capacity developments alter fuel supply logistics and vessel routing economics across the Gulf of Guinea corridor.
Market Dynamics
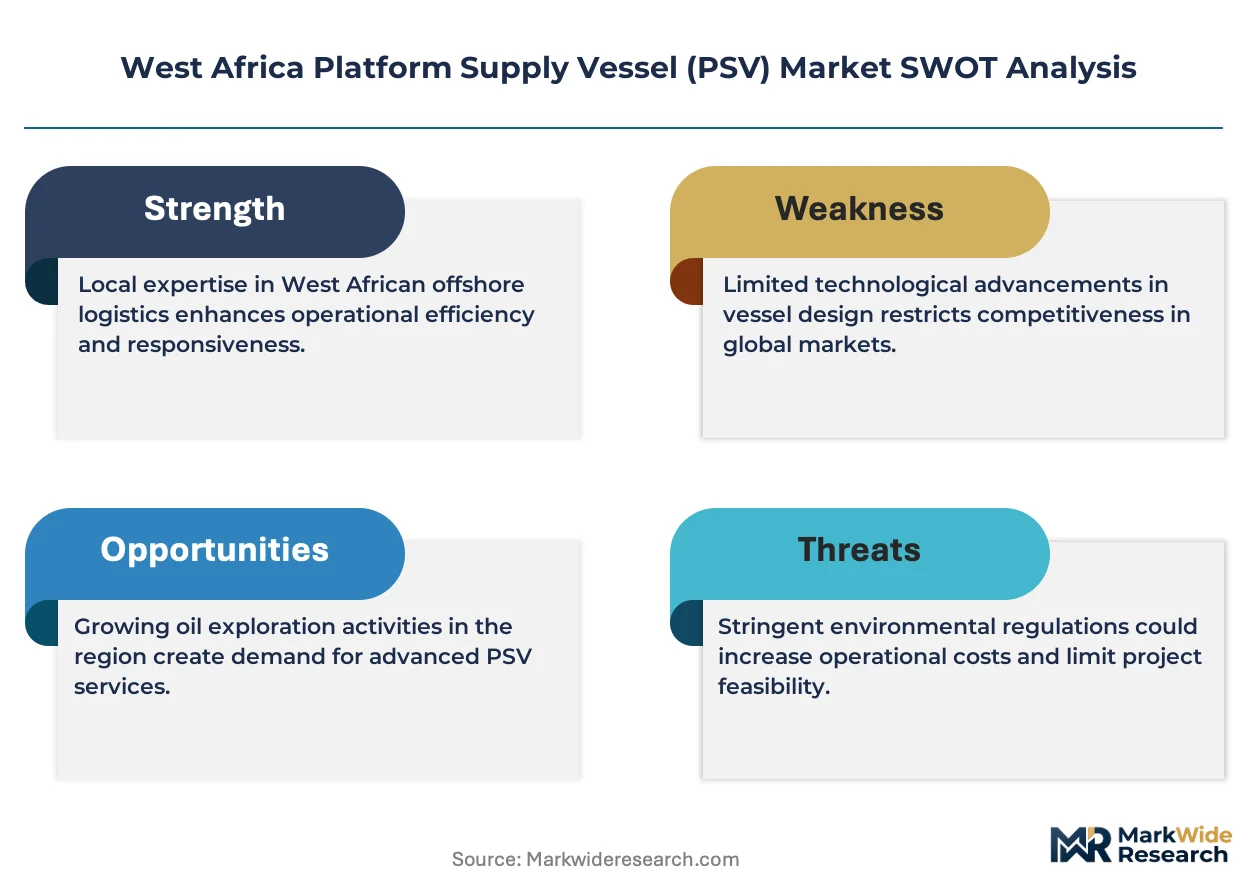
The International Maritime Organization's Energy Efficiency Existing Ship Index is compressing charter economics for aging Platform Supply Vessels across the Gulf of Guinea, forcing operators to accelerate fleet renewal decisions or exit Nigerian and Ghanaian waters entirely.
Growth Catalysts
- Deepwater Production Tiebacks:Nigerian deepwater field developments require sustained logistics support for subsea infrastructure, extending contract durations for PSV operators with dynamic positioning capabilities.
- NIMASA Cabotage Enforcement:Nigeria's Maritime Administration and Safety Agency cabotage compliance requirements reserve coastal vessel employment for domestically registered operators, creating protected demand pools for local fleet owners.
- Subsea Inspection Intensification:ROV Support vessel configurations are capturing expanded deployment as maturing West African oil provinces require continuous subsea asset monitoring and intervention.
Market Restraints
- Marine Fuel Price Volatility:Low-sulfur marine gasoil price swings at Lagos and Takoradi bunkering hubs compress operating margins for vessels without fuel-efficient hull designs or hybrid propulsion.
- European Shipyard Concentration:Newbuild PSV construction concentrates in Norwegian and Dutch yards, exposing West African operators to euro-denominated contract exposure and extended delivery timelines.
- Emissions Retrofit Burden:The IMO's Energy Efficiency Existing Ship Index mandates capital-intensive engine and hull modifications for pre-2013 vessels, stranding older tonnage in Nigerian coastal trades.
Strategic Opportunities
- Ghanaian Local Content Thresholds:Ghana's Petroleum Commission mandates for local content participation restructure contractor eligibility, creating entry pathways for indigenous vessel operators with Ghanaian registry.
- Hybrid-Electric Convergence:Battery-hybrid propulsion systems combined with shore power connectivity at Takoradi and Lagos supply bases enable fuel consumption reductions that command premium charter rates.
- Angolan Shallow-Water Revival:Small and Medium PSV categories retain structural importance in Angolan fields where draft restrictions limit larger hull deployment, preserving niche demand for specialized operators.
Industry Challenges
- Dynamic Positioning Officer Scarcity:Certified DPO availability constrains vessel utilization rates, as Nigerian maritime academies produce insufficient qualified officers for expanding fleet requirements.
- Legacy Vessel Integration Complexity:Aging PSVs with single-fuel diesel architectures face technical barriers when retrofitting for biofuel blends or hybrid-electric systems, complicating compliance pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Platform Supply Vessel (PSV) Market |
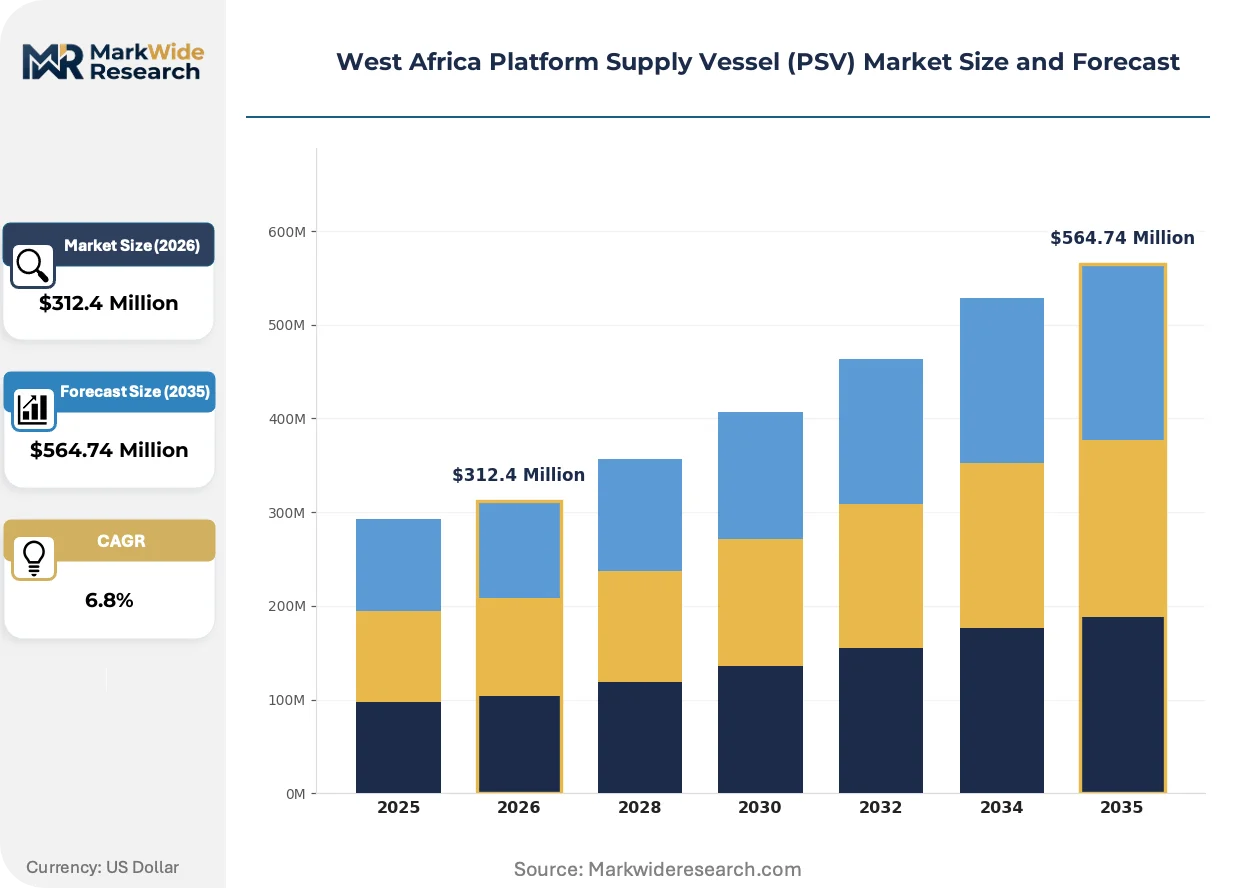
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Anchor Handling, ROV Support, Crew Boats, Utility Vessels Service Type: Logistics Support, Transport Services, Supply Operations, Maintenance Services End User: Oil & Gas Companies, Offshore Contractors, Mining Firms, Energy Producers Size: Small PSV, Medium PSV, Large PSV, Ultra-large PSV |
| Companies Covered | SeaForce Shipping Company Ltd, Petromarine Nigeria Limited, Starzs Marine and Engineering Limited, GE Offshore Marine Services S.L, Aquashield Oil & Marine Services Limited, African Offshore Services, Team Offshore Nigeria Limited, Bourbon, Blue Sea Marine Services, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Platform Supply Vessel (PSV) Market Evolving Landscape
Fuel transition pathways and digital vessel management systems are restructuring competitive differentiation across West African offshore logistics, compressing the operational lifespan of conventional tonnage while elevating charter rate premiums for compliant assets.
Battery-hybrid propulsion architectures with shore power connectivity are rendering obsolete single-fuel diesel PSVs in Nigerian deepwater charter markets. International oil companies now specify hybrid-capable vessels in new tender documentation, compressing day rate achievable by conventional tonnage and accelerating scrapping decisions for pre-2010 builds.
NIMASA's enforcement of revised Safety of Life at Sea protocols for domestic fleet registration is tightening vessel eligibility for Nigerian cabotage contracts. Operators must demonstrate compliance with updated firefighting and lifesaving equipment standards, redirecting capital toward safety system upgrades rather than capacity expansion.
Long-term bareboat charter arrangements with embedded fuel price adjustment mechanisms are displacing traditional spot market fixtures in Ghanaian and Nigerian waters. Integrated vessel management platforms now bundle maintenance, crewing, and regulatory compliance into single-contract structures, concentrating procurement authority with major international oil companies and marginalizing smaller independent operators.
West Africa Platform Supply Vessel (PSV) Market Segmentation
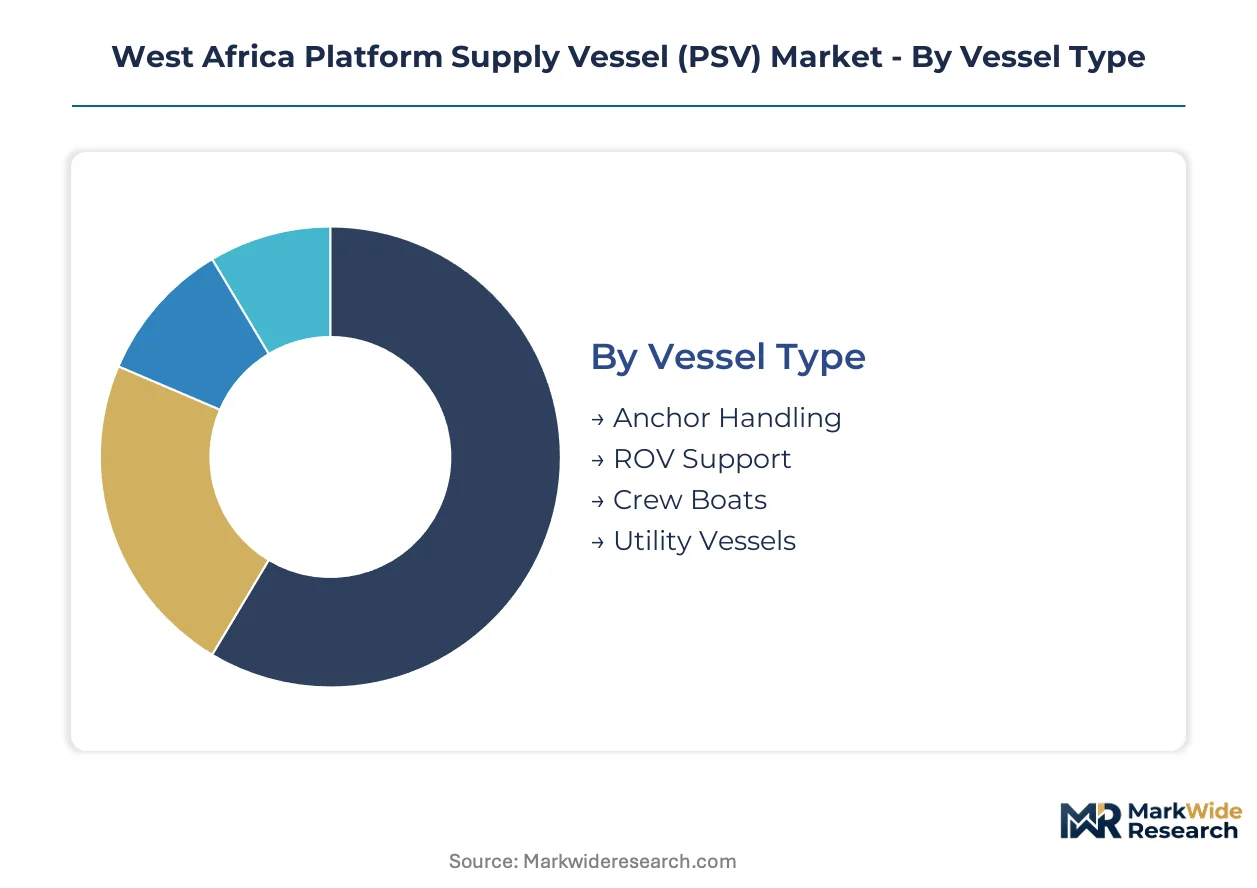
Vessel classification across West African waters determines charter rate structures, regulatory compliance burdens, and operational flexibility in Nigerian and Ghanaian offshore logistics. Distinct segment boundaries reflect technical capabilities, draft limitations, and contract duration patterns that operators must navigate.
Vessel Type:
Mature categories dominate current fleet deployment while emerging configurations capture premium day rates through specialized functionality.
- Anchor Handling:Dual-capability vessels combine mooring operations with supply functions, requiring enhanced bollard pull ratings and winch systems. Nigerian deepwater fields concentrate demand for these assets where floating production facility installation demands sustained station-keeping support.
- ROV Support:Configured with moon pools, crane systems, and subsea equipment storage, these vessels enable continuous inspection and intervention across maturing West African oil provinces. Ghanaian operators specify ROV-capable hulls in new tenders as subsea infrastructure ages.
- Crew Boats:Fast personnel transport vessels bridge onshore supply bases with offshore installations, concentrating in Nigerian cabotage trades.
- Utility Vessels:General-purpose platforms handle non-specialized cargo movements in shallow-water Angolan and Nigerian fields.
Anchor Handling retains volume leadership; ROV Support holds the steepest expansion curve.
Service Type:
Cost tier differentiation separates commodity logistics from high-margin technical services requiring specialized equipment and certification.
- Logistics Support:Comprehensive supply chain coordination spanning procurement, warehousing, and vessel scheduling. Nigerian international oil company contracts bundle these services into multi-year agreements with embedded fuel adjustment mechanisms.
- Transport Services:Point-to-point cargo movement between shore bases and offshore facilities, capturing standard day rate structures without technical premium.
- Supply Operations:Just-in-time delivery of drilling fluids, cement, and consumables to floating production units. Ghanaian deepwater developments require 24/7 supply continuity with dynamic positioning capabilities.
- Maintenance Services:Technical interventions including equipment repair, spare parts delivery, and offshore workshop support. Aging Nigerian infrastructure expands demand for maintenance-intensive contracts.
Logistics Support commands the largest contract value; Maintenance Services is climbing the fastest as offshore assets mature.
End User:
Customer type segmentation reveals divergent procurement authority, contract duration preferences, and local content compliance requirements.
- Oil & Gas Companies:International oil majors and national oil companies operate integrated procurement platforms. Nigerian deepwater operators specify vessel capabilities in master service agreements spanning five to ten years.
- Offshore Contractors:Engineering, procurement, and construction firms charter vessels for project-specific durations. Ghanaian local content thresholds restructure contractor eligibility for these awards.
- Mining Firms:Offshore mineral exploration operators require specialized logistics for seabed mining support vessels.
- Energy Producers:Renewable energy developers deploying floating offshore wind infrastructure in emerging West African markets.
Oil & Gas Companies retain procurement dominance; Energy Producers are gaining share fastest through offshore wind pre-development activity.
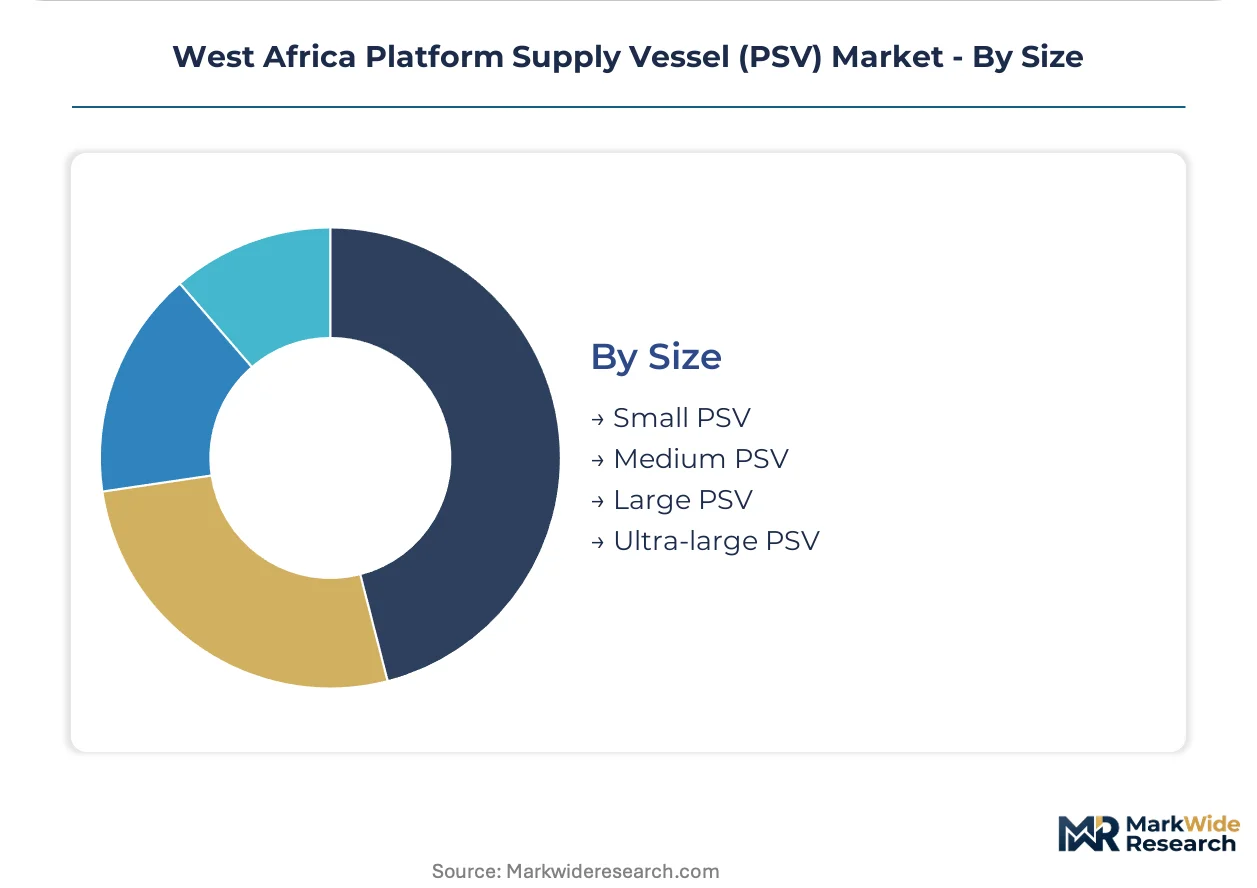
Size:
Volume concentration across hull dimensions reflects draft restrictions, deck capacity requirements, and fuel efficiency trade-offs in Gulf of Guinea operations.
- Small PSV:Compact hulls under 70 meters navigate shallow-water Nigerian and Angolan fields where port infrastructure limits larger vessel access. Draft restrictions preserve structural demand for these categories.
- Medium PSV:Versatile platforms balancing cargo capacity with maneuverability. Ghanaian and Nigerian coastal trades favor these vessels for mixed cargo profiles.
- Large PSV:Extended deck areas exceeding 1,000 square meters accommodate bulk liquid and dry cargo for deepwater production support.
- Ultra-large PSV:Maximum capacity hulls serve floating production storage and offloading units with sustained high-volume logistics requirements.
Medium PSV retains deployment frequency leadership; Ultra-large PSV shows the steepest expansion trajectory as Nigerian deepwater fields scale production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
International oil companies operating Nigerian deepwater fields drive regional procurement concentration, with Ghanaian offshore contractors and Angolan shallow-water operators forming secondary demand clusters across the Gulf of Guinea corridor.
Nigeria
Deepwater production tiebacks at Bonga and Egina fields sustain demand for large PSVs with dynamic positioning capabilities. NIMASA cabotage enforcement reserves coastal vessel employment for domestically registered operators, creating protected demand pools for local fleet owners. Lagos and Port Harcourt anchor vessel supply base operations, with Lekki Free Trade Zone emerging as a bunkering and maintenance hub.
Ghana
Jubilee and TEN field developments require continuous logistics support for floating production facilities. Ghana's Petroleum Commission mandates local content participation thresholds that restructure contractor eligibility for offshore logistics awards. Takoradi serves as the primary supply base, with hybrid-electric vessel trials underway at its expanded port facilities.
Angola
Shallow-water field revival programs preserve structural demand for small and medium PSV categories where draft restrictions limit larger hull deployment. The country's petroleum regulator enforces maritime safety standards that accelerate fleet renewal timelines. Luanda and Cabinda concentrate vessel operations, with Soyo emerging as a maintenance and crew change center.
Ivory Coast
Emerging deepwater discoveries at Calao and Foxtrot fields generate new PSV requirements for exploration and early production support. The national oil company partners with international operators under production sharing contracts that specify vessel capability standards. Abidjan anchors offshore logistics coordination, with San Pedro developing as a secondary supply base.
Cameroon
Maturing offshore infrastructure at Rio del Rey fields expands demand for maintenance-intensive contracts and ROV support vessels. The national hydrocarbons company imposes local content requirements on service contractors. Douala and Kribi host vessel operations, with Kribi Deep Seaport enabling larger PSV access for emerging field developments.
West Africa Platform Supply Vessel (PSV) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Bourbon anchors integrated vessel management platforms that bundle maintenance, crewing, and regulatory compliance into multi-year agreements. Domestic Nigerian operators concentrate in cabotage-protected coastal trades. European shipyard relationships and hybrid propulsion capabilities separate premium-tier competitors from commodity operators.
Among Nigeria-based specialists, SeaForce Shipping Company Ltd and Starzs Marine and Engineering Limited exemplify the domestic operator archetype serving cabotage-protected demand pools. Bourbon represents the integrated international operator segment with platform-scale procurement relationships. These three companies occupy distinct competitive positions shaped by registry status, vessel capability profiles, and contract duration preferences.
| Leading Market Players |
|---|
| SeaForce Shipping Company Ltd |
| Petromarine Nigeria Limited |
| Starzs Marine and Engineering Limited |
| GE Offshore Marine Services S.L |
| Aquashield Oil & Marine Services Limited |
| African Offshore Services |
| Team Offshore Nigeria Limited |
| Bourbon |
| Blue Sea Marine Services |
| Others |
Value Network & Pricing Analysis
Norwegian and Dutch shipyard concentration for newbuild PSV construction anchors upstream margin capture, forcing West African operators into euro-denominated contract exposure that compresses downstream charter economics and accelerates fleet renewal decisions toward hybrid-capable tonnage.
Pricing Analysis
IMO certification tiers for Energy Efficiency Existing Ship Index compliance create the primary spread between premium and standard charter rates. Three-tier pricing structure across IMO-compliant hybrid vessels, retrofitted medium-efficiency hulls, and legacy single-fuel diesel tonnage dominates contract structures. Cost compression in the legacy tier is intensifying because NIMASA cabotage enforcement strands older vessels in protected coastal trades with shrinking day rate premiums. International oil companies demonstrate lowest price sensitivity, prioritizing fuel efficiency guarantees and dynamic positioning reliability over per-day cost minimization.
Supply Chain Analysis
Specialized marine steel and high-tensile winch systems feed from concentrated European and East Asian manufacturing bases. Norway, the Netherlands, and South Korea anchor hull construction and propulsion system supply. Supply chain risk centers on single-source vulnerability for battery-hybrid propulsion components where Korean and Chinese suppliers dominate cell and power electronics production. Distribution runs through integrated vessel management platforms that bundle newbuild procurement, crewing, and long-term charter contracting into consolidated procurement relationships with major international oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated logistics support contracts represent the fastest-expanding recurring revenue layer, outpacing bareboat charter hardware economics as international oil companies outsource regulatory compliance and crew management to platform-scale operators.
For Market Incumbents: Pre-empt hybrid-electric capability gaps by securing exclusive yard slots at Norwegian and Dutch facilities before 2026 delivery windows tighten. Anchor position through backward integration into shore power infrastructure at Lagos and Takoradi supply bases, creating captive demand lock-in for battery-hybrid vessels. Defend against domestic Nigerian operators by accelerating NIMASA certification investments that exceed minimum cabotage compliance thresholds. For New Entrants and Emerging Players: Ghanaian offshore contractors facing local content threshold restructuring represent the most penetrable entry point for indigenous vessel operators with Ghanaian registry. Angolan shallow-water field revival programs preserve structural demand for small and medium PSV categories where draft restrictions limit larger hull deployment and international operator interest. Pursue joint venture structures with established European shipyards to bypass capital barriers for hybrid propulsion capability. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic Nigerian operators holding cabotage-protected contract portfolios but lacking hybrid propulsion upgrade capital. Long-term viability hinges on regulatory compliance trajectory rather than cyclical oil price exposure. Monitor IMO EEXI enforcement stringency across Nigerian and Ghanaian waters as the primary inflection signal for stranded legacy tonnage valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Fleet Conversion | Battery-hybrid propulsion systems command premium charter rates from international oil companies specifying fuel efficiency in Nigerian deepwater tenders. |
| Shore Power Infrastructure Investment | Takoradi and Lagos supply base electrification enables fuel consumption reductions that differentiate compliant operators in Ghanaian logistics awards. |
| NIMASA Certification Acceleration | Enhanced Safety of Life at Sea compliance beyond minimum cabotage thresholds protects contract eligibility against tightening Nigerian enforcement. |
| Integrated Logistics Platform Expansion | Bundling maintenance, crewing, and regulatory compliance concentrates procurement authority with operators capable of multi-year agreement structures. |
| Angolan Shallow-Water Specialization | Small and medium PSV categories retain structural importance where draft restrictions limit larger hull deployment in field revival programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vessel chartering managers at international oil companies, fleet operations directors at integrated vessel management platforms, and regulatory compliance officers at domestic Nigerian operators. Secondary validation drew from NIMASA cabotage enforcement records, Ghana Petroleum Commission local content filings, IMO EEXI implementation guidelines, and customs data for PSV newbuild deliveries into West African registries. Bottom-up charter rate aggregation across Nigerian and Ghanaian supply bases was triangulated against top-down fleet capacity estimates from European shipyard order books.
Calibration against historical contract award patterns and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vessel type, service tier, end-user category, and hull size class, with additional granularity for IMO compliance tier and dynamic positioning capability grade. CAGRs were derived from contract duration-weighted day rate trajectories and fleet renewal velocity assumptions tied to EEXI enforcement phases. Forecast inputs incorporated subsea infrastructure age profiles across maturing West African oil provinces and hybrid propulsion adoption curves from European lead markets.
Practitioners should monitor IMO EEXI enforcement stringency, NIMASA cabotage compliance audit frequency, and Ghana Petroleum Commission local content threshold adjustments for early signals of forecast revision. Cross-checking against Lloyd's List vessel movement data and Clarksons offshore vessel order book disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Ship Galley Equipment Market