
 Electric Vehicle Aluminum Electric Drive Parts Market | 2026-2036
Electric Vehicle Aluminum Electric Drive Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Aluminum Electric Drive Parts Market Insights
Aluminum is shifting steel out of motor housings and rotor brackets across high-volume EV architectures, cutting component weight while maintaining thermal conductivity thresholds. Robert Bosch GmbH leverages in-house die-casting capacity to supply OEMs with integrated aluminum stator carriers. ZF Friedrichshafen AG anchors its electric axle programs on extruded aluminum gearboxes that merge structural and thermal functions. Continental AG competes through precision-cast rotor housings engineered for permanent magnet motor architectures.
Electric vehicle aluminum electric drive parts comprise cast, extruded, and machined aluminum components forming the structural and thermal backbone of battery-electric propulsion systems, typically specified in 6061-T6 or A380 alloy grades for housing applications requiring heat dissipation above 150 W/m·K. These parts channel coolant, support magnetic assemblies, and isolate electrical windings from road loads across passenger and commercial platforms. Housings dominate current output value given their complexity and alloy specificity, while rotor demand is accelerating fastest as automakers raise motor speeds above 20,000 RPM to shrink powertrain mass. Cast aluminum still occupies the largest share by tonnage, though extruded aluminum is gaining in gearless direct-drive layouts where hollow shaft geometries reduce rotating inertia.
The EPA tailpipe rules and the EU F-Gas Regulation are tightening thermal-management requirements that aluminum housings must satisfy, while China's MIIT mandates domestic EV component sourcing quotas that reshape supplier geography. NHTSA crash standards in the United States and ECE R94 homologation in Europe dictate housing structural performance under impact, forcing alloy selection toward high-ductility formulations. Stakeholders must monitor divergence between regional carbon-accounting standards for aluminum smelting, as scope-three emissions thresholds will soon differentiate qualified suppliers from excluded bidders in OEM RFQs.
Market Dynamics
OEM mass-reduction mandates are compressing motor housing design cycles, forcing aluminum die-casters to deliver integrated thermal-structural castings that previously required multi-material assemblies.
Growth Catalysts
- EU Green Deal embodied-carbon rules:Low-carbon aluminum smelters in Iceland and Norway now qualify for premium EV supply contracts that exclude coal-powered Chinese primary aluminum.
- China's MIIT domestic sourcing quotas:Battery-electric OEMs must source 60% of drivetrain components locally, redirecting aluminum motor housing demand toward Shanghai and Guangdong foundries.
- High-pressure die-casting integration:Gigacasting platforms consolidate 70+ stamped steel parts into single aluminum motor-mount structures, collapsing assembly labor content.
Market Restraints
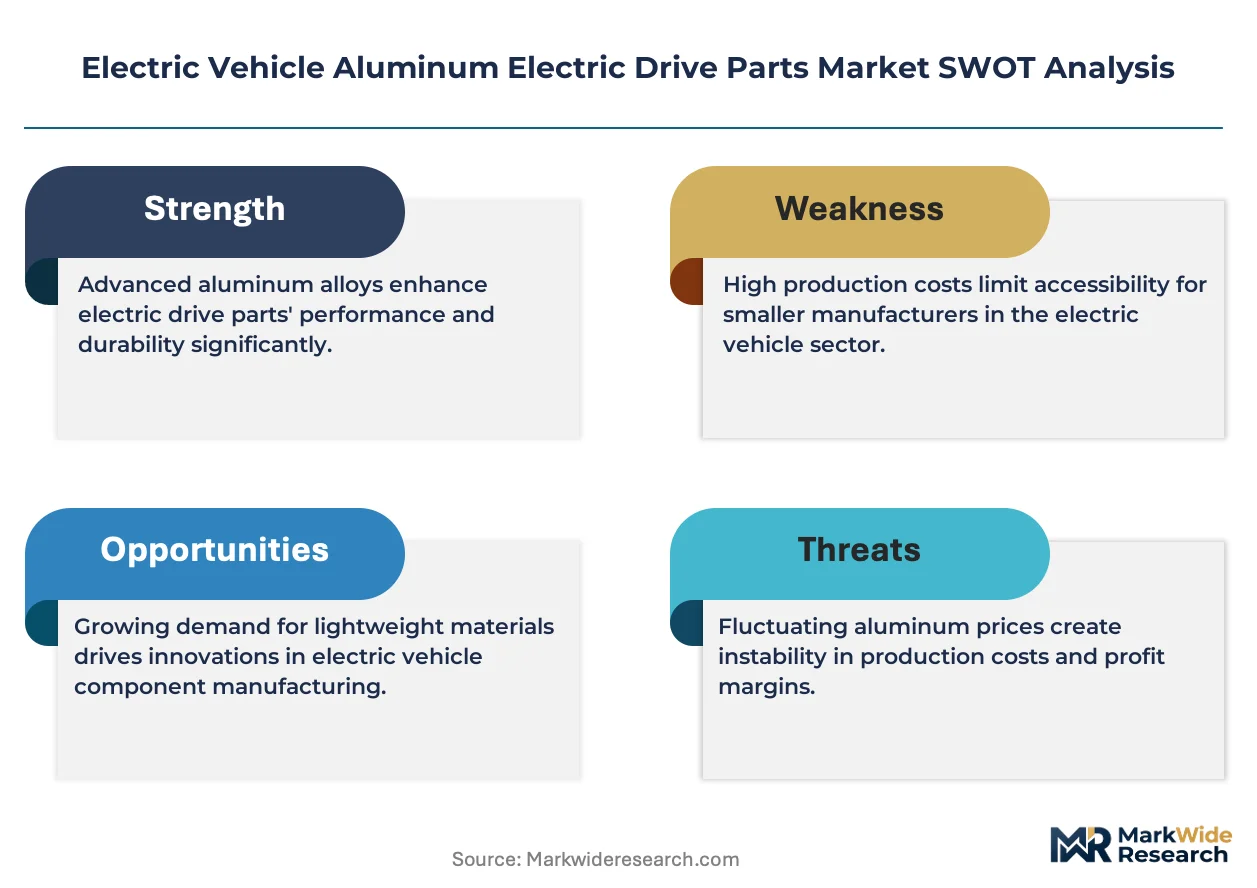
- Primary aluminum price volatility:London Metal Exchange aluminum contracts swung 40% between 2022-2024, destabilizing long-term housing supply agreements for Tier-1 suppliers.
- Scrap availability constraints:Post-consumer aluminum scrap suitable for A356.2 rotor housing remelt remains concentrated in Germany and the US, leaving Asian casters import-dependent.
- Thermal expansion coefficient mismatch:Aluminum motor housings expand 2.3x faster than carbon-fiber wound stators, creating seal-groove fatigue in liquid-cooled architectures above 180°C.
Strategic Opportunities
- Commercial EV underpenetration:Class 4-8 electric trucks in the US and EU specify aluminum gearbox housings at 15% passenger EV penetration rates, opening 300,000-unit annual demand white space.
- India's PLI scheme for auto components:25% capex reimbursement for aluminum casting investments above $50 million is pulling Chinese and Korean die-casters into Tamil Nadu.
- Silicon-carbide inverter thermal loads:800V architectures generate 40% more waste heat, expanding aluminum cooling jacket surface area requirements by 25% per housing.
Industry Challenges
- High-pressure die-casting tooling capex:4,000-ton gigacasting cells require $15-20 million per installation, freezing out mid-cap suppliers from integrated housing contracts.
- ECE R94 homologation timelines:European motor housing crash certification now demands 18-month validation cycles for new alloy formulations, compressing platform development schedules.
- Magnetic assembly contamination control:Aluminum oxide residues from machining operations degrade permanent magnet performance, requiring clean-room integration that 60% of Tier-2 machine shops lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Aluminum Electric Drive Parts Market |
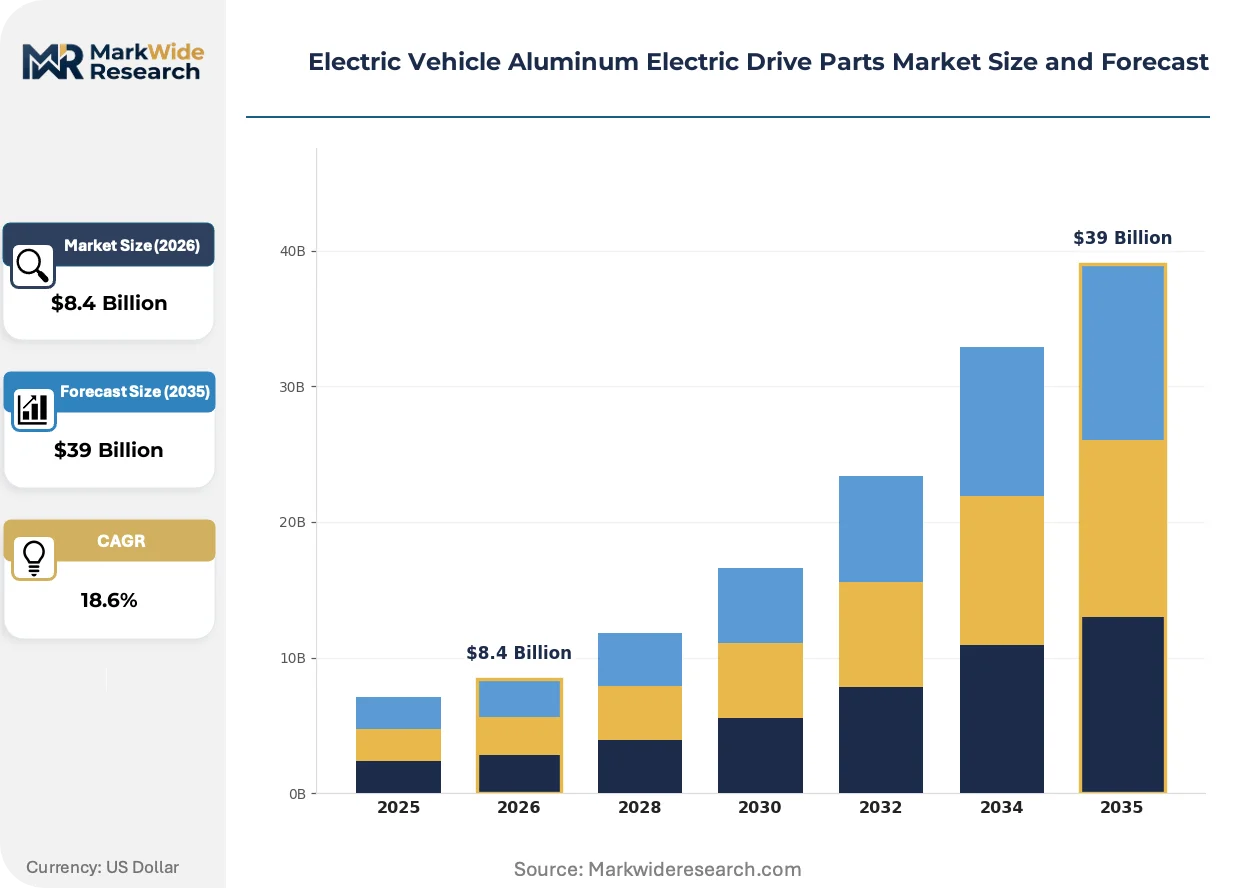
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stators, Rotors, Gears, Housings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Permanent Magnet, Switched Reluctance, Induction, Gearless Material: Aluminum Alloys, Cast Aluminum, Extruded Aluminum, Composite Materials |
| Companies Covered | Robert Bosch GmbH, DENSO Corporation, BorgWarner Inc, MAHLE Group, ZF Friedrichshafen AG, Continental AG, Dana Incorporated, ABB, General Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Aluminum Electric Drive Parts Market Trends and Innovations
Process automation and regulatory carbon accounting are rewriting sourcing criteria for aluminum electric drive components faster than alloy specifications themselves.
Artificial vision-guided robotic finishing is automating post-cast machining of complex motor housing geometries that previously required manual deburring. European OEMs now specify 0.05mm surface finish tolerances on stator bore interfaces, a precision threshold that robotic grinding cells hit consistently while manual stations scrap 12% of parts. This automation is compressing the cost gap between Chinese and German aluminum housing suppliers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in motor cooling loops, forcing aluminum housing designers to enlarge coolant channel volumes for CO2-based systems. German OEMs led by BMW and Volkswagen are already validating 30% larger water jackets that maintain thermal performance with transcritical CO2. Housing weight penalties from this channel expansion are driving adoption of hollow-core extruded aluminum shafts that recover 40% of the added mass.
Direct long-term contracting between OEMs and primary aluminum smelters is displacing spot-market purchasing through commodity traders. Tesla, Rivian, and Mercedes-Benz now source low-carbon aluminum directly from Iceland's Rio Tinto Alcan and Norway's Hydro Karmøy, bypassing London Metal Exchange price exposure. This procurement restructuring concentrates qualified supply among six smelters globally and locks out secondary traders from EV-grade aluminum flows.
Electric Vehicle Aluminum Electric Drive Parts Market Segmentation
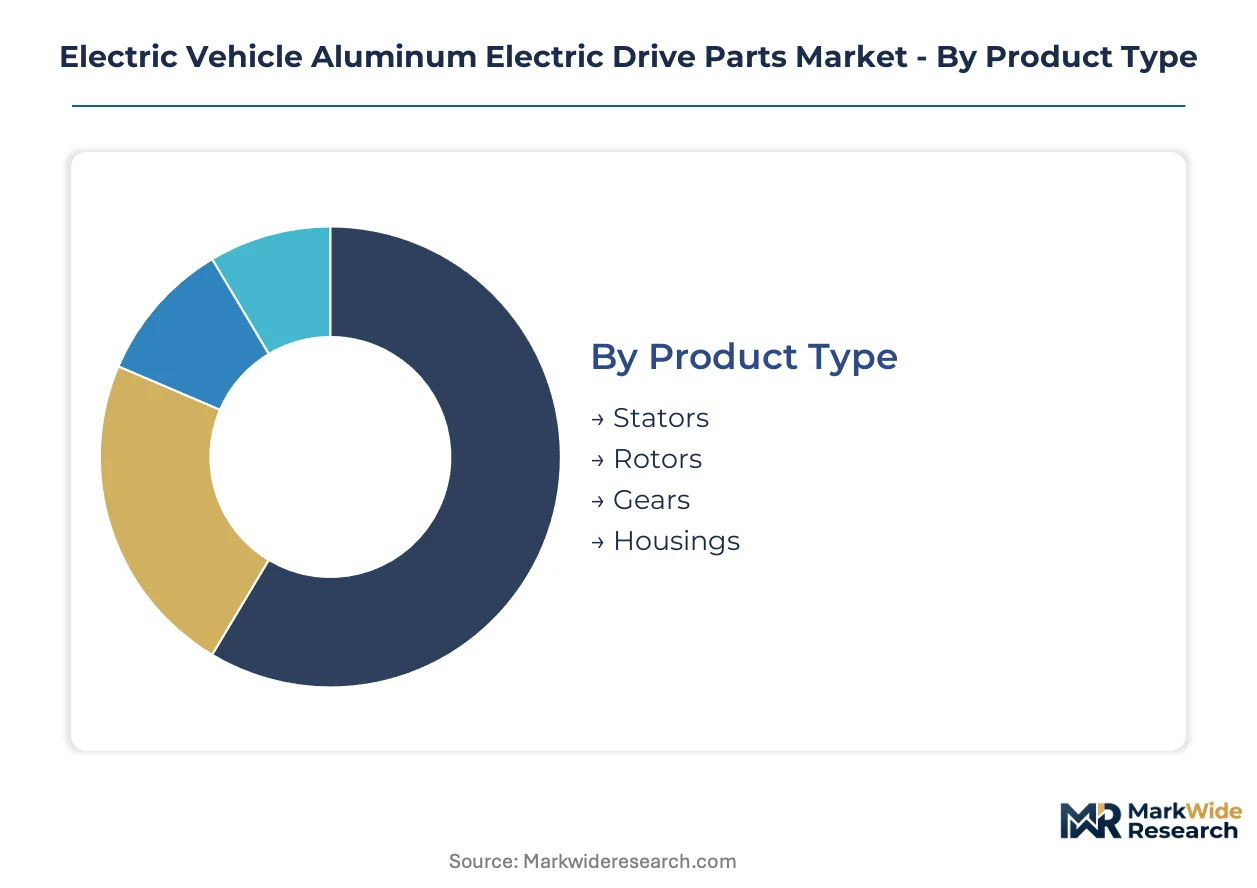
Aluminum electric drive parts span four critical dimensions that determine procurement priorities. Product type dictates thermal and structural specifications. End-user relationships shape volume commitments and certification requirements.
Product Type:
Buyer decisions hinge on thermal load capacity and assembly integration complexity.
- Housings:Cast aluminum enclosures channel coolant, support magnetic assemblies, and isolate electrical windings from road loads. Demand concentrates in Germany's automotive manufacturing belt, where OEMs and Tier-1 suppliers co-locate electric drive engineering centers to compress design cycles.
- Rotors:High-speed aluminum rotor cores and brackets maintain dimensional stability above 20,000 RPM. China's MIIT domestic sourcing quotas redirect procurement toward Shanghai and Guangdong foundries as battery-electric OEMs must source drivetrain components locally.
- Stators:Aluminum stator carriers and end bells provide structural backbone for copper winding assemblies.
- Gears:Extruded aluminum gearbox housings merge structural and thermal functions in integrated electric axle programs.
Housings lead on scale; rotors lead on momentum.
End User:
Procurement scale and technical integration depth separate the four buyer categories.
- OEMs:Volkswagen, BMW, and Tesla specify integrated aluminum motor-mount structures that consolidate 70+ stamped steel parts through gigacasting platforms. Direct long-term contracting with Iceland's Rio Tinto Alcan and Norway's Hydro Karmøy now displaces spot-market purchasing through commodity traders.
- Tier-1 Suppliers:Robert Bosch GmbH and ZF Friedrichshafen AG leverage in-house die-casting capacity to supply OEMs with aluminum stator carriers and extruded gearboxes. These suppliers face 18-month ECE R94 homologation timelines for new alloy formulations in Europe.
- Vehicle Assemblers:Contract manufacturers source aluminum housings under white-label arrangements for emerging EV brands.
- Aftermarket Providers:Replacement part distributors serve collision repair and refurbishment channels with machined aluminum components.
OEMs dominate absolute volume; Tier-1 suppliers drive process innovation.
Technology:
Motor architecture determines aluminum component specifications and cooling requirements.
- Permanent Magnet:Neodymium-iron-boron motor architectures demand precision-cast aluminum rotor housings with tight dimensional tolerances. 800V silicon-carbide inverter architectures generate 40% more waste heat, expanding aluminum cooling jacket surface area requirements.
- Gearless:Direct-drive layouts specify hollow-core extruded aluminum shafts that reduce rotating inertia and recover mass from enlarged coolant channels.
- Induction:Copper rotor designs use aluminum end rings and housings for cost-sensitive mass-market platforms.
- Switched Reluctance:Magnet-free motor architectures simplify aluminum housing specifications but require enhanced vibration damping.
Permanent magnet systems anchor current output; gearless direct-drive climbs the fastest.
Material:
Alloy selection balances thermal conductivity, structural ductility, and embodied-carbon thresholds.
- Cast Aluminum:A380 and A356.2 alloys dominate motor housing tonnage through high-pressure die-casting. Post-consumer scrap suitable for A356.2 rotor housing remelt remains concentrated in Germany and the US, leaving Asian casters import-dependent.
- Extruded Aluminum:6061-T6 hollow shafts and cooling jackets gain share in gearless direct-drive layouts where thermal management requirements intensify.
- Aluminum Alloys:Custom formulations address thermal expansion coefficient mismatches with carbon-fiber wound stators.
- Composite Materials:Hybrid aluminum-polymer assemblies serve niche applications requiring electrical isolation.
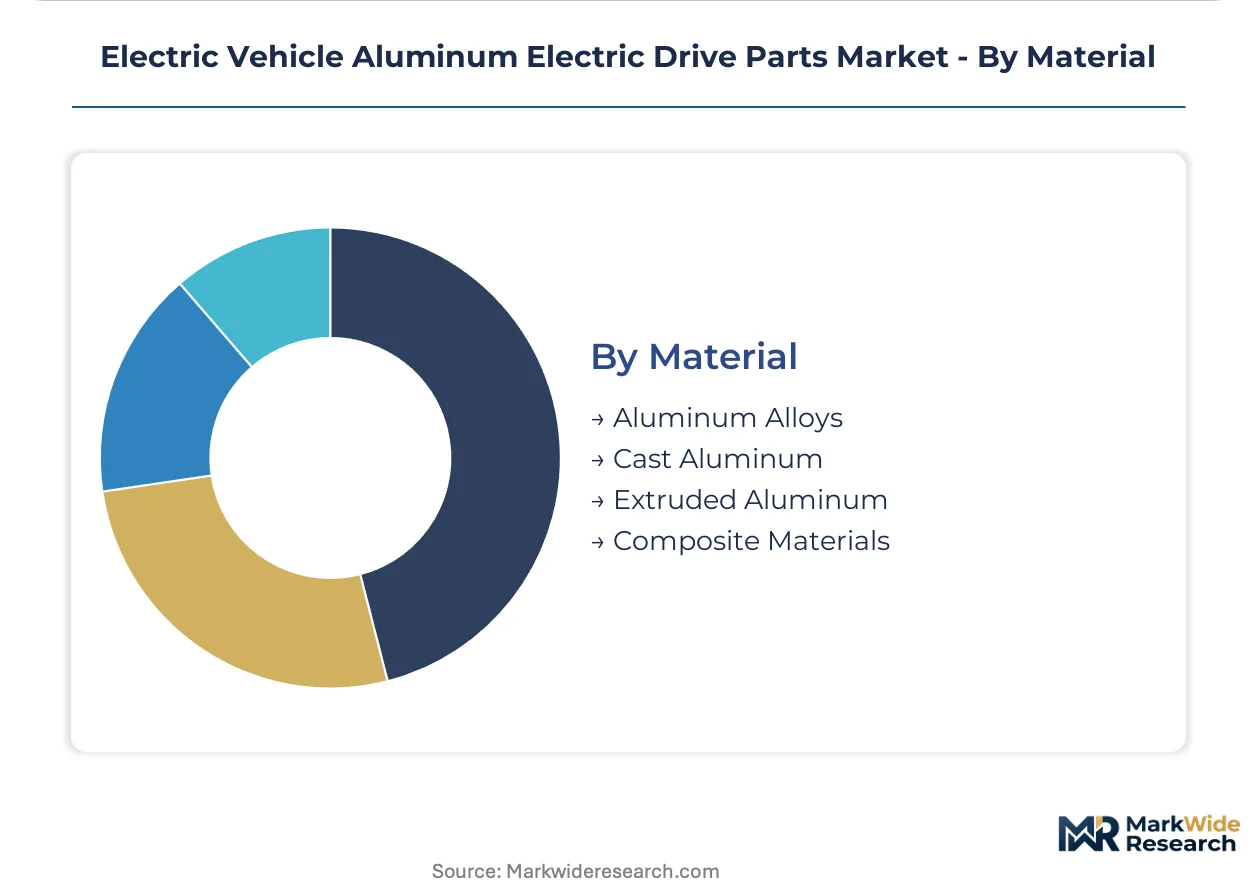
Cast aluminum holds volume leadership; extruded aluminum gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing belt concentrates electric drive engineering centers where OEMs and Tier-1 suppliers co-locate to compress aluminum housing design cycles. Regional regulatory divergence on embodied-carbon accounting is redirecting sourcing toward low-carbon aluminum smelters in Iceland and Norway.
United States
EPA tailpipe rules and NHTSA crash standards tighten thermal-management and structural performance requirements for aluminum motor housings. The IRA domestic content provisions incentivize localized aluminum casting investments. Detroit's engineering corridors host validation facilities for 800V silicon-carbide inverter thermal loads.
China
MIIT domestic sourcing quotas mandate 60% local drivetrain component procurement, redirecting aluminum motor housing demand toward Shanghai and Guangdong foundries. The country's dual carbon goals tighten embodied-carbon thresholds for EV materials. Shenzhen and Shanghai clusters anchor high-pressure die-casting capacity expansion.
Germany
ECE R94 homologation timelines extend motor housing crash certification to 18 months for new alloy formulations, compressing platform development schedules. The EU Green Deal embodied-carbon rules exclude coal-powered primary aluminum from premium EV supply contracts. Bavaria and Baden-Württemberg house integrated electric axle engineering centers.
Japan
METI efficiency mandates accelerate motor speed targets above 20,000 RPM, intensifying demand for high-speed aluminum rotor cores. JIS standards govern alloy specifications for thermal conductivity above 150 W/m·K. Nagoya's automotive belt concentrates precision-casting capacity for permanent magnet motor architectures.
India
The PLI scheme for auto components offers 25% capex reimbursement for aluminum casting investments above $50 million, pulling Chinese and Korean die-casters into Tamil Nadu. BIS standards for EV component quality are tightening. Chennai and Pune clusters emerge as alternative supply bases for gearbox housing exports.
Electric Vehicle Aluminum Electric Drive Parts Market Competitive Landscape
High-pressure die-casting integration dominates the current landscape as suppliers consolidate multi-material assemblies into single aluminum structures. The vendor base separates into three tiers: global Tier-1 systems integrators with captive casting capacity, regional specialists in precision machining, and emerging Asian scale players. Two strategic archetypes predominate: vertically integrated engineering houses that control alloy formulation through finished housing delivery, and technology licensors that monetize casting process IP. Capacity expansion and direct long-term contracting with primary aluminum smelters represent the dominant competitive moves reshaping supplier relationships.
Among German-based engineering houses, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the vertically integrated archetype, while Continental AG occupies a position within the precision-casting specialist tier. DENSO Corporation represents Japanese systems integration capability. These anchors illustrate how geographic clustering around OEM engineering centers shapes competitive positioning without determining specific market outcomes.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DENSO Corporation |
| BorgWarner Inc |
| MAHLE Group |
| ZF Friedrichshafen AG |
| Continental AG |
| Dana Incorporated |
| ABB |
| General Motors |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embodied-carbon thresholds gate qualified supply for premium-tier aluminum motor housing contracts, redirecting procurement toward Iceland's Rio Tinto Alcan and Norway's Hydro Karmøy while excluding coal-powered primary smelters from OEM long-term offtake agreements. This environmental mandate bifurcates the supplier base into certified low-carbon tier and spot-market commodity tier, with pricing power concentrating among the six qualified smelters capable of documenting scope-three emissions below OEM thresholds.
Pricing Analysis
Input-cost pass-through from London Metal Exchange aluminum contracts destabilizes long-term housing supply agreements, forcing Tier-1 suppliers toward direct smelter contracting that bypasses commodity trader markups. Pricing stratifies across low-carbon certified, standard primary, and secondary scrap tiers, with OEMs absorbing premiums for Iceland and Norway origin while aftermarket providers remain most price-sensitive to spot volatility. Cost compression in standard-grade castings intensifies as Chinese foundries compete on volume, though ECE R94 homologation investments protect European suppliers in premium segments.
Supply Chain Analysis
Dual-sourcing requirements from German OEMs mandate qualified secondary suppliers for aluminum motor housings, preventing single-foundry dependency despite concentration in Germany, China, and Japan. The supply chain draws from primary aluminum ingots, high-pressure die-casting tooling, and precision machining capacity, with tariff exposure on Chinese castings threatening cost structures for US-bound components. Distribution runs through Tier-1 systems integrators with captive casting capacity, consolidating downstream channel control among Robert Bosch GmbH, ZF Friedrichshafen AG, and Continental AG.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aluminum electric drive parts rests on gigacasting integration that collapses assembly labor content, while low-carbon certification unlocks premium-tier pricing access previously reserved for European suppliers.
For Market Incumbents: Anticipate displacement from Chinese die-casters expanding into European OEM supply chains through cost-competitive A356.2 rotor housing production. Defensive consolidation requires backward integration into primary aluminum offtake from Iceland and Norway smelters, plus investment in robotic finishing cells that hit 0.05mm surface finish tolerances on stator bore interfaces without manual deburring scrap. For New Entrants and Emerging Players: Launch via white-label supply to commercial EV assemblers in Class 4-8 electric trucks, where aluminum gearbox housing penetration lags passenger EV platforms by 85 percentage points. Tamil Nadu's PLI scheme offers 25% capex reimbursement for casting investments above $50 million, creating a geographic entry point outside established German and Chinese supply clusters. For Investors and Strategic Acquirers: Roll-up economics work for precision-casting specialists with ECE R94 certification because 18-month homologation timelines create artificial scarcity for new alloy formulations. Long-term viability hinges on 800V silicon-carbide inverter thermal load exposure expanding cooling jacket surface area requirements. Watch for divergence between regional carbon-accounting standards as the inflection indicator separating qualified from excluded bidders in OEM RFQs.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Smelter Contracting | Tesla, Rivian, and Mercedes-Benz bypass LME price exposure through Iceland and Norway offtake agreements. |
| Gigacasting Platform Investment | 4,000-ton cells consolidate 70+ stamped steel parts into single aluminum motor-mount structures. |
| Low-Carbon Certification Program | EU Green Deal embodied-carbon rules exclude coal-powered Chinese primary aluminum from premium contracts. |
| Robotic Finishing Cell Deployment | Artificial vision-guided automation hits 0.05mm tolerances while manual stations scrap 12% of parts. |
| Geographic Capacity Expansion | Tamil Nadu's PLI scheme pulls Chinese and Korean die-casters into India's emerging supply base. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, aluminum foundry operations managers, and regulatory affairs specialists at Germany's KBA grounded qualitative insights in operational reality. Secondary validation drew from EPA tailpipe rule filings, EU ECE R94 homologation databases, China MIIT domestic sourcing quota documentation, and London Metal Exchange contract data. Bottom-up and top-down triangulation cross-checked segment-level volume assumptions against aggregate market sizing.
Bottom-up modeling built from vehicle production forecasts, content-per-vehicle estimates for aluminum motor housings and rotor cores, and alloy-grade pricing differentials across the projection horizon. Top-down analysis stress-tested these outputs against OEM capital expenditure disclosures and Tier-1 supplier order backlog patterns. Segmentation dimensions included product type, end-user category, motor architecture technology, and material alloy grade, with CAGRs derived from regression analysis of historical procurement volume against EV platform launch timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under primary aluminum price volatility and regulatory divergence on carbon-accounting methodologies. Deviation in China's MIIT domestic sourcing quota enforcement or EU F-Gas Regulation phase-down timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Brake Pad Market
Automotive Parts
Air Brake Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Africa Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Large Volume Injector Market