
 Automotive Engine Bearings Market | 2026-2036
Automotive Engine Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Bearings Market Analysis
The EU Green Deal is shifting procurement criteria across European automotive supply chains, compelling tier-one suppliers to source bearings with verified carbon footprints. SKF leverages its integrated steel-to-bearing production network to meet these traceability requirements. Schaeffler AG anchors its position through R&D intensity in polymer-composite bearing architectures. NSK Ltd. dominates Asian OEM supply channels with manufacturing scale across Japan and China.
Automotive engine bearings are precision-machined or sintered components, typically manufactured from steel-backed alloys with bronze or polymer overlays, designed to reduce friction between rotating crankshafts and engine blocks while maintaining oil film integrity under thermal and mechanical load. Roller bearings command the largest product type share due to load-bearing capacity in heavy-duty applications, though polymer bushings represent the fastest-expanding material category as thermal stability improves. OEMs capture the dominant end-user value pool through long-term supply agreements, while aftermarket providers compete on availability across aging vehicle parcs.
EPA tailpipe standards in the United States and Euro 7 regulations in Europe are tightening tolerances on engine friction losses, directly elevating bearing performance specifications for market access. China's MIIT enforces GB standards on domestic automotive component durability, shaping export competitiveness for regional manufacturers. Japan's METI coordinates JIS certification requirements that influence premium bearing qualification protocols. Stakeholders must monitor divergence between regional emissions trajectories and material compliance timelines to align capacity investments with shifting certification thresholds.
Market Dynamics
Euro 7 emission standards are compressing bearing friction tolerances across European OEM supply chains, forcing material upgrades from traditional bronze overlays to engineered polymer composites while Asian commercial fleets simultaneously expand heavy-duty bearing procurement.
Growth Catalysts
- Commercial Fleet Expansion:Asia-Pacific logistics operators are retrofitting aging truck parcs with high-durability bearings to extend engine overhaul intervals and reduce downtime costs.
- REACH Compliance:European chemical substance restrictions are accelerating substitution of lead-based bearing overlays with bismuth and polymer alternatives in crankshaft applications.
- Thermal Stability Advances:Polyimide-based bearing materials now withstand continuous operating temperatures above 200°C, opening deployment in turbocharged downsized engines.
Market Restraints
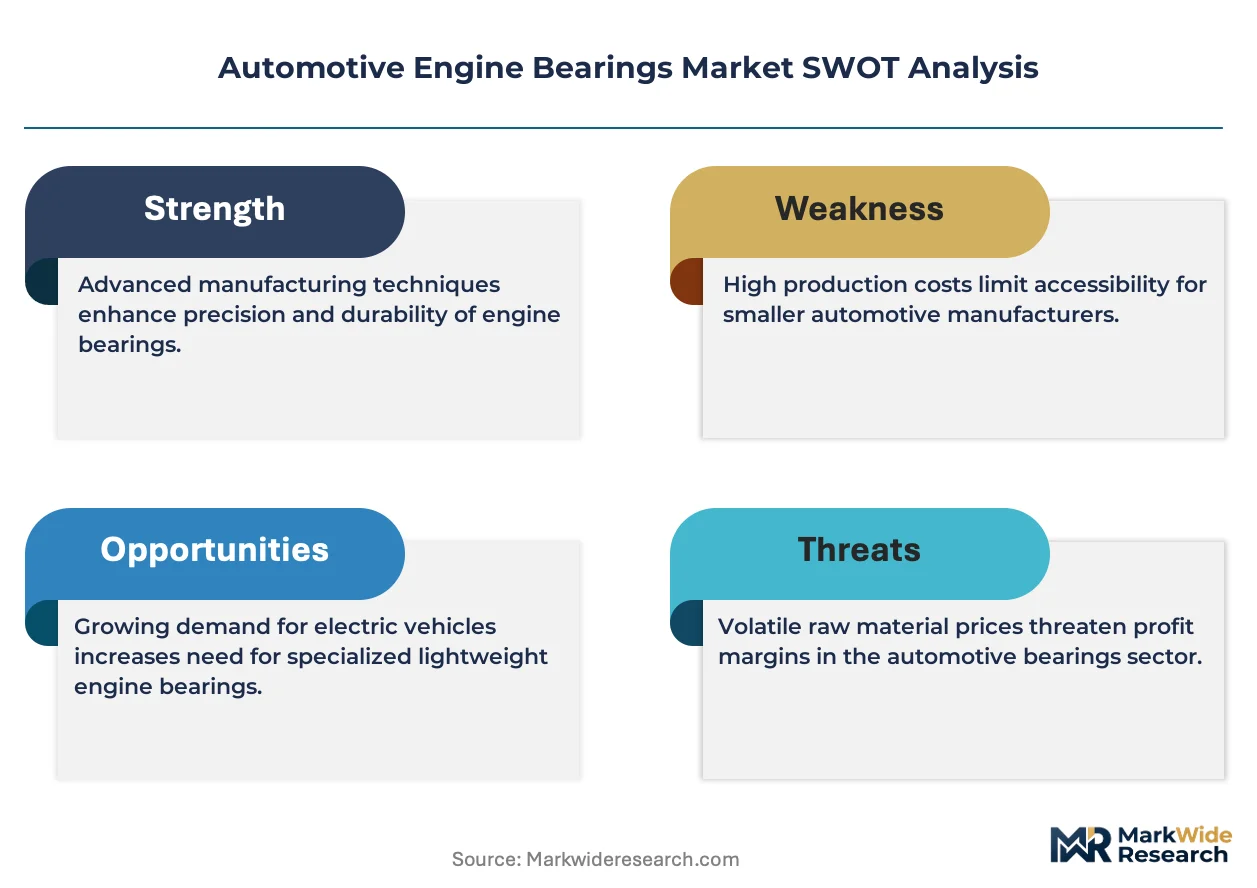
- Steel Alloy Volatility:Bearing manufacturers face margin compression from fluctuating specialty steel and copper alloy input costs with limited pass-through mechanisms in long-term OEM contracts.
- Concentrated Sintering Capacity:Precision powder metallurgy for high-performance engine bearings clusters in German and Japanese supplier networks, creating geographic supply vulnerability.
- Electric Powertrain Substitution:Battery electric vehicle architectures eliminate crankshaft bearings entirely, threatening demand erosion in passenger vehicle segments.
Strategic Opportunities
- Aftermarket Channel Digitization:Independent distributors are deploying AI-driven inventory matching platforms to serve fragmented commercial vehicle repair networks across India's state-level transport corridors.
- EU Green Deal Procurement:Verified carbon footprint documentation for bearing steel is becoming a mandatory tier-one supplier qualification criterion under CSRD-linked supply chain audits.
- Hybrid Engine Architectures:Range-extender and plug-in hybrid powertrains require specialized bearings for intermittent high-load operation, creating specification differentiation opportunities.
Industry Challenges
- Metrology Skill Scarcity:Precision bearing inspection requires sub-micron surface measurement expertise that outpaces vocational training program output in manufacturing regions.
- Dual Certification Burden:Suppliers must simultaneously maintain IATF 16949 automotive quality systems and emerging carbon accounting protocols under divergent audit timelines.
- Legacy Equipment Integration:New low-friction bearing designs often require crankshaft surface finish modifications incompatible with existing engine block machining lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Bearings Market |
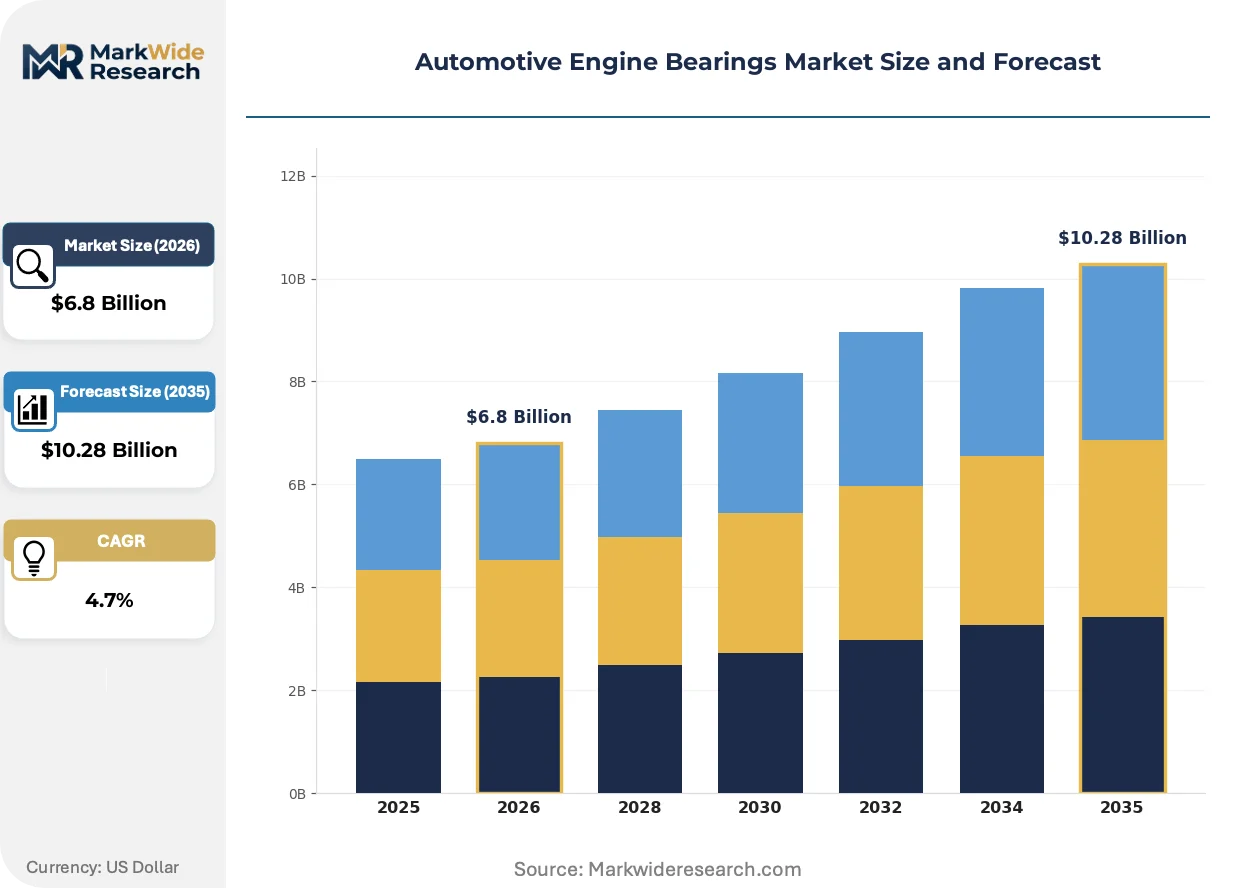
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Bushings, Plain Bearings Material: Steel, Bronze, Polymer, Composite Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Motorcycles End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops |
| Companies Covered | NTN Corporation, JTEKT Corporation, Schaeffler AG, MinebeaMitsumi Inc., Nachi Fujikoshi Corp., SKF, Timken Company, RBC Bearings, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Bearings Market Emerging Trajectories
Material science breakthroughs and emissions-driven specification tightening are converging to transform bearing architecture from commodity hardware into precision thermal-mechanical systems.
Polymer-composite bearing overlays with embedded solid lubricant phases are electrifying crankshaft applications previously reserved for tri-metal constructions. OEMs in Germany and Japan are qualifying these materials for production turbocharged engines. The technology is electrifying supplier R&D allocation toward polymer formulation rather than traditional metallurgy.
EPA tailpipe standards are tightening friction loss thresholds for internal combustion engines sold in the United States, directly elevating bearing surface finish and oil retention specifications. Manufacturers must now document micropore structure and embeddability characteristics for regulatory submission. Heavy-duty diesel applications face the steepest compliance cost increases as they balance durability against friction reduction targets.
Commercial fleet operators are unbundling bearing procurement from engine rebuild packages, creating direct relationships with component suppliers rather than relying on OEM captive distribution. Independent parts distributors in China's Yangtze River Delta are capturing this disintermediation opportunity through same-day fulfillment networks. The shift is most pronounced in long-haul trucking segments where vehicle utilization rates maximize the value of component traceability and rapid replacement availability.
Automotive Engine Bearings Market Segmentation
Engine bearing specification varies sharply by duty cycle, thermal load, and procurement channel. Each segmentation axis reveals distinct margin structures and technical barriers that shape supplier positioning across automotive supply chains.
Product Type:
Customization intensity spans from commodity plain bearings to precision roller assemblies engineered for specific crankshaft geometries.
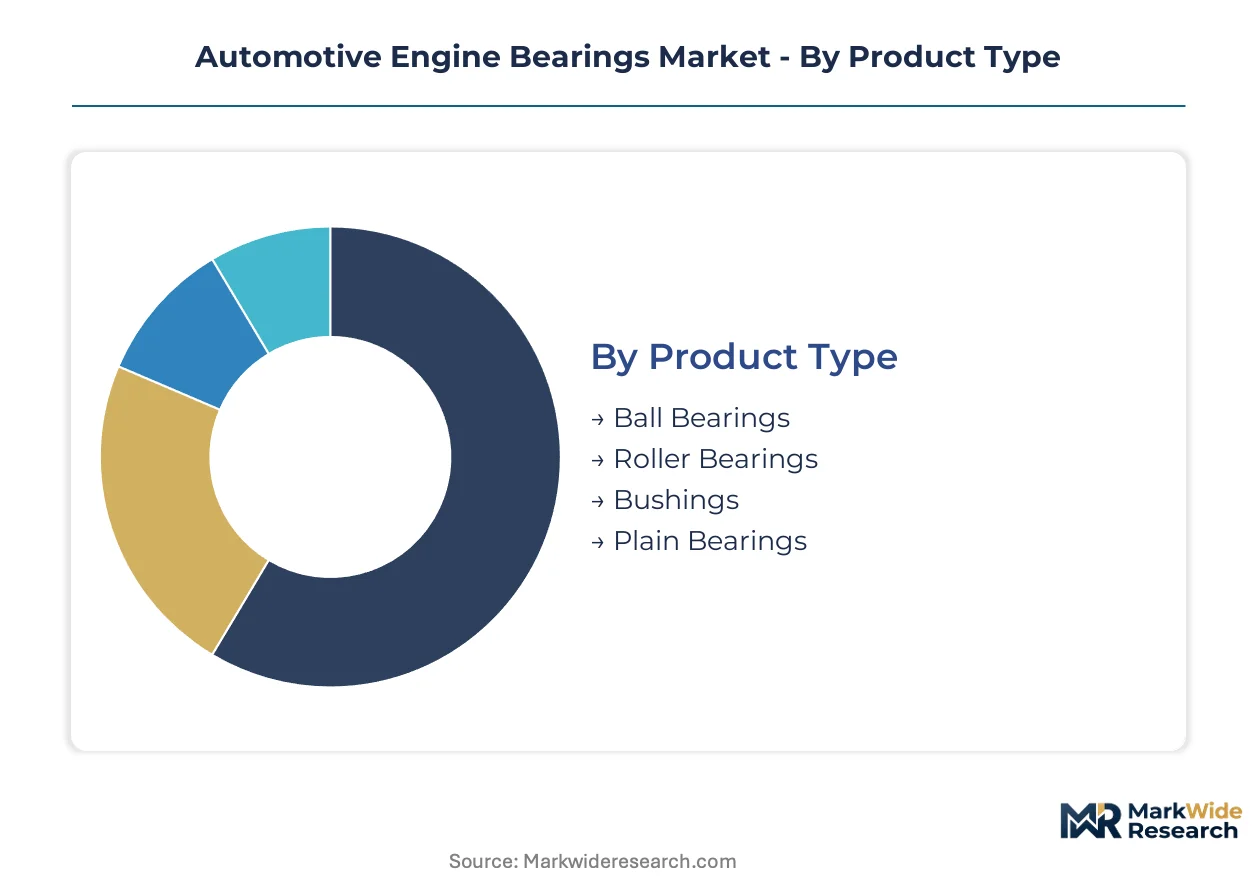
- Roller Bearings:Cylindrical and tapered roller configurations distribute radial and axial loads across multiple contact points. Heavy-duty diesel engines in commercial vehicle fleets across China's Yangtze River Delta specify these for extended overhaul intervals under continuous high-torque operation.
- Ball Bearings:Point-contact designs minimize friction in lighter-load applications where space constraints dominate. Japanese and German OEMs specify these for downsized turbocharged gasoline engines where reduced bearing width frees block architecture for cooling gallery optimization.
- Bushings:Sleeve-type bearings machined from bronze or polymer composites serve cost-sensitive applications with moderate rotational speeds.
- Plain Bearings:Simple bearing surfaces without rolling elements persist in legacy engine architectures and certain auxiliary drives.
Most installed capacity flows through Roller Bearings. Expansion is steepest in Ball Bearings.
Material:
Cost tier stratification separates commodity metal systems from advanced polymer formulations commanding specification premiums.
- Steel:Steel-backed structures with overlay coatings provide the foundational substrate for high-load engine bearings. German and Japanese sintering networks concentrate precision powder metallurgy capacity for these substrates.
- Polymer:Polyimide and PEEK-based composites with embedded solid lubricant phases now withstand continuous temperatures above 200°C. Euro 7 friction tolerance requirements are accelerating OEM qualification of these materials for production turbocharged engines.
- Bronze:Traditional copper-tin alloys with lead or bismuth overlays face REACH-driven substitution pressure in European supply chains.
- Composite:Multi-layer constructions combining steel strength with polymer friction properties serve hybrid powertrain intermittent load profiles.
Steel retains the largest installed base. Polymer formulations are climbing the fastest.
Application:
Volume concentration versus margin intensity splits this category between mass-market passenger production and specialized commercial duty cycles.
- Passenger Vehicles:High-volume production lines specify bearings optimized for friction reduction over absolute durability. EPA tailpipe standards in the United States directly elevate surface finish and oil retention specifications for this segment's regulatory compliance.
- Commercial Vehicles:Long-haul trucking and logistics fleets prioritize bearing life extension to minimize downtime costs. Fleet operators in India's state-level transport corridors are unbundling bearing procurement from engine rebuild packages, creating direct supplier relationships.
- Heavy Machinery:Construction and mining equipment bearings face shock loading and contamination exposure beyond automotive duty cycles.
- Motorcycles:Compact engine architectures with high RPM operation specify specialized bearing geometries for crankshaft and transmission applications.
Passenger Vehicles absorb the greatest production volume. Commercial Vehicles are gaining share fastest.
End User:
Customer type determines pricing power, certification burden, and inventory velocity across fundamentally different procurement workflows.
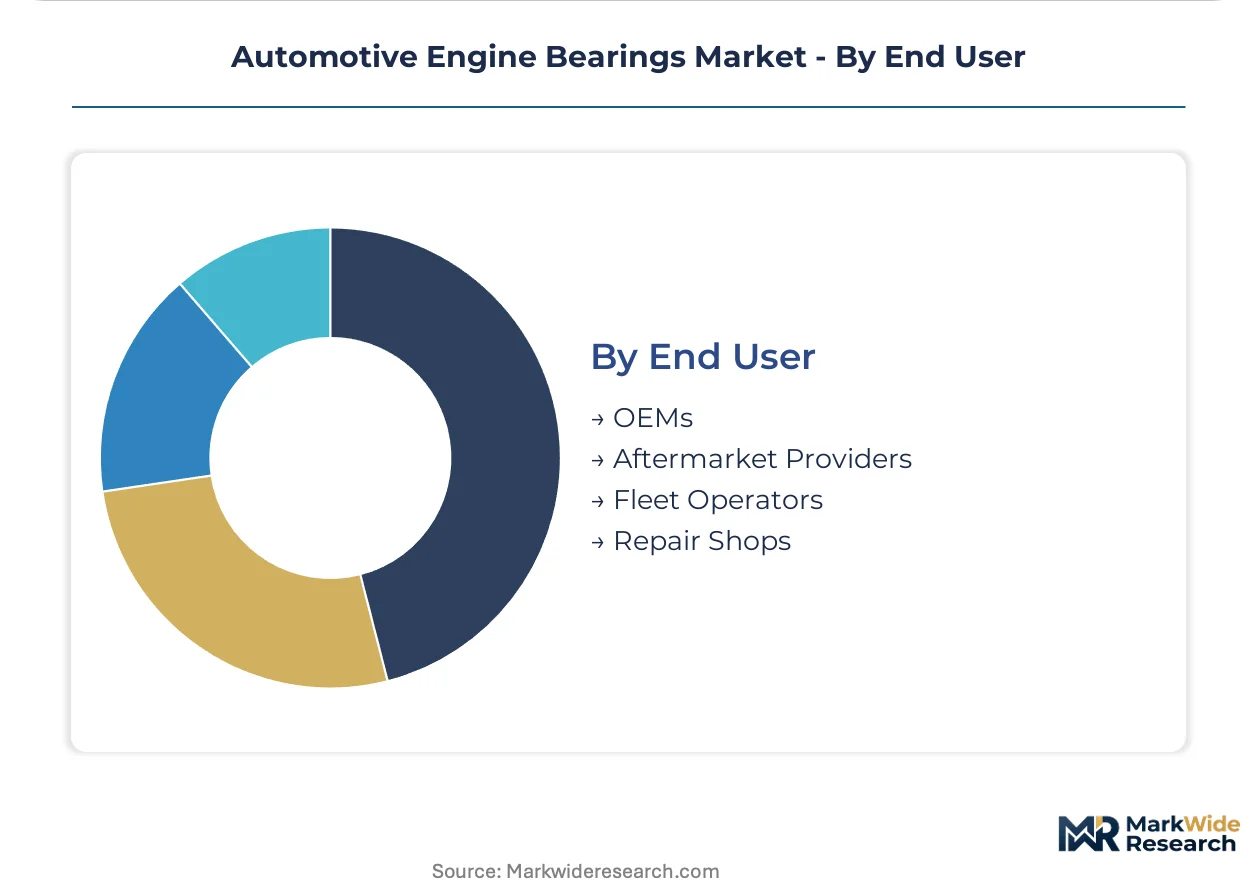
- OEMs:Original equipment manufacturers lock in multi-year supply agreements with IATF 16949 quality system requirements and emerging carbon accounting protocols. Tier-one suppliers to European OEMs now face mandatory verified carbon footprint documentation under CSRD-linked audits.
- Aftermarket Providers:Independent distributors compete on availability across aging vehicle parcs. AI-driven inventory matching platforms are emerging across India's fragmented commercial vehicle repair networks to serve this channel.
- Fleet Operators:Large logistics companies with captive maintenance facilities increasingly procure bearings directly rather than through OEM captive distribution.
- Repair Shops:Small-scale service providers rely on distributor networks for same-day fulfillment and technical support.
OEMs command the dominant value pool. Aftermarket Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision metrology talent clusters in Stuttgart, Nagoya, and Shanghai anchor bearing manufacturing quality systems. German and Japanese vocational pipelines supply sub-micron surface measurement expertise that outpaces training capacity elsewhere. Chinese technical universities are scaling precision engineering programs to close this gap.
China
Commercial fleet operators in the Yangtze River Delta are retrofitting aging truck parcs with high-durability bearings to extend engine overhaul intervals. MIIT enforces GB standards on domestic automotive component durability that shape export competitiveness for regional manufacturers. Manufacturing corridors around Shanghai and Chongqing concentrate sintering capacity and polymer-composite formulation R&D.
Germany
OEM procurement teams are mandating verified carbon footprint documentation for bearing steel under CSRD-linked supply chain audits. ECHA REACH restrictions accelerate substitution of lead-based bearing overlays with bismuth and polymer alternatives in crankshaft applications. Precision powder metallurgy networks in Baden-Württemberg and Bavaria supply European tier-one suppliers with steel-backed alloy substrates.
Japan
Downsized turbocharged gasoline engine programs specify ball bearings where reduced bearing width frees block architecture for cooling gallery optimization. METI coordinates JIS certification requirements that influence premium bearing qualification protocols for domestic OEMs. Kanto and Chubu industrial regions host integrated steel-to-bearing production networks serving Asian export channels.
United States
Heavy-duty diesel applications face steep compliance cost increases as EPA tailpipe standards tighten friction loss thresholds for internal combustion engines. Manufacturers must document micropore structure and embeddability characteristics for regulatory submission. Midwest automotive supplier corridors around Detroit and Cleveland maintain legacy plain bearing machining capacity for commercial vehicle aftermarket channels.
India
Independent parts distributors are deploying AI-driven inventory matching platforms to serve fragmented commercial vehicle repair networks across state-level transport corridors. Fleet operators are unbundling bearing procurement from engine rebuild packages to create direct supplier relationships. Manufacturing clusters in Maharashtra and Tamil Nadu are expanding polymer bushing production for cost-sensitive applications.
Automotive Engine Bearings Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered supply positions. Integrated steel-to-bearing manufacturers maintain captive metallurgy control while specialized fabricators outsource substrate sourcing. Three archetypes dominate: vertically integrated material specialists, precision sintering houses, and polymer-composite formulators. Capacity expansion and strategic partnerships represent the primary competitive moves as firms align with divergent regional emissions trajectories.
Within the integrated production tier, Schaeffler AG and SKF exemplify material control strategies spanning substrate metallurgy to finished bearing architecture. NSK Ltd. occupies a position representing Asian manufacturing scale across Japanese and Chinese production networks. Among precision-focused specialists, NTN Corporation and JTEKT Corporation sit within the tier of component suppliers serving OEM captive distribution channels with long-term supply agreements.
| Leading Market Players |
|---|
| NTN Corporation |
| JTEKT Corporation |
| Schaeffler AG |
| MinebeaMitsumi Inc. |
| Nachi Fujikoshi Corp. |
| SKF |
| Timken Company |
| RBC Bearings |
| NSK Ltd. |
| Others |
Supply Flow & Price Mechanics
Tier-one OEM procurement teams concentrated in Germany and Japan negotiate multi-year supply agreements that anchor contract-based long-term offtake pricing across the automotive engine bearings market. This buyer concentration shifts pricing power toward volume-scaled manufacturers capable of meeting IATF 16949 quality systems and emerging carbon accounting protocols.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates polymer-composite bearings with verified carbon footprints from conventional bronze-overlay systems and commodity plain bearings. Price differentiation hinges on certification grade under Euro 7 friction tolerance requirements and volume scale in multi-year OEM contracts. Cost compression in standard-tier steel-backed bearings is intensifying because specialty steel and copper alloy input volatility outpaces pass-through mechanisms. Fleet operators in India's state-level transport corridors exhibit highest price sensitivity, while German OEM procurement teams prioritize thermal stability specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision powder metallurgy networks concentrated in Germany and Japan, where sub-micron surface measurement expertise outpaces vocational training capacity elsewhere. Geographic supply concentration clusters in Germany, China, and Japan for steel-backed alloy substrates and polymer-composite formulation R&D. Raw material dependencies draw from specialty steel mills, copper-tin alloy foundries, and polyimide resin suppliers. Tariff exposure on bearing steel imports threatens margin structures for European tier-one suppliers. Distribution runs through OEM captive channels for production volumes and independent aftermarket distributors for aging vehicle parc replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive engine bearings market functions as a geographic-arbitrage play where polymer-composite formulation R&D costs in Germany and Japan run substantially above scalable manufacturing economics in China's Yangtze River Delta corridors.
For Market Incumbents: Deepen backward integration into captive steel metallurgy to insulate margin structures from alloy input volatility while accelerating polymer-composite bearing qualification for Euro 7 production programs. Electric powertrain substitution threatens crankshaft bearing demand in passenger segments, demanding capacity reallocation toward commercial vehicle and hybrid engine architectures. Prioritize IATF 16949 and CSRD-linked carbon accounting protocol certification to defend tier-one supply positions. For New Entrants and Emerging Players: Begin with aftermarket channel digitization across India's fragmented commercial vehicle repair networks, where AI-driven inventory matching platforms remain underpenetrated relative to OEM captive distribution density. Fleet operator direct procurement relationships represent the most penetrable entry vector, bypassing long-term supply agreement barriers. Target same-day fulfillment capability in state-level transport corridors as the primary go-to-market angle. For Investors and Strategic Acquirers: Precision sintering houses with polymer-composite formulation capabilities are the most active acquirer targets in this space, as integrated steel-to-bearing manufacturers seek thermal-mechanical systems expertise. The five-to-ten-year viability window hinges on hybrid powertrain penetration rates and commercial fleet electrification trajectories. Monitor divergence between EPA tailpipe standard enforcement and Euro 7 compliance timelines as the critical inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Composite Formulation Scale-Up | Enables Euro 7 friction tolerance compliance for turbocharged gasoline engine programs at German OEMs. |
| Backward Integration into Specialty Steel | Captive metallurgy control insulates margin structures from alloy input cost volatility in long-term contracts. |
| Aftermarket Channel Digitization | AI-driven inventory matching platforms capture fleet operator direct procurement relationships in India's transport corridors. |
| Carbon Footprint Verification Program | CSRD-linked supply chain audits mandate verified documentation for tier-one supplier qualification in Europe. |
| Hybrid Engine Bearing Specification Development | Range-extender and plug-in hybrid architectures require specialized bearings for intermittent high-load operation. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down sintering capacity tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and ECHA REACH restriction updates. Triangulation across these sources anchors segmentation-specific volume and value estimates.
Input-output matrices map bearing content per vehicle across passenger, commercial, and hybrid propulsion architectures over the projection horizon. Segmentation dimensions modeled include product type, material formulation, application duty cycle, and end-user procurement channel. CAGRs derive from regression analysis of historical production correlations and regulatory-driven specification upgrade cycles. Industry-specific forecast inputs incorporate Euro 7 friction tolerance phase-in schedules and EPA tailpipe standard enforcement trajectories.
Several conditions sit outside the modeled scope, including abrupt battery electric vehicle adoption accelerations that would eliminate crankshaft bearing demand, and trade policy shifts affecting specialty steel tariff structures. Forecasts reflect documented assumptions about OEM platform engineering timelines and polymer material qualification protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Automotive Catalyst Market