
 Middle East and Africa Internal Combustion Engines Market | 2026-2036
Middle East and Africa Internal Combustion Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Internal Combustion Engines Market Insights
A shift from single-source procurement to multi-source supply strategies is repositioning how Middle East and Africa fleet operators secure engine blocks and after-treatment systems. Caterpillar Inc. leverages its regional parts distribution network to sustain long-dated service contracts across mining and oilfield segments. Cummins Inc. anchors its position through localized assembly operations that reduce lead times for African power generation customers. Wärtsilä Corporation competes on dual-fuel architecture for marine and utility applications in Gulf ports.
Internal combustion engines in the Middle East and Africa context convert hydrocarbon fuels into mechanical work through reciprocating piston assemblies, with compression ratios typically ranging from 14:1 to 22:1 for diesel variants optimized for high-ambient-temperature operation. These engines primarily serve as prime movers for transportation fleets, stationary power plants, and off-highway equipment across infrastructure-deficient terrains. Diesel configurations within the fuel type dimension dominate commercial vehicle and power generation installations due to superior thermal efficiency and fuel availability across remote African corridors. Natural gas variants are gaining share in Gulf utility applications where pipeline infrastructure exists and emission restrictions tighten. The inline engine architecture occupies the majority of medium-duty transportation and agricultural equipment lines, while V-type layouts concentrate in heavy marine and mining sectors where torque density commands premium positioning.
South Africa's National Regulator for Compulsory Specifications enforces emission standards that filter non-compliant engine imports, while Gulf Standardization Organization harmonization across Saudi Arabia, UAE, and Kuwait creates a partial regulatory bloc for product certification. Nigeria's Federal Ministry of Environment air quality guidelines are beginning to constrain generator set deployments in Lagos and Port Harcourt industrial zones. Stakeholders must monitor how carbon border adjustment discussions in European trading partners reshape engine export eligibility from North African manufacturing hubs.
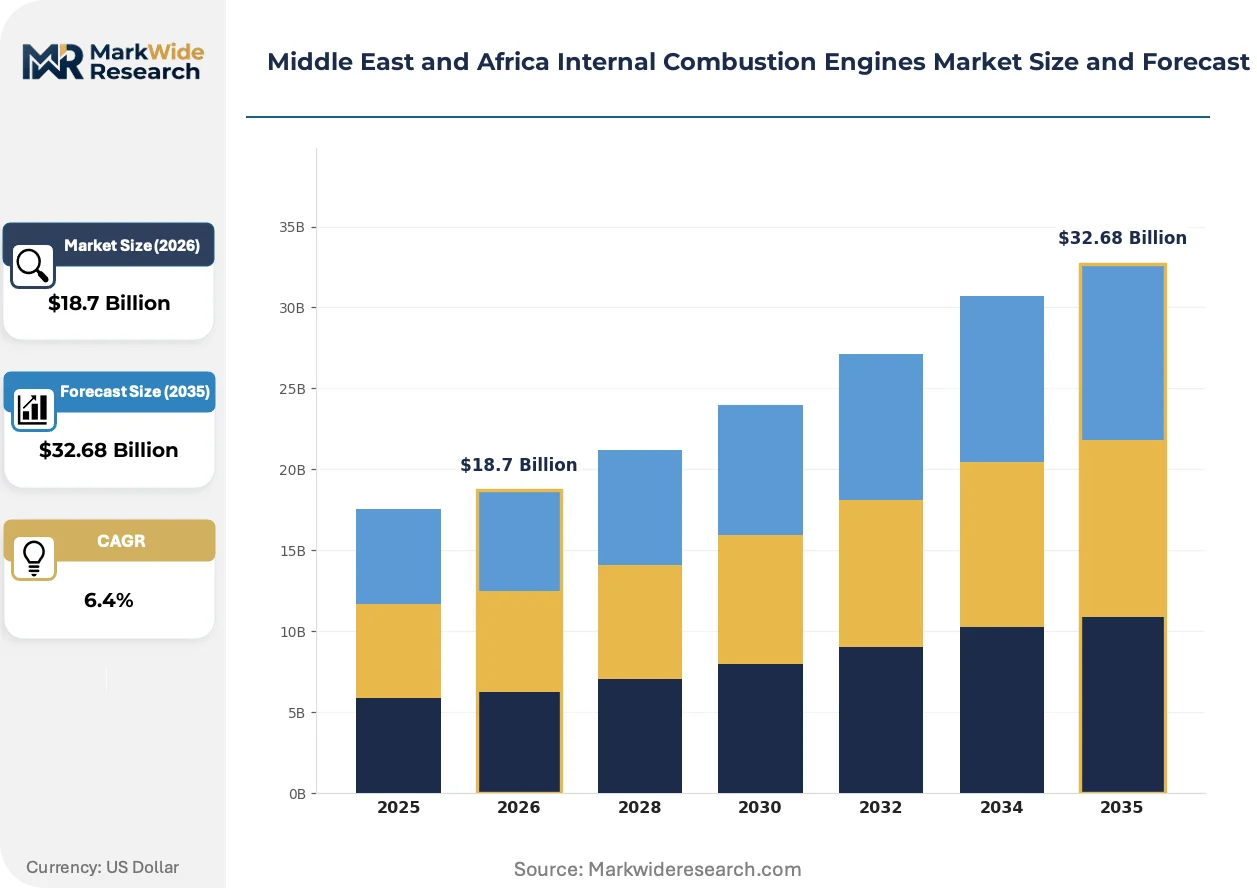
Market Dynamics
Gulf Cooperation Council utilities are accelerating fleet renewal cycles as dual-fuel engine architectures displace pure diesel configurations in baseload power applications, compressing supplier lead times and reshaping procurement specifications across Saudi Arabia's industrial city clusters.
Growth Catalysts
- Captive Power Expansion:Nigeria's Federal Ministry of Environment air quality guidelines are tightening emission thresholds for generator set deployments in Lagos and Port Harcourt industrial zones, pulling demand toward certified low-NOx diesel configurations.
- Gulf Standardization Organization Harmonization:Saudi Arabia, UAE, and Kuwait have created a partial regulatory bloc for product certification, reducing technical barriers for engine manufacturers seeking multi-country approvals.
- Mining Fleet Electrification Backlash:South Africa's Department of Mineral Resources and Energy efficiency mandates are tightening emission thresholds for stationary engines, sustaining demand for high-thermal-efficiency diesel prime movers where grid connectivity remains unreliable.
Market Restraints
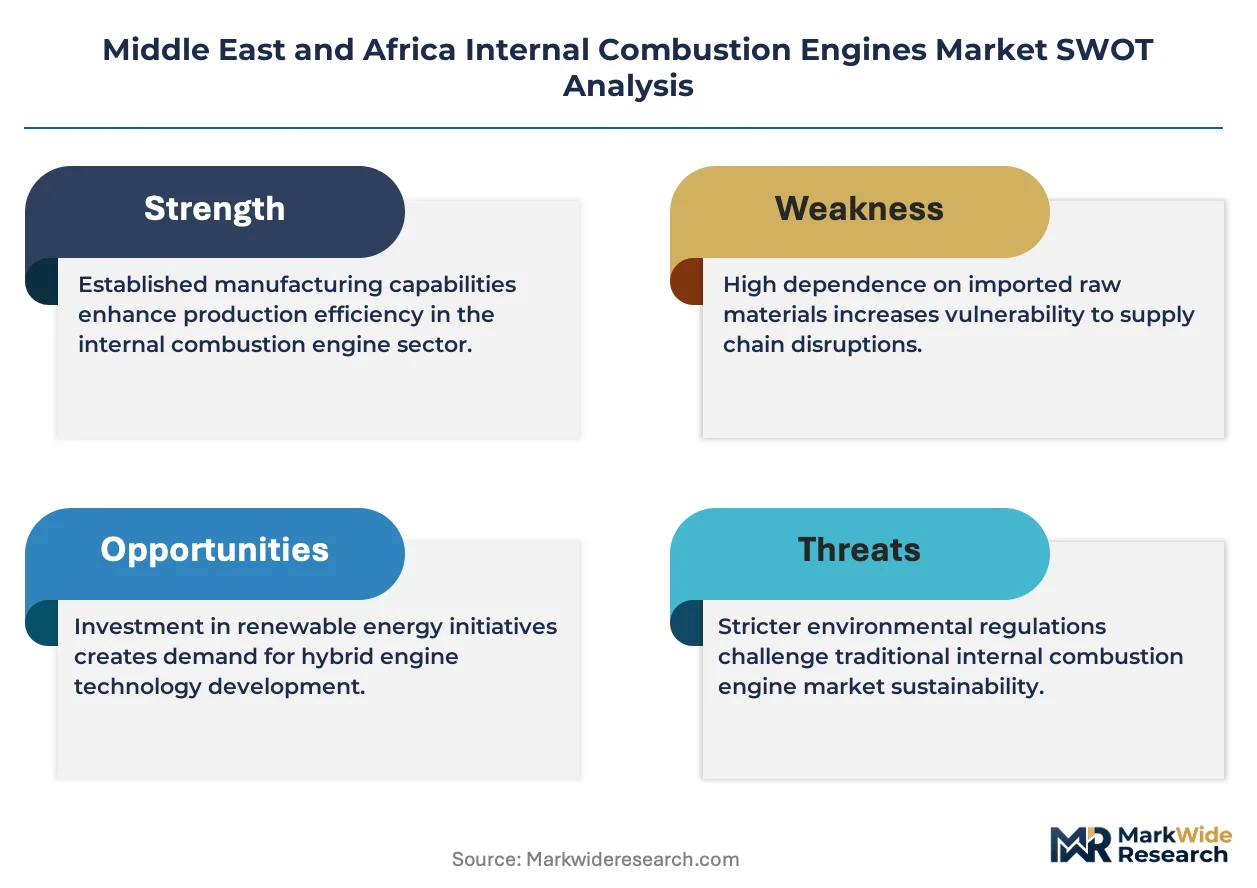
- Steel and Cast Iron Input Volatility:Engine block foundries face margin compression from fluctuating scrap metal and alloy prices, particularly affecting heavy-duty cylinder head production in North African manufacturing hubs.
- After-Treatment System Concentration:Selective catalytic reduction and diesel particulate filter supply chains concentrate among a narrow supplier base in European trading partners, exposing African power generation customers to extended lead times.
- Electrification Substitution:Battery energy storage systems paired with solar arrays are displacing diesel generator sets in remote telecommunications and rural electrification projects across East African corridors.
Strategic Opportunities
- Ethiopia's Industrial Park Buildout:The country's manufacturing zone expansion lacks reliable grid infrastructure, creating white space for natural gas engine installations where pipeline distribution networks reach processing facilities.
- Retrofit Emissions Compliance:South Africa's National Regulator for Compulsory Specifications enforcement creates aftermarket demand for engine remanufacturing and exhaust after-treatment retrofits on existing stationary power fleets.
- Digital Remote Monitoring Convergence:Integration of IoT sensor networks with predictive maintenance algorithms is opening service contract opportunities for engine OEMs managing distributed power assets across Nigeria's captive power installations.
Industry Challenges
- Combustion Calibration Expertise Scarcity:High-ambient-temperature engine tuning for Gulf conditions requires specialized thermodynamics knowledge that remains concentrated among senior engineering cohorts approaching retirement.
- Multi-Source Certification Complexity:Fleet operators shifting from single-source to multi-source procurement face extended homologation timelines as Gulf Standardization Organization and South African Bureau of Standards testing protocols diverge on particulate measurement methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Internal Combustion Engines Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Automotive OEMs, Commercial Vehicles, Marine Applications, Industrial Equipment Fuel Type: Petrol, Diesel, Natural Gas, Ethanol Engine Type: Inline, V-Type, Rotary, Flat Application: Transportation, Power Generation, Construction, Agriculture |
| Companies Covered | Caterpillar Inc., Cummins Inc., Volvo AB, Volkswagen Group, Hyundai Motor Company, Mitsubishi Heavy Industries Ltd., Wärtsilä Corporation, MAN Energy Solutions, Yanmar Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Internal Combustion Engines Market Trends and Innovations
Engine architecture is fragmenting into configurable subsystems as modular component design compresses development cycles and enables field-upgradable emission compliance across disparate regulatory environments.
Dual-fuel injection hardware is modularizing around standardized rail pressure specifications and interchangeable combustion chamber geometries. Saudi Aramco industrial customers and UAE port authorities are specifying these configurations for marine and utility applications to preserve fuel optionality. This modularization is compressing supplier development timelines and enabling post-installation fuel system conversions without block replacement.
Gulf Standardization Organization emission harmonization across Saudi Arabia, UAE, and Kuwait is converging test cycles with EU Stage V thresholds for non-road mobile machinery. Engine manufacturers must now certify once for multi-country deployment, reducing homologation costs but tightening particulate and NOx limits that demand advanced after-treatment integration. Heavy marine and mining sectors in Gulf ports are absorbing compliance costs through longer service contract durations.
After-sales service unbundling is accelerating as fleet operators separate parts procurement from maintenance execution. Nigerian captive power installations and South African mining operators are contracting independent service providers for routine maintenance while sourcing genuine components through regional distribution networks. This bifurcation is most visible in Lagos and Johannesburg industrial corridors where skilled technician labor pools support third-party service competition.
Middle East and Africa Internal Combustion Engines Market Segmentation
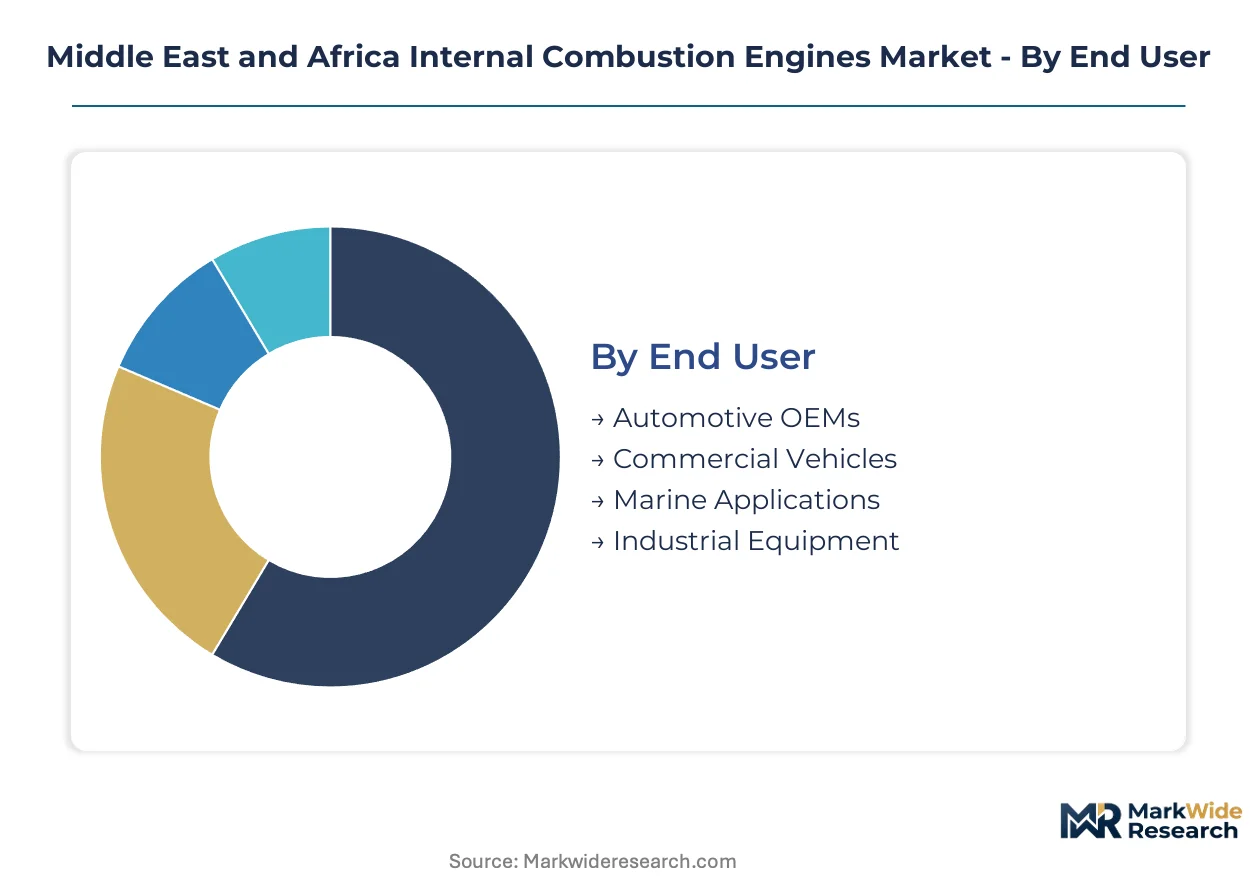
Segmentation in this market exposes how fuel availability, ambient operating conditions, and regulatory stringency fragment procurement patterns across Middle East and Africa territories. Fleet operators select engine configurations based on infrastructure maturity rather than performance optimization alone.
End User:
Buyers in this category diverge sharply by capital deployment cycles and in-house technical capability.
- Automotive OEMs:These manufacturers specify engines for passenger vehicle assembly lines, prioritizing emission certification alignment with Gulf Standardization Organization thresholds. Saudi Arabia's vehicle assembly plants and Morocco's automotive export zones concentrate procurement for light-duty petrol and diesel variants.
- Commercial Vehicles:Fleet operators running long-haul corridors across Nigeria's Lagos-Kano axis and South Africa's N3 corridor demand high-torque diesel configurations with extended service intervals. Compression ratios optimized for high-ambient-temperature operation dominate specifications.
- Marine Applications:UAE port authorities and Saudi Aramco marine terminals specify dual-fuel architectures for harbor craft and offshore supply vessels.
- Industrial Equipment:Mining houses and construction contractors in South Africa's platinum belt and Ghana's gold fields source heavy-duty prime movers for excavators and haul trucks.
Volume sits with Commercial Vehicles; growth tilts toward Marine Applications.
Fuel Type:
Regional infrastructure availability and emission mandates reshape fuel preference hierarchies across territories.
- Diesel:Compression-ignition configurations dominate remote power generation and commercial transportation where fuel distribution networks remain sparse. Nigeria's captive power installations and East African trucking corridors sustain demand despite tightening particulate thresholds.
- Natural Gas:Spark-ignited engines gain share in Gulf utility applications where pipeline infrastructure reaches industrial city clusters. Saudi Arabia's power generation fleet renewal and UAE desalination plants anchor procurement.
- Petrol:Light-duty automotive and small-scale agricultural equipment in North African manufacturing hubs specify these configurations.
- Ethanol:Flex-fuel variants see limited deployment in sugar-producing economies with established biofuel blending mandates.
Procurement volume clusters on Diesel; the steepest expansion trajectory belongs to Natural Gas.
Engine Type:
Physical packaging constraints and torque density requirements drive architecture selection for specific duty cycles.
- Inline:Cylinder arrangements in single or double rows dominate medium-duty transportation and agricultural equipment where service access simplicity outweighs power density. Ethiopia's industrial park machinery and Nigerian generator set manufacturing lines standardize on these configurations.
- V-Type:Angled cylinder banks concentrate in heavy marine propulsion and mining haul trucks where packaging volume limits apply. South Africa's platinum mining sector and Gulf port tugboat operators specify these for torque output per unit displacement.
- Rotary:Wankel configurations maintain niche presence in specialized aerospace and racing applications.
- Flat:Horizontally opposed engines see limited adoption in compact industrial equipment where center-of-gravity reduction matters.
Inline architectures command unit volume; V-Type configurations capture value concentration.
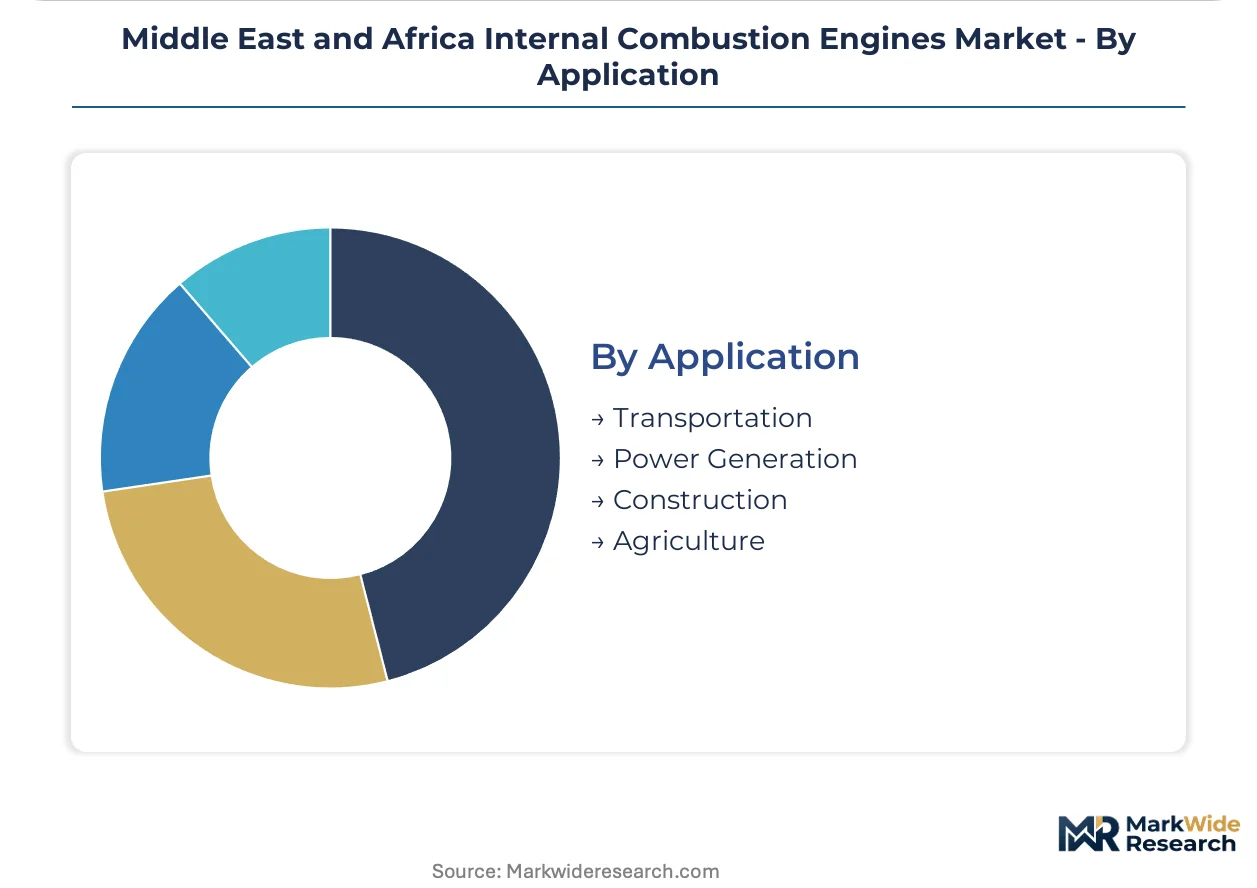
Application:
Grid reliability gaps and infrastructure buildout schedules create divergent demand profiles across use cases.
- Power Generation:Stationary diesel and gas engines serve as prime movers for baseload and backup capacity where national grids falter. Nigeria's Federal Ministry of Environment guidelines are tightening emission thresholds for generator deployments in Lagos and Port Harcourt industrial zones.
- Transportation:On-highway and off-highway vehicle propulsion accounts for substantial installed base across long-haul corridors and last-mile distribution networks.
- Construction:Earthmoving and material handling equipment in Saudi Arabia's industrial city clusters and Egypt's new administrative capital project drive periodic demand spikes.
- Agriculture:Mechanization programs in Ethiopia's lowland regions and Sudan's irrigation schemes specify mid-duty engines for tillage and pumping applications.
Power Generation holds installed base dominance; Transportation applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scrap metal and alloy feedstock flows from North African foundries anchor engine block manufacturing across the Middle East and Africa corridor. Regional demand concentrates where grid infrastructure remains deficient and industrial clusters require captive power solutions. Regulatory fragmentation between Gulf Standardization Organization harmonization and South African national standards shapes procurement specifications.
Saudi Arabia
Industrial city clusters at Jubail and Yanbu drive heavy-duty diesel and gas engine procurement for baseload power applications. The Gulf Standardization Organization emission harmonization with EU Stage V thresholds tightens particulate limits for non-road mobile machinery. Saudi Aramco marine terminals specify dual-fuel architectures for harbor craft operating out of Ras Tanura and Jeddah Islamic Port.
United Arab Emirates
Desalination plants and utility-scale power generation anchor natural gas engine demand where pipeline infrastructure reaches processing facilities. MOHAP and federal environmental guidelines constrain generator set deployments in industrial free zones. Dubai Maritime City and Khalifa Port marine terminals absorb compliance costs through extended service contract durations for harbor tugboat fleets.
South Africa
The platinum belt mining sector and N3 corridor commercial trucking sustain demand for high-torque diesel configurations with extended service intervals. The National Regulator for Compulsory Specifications enforces emission standards that filter non-compliant engine imports through homologation testing. Johannesburg industrial corridors and Richards Bay port facilities witness aftermarket demand for engine remanufacturing and exhaust after-treatment retrofits.
Nigeria
Captive power installations in Lagos and Port Harcourt industrial zones pull demand toward certified low-NOx diesel configurations as grid reliability remains intermittent. The Federal Ministry of Environment air quality guidelines constrain generator set deployments in manufacturing districts. Dangote industrial complex and Onne Oil and Gas Free Zone concentrate procurement for stationary power prime movers.
Egypt
The new administrative capital construction project and Suez Canal Economic Zone drive periodic demand spikes for earthmoving equipment prime movers. National environmental quality standards are beginning to align with Gulf Standardization Organization thresholds for product certification. Cairo-Alexandria industrial corridor and Ain Sokhna port facilities standardize on inline engine architectures for medium-duty machinery applications.
Middle East and Africa Internal Combustion Engines Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers localize assembly operations to compress lead times for African power generation customers. The vendor base concentrates among integrated industrial conglomerates with captive foundry and after-treatment system capabilities. Three strategic archetypes occupy distinct positions: diversified heavy equipment manufacturers, specialized power generation engine builders, and maritime propulsion specialists. Geographic expansion through regional parts distribution networks and technology licensing for dual-fuel architectures constitute the dominant competitive moves reshaping procurement relationships.
Within the diversified industrial equipment tier, Caterpillar Inc. and Cummins Inc. exemplify archetypes built on service contract anchoring and localized assembly operations respectively. Wärtsilä Corporation occupies a position representing dual-fuel architecture specialization for marine and utility applications. These three entities collectively demonstrate how aftermarket service unbundling and predictive maintenance convergence are opening distributed power asset management opportunities across Nigerian captive power installations and Gulf port authorities.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Volvo AB |
| Volkswagen Group |
| Hyundai Motor Company |
| Mitsubishi Heavy Industries Ltd. |
| Wärtsilä Corporation |
| MAN Energy Solutions |
| Yanmar Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Gulf Standardization Organization emission harmonization with EU Stage V thresholds is compressing supplier margins as engine manufacturers absorb compliance costs for multi-country certification while extending service contract durations to preserve pricing power. After-sales service unbundling across Nigerian captive power installations and South African mining corridors is fragmenting procurement relationships and forcing OEMs to defend component pricing through genuine parts authentication programs.
Pricing Analysis
Warranty and service contract bundling varies sharply across buyer archetypes, with Gulf utility operators demanding comprehensive long-term maintenance agreements while African power generation customers pursue unbundled parts procurement. Three-tier pricing structure across premium certified, standard compliant, and economy non-compliant configurations reflects Gulf Standardization Organization certification tiers. Price differentiation stems from after-treatment system integration depth and localized assembly proximity. Pricing pressure intensifies in economy tiers as battery energy storage systems displace diesel generator sets in East African telecommunications applications. Commercial vehicle fleet operators exhibit highest price sensitivity, while marine and mining sectors absorb premium positioning for torque density.
Supply Chain Analysis
Single-source vulnerability sits with European selective catalytic reduction and diesel particulate filter suppliers, exposing African power generation customers to extended lead times and procurement concentration risk. Engine block manufacturing draws from North African foundries in Egypt and Morocco, while precision fuel injection components source from Germany and Japan. Raw material dependencies include scrap steel and alloy feedstocks, high-pressure common rail systems, and exhaust after-treatment substrates. Tariff exposure through carbon border adjustment discussions in European trading partners threatens export eligibility from North African manufacturing hubs. Distribution runs through regional parts distribution networks anchored in Johannesburg, Dubai, and Lagos industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa internal combustion engines market sits in a technology-transition phase as dual-fuel architectures displace pure diesel configurations and battery energy storage systems encroach on remote power applications. Fleet operators must calibrate procurement strategies around fuel optionality and emission compliance durability.
For Market Incumbents: Anchor service contract portfolios through predictive maintenance algorithm integration and IoT sensor network deployment across distributed power assets. Deepen backward integration into exhaust after-treatment system manufacturing to reduce European supplier dependency and compress lead times for African customers. Defend against electrification substitution by emphasizing thermal efficiency advantages in grid-deficient terrains and extending dual-fuel architecture development timelines. For New Entrants and Emerging Players: Ethiopian industrial park machinery operators represent an underserved buyer archetype lacking reliable grid infrastructure and seeking natural gas engine installations where pipeline networks reach processing facilities. Target aftermarket remanufacturing and emission retrofit services in South Africa's platinum belt, where National Regulator for Compulsory Specifications enforcement creates compliance-driven replacement demand. Pursue technology licensing arrangements with established OEMs to bypass homologation timeline disadvantages and accelerate market entry. For Investors and Strategic Acquirers: Re-rating potential sits with independent service providers possessing skilled technician labor pools and genuine parts distribution relationships, given after-sales service unbundling acceleration across Lagos and Johannesburg industrial corridors. Long-term viability hinges on dual-fuel architecture capabilities and digital remote monitoring convergence. Acquisition focus should center on regional parts distribution networks and exhaust after-treatment retrofit specialists. Deviation in Gulf Standardization Organization emission threshold alignment with EU Stage V would shift the competitive outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Architecture Development | Preserves fuel optionality for Saudi Aramco marine terminals and UAE port authorities facing emission restrictions. |
| Regional Assembly Localization | Compresses lead times for African power generation customers and reduces logistics exposure. |
| After-Treatment Retrofit Services | Captures South African compliance-driven demand as National Regulator for Compulsory Specifications tightens enforcement. |
| IoT Predictive Maintenance Integration | Opens service contract opportunities across Nigeria's captive power installations and distributed mining assets. |
| Natural Gas Pipeline Alignment | Positions for Ethiopia's industrial park buildout where grid infrastructure remains deficient. |
Research Methodology
Multi-period observation of fleet renewal cycles, emission certification timelines, and procurement specification shifts anchored the trend analysis, supplemented by interviews with utility planning officers, mining maintenance directors, marine fleet managers, and aftermarket service heads. Primary fieldwork combined with secondary validation from Gulf Standardization Organization harmonization documents, South African Bureau of Standards testing protocols, customs and trade data on engine block imports, and utility procurement disclosure records. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Input-output matrices mapped fuel type, engine architecture, and application dimensions against regional infrastructure maturity and regulatory stringency across the projection horizon. Segmentation dimensions included end-user category, fuel configuration, physical engine type, and geographic regulatory cluster. CAGRs derived from fitted trend extrapolation validated against industry stakeholder consensus on replacement cycle compression and dual-fuel adoption trajectories. Forecast inputs incorporated pipeline infrastructure buildout schedules, grid reliability indices, and carbon border adjustment policy development.
Revisions become necessary when battery energy storage cost curves accelerate displacement of diesel generator sets, Gulf Standardization Organization emission thresholds diverge from EU Stage V alignment, or carbon border adjustment mechanisms reshape North African manufacturing hub export eligibility. Deviation in dual-fuel architecture adoption rates or natural gas pipeline distribution expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
High Speed Engine Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Axle Shaft Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Automotive Camless Engine Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Timing Belt Market
Powertrain
Automotive Turbocharger Market
Powertrain
Transmission Control System Market