
 Iran Automotive Lubricants Market | 2026-2036
Iran Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Automotive Lubricants Market Foresight
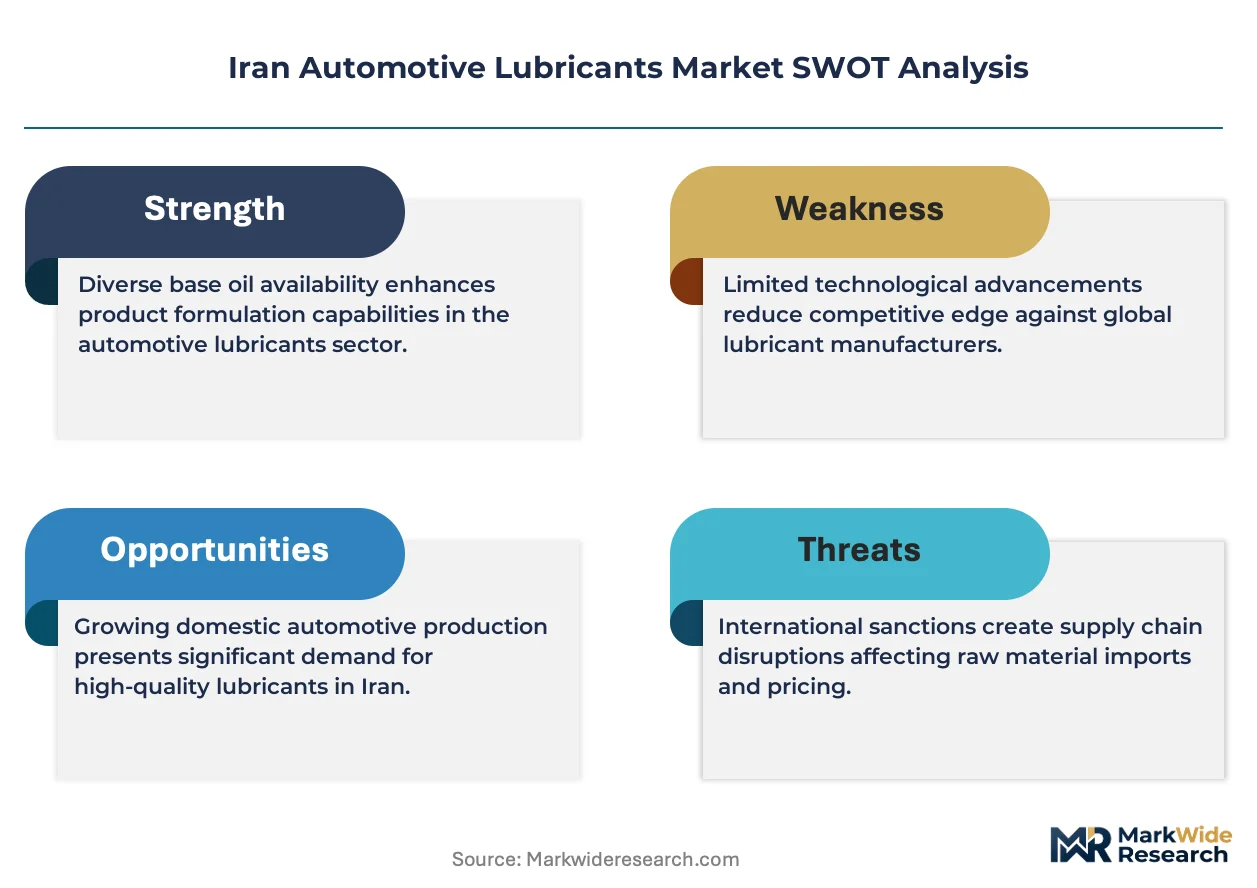
Multi-source procurement from domestic blenders is repositioning supply security for Iranian workshops and fleet operators. Behran Oil Company leverages captive refining capacity to secure base stock supply. Iranol Oil Company anchors its position through broad distribution across provincial service networks. Pars Oil Company competes on price in the volume-driven engine oil segment.
Automotive lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines and drivetrains; typical engine oils contain viscosity modifiers, detergents, and anti-wear chemistries measured by SAE grade and API service classification. The product type dimension shows engine oil commanding the largest volume share due to universal applicability across vehicle classes, while gear oil generates disproportionate margin contribution from commercial and heavy-duty applications. Application segmentation reveals passenger vehicles as the mature volume base, with heavy-duty trucks representing the fastest structural expansion as logistics fleet renewal accelerates.
Iran's national standardization organization (INSO) mandates lubricant labeling and quality certification, while the Ministry of Industry, Mine and Trade oversees import substitution policies that protect domestic blenders. These frameworks elevate compliance costs for unofficial imports while creating protected runway for local formulators to scale. Stakeholders must monitor base oil import license flexibility and domestic additive blending capacity as decisive variables for margin sustainability.
Market Dynamics
Fleet operators in Iran are consolidating preventive maintenance contracts around certified lubricant suppliers, compressing procurement cycles and elevating quality compliance as the decisive competitive filter for domestic blenders.
Growth Catalysts
- INSO Quality Mandates:Iran's national standardization body enforces API-aligned certification, disqualifying gray-market imports and expanding addressable market share for compliant domestic formulators.
- Heavy-Duty Fleet Renewal:Logistics operators are replacing aging truck populations, amplifying demand for high-performance diesel engine oils and extended-drain formulations.
- Tehran Industrial Corridor Density:Vehicle concentration in Iran's capital region creates service infrastructure economies that accelerate aftermarket lubricant throughput.
Market Restraints
- Base Oil Import Dependency:Iranian blenders rely on licensed imports of Group II/III base stocks, exposing margin stability to foreign exchange volatility and license approval delays.
- Additive Supply Concentration:Performance additive packages concentrate among a limited set of international suppliers, creating formulation bottlenecks during supply disruptions.
- Synthetic Substitution Economics:Extended-drain synthetic formulations threaten volume-based revenue models by reducing per-vehicle consumption frequency.
Strategic Opportunities
- Provincial Network Expansion:Underpenetrated service corridors in Khorasan and Fars provinces offer first-mover positioning for distribution infrastructure investment.
- Hybrid Powertrain Formulations:Emerging dual-clutch and mild-hybrid architectures require specialized thermal management fluids, opening premium product development lanes.
- Import Substitution Incentives:Ministry of Industry, Mine and Trade policies protect domestic blending capacity, enabling scaled production of previously imported specialty grades.
Industry Challenges
- Formulation Chemist Scarcity:Domestic technical talent pools lack depth in advanced additive chemistry and tribology, constraining R&D velocity for next-generation products.
- Certification Timeline Compression:INSO testing protocols and API license acquisition create extended product launch cycles that lag behind formulation readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Automotive Lubricants Market |
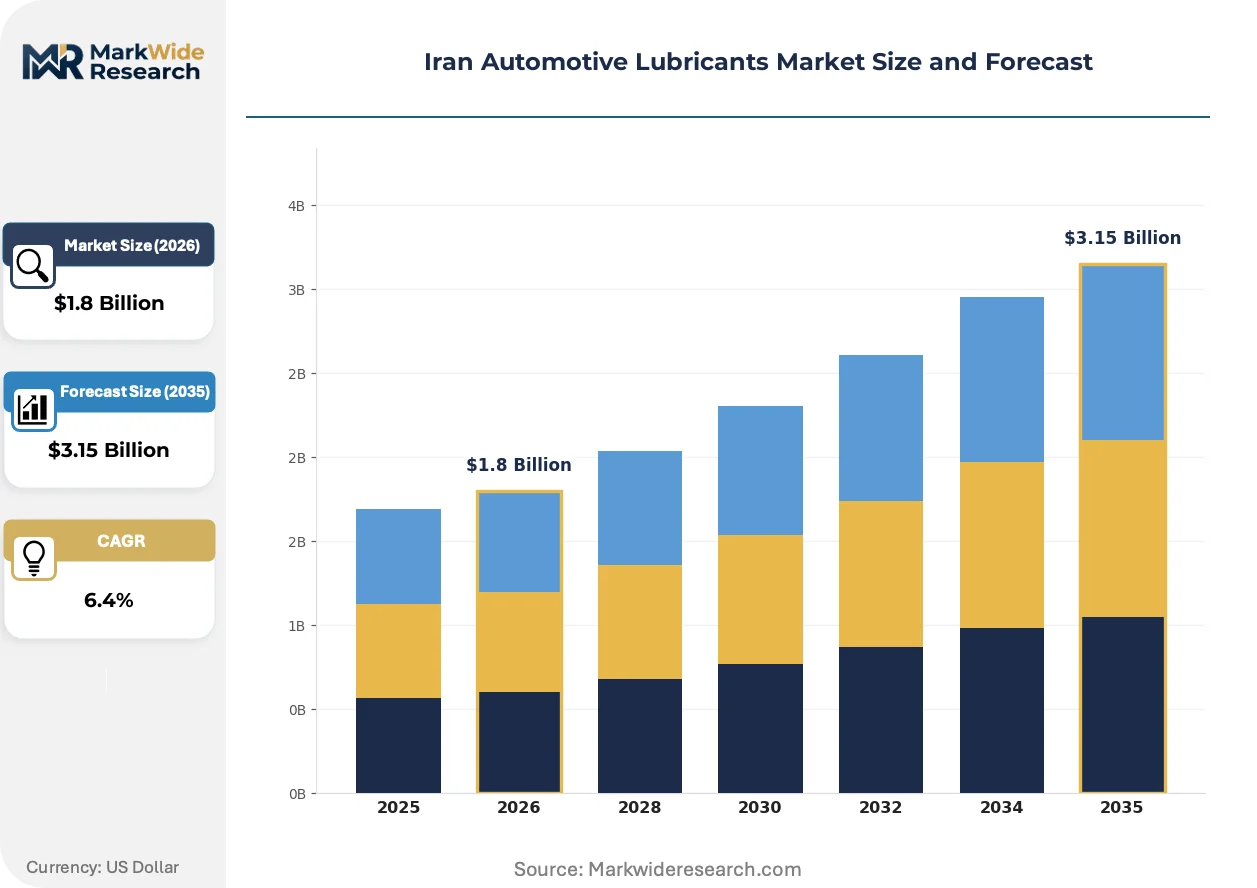
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Distribution Channel: Retail Outlets, Online Platforms, Wholesale Distributors, Service Stations Customer Type: Private Owners, Fleet Operators, Workshops, OEMs |
| Companies Covered | Behran Oil Company, Iranol Oil Company, Pars Oil Company, Pardis Engine Oil Company, Sepahan Oil Company, Ghatran Kaveh Motor Oil Co, AZAR RAVAN SAZ (Petronol), Asiajole Factory, Sanat Farzan Chemical Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Automotive Lubricants Market Shifts & Advancements
Formulation chemistry and procurement architecture are undergoing parallel transformation, with electrification-adjacent fluid requirements and consolidated fleet purchasing rewriting competitive rules for Iranian blenders.
Low-viscosity 0W-20 and 5W-30 engine oils are penetrating passenger vehicle service bays as OEM fill specifications tighten. Iranian workshops serving Peugeot and domestic-brand fleets are adopting these grades to align with warranty retention requirements. This viscosity downsizing is electrifying demand for high-quality base oil feedstocks that maintain film strength at reduced thickness.
INSO labeling enforcement is tightening traceability requirements across the lubricant value chain. Domestic blenders must now document base oil origin and additive package certification, elevating compliance investment but squeezing informal competitors. The aftermarket segment is responding fastest, with Tehran-based distributors prioritizing certified inventory to avoid penalty exposure.
Workshop procurement is consolidating around annual service contracts rather than spot purchasing. Fleet managers in Iran's commercial transport sector are unbundling lubricant supply from mechanical labor, negotiating direct volume agreements with blenders. This disintermediation is most visible in Isfahan's trucking corridors, where large operators now source bulk engine oil independent of traditional retail channels.
Iran Automotive Lubricants Market Segmentation
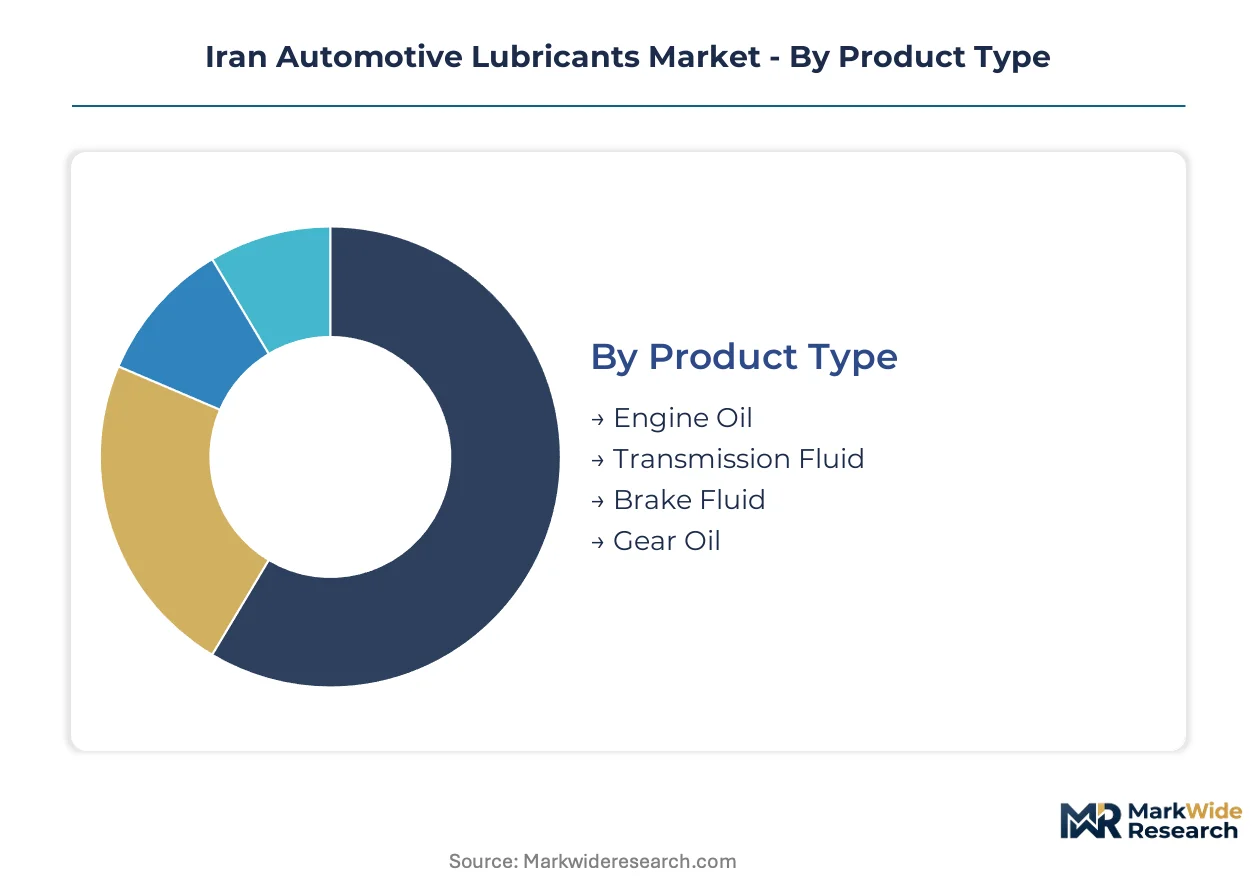
Segmentation in Iran's automotive lubricants market reveals how formulation specifications, vehicle duty cycles, and procurement channels create distinct competitive arenas for domestic blenders. Understanding these divisions exposes where margin pools concentrate and where volume expansion opportunities sit.
Product Type:
Viscosity grades and additive packages define performance tiers across lubricant categories, with SAE specifications and API service classifications determining compatibility and drain intervals.
- Engine Oil:Formulated from base oil blends with detergents, dispersants, and anti-wear additives, these lubricants reduce friction and control deposits in internal combustion engines. Tehran's dense passenger vehicle population and heavy-duty trucking corridors generate concentrated demand for both mineral and synthetic grades, with fleet operators prioritizing extended-drain formulations to compress maintenance downtime.
- Gear Oil:High-viscosity lubricants containing extreme-pressure additives protect differentials and manual transmissions under load stress. Commercial transport operators in Isfahan's logistics hubs specify these grades for axle longevity, creating margin concentration in the heavy-duty segment despite smaller volume relative to engine oils.
- Transmission Fluid:Specialized formulations for automatic and dual-clutch systems manage heat transfer and clutch friction coefficients.
- Brake Fluid:Hygroscopic glycol-ether or silicone-based fluids maintaining hydraulic system integrity across temperature extremes.
Engine oil leads on scale; gear oil leads on momentum.
Application:
Vehicle duty cycles and operating environments dictate lubricant stress profiles, with thermal load and contamination exposure varying sharply across transport modes.
- Passenger Vehicles:Light-duty gasoline engines in Tehran's stop-start traffic conditions require low-viscosity 0W-20 and 5W-30 grades that balance fuel economy with wear protection. Peugeot and domestic-brand service networks anchor volume demand, though synthetic substitution is compressing per-vehicle consumption frequency.
- Heavy-Duty Trucks:Diesel engines operating long-haul routes through Iran's high-altitude corridors face thermal degradation and soot loading challenges. Fleet renewal programs in the commercial logistics sector are amplifying demand for CJ-4/CK-4 certified heavy-duty engine oils with extended drain capabilities.
- Commercial Vehicles:Mid-duty applications including vans and light trucks serving urban delivery routes.
- Two-Wheelers:Small-displacement engines in motorcycles and scooters requiring single-grade or multi-grade mineral oils.
Passenger vehicles dominate current volume; heavy-duty trucks are climbing the fastest.
Distribution Channel:
Procurement architecture is shifting from fragmented spot purchasing toward consolidated supply agreements, rewiring how lubricants reach end-users.
- Wholesale Distributors:Regional inventory hubs supplying provincial service networks and independent workshops across Khorasan and Fars provinces. These intermediaries aggregate volume from domestic blenders and extend credit terms that smaller retail channels cannot match.
- Service Stations:Branded quick-lube facilities and OEM-affiliated service centers performing scheduled maintenance. Tehran's industrial corridor concentrates these outlets, with certified suppliers capturing preventive maintenance contracts from fleet operators unbundling lubricant supply from mechanical labor.
- Retail Outlets:Automotive parts stores and general merchandise channels serving private owner DIY segments.
- Online Platforms:Emerging e-commerce channels for bulk and specialty lubricant procurement.
Wholesale distributors hold the broadest geographic footprint; service stations are gaining share fastest.
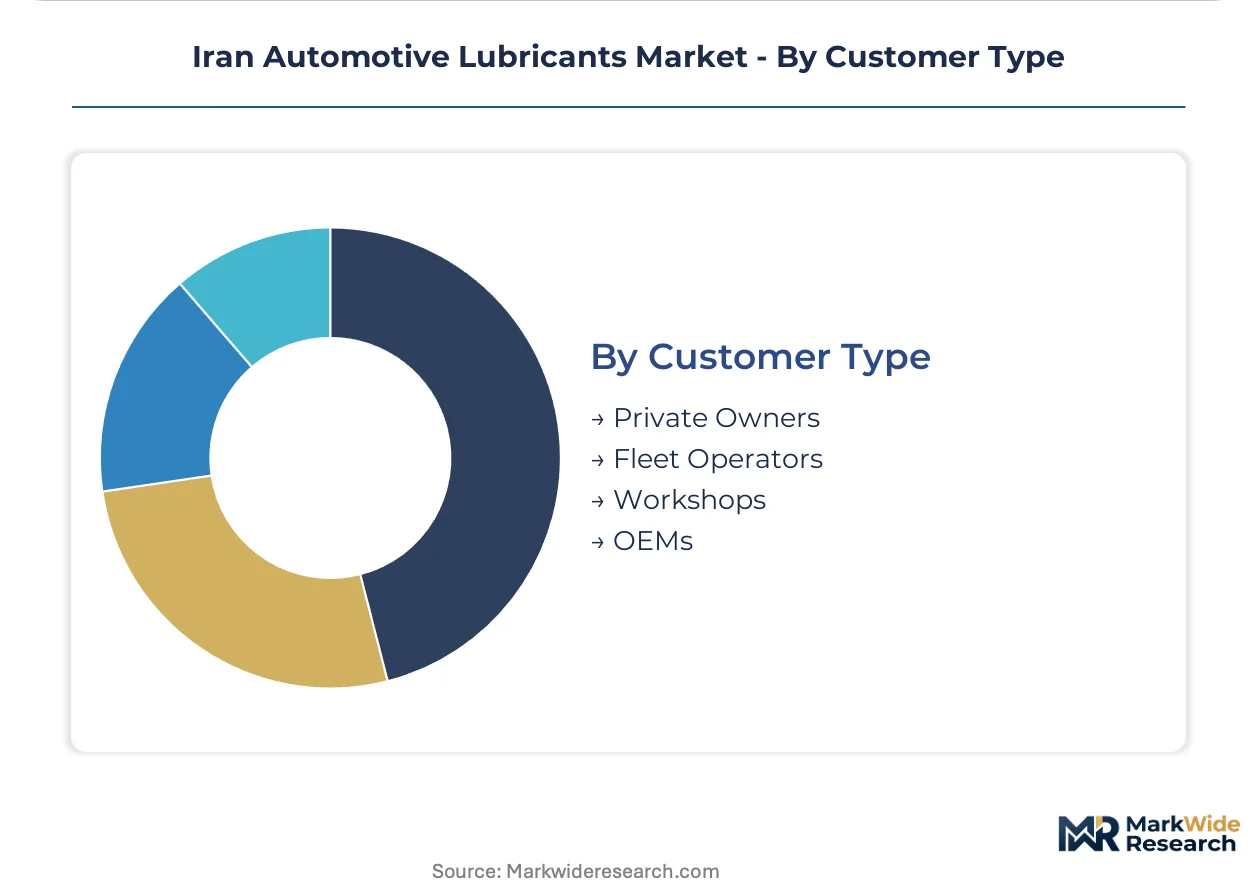
Customer Type:
Procurement sophistication and volume scale separate lubricant buyers, with contract structures and technical specifications diverging across user categories.
- Fleet Operators:Large commercial transport companies negotiating direct annual supply agreements with domestic blenders, bypassing traditional retail markup. These buyers mandate INSO-certified inventory and impose penalty clauses for off-specification deliveries, compressing supplier margins while securing volume commitments.
- Workshops:Independent and franchise service centers consolidating procurement around certified suppliers to align with warranty retention requirements and avoid INSO enforcement exposure.
- Private Owners:Individual vehicle owners purchasing lubricants through retail channels or service bundling.
- OEMs:Vehicle manufacturers specifying first-fill and service-fill lubricants for warranty compliance.
Fleet operators command the steepest volume concentration; workshops show the strongest procurement consolidation trend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tehran's industrial corridor concentrates Iran's automotive lubricant demand through dense vehicle populations and aftermarket service infrastructure clustering. Provincial networks in Khorasan and Fars remain underpenetrated relative to the capital region. Domestic blenders leverage captive refining capacity to secure base stock supply across these geographic tiers.
Tehran Province
Tehran's stop-start traffic conditions drive demand for low-viscosity 0W-20 and 5W-30 grades among Peugeot and domestic-brand service networks. INSO labeling enforcement tightens traceability requirements across lubricant value chains in the capital. The city's industrial corridor generates concentrated aftermarket throughput, with fleet operators consolidating preventive maintenance contracts around certified suppliers.
Isfahan Province
Isfahan's logistics hubs specify high-viscosity gear oils for axle longevity in heavy-duty commercial transport operations. The Ministry of Industry, Mine and Trade oversees import substitution policies that protect domestic blenders serving this corridor. Fleet renewal programs in Isfahan's trucking corridors amplify demand for CJ-4/CK-4 certified heavy-duty engine oils with extended drain capabilities.
Khorasan Province
Khorasan's underpenetrated service corridors offer first-mover positioning for distribution infrastructure investment by domestic formulators. INSO quality mandates disqualify gray-market imports, expanding addressable market share for compliant suppliers entering this region. Wholesale distributors aggregate volume from domestic blenders to extend credit terms that smaller retail channels cannot match across provincial service networks.
Fars Province
Fars province presents expansion opportunities for certified lubricant distribution beyond Tehran's saturated infrastructure. The national standardization organization's API-aligned certification requirements elevate compliance costs for unofficial imports in this region. Regional inventory hubs supply independent workshops, with Tehran-based distributors prioritizing certified inventory to avoid penalty exposure.
East Azerbaijan Province
East Azerbaijan's industrial base generates demand for specialized thermal management fluids as commercial vehicle populations age. Domestic blenders rely on licensed imports of Group II/III base stocks, exposing margin stability to foreign exchange volatility in this northwestern region. Provincial service networks remain fragmented, creating runway for scaled production of previously imported specialty grades under import substitution incentives.
Iran Automotive Lubricants Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution reach, though Iranian market structure favors domestic blenders shielded by import substitution policies. The competitive arena segments into captive refiners with backward-integrated base oil supply, provincial network specialists, and price-competitive volume players. Strategic archetypes include integrated refiners controlling upstream feedstocks, distributors anchoring geographic coverage, and formulators competing on technical certification. Dominant competitive moves center on provincial network expansion and direct fleet contracting to bypass traditional retail markup.
Among Tehran-based integrated refiners, Behran Oil Company and Iranol Oil Company exemplify the captive supply archetype, leveraging in-house production of base stocks to secure formulation inputs. Pars Oil Company occupies a position within the price-competitive volume tier, representing domestic challengers focused on engine oil segments where scale economics dominate procurement decisions. These three anchors illustrate how Iranian market structure rewards vertical control over feedstocks, geographic density in distribution, and cost positioning in high-volume categories.
| Leading Market Players |
|---|
| Behran Oil Company |
| Iranol Oil Company |
| Pars Oil Company |
| Pardis Engine Oil Company |
| Sepahan Oil Company |
| Ghatran Kaveh Motor Oil Co |
| AZAR RAVAN SAZ (Petronol) |
| Asiajole Factory |
| Sanat Farzan Chemical Company |
| Others |
Supply & Pricing Matrix
API certification tiers in Iran's lubricant market bifurcate sharply between INSO-validated premium formulations and uncertified economy grades, with this quality ladder dictating both margin capture and procurement channel configurations across Tehran's industrial corridor and provincial networks.
Pricing Analysis
Base oil import costs pass through directly to finished lubricant pricing, with Group II/III feedstock volatility compressing blender margins on synthetic grades. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fleet scale and warranty compliance requirements. Pricing pressure stems from synthetic substitution reducing per-vehicle consumption frequency. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while independent workshops face acute margin compression.
Supply Chain Analysis
INSO certification gating restricts import channels to licensed distributors, elevating compliance investment for market entry. Base oil supply draws from South Korea, the UAE, and Turkey as primary source markets. Additive packages hinge on concentrated international suppliers, creating formulation bottlenecks during disruptions. Tehran-based wholesale distributors anchor downstream reach, extending credit terms that bypass traditional retail markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's automotive lubricants market compounds steadily as fleet renewal programs and INSO enforcement expand the certified product addressable base. Preventive maintenance contract consolidation anchors recurring revenue visibility for compliant suppliers.
For Market Incumbents: Deploy captive refining capacity to secure base oil supply against import license volatility. Expand direct fleet contracting in Isfahan's trucking corridors to disintermediate wholesale markup. Invest in CJ-4/CK-4 certification capacity to capture heavy-duty diesel demand acceleration. Channel control through annual service agreements defends against price-competitive volume challengers.
For New Entrants and Emerging Players: A 30-40% price-point gap between API-certified synthetics and mineral economy grades opens white-space in mid-tier semi-synthetic formulations. Target Khorasan and Fars provincial networks where certified distribution remains underpenetrated relative to Tehran. Enter through workshop procurement consolidation, offering INSO-compliant inventory with extended credit terms that match incumbent distributor economics.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity and certification timeline compression constrain R&D velocity for mid-tier blenders. Five-to-ten-year viability favors integrated refiners with backward base oil control and established provincial distribution footprints. Watch base oil import license flexibility as the decisive inflection signal for margin sustainability across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Distribution Network Expansion | Khorasan and Fars corridors offer first-mover positioning beyond Tehran's saturated infrastructure. |
| INSO Certification Investment | API-aligned validation disqualifies gray-market imports, expanding compliant supplier market share. |
| Direct Fleet Contracting | Annual supply agreements with logistics operators bypass wholesale markup and secure volume commitments. |
| Synthetic Formulation Capacity Addition | Extended-drain products capture heavy-duty fleet renewal demand in Isfahan's trucking corridors. |
| Additive Package Partnership | International supplier relationships reduce formulation bottlenecks during supply disruptions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant procurement managers at fleet operators, technical directors at domestic blenders, wholesale distribution heads, and INSO compliance officers with secondary validation. Trade customs data, Ministry of Industry regulatory filings, base oil import license records, and vehicle registration databases anchored volume estimation. Bottom-up channel throughput triangulated against top-down lubricant consumption models.
Historical reference periods anchored the projection horizon across multi-year modeling windows. Segmentation dimensions included product viscosity grade, vehicle duty cycle classification, distribution channel tier, and provincial geographic cluster. CAGRs derived from regression analysis against fleet population growth, drain interval extension trends, and synthetic penetration curves. Forecast inputs incorporated INSO enforcement intensity indices and base oil import license approval velocity.
Caveats apply where foreign exchange volatility or additive supply disruptions could materially shift the outlook. Forecasts reflect assumptions around continued INSO certification mandate enforcement and stable fleet renewal program funding. Deviation in base oil import license flexibility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Automotive Glass Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automated Lubrication Systems Market