
 Automotive V-Belts Market | 2026-2036
Automotive V-Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive V-Belts Market Analytics
Subscription-based fleet maintenance programs is broadening the addressable base for automotive V-belt suppliers beyond traditional spot replacement. Gates Corporation leverages its captive distribution network to secure long-term service contracts with North American logistics fleets. Continental AG anchors its position through backward integration into synthetic rubber compounding for heat-resistant belt formulations. Mitsuboshi Belting Ltd competes on manufacturing scale across Southeast Asian assembly plants.
Automotive V-Belts are trapezoidal-section power transmission elements manufactured from chloroprene or ethylene propylene diene monomer rubber reinforced with polyester or aramid tensile cords, engineered to transfer torque from engine crankshafts to accessory pulleys in internal combustion and mild-hybrid drivetrains. Raw Edge V-Belts command margin pools in high-temperature engine bays where reduced bending resistance improves accessory-drive efficiency. Multi-V-Belts sustain volume leadership as serpentine configurations consolidate multiple accessories under single-belt architectures across OEM engine platforms. Cogged V-Belts occupy the fastest-growing material slot where notched profiles reduce heat buildup in stop-start urban duty cycles.
The US EPA enforces Corporate Average Fuel Economy standards that penalize accessory-drive parasitic losses, while the EU F-Gas Regulation and REACH restrict chlorofluorocarbon-based manufacturing solvents in European-sourced rubber compounds. India's BIS mandates tensile-strength certification for aftermarket belts sold through formal channels, compressing informal supplier access. Stakeholders must monitor regulatory divergence between thermal-efficiency mandates and material-restriction frameworks when configuring regional product portfolios.
Market Dynamics
Fleet operators are consolidating maintenance spend under long-term service contracts, compressing spot-replacement volumes while elevating specification requirements for heat-resistant belt formulations across commercial vehicle segments.
Growth Catalysts
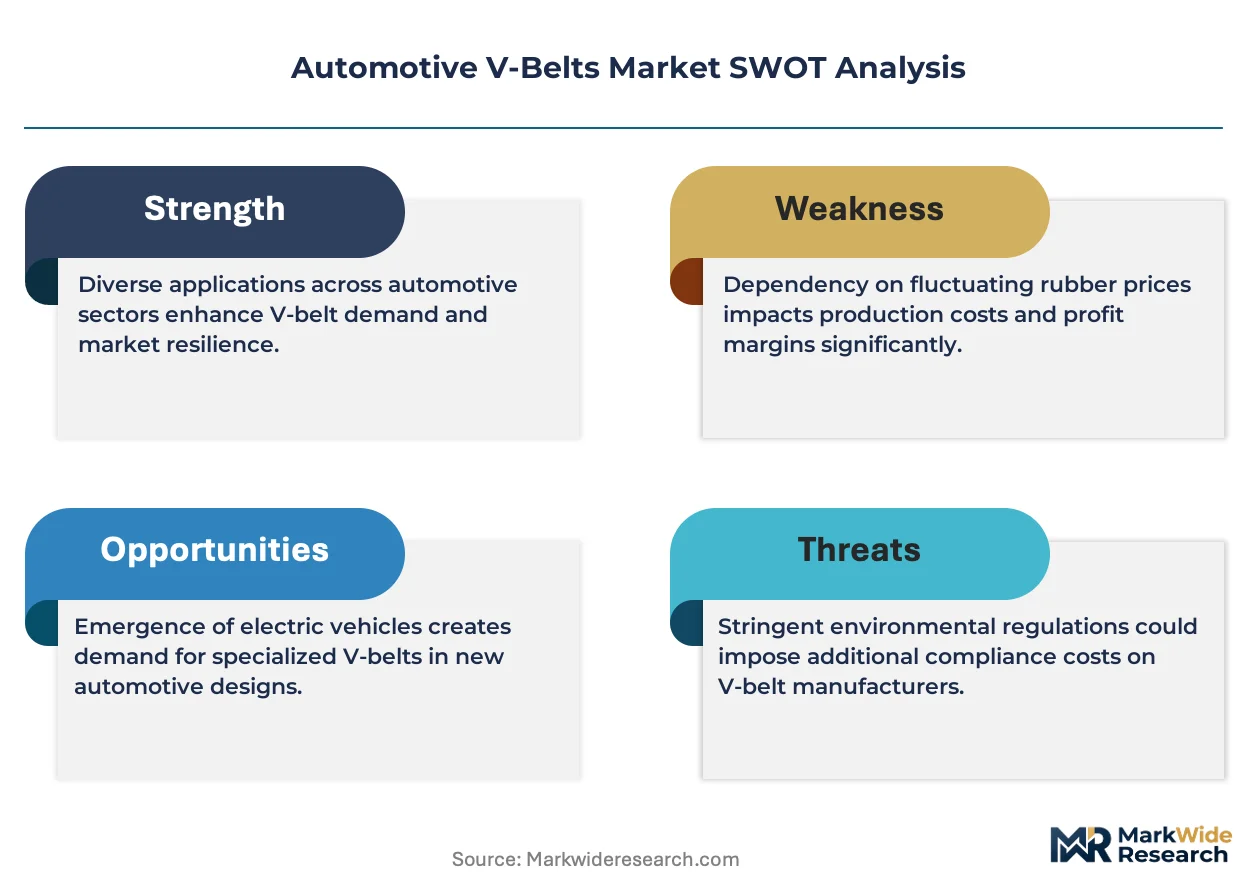
- Euro 7 Emissions Frameworks:Tightening accessory-drive efficiency mandates force OEMs to specify low-friction belt geometries, expanding premium product penetration across European engine platforms.
- India Commercial Vehicle Density:Formal aftermarket channel expansion under BIS tensile-strength certification compresses informal supplier access, concentrating volume with certified domestic manufacturers.
- Stop-Start Urban Duty Cycles:Cogged V-Belt architectures reduce heat buildup in congested operating conditions, displacing conventional raw-edge designs in metropolitan fleet specifications.
Market Restraints
- Synthetic Rubber Price Volatility:Chloroprene and EPDM feedstock costs fluctuate with petrochemical indices, compressing margin stability for compound-dependent manufacturers.
- Southeast Asian Supply Concentration:Mitsuboshi Belting and regional competitors anchor production in Thailand and Indonesia, creating geographic risk exposure for buyers seeking supply diversification.
- Serpentine Belt Consolidation:Multi-V-Belt architectures reduce per-vehicle belt counts from 3-4 units to single-belt configurations, structurally limiting unit volume expansion.
Strategic Opportunities
- Mild-Hybrid Accessory Electrification:Belt-driven starter-generator integration creates demand for reinforced tensile cord specifications in 48V architectures.
- Subscription Fleet Maintenance:North American logistics operators are unbundling belt replacement from general service contracts, opening dedicated supplier-direct channels.
- EPA Fuel-Economy Penalty Avoidance:Accessory-drive parasitic loss reduction mandates incentivize OEM specification of advanced belt materials with lower bending resistance.
Industry Challenges
- Aramid Cord Processing Expertise:Heat-resistant tensile reinforcement requires specialized vulcanization controls that concentrate technical talent with established compounders.
- REACH Solvent Transition:Chlorofluorocarbon-based manufacturing process replacement demands capital retooling for European regulatory compliance without production interruption.
- Aftermarket Counterfeit Detection:BIS certification enforcement capacity constraints allow non-compliant belt circulation through informal Indian distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive V-Belts Market |
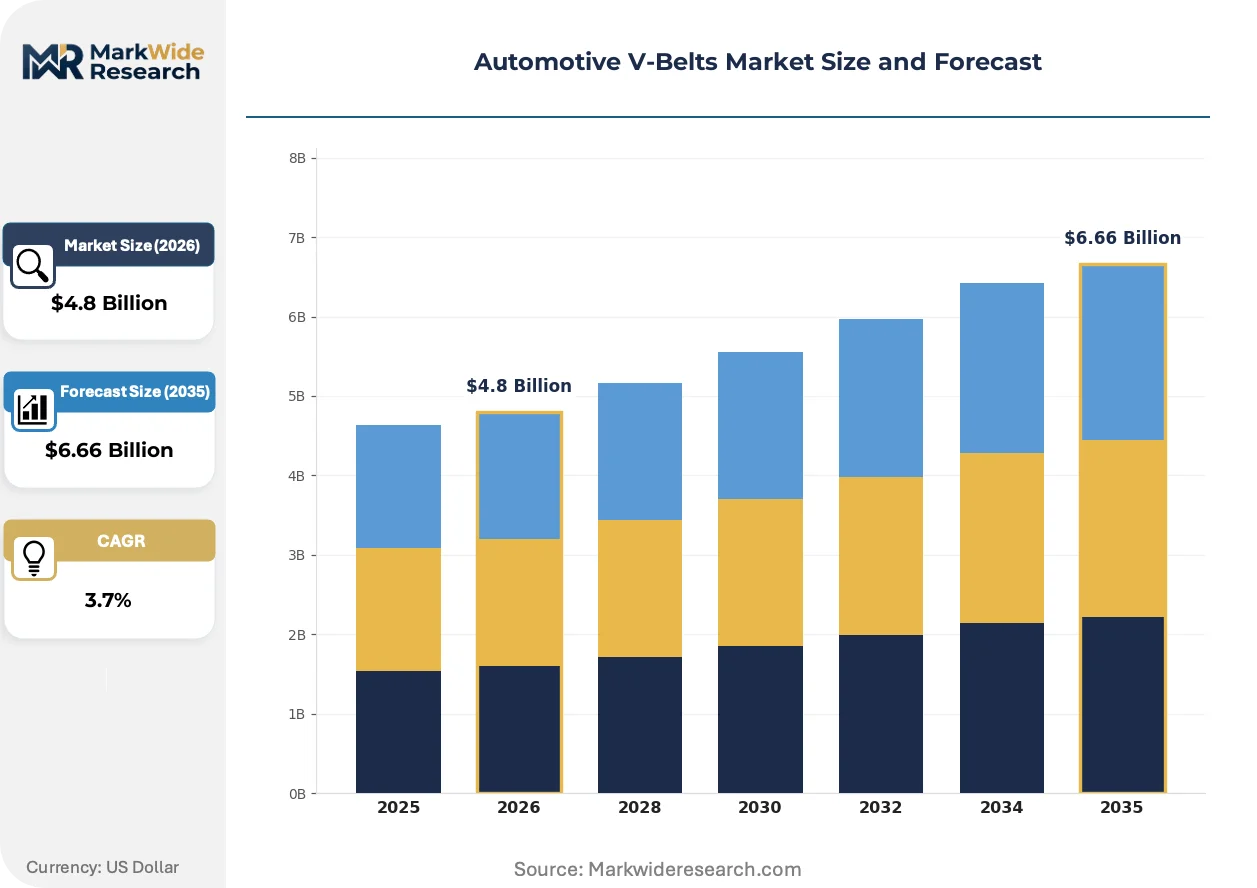
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrapped V-Belts, Raw Edge V-Belts, Cogged V-Belts, Multi-V-Belts End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Material: Rubber, Polyurethane, Polyester, Fiberglass Installation Type: Manual Installation, Automated Installation, Semi-Automated Installation, DIY |
| Companies Covered | Gates Corporation, Continental AG, Mitsuboshi Belting Ltd, Hutchinson SA, Dayco IP Holdings LLC, Bando Chemical Industries Ltd, SKF Group, Schaeffler AG, Optibelt GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive V-Belts Market Evolving Landscape
Material science advances and regulatory efficiency mandates are converging to redefine belt specification criteria across OEM and aftermarket channels, with thermal performance emerging as the primary competitive differentiator.
Aramid-reinforced tensile cord technology is electrifying competitive positioning in high-temperature engine bay applications. Fleet operators operating in desert climates and heavy-load conditions specify aramid-cogged configurations for reduced stretch and extended service intervals. This material transition is compressing market share for conventional polyester-reinforced alternatives in premium specification tiers.
REACH restrictions on chlorofluorocarbon-based manufacturing solvents are forcing compound reformulation across European-sourced rubber production. Belt manufacturers are investing in aqueous-based vulcanization processes to maintain market access under ECHA enforcement timelines. Heat-resistant EPDM formulations are capturing specification preference as chloroprene alternatives face supply chain scrutiny.
North American logistics fleets are unbundling preventive maintenance components from bundled service agreements. Dedicated belt replacement contracts are displacing generalist mechanic procurement through direct supplier engagement. This channel restructuring concentrates volume with manufacturers maintaining captive distribution infrastructure and technical field support capabilities.
Automotive V-Belts Market Segmentation
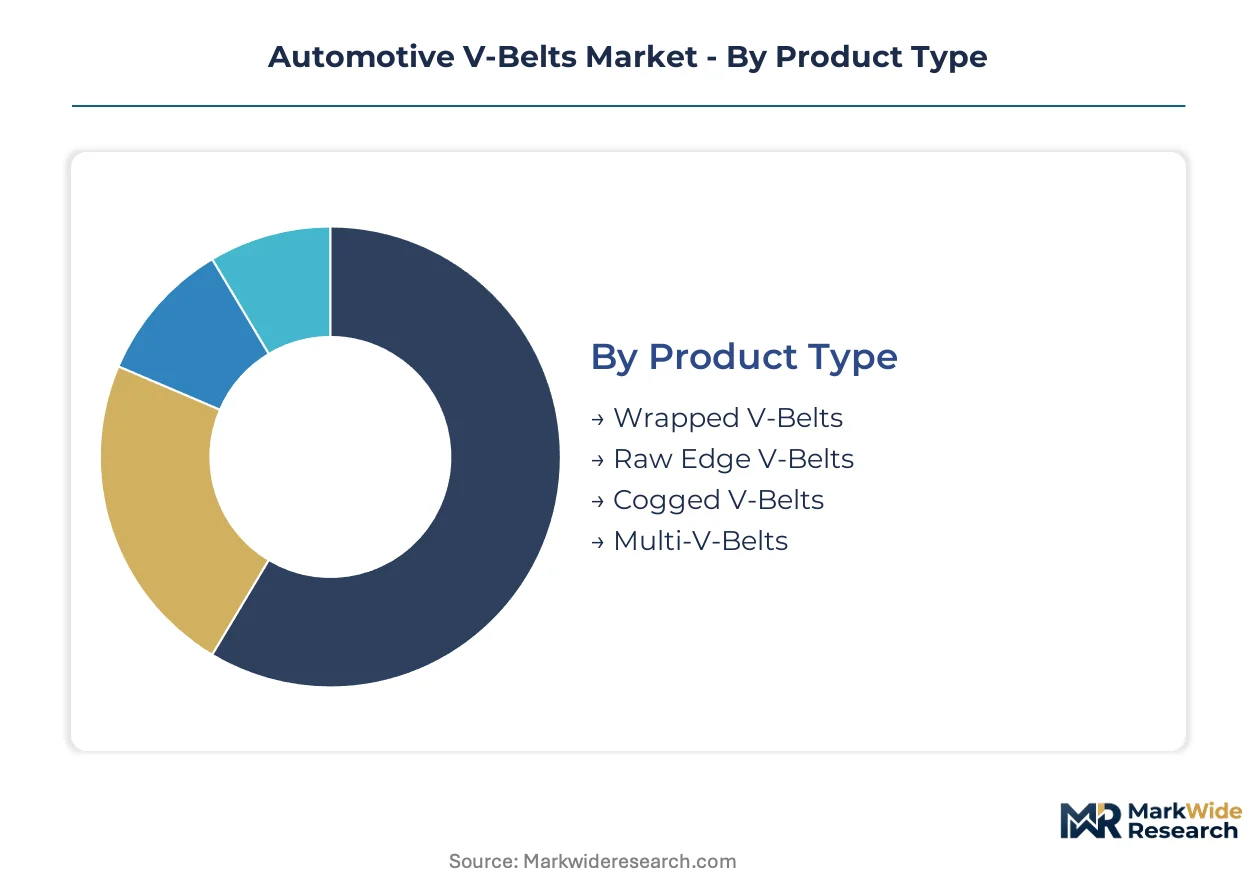
Automotive V-Belt segmentation maps directly to specification hierarchies that govern thermal performance, service intervals, and regulatory compliance across engine architectures. Understanding these category boundaries clarifies where margin pools concentrate and which material transitions are displacing incumbent technologies.
Product Type:
Technology differentiation separates legacy wrapped constructions from advanced geometries engineered for accessory-drive efficiency mandates.
- Multi-V-Belts:Serpentine configurations consolidate multiple accessory drives under single-belt architectures, reducing per-vehicle component counts. OEM specification concentrates in European and North American engine platforms facing EPA and Euro 7 parasitic-loss penalties.
- Cogged V-Belts:Notched profiles reduce bending resistance and heat accumulation in stop-start urban duty cycles. Fleet operators in congested metropolitan corridors specify these for extended service intervals under preventive maintenance contracts.
- Raw Edge V-Belts:Precision-molded sidewalls without fabric wrapping improve heat dissipation in high-temperature engine bays.
- Wrapped V-Belts:Fabric-covered constructions dominate legacy aftermarket replacement for older vehicle parc.
Mature deployment sits with Wrapped V-Belts. Newer deployment is concentrated in Cogged V-Belt specifications.
End User:
Procurement authority splits between factory-fit specification and replacement-channel economics, with diverging technical requirements.
- Fleet Operators:Consolidated maintenance spend under long-term service contracts elevates heat-resistant formulation requirements. North American logistics fleets unbundle belt replacement from general service agreements, opening direct supplier channels.
- OEMs:Factory-fit specification demands low-friction geometries compliant with tightening fuel-economy standards. Design-in decisions lock in compound and cord specifications for entire engine platform lifecycles.
- Aftermarket Providers:Channel fragmentation concentrates volume with certified distributors in regulated markets.
- Vehicle Assemblers:Contract manufacturing relationships prioritize supply security over specification innovation.
Volume leadership rests with OEMs. Margin expansion is concentrated in Fleet Operators.
Material:
Compound selection determines thermal ceiling, flex fatigue resistance, and regulatory compliance under REACH solvent restrictions.
- Rubber:Chloroprene and EPDM formulations anchor volume production, with heat-resistant EPDM gaining preference as chloroprene faces supply chain scrutiny. REACH-compliant aqueous vulcanization processes are retooling European-sourced production.
- Polyester:Standard tensile reinforcement for economy-tier specifications in high-volume replacement markets.
- Polyurethane:Abrasion-resistant compounds serve specialized industrial auxiliary drives.
- Fiberglass:High-modulus cord options for heavy-load commercial applications.
Specification density peaks with Rubber. Material transition momentum is concentrated in EPDM substitution trajectories.
Installation Type:
Service economics and labor cost structures determine channel preference across geographic markets.
- Manual Installation:Technician-dependent replacement dominates emerging market aftermarket channels where labor costs compress automation returns.
- Automated Installation:Robotic belt placement systems integrate with OEM assembly lines for serpentine configurations.
- Semi-Automated Installation:Guided tooling assists technician productivity in formal service networks.
- DIY:Consumer-direct replacement concentrates in light-duty passenger vehicle segments with accessible engine bays.
Channel control sits with Manual Installation. Efficiency investment is concentrated in Automated Installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Thailand and Indonesia while consumption concentrates in India and the United States. This geographic split shapes procurement patterns and regulatory exposure across the value chain.
United States
North American logistics fleets drive specification upgrades through unbundled preventive maintenance contracts. EPA Corporate Average Fuel Economy standards penalize accessory-drive parasitic losses, forcing OEMs toward low-friction belt geometries. Detroit-based automotive clusters anchor demand for heat-resistant formulations in commercial vehicle segments.
India
Commercial vehicle production expansion and formal aftermarket channel growth concentrate demand in Maharashtra and Tamil Nadu. BIS tensile-strength certification mandates compress informal supplier access, redirecting volume toward certified domestic manufacturers. Delhi-NCR serves as the compliance enforcement hub for aftermarket distribution networks.
Germany
EU F-Gas Regulation and REACH solvent restrictions force compound reformulation across European-sourced rubber production. Euro 7 emissions frameworks tighten accessory-drive efficiency requirements for OEM specification. Stuttgart and Munich industrial corridors host formulation R&D for heat-resistant EPDM alternatives.
Thailand
Southeast Asian manufacturing concentration creates geographic risk exposure for buyers seeking supply diversification. Mitsuboshi Belting anchors production scale across regional assembly plants serving export markets. Bangkok-Rayong industrial belt concentrates vulcanization capacity for chloroprene and EPDM formulations.
Japan
Aramid cord processing expertise concentrates technical talent with established compounders serving premium specification tiers. METI industrial standards govern tensile reinforcement quality for domestic OEM supply. Nagoya and Osaka manufacturing clusters specialize in high-temperature engine bay applications.
Automotive V-Belts Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across compound formulation and tensile cord engineering. The market structure consolidates around three tiers: integrated rubber compounders controlling upstream material supply, specialized belt manufacturers scaling Southeast Asian production, and captive distribution networks securing fleet service contracts. Strategic archetypes include backward-integrated material specialists, scale-driven Asian fabricators, and channel-integrated North American service providers. Competitive moves concentrate on aqueous vulcanization process retooling for REACH compliance and direct fleet contract acquisition bypassing traditional distribution.
Among German-based integrated suppliers, Continental AG exemplifies the backward-integrated archetype through synthetic rubber compounding capabilities. Gates Corporation occupies the channel-integrated position with captive distribution infrastructure securing North American logistics fleet contracts. Mitsuboshi Belting Ltd represents the scale-driven Asian manufacturer archetype with production concentration across Thailand and Indonesia.
| Leading Market Players |
|---|
| Gates Corporation |
| Continental AG |
| Mitsuboshi Belting Ltd |
| Hutchinson SA |
| Dayco IP Holdings LLC |
| Bando Chemical Industries Ltd |
| SKF Group |
| Schaeffler AG |
| Optibelt GmbH |
| Others |
Value Network & Pricing Analysis
Fleet operator consolidation of maintenance spend under long-term service contracts is compressing spot-replacement volumes and forcing suppliers to absorb specification upgrade costs for heat-resistant formulations. This procurement shift concentrates pricing power with buyers holding multi-year agreements while elevating technical compliance barriers for marginal producers.
Pricing Analysis
Cost-down pressure on economy-tier wrapped belts accelerates as BIS certification mandates in India compress informal supplier access and redirect volume toward certified domestic manufacturers. Three-tier pricing structure across premium aramid-reinforced, standard polyester, and economy wrapped constructions separates specifications by thermal ceiling and service interval guarantees. Price differentiation hinges on REACH-compliant aqueous vulcanization processes and aramid cord processing expertise. Fleet operators demonstrate lowest price sensitivity due to unbundled preventive maintenance contracts, while informal aftermarket channels in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing qualification requirements from North American OEMs are forcing buyers to diversify beyond Thailand and Indonesia manufacturing concentration toward secondary production in Japan and Germany. Raw material dependencies draw from chloroprene and EPDM rubber feedstocks, polyester and aramid tensile cords, and sulfur-based vulcanization agents. Single-source vulnerability concentrates around Mitsuboshi Belting's Southeast Asian production scale. Distribution runs through captive supplier-direct channels for fleet contracts and certified distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH solvent restrictions and BIS tensile-strength certification create regulatory moats that reward compound reformulation investment and punish informal competitors.
For Market Incumbents: Anticipate EPDM substitution trajectories displacing chloroprene formulations by accelerating aqueous vulcanization retooling ahead of ECHA enforcement timelines. Defend margin position through backward integration into synthetic rubber compounding and captive distribution infrastructure securing long-term fleet service contracts against emerging Asian scale competitors.
For New Entrants and Emerging Players: Enter via aftermarket certification gaps in India's formal channel expansion under BIS mandates, where enforcement capacity constraints allow non-compliant belt circulation. Target metropolitan fleet operators specifying cogged V-Belt architectures for stop-start urban duty cycles. Pursue direct supplier engagement models unbundling belt replacement from generalist mechanic procurement.
For Investors and Strategic Acquirers: The window for entry favors compounders possessing aramid cord processing expertise and REACH-compliant production infrastructure. Long-term viability rests on technical talent concentration with established vulcanization controls rather than pure manufacturing scale. Watch for inflection in EPA fuel-economy penalty enforcement intensity driving OEM specification of low-friction belt geometries.
| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Vulcanization Retooling | REACH-compliant process investment secures European market access under ECHA enforcement timelines. |
| Aramid Cord Specification Expansion | Desert climate fleet demand for reduced stretch reinforces premium tier margin pools. |
| Captive Distribution Infrastructure | Direct fleet contract acquisition bypasses traditional aftermarket channel fragmentation. |
| EPDM Formulation Scale-Up | Heat-resistant compound substitution captures specification preference as chloroprene faces scrutiny. |
| Dual-Sourcing Qualification | Secondary production sites in Japan and Germany mitigate geographic concentration risk for OEM buyers. |
Research Methodology
Trade databases, customs records, and vehicle production registries formed the secondary backbone for volume estimation across regional manufacturing clusters. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors validated specification trends and channel restructuring patterns. Bottom-up belt consumption modeling triangulated against top-down automotive production forecasts across the analysis window.
Historical trendline analysis of compound formulation transitions and serpentine belt adoption rates informed projection assumptions. Segmentation dimensions modeled include product type, material composition, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA fuel-economy penalty exposure and Euro 7 accessory-drive efficiency mandates. Industry-specific inputs encompassed BIS certification enforcement capacity and REACH solvent transition timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under synthetic rubber price volatility and geopolitical disruption to Southeast Asian manufacturing. Model outputs reflect assumptions regarding fleet contract unbundling velocity and mild-hybrid 48V architecture penetration. A model refresh is warranted upon material change in ECHA enforcement intensity or BIS aftermarket certification capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brake Tube Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive Silencer Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Automotive Subframe Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
China Automotive Actuators Market