
 Automotive Fuel Injection System Market | 2026-2036
Automotive Fuel Injection System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Injection System Market Intelligence
Electrical engineering talent specializing in high-pressure piezoelectric actuators is rotating toward Asia-Pacific manufacturing hubs, constraining European and North American expansion timelines. Robert Bosch GmbH leverages its captive semiconductor foundry partnerships to sustain injector control module production. Denso Corporation anchors Japanese OEM supply chains through dedicated just-in-sequence assembly lines. Continental AG competes on integrated powertrain software stacks that bridge fuel delivery with engine management.
An automotive fuel injection system meters and atomizes fuel into an internal combustion chamber at pressures ranging from 100 bar in port systems to over 2,500 bar in diesel common rail architectures, enabling precise air-fuel ratio control for emissions compliance and thermal efficiency. Direct injection product types command premium positioning due to their role in downsized turbocharged gasoline engines, while common rail injection retains structural dominance in commercial vehicle and agricultural equipment applications where torque density and durability standards exceed passenger car parameters. Electromagnetic technology leads volume shipments across cost-sensitive motorcycle and entry passenger car segments, whereas piezoelectric variants capture margin pools in performance and heavy-duty platforms requiring nanosecond injection event precision.
EPA tailpipe standards and Euro 7 proposals from the European Commission are forcing simultaneous reductions in particulate matter and nitrogen oxide outputs, which elevates injector spray pattern accuracy to a compliance-critical specification. China's MIIT fuel consumption mandates and NMPA certification protocols for new energy vehicle-adjacent hybrid powertrains create parallel certification pathways that shape product development roadmaps. Stakeholders must monitor how split-cycle and opposed-piston engine architectures alter injector duty cycles and placement geometry before committing capital to next-generation platform designs.
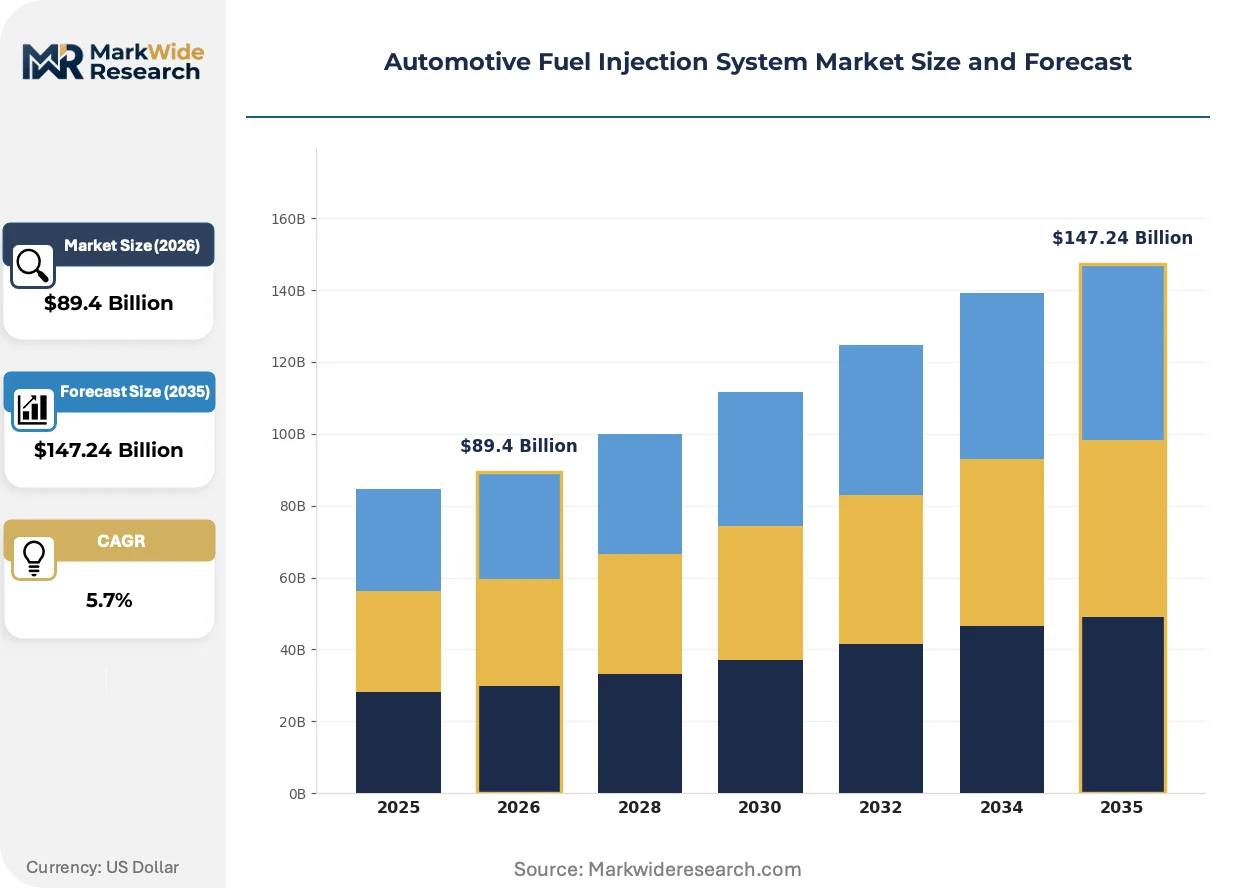
Market Dynamics
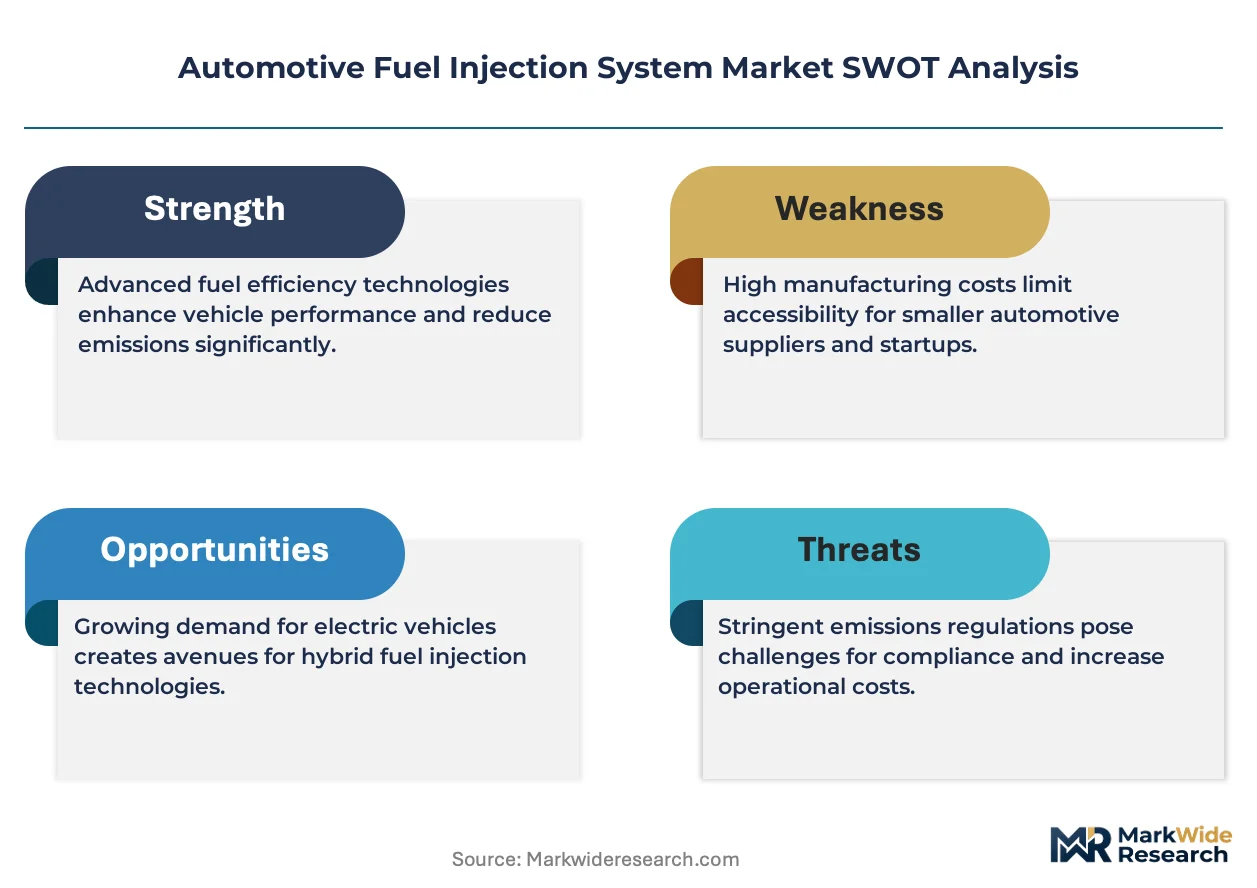
EPA tailpipe standards and Euro 7 proposals are compressing injector spray tolerances to nanosecond precision, forcing simultaneous capital deployment across piezoelectric actuator foundries and control module semiconductor capacity.
Growth Catalysts
- Euro 7 Emissions Framework:The European Commission's proposed nitrogen oxide and particulate matter limits are mandating multi-event injection strategies that expand addressable demand for high-pressure common rail architectures in commercial vehicle powertrains.
- Hybrid Powertrain Certification:China's MIIT fuel consumption mandates for new energy vehicle-adjacent hybrid systems are creating parallel certification pathways that sustain gasoline direct injection development alongside electrification investments.
- Piezoelectric Actuator Talent Migration:Electrical engineering specialization in high-pressure piezoelectric control is concentrating in Asia-Pacific manufacturing hubs, accelerating regional production scale-up for precision injector components.
Market Restraints
- Semiconductor Supply Concentration:Captive foundry partnerships for injector control module ASICs remain limited to a handful of integrated suppliers, creating single-source vulnerability for OEMs pursuing multi-sourcing strategies.
- Platinum Group Metal Cost Volatility:Catalytic after-treatment systems paired with advanced injection architectures face input cost pressure from palladium and rhodium price swings that erode powertrain margin pools.
- Diesel Demand Compression:Passenger car diesel share collapse in European markets is eliminating volume scale for common rail injector platforms optimized below 2.0-liter displacement categories.
Strategic Opportunities
- Agricultural Equipment Electrification:Torque-dense common rail systems for high-horsepower tractors and harvesters remain underpenetrated by piezoelectric precision technology, opening margin expansion for durability-rated actuator platforms.
- Split-Cycle Engine Architectures:Opposed-piston and split-cycle combustion concepts under development by independent powertrain laboratories are redefining injector placement geometry and duty cycle specifications.
- Indian BIS Fuel Efficiency Standards:The Bureau of Indian Standards' tightening corporate average fuel economy requirements are accelerating gasoline direct injection penetration in sub-4-meter compact passenger vehicles.
Industry Challenges
- Embedded Software Validation:ISO 26262 functional safety certification for injector control algorithms requires 18-24 month validation cycles that compress product launch windows against tightening OEM platform deadlines.
- Legacy Powertrain Integration:Backward compatibility requirements for 12-volt electrical architectures in cost-sensitive vehicle segments constrain adoption of advanced solenoid driver topologies optimized for 48-volt mild-hybrid systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Injection System Market |
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $147.24 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Injection, Port Fuel Injection, Mechanical Injection, Electronic Injection, Common Rail Injection Technology: Electromagnetic, Piezoelectric, Solenoid, Hydraulic, Mechanical Application: Passenger Cars, Commercial Vehicles, Motorcycles, Marine Engines, Agricultural Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | BorgWarner Inc., Hitachi Astemo, Ltd., Robert Bosch GmbH, Vitesco Technologies Group AG, Keihin Corporation, Denso Corporation, Marelli Holdings Co., Ltd., MAHLE GmbH, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Injection System Market Strategic Shifts & Innovations
Injector architecture evolution is bifurcating between extreme high-pressure diesel common rail advancement and gasoline direct injection precision refinement, with software-defined spray control emerging as the primary differentiation vector.
Piezoelectric actuator technology is displacing electromagnetic solenoids in performance and heavy-duty applications where nanosecond injection event precision enables multiple spray patterns per combustion cycle. European heavy commercial vehicle manufacturers are adopting these architectures at accelerated procurement rates. The technology is displacing legacy electromagnetic volume leadership in torque-critical segments where emissions compliance margins are narrowest.
The EPA's updated greenhouse gas standards for light-duty vehicles are mandating real-world emissions performance validation that extends beyond laboratory test cycles. This regulatory architecture is forcing OEMs to deploy closed-loop fuel trim systems with onboard diagnostic redundancy. Gasoline direct injection platforms in the United States are responding with expanded sensor integration and cloud-connected calibration update capabilities.
Fleet procurement departments are consolidating injector supplier relationships from three-tier to dual-source configurations to secure volume pricing while maintaining technical redundancy. Tier-1 powertrain integrators are absorbing this consolidation pressure through dedicated just-in-sequence assembly investments. This pattern is most visible in German premium passenger car manufacturing clusters where platform commonality across multiple OEMs enables scale aggregation.
Automotive Fuel Injection System Market Segmentation
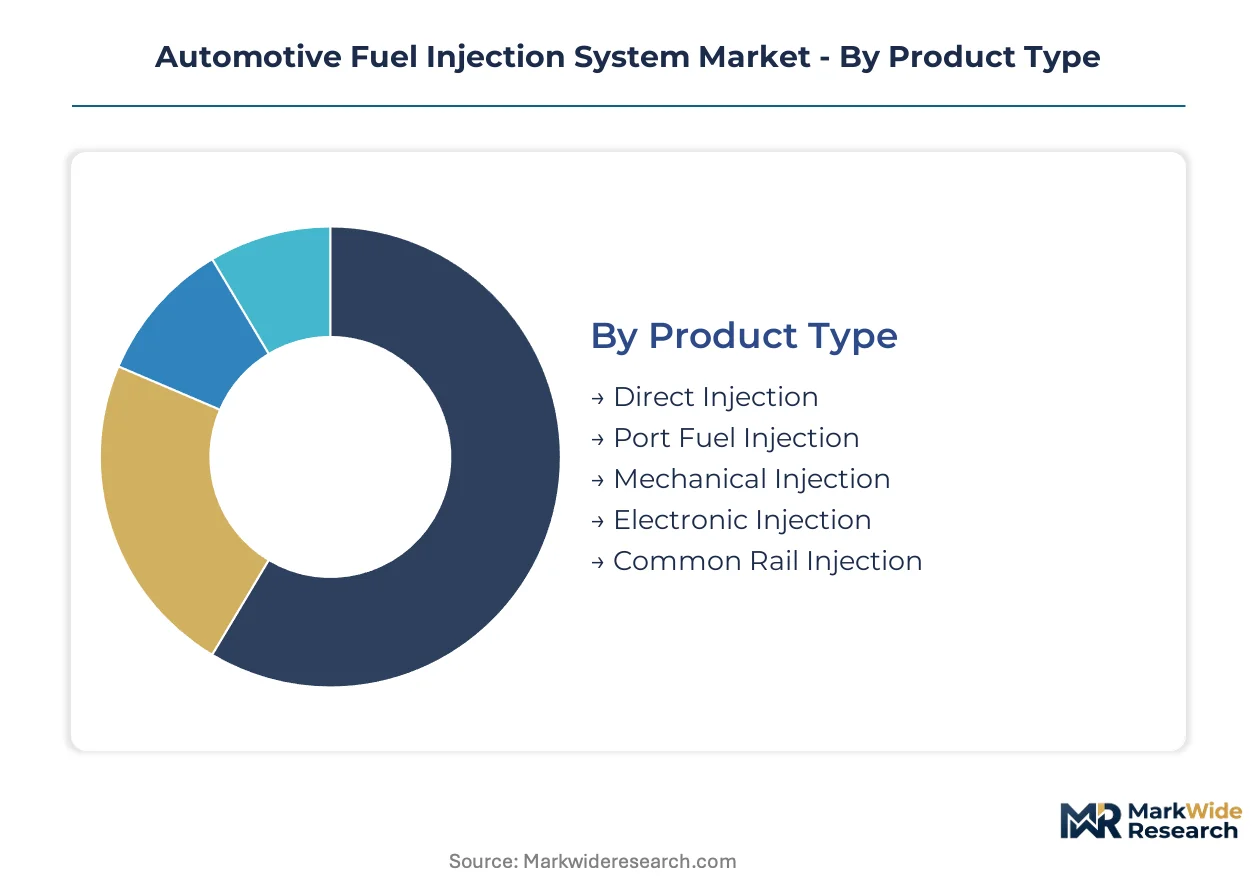
Segmentation in automotive fuel injection systems reveals how pressure specifications, actuator technologies, and duty cycle requirements diverge across powertrain architectures. Procurement patterns vary sharply between OEM captive supply and independent aftermarket channels.
Product Type:
Domestic assembly lines in Germany, China, and the United States concentrate volume for direct injection and common rail systems, while port fuel injection serves export-heavy manufacturing clusters in Eastern Europe and Mexico.
- Direct Injection:Gasoline direct injection atomizes fuel at 100-200 bar directly into combustion chambers, enabling downsized turbocharged architectures. Demand concentrates in German premium passenger car manufacturing where Euro 7 NOx limits mandate multi-event injection strategies.
- Common Rail Injection:Diesel common rail architectures operate at 2,000-2,500 bar for precise multiple injection events per cycle. Heavy commercial vehicle production in the United States and European long-haul segments drives procurement, with torque density requirements exceeding passenger car parameters.
- Port Fuel Injection:Lower-pressure port systems at 3-5 bar serve cost-sensitive vehicle categories where emissions compliance margins remain achievable without direct injection complexity.
- Mechanical Injection:Legacy mechanical pump-line-nozzle systems persist in agricultural equipment and marine applications where electronic infrastructure reliability concerns dominate.
- Electronic Injection:Electronic control modules integrate sensor feedback for closed-loop air-fuel ratio management across hybrid powertrain certification pathways.
Common rail injection commands the established base in commercial vehicle powertrains. The steepest expansion runs through direct injection platforms serving hybrid gasoline engines.
Technology:
Cost tiers separate electromagnetic volume leadership from piezoelectric precision premiums, with solenoid variants occupying mid-range positioning across Asian motorcycle and entry passenger car segments.
- Piezoelectric:Piezoelectric actuators deliver nanosecond injection event precision through crystalline expansion under electric field. Heavy-duty and performance applications in European commercial vehicles adopt these architectures where emissions compliance margins are narrowest.
- Electromagnetic:Electromagnetic solenoids dominate shipment volumes through simpler construction and lower unit costs. Motorcycle manufacturing in India and Southeast Asia sources these actuators exclusively for single-cylinder and parallel-twin powertrains.
- Solenoid:Advanced solenoid designs with optimized magnetic circuits bridge cost and precision requirements for mid-size passenger car direct injection systems.
- Hydraulic:Hydraulic amplification stages in some common rail injectors multiply piezoelectric displacement for extreme pressure operation in marine and locomotive engines.
- Mechanical:Pure mechanical actuation without electronic control survives in retrofit markets and jurisdictions with limited diagnostic infrastructure.
Electromagnetic technology holds the volume base across cost-sensitive segments. Piezoelectric platforms are climbing the fastest as heavy-duty emissions standards tighten.
Application:
Customer type fragmentation separates fleet procurement departments from individual owner-operator purchasing patterns, with agricultural equipment representing distinct seasonal demand cycles.
- Passenger Cars:Gasoline direct injection and port fuel injection systems serve light-duty vehicle platforms where EPA greenhouse gas standards mandate real-world emissions validation beyond laboratory cycles.
- Commercial Vehicles:Heavy-duty diesel common rail dominates long-haul trucking and urban delivery segments with 15-20 year durability specifications and million-mile service intervals.
- Motorcycles:Single-cylinder and small-displacement multi-cylinder engines in Asian markets rely on simplified electronic fuel injection replacing carburetor architectures.
- Marine Engines:High-horsepower outboard and inboard marine applications require corrosion-resistant injector materials and salt spray certification protocols.
- Agricultural Equipment:Tractor and harvester powertrains demand torque-dense common rail systems with dust ingress protection and extended service intervals between planting and harvest seasons.
Commercial vehicles command the established base through fleet replacement cycles. Agricultural equipment is gaining share fastest as precision farming electrification creates hybrid powertrain opportunities.
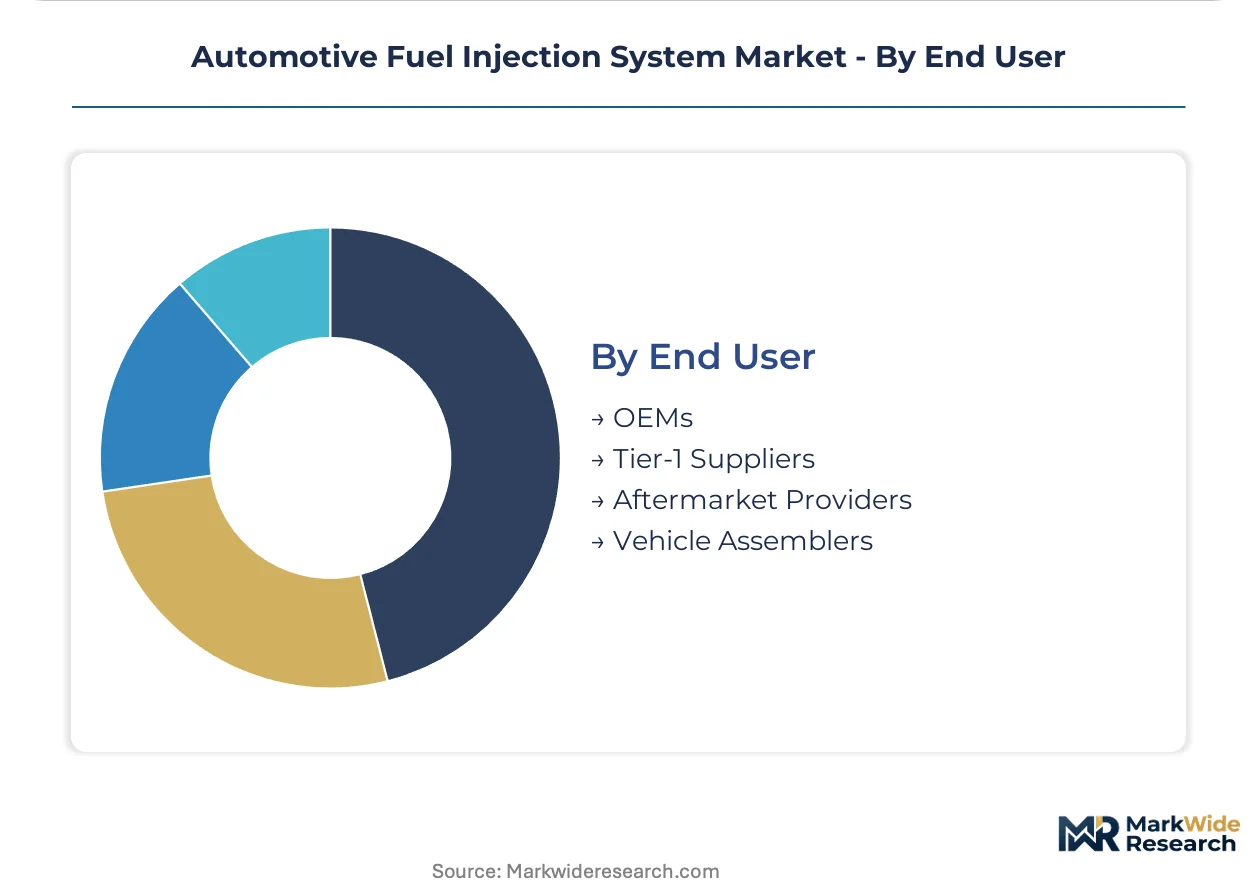
End User:
Supply concentration varies sharply between OEM captive foundry relationships and fragmented aftermarket distribution through jobber networks and original equipment service channels.
- OEMs:Original equipment manufacturers specify injector architectures during platform development, locking in multi-year supply agreements with integrated Tier-1 powertrain suppliers.
- Tier-1 Suppliers:Dedicated just-in-sequence assembly investments by Bosch, Denso, and Continental aggregate volume across multiple OEM platforms.
- Aftermarket Providers:Independent distributors and remanufacturers serve vehicle aging populations with replacement injectors and repair kits.
- Vehicle Assemblers:Contract assembly operations in emerging markets source complete fuel injection modules rather than component-level procurement.
OEMs command the established base through platform specification authority. Aftermarket providers are climbing the fastest as vehicle parc aging extends replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe standards in the United States anchor the dominant geography for emissions-driven fuel injection technology procurement. National regulators in Germany, China, Japan, and India shape parallel certification pathways that fragment manufacturing investment across three continents.
United States
Heavy commercial vehicle fleet replacement cycles and EPA greenhouse gas standards for light-duty vehicles drive precision injector demand. NHTSA corporate average fuel economy mandates compress product development timelines for gasoline direct injection platforms. Detroit-Warren-Dearborn manufacturing clusters concentrate Tier-1 assembly capacity for North American OEM supply chains.
Germany
Premium passenger car manufacturing and Euro 7 nitrogen oxide limit proposals sustain multi-event injection strategy development. KBA type-approval protocols for real-driving emissions validation extend certification cycles for new powertrain architectures. Stuttgart and Munich metropolitan regions host captive semiconductor foundry partnerships for injector control module production.
China
MIIT fuel consumption mandates for new energy vehicle-adjacent hybrid systems sustain parallel gasoline direct injection investment alongside electrification. NMPA certification protocols for hybrid powertrains create dual-track regulatory compliance requirements. Yangtze River Delta manufacturing hubs concentrate piezoelectric actuator talent migration from European engineering centers.
Japan
METI energy efficiency standards for transportation equipment and domestic OEM hybrid platform dominance sustain precision fuel injection development. JIS certification requirements for automotive electronics shape control module validation protocols. Nagoya-Toyota industrial corridor anchors just-in-sequence assembly investments for dedicated OEM supply relationships.
India
BIS corporate average fuel economy standards accelerate gasoline direct injection penetration in sub-4-meter compact passenger vehicles. PLI scheme incentives for automotive component manufacturing attract foreign Tier-1 assembly investments. Tamil Nadu and Gujarat automotive clusters concentrate motorcycle electronic fuel injection adoption replacing carburetor architectures.
Automotive Fuel Injection System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the fuel injection system value chain. The market structure consolidates around integrated Tier-1 powertrain suppliers with captive semiconductor partnerships, while specialized actuator manufacturers occupy precision niches. Three archetypes dominate: vertically integrated German-Japanese conglomerates with foundry control, Asian cost-optimized volume manufacturers, and European software-defined powertrain integrators. Competitive moves concentrate on just-in-sequence assembly investments and strategic semiconductor capacity reservations.
Within the integrated conglomerate tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes combining captive electronics production with dedicated OEM supply relationships. Continental AG occupies a position bridging hardware manufacturing with powertrain software integration. These three anchors represent distinct strategic postures: German engineering-centric vertical control, Japanese just-in-time manufacturing discipline, and European software-defined vehicle transition positioning.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Hitachi Astemo, Ltd. |
| Robert Bosch GmbH |
| Vitesco Technologies Group AG |
| Keihin Corporation |
| Denso Corporation |
| Marelli Holdings Co., Ltd. |
| MAHLE GmbH |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with captive semiconductor foundries lock in both piezoelectric actuator supply access and forward price visibility for Tier 1 powertrain integrators serving EPA and Euro 7 compliance timelines. These contractual structures concentrate procurement leverage among vertically integrated suppliers while fragmenting pricing power across electromagnetic solenoid commodity tiers.
Pricing Analysis
Price spreads between German premium passenger car manufacturing clusters and Indian motorcycle assembly operations exceed threefold for functionally equivalent electromagnetic injector platforms. Three-tier pricing structure across piezoelectric precision, advanced solenoid, and commodity electromagnetic levels segments buyer archetypes by emissions compliance stringency and torque density requirements. Cost compression in entry passenger car electromagnetic tiers is intensifying because Chinese MIIT hybrid certification mandates are accelerating volume scale. Fleet procurement departments exhibit lowest price sensitivity due to million-mile service interval specifications, while individual owner-operators in aftermarket channels drive hardest bargain negotiation.
Supply Chain Analysis
Piezoelectric ceramic substrate processing capacity in Japan's Nagoya-Toyota industrial corridor constitutes a single-source chokepoint for nanosecond-precision actuator architectures. Manufacturing concentration in Germany, China, and the United States draws from palladium and rhodium catalytic after-treatment pairings, high-pressure steel alloy forging stock, and silicon carbide semiconductor wafers. Single-source vulnerability runs through Bosch and Denso captive foundry partnerships for injector control module ASICs. Distribution runs through dedicated just-in-sequence assembly lines feeding OEM platform engineering centers rather than speculative inventory builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 nitrogen oxide limits and EPA greenhouse gas standards are compressing product development timelines, creating high-growth disruption as emissions-driven precision requirements displace legacy electromagnetic volume leadership.
For Market Incumbents: Fortify captive semiconductor foundry partnerships through capacity reservation deposits and backward integration into piezoelectric ceramic substrate processing. Expand just-in-sequence assembly footprint in Yangtze River Delta manufacturing hubs to anchor electrical engineering talent migration. ISO 26262 functional safety certification cycles represent the critical bottleneck threatening platform launch windows against tightening OEM deadlines. For New Entrants and Emerging Players: Differentiate on agricultural equipment electrification white-space where torque-dense common rail systems remain underpenetrated by piezoelectric precision technology. Target Indian BIS fuel efficiency standard acceleration in sub-4-meter compact passenger vehicles as the most penetrable geography. Pursue joint development agreements with independent powertrain laboratories exploring split-cycle and opposed-piston engine architectures to secure placement geometry specification influence early. For Investors and Strategic Acquirers: Capital is best deployed toward specialized actuator manufacturers with durability-rated platforms certified for heavy commercial vehicle million-mile service intervals. Long-term viability over the next decade hinges on software-defined spray control differentiation bridging fuel delivery with engine management integration. Watch for inflection signals in opposed-piston engine architecture commercialization timelines that would redefine injector duty cycle specifications and obsolete legacy platform investments.| Strategic Initiative | Industry Significance |
|---|---|
| Piezoelectric Actuator Foundry Partnership | Captive semiconductor capacity secures nanosecond precision supply for Euro 7 compliance timelines. |
| Just-in-Sequence Assembly Expansion | Dedicated OEM supply relationships aggregate volume across multiple platform engineering centers. |
| Software-Defined Spray Control Investment | Closed-loop fuel trim systems with cloud-connected calibration respond to EPA real-world emissions validation. |
| Agricultural Equipment Certification Pathway | Durability-rated actuator platforms capture margin expansion in precision farming electrification. |
| Hybrid Powertrain Dual-Track Development | Parallel gasoline direct injection investment sustains relevance alongside China's MIIT electrification mandates. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and piezoelectric actuator manufacturing specialists; and secondary validation through vehicle production databases, IHS Markit registration data, EPA certification filings, and KBA type-approval documentation. Bottom-up triangulation across component-level bill-of-materials analysis and top-down market sizing reconciled volume and value estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning injection architecture type, actuator technology tier, vehicle class, propulsion architecture, and regional production cluster. CAGRs were derived from production volume trajectories weighted by content-per-vehicle assumptions and technology mix shifts. Forecast inputs incorporated OEM platform lifecycle timing, regulatory phase-in schedules, and semiconductor capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained EPA and Euro 7 regulatory stringency, continued hybrid powertrain certification parallel tracks, and stable palladium group metal supply would require recalibration. Forecasts reflect documented assumptions regarding piezoelectric talent migration velocity and captive foundry partnership durability. Practitioners should keep alternative scenarios live as split-cycle engine architecture commercialization and 48-volt electrical system adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Gears Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automotive Door Module Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Key Market